
Global Robotics Market Overview - Size, Share & Industry Snapshot
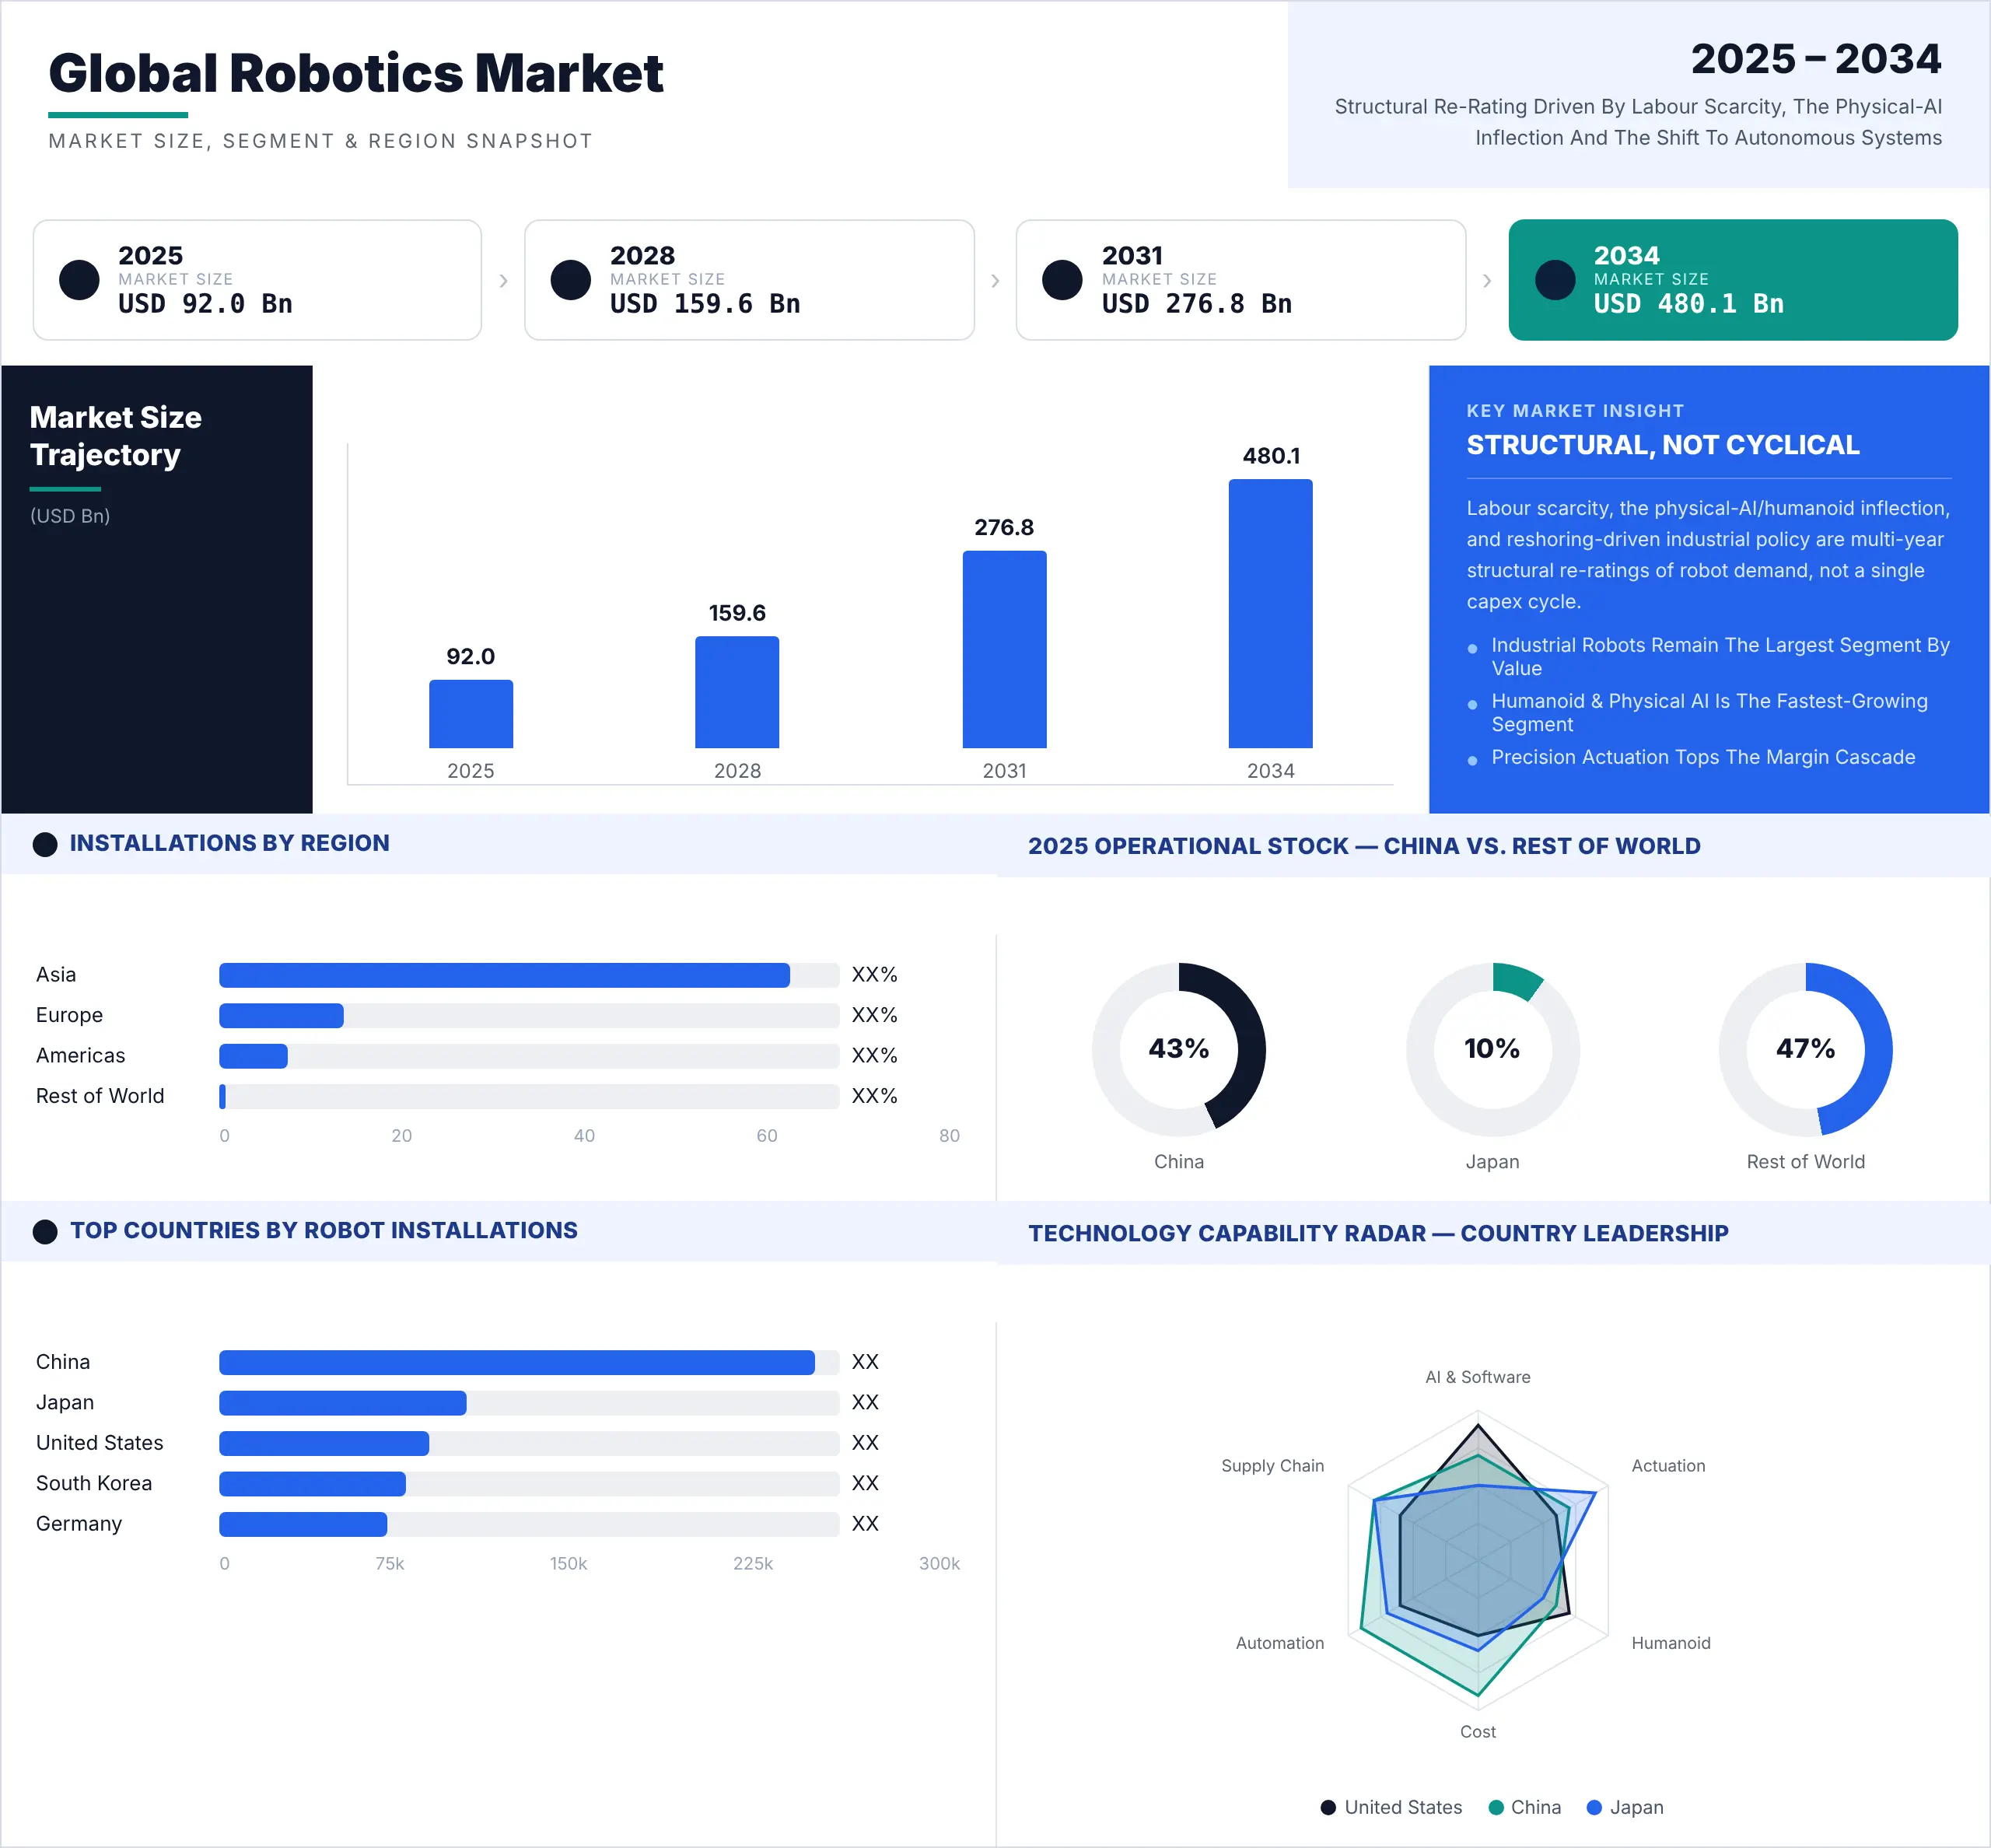
The Global Robotics Market was valued at USD 92 Bn in 2025 and is projected to reach USD 480.1 Bn by 2034, growing at a CAGR of 20.15% - one of the steepest re-rating curves of any industrial-technology market tracked by MMR, reflecting the shift from pure industrial arms toward cobots, mobile robots and the still-early humanoid/physical-AI category. The shipment base underneath that forecast is already large and growing: annual robot installations have climbed for multiple consecutive years and now number in the hundreds of thousands of units worldwide, with a global operational stock running into the millions of installed units as of 2025 - and that is before cobots, mobile robots, professional service robots and the emerging humanoid/physical-AI category are added on top.
Robotics Market Scope & Report Coverage - Inquire Before Buying
| Report Coverage | Details | ||
|---|---|---|---|
| Base Year | 2025 | Forecast Period | 2026-2034 |
| Historical Data | 2020 to 2025 | Market Size in 2025 | USD 92 Bn |
| Forecast Period 2026-2034 CAGR | 20.15% | Market Size in 2034 | USD 480.1 Bn |
Segments Covered
| Segment | Coverage |
|---|---|
| By Robot Type | Industrial Robots (Articulated, SCARA, Parallel/Delta, Cartesian, Cylindrical, Others) • Collaborative Robots (Cobots) • AMR & AGV • Service Robots • Humanoid Robots • Exoskeletons |
| By Payload | Light-Duty (up to 16 kg) • Medium-Duty (16 to 60 kg) • Heavy-Duty (61 to 225 kg) • Ultra-Heavy (Above 225 kg) |
| By Offering | Hardware (End Effectors - Welding Guns, Grippers, Tool Changers, Clamps, Suction Cups, Others; Controllers; Drive Units - Hydraulic, Electric, Pneumatic; Vision Systems; Sensors; Power Supply Accessories; Safety Fencing Hardware; Fixtures & Tools; Conveyor Hardware; Others) • System Engineering • Software & Programming |
| By Application | Handling (Pick & Place, Material Handling, Packaging & Palletizing) • Assembling & Disassembling • Welding & Soldering • Dispensing (Gluing, Painting, Food Dispensing) • Processing (Grinding & Polishing, Milling, Cutting) • Cleanroom |
| By End-Use Industry | Automotive • Electrical & Electronics • Metals & Machinery • Plastics, Rubber & Chemicals • Food & Beverages • Precision Engineering & Optics • Pharmaceuticals & Cosmetics • Oil & Gas |
| By Region | North America • Europe • Asia-Pacific • Middle East & Africa • South America |
Segment definitions and coverage shown here mirror the complete report's table of contents; all share and value figures are released at the sub-segment level in the full study.
Robotics Market Key Highlights & Growth Trends 2025-2034
Most market reports list highlights. This section explains what they mean - for OEM strategy, for component-supplier positioning, and for investment timing in the global robotics industry.
1. Physical AI & Humanoid Robots - The Next Growth Engine
Humanoid and general-purpose embodied-AI platforms have moved from lab demonstrations to funded industrial pilots at automotive, logistics and electronics sites across the United States, China and Europe. The first use cases to reach genuine payback - not hype-driven deployment - are narrow and repetitive: tote handling, kitting, and machine-tending tasks that already look like a mobile manipulator's natural habitat, well before the "general-purpose labour" vision most funding decks promise.
The real bottleneck is not the AI model - it is the hardware underneath it: torque-dense joint actuators, dexterous hands and battery/thermal systems that must survive continuous duty cycles, not demo-day choreography. Component suppliers who get designed into a humanoid actuator stack today are qualifying into a platform category still being defined, which is a materially different opportunity than qualifying into a mature industrial-robot supply chain.
2. China's Installation Scale - The Market's New Centre of Gravity
China installs more industrial robots every year than any other country by a wide margin, and now holds the largest operational robot stock of any single market. Just as consequential: China's own domestic robot makers' share of Chinese sales has been rising steadily over the past decade, meaning China is no longer simply the world's largest robot buyer, it is rapidly becoming self-sufficient in robot supply too.
For non-Chinese OEMs and component suppliers, this cuts two ways. It shrinks the addressable import opportunity inside China itself, but it also means Chinese robot and component makers are now a credible, lower-cost competitive force in export markets - a dynamic very similar to the Chinese EV and solar trajectories, and one every Western and Japanese robotics strategy in this report is now explicitly priced against.
3. Precision Actuation - Reducers, Bearings & Ball Screws - The Quiet Moat
Every robot in this report - from an articulated welding arm to a cobot to a humanoid - is, underneath its software, a stack of precision-motion components: strain-wave and cycloidal reducers, crossed-roller and thin-section bearings, ball screws and frameless torque motors. These components carry long qualification cycles and are dominated by a small number of Japanese and European specialists, which makes them one of the most durable, least-discussed moats in the entire robotics value chain.
Humanoid platforms raise the stakes further: a single humanoid can require more than a dozen precision actuators across its joints, versus a handful on an industrial arm, so the component content per robot rises sharply as the mix shifts toward humanoids and away from simple pick-and-place arms. A component supplier qualified into this layer captures revenue across every robot category simultaneously, not just one.
4. Rare-Earth Magnets - The Actuation Supply Chain's Critical Chokepoint
Nearly every servo motor and joint actuator in a modern robot depends on NdFeB permanent magnets, and China dominates mining, separation and magnet manufacturing for the rare earths that go into them. Chinese licensing controls on heavy rare earths (dysprosium, terbium) have already shown they can reprice motor and robot bills of materials within a single quarter, not a multi-year horizon.
Magnet-free and reduced-rare-earth motor designs, recycling capacity, and non-Chinese separation capacity are all still early-stage relative to the scale of robot-industry demand, which means this chokepoint is not a one-time risk disclosure - it is a live, recurring input to every robot and component maker's cost and delivery planning through at least 2034.
5. Labour Scarcity & Reshoring - The Structural Demand Floor Beneath Every Cycle
Working-age population decline and skilled-labour shortages across the industrialized world are not a cyclical story - they are a demographic one, which means the baseline demand for automation keeps rising even in years when manufacturing capex itself is soft. Reshoring and nearshoring investment announcements add a second, policy-driven layer of demand on top, since high-wage reshored manufacturing is only competitive with automation built in from day one.
This is why robot density (installed robots per 10,000 manufacturing workers) keeps climbing even through industrial downturns: it is the denominator, not just the numerator, that is shrinking. A supplier or investor underwriting robotics demand purely on the industrial capex cycle is missing the structural floor sitting underneath it.
Global Robotics Industry Overview - Definition, Scope & Market Evolution
The robotics market is the hardware, software and services ecosystem built around machines that sense, decide and physically act - industrial robot arms, collaborative robots, autonomous mobile robots, professional service robots, and humanoid/physical-AI systems - deployed across industrial, commercial and consumer environments.
This report's market sizing covers robot hardware (arms, mobile platforms, humanoids), precision components and actuation, robot-specific control and embodied-AI software, system integration, and robots-as-a-service/leasing revenue. It does not include non-robotic fixed automation (conveyors, fixed PLC-only machinery with no autonomous manipulation or mobility) or general enterprise software unrelated to robot control, even though these are sometimes bundled under broader "automation" budgets.
The global robotics market is the economic expression of a structural shift in how physical work gets done - from human-only and fixed-automation production toward autonomous, increasingly AI-native physical systems that span the factory floor, the warehouse, the hospital and the farm. It spans the full value chain from raw materials and precision components, through robot assembly and embodied-AI software, to integration, deployment and the fleet-software/MRO tail that follows every installed base.
Annual robot installations have grown for multiple consecutive years and remain concentrated in a handful of large manufacturing economies, even as several major markets saw installations dip year-on-year in the most recent cycle. That is not a contradiction: it reflects a shift in where growth concentrates, with one country alone responsible for the majority of global installations, even as its own domestic manufacturers capture a rising share of that demand.
Three forces are reshaping who captures the next decade of growth. First, the center of gravity is shifting from pure industrial arms toward cobots, mobile robots and - still early, but accelerating - humanoid and physical-AI platforms. Second, labour scarcity and reshoring have converted robotics from a discretionary productivity tool into a structural requirement for competitive manufacturing in high-wage economies. Third, supply-chain resilience in precision components and rare-earth magnets has become a procurement-evaluation criterion on par with unit cost, opening doors for suppliers who can demonstrate qualified, diversified sourcing.
Robotics Market Segmentation - By Robot Type, Application, Industry & Region
Robotics Market Regional Analysis - Growth Map by Geography
North America XX% share • XX% CAGR
Reshoring and nearshoring investment, led by automotive, EV/battery and semiconductor fabrication, is the dominant demand story, layered on top of a mature industrial-robot base. The United States has seen installation growth soften in recent cycles even as reshoring announcements continued to accumulate - a reminder that announced capex and installed robots run on different clocks, and that a near-term dip does not represent a change in direction.
Europe XX% share • XX% CAGR
The sharpest labour-scarcity-driven re-rating of any region: working-age population decline and wage inflation are pushing cobot and SME adoption up even as Europe's energy-cost disadvantage weighs on robot-intensive manufacturing economics. Germany remains the largest single European market by installations but has posted a year-on-year decline in recent cycles, consistent with a broader European cyclical softening layered on top of the structural automation trend.
Asia-Pacific XX% share • XX% CAGR
The largest and fastest-growing region in this report by a wide margin, with China alone accounting for the majority of global installations and India's installations rising even as several mature Asian markets softened. China's own domestic manufacturers' rising share of Chinese sales means this region is scaling both demand and supply simultaneously.
Middle East & Africa XX% share • XX% CAGR
The smallest base among the five regions today, but a fast-rising one: sovereign-wealth-funded diversification strategies in the Gulf are channeling capital into robotics, AI and advanced manufacturing as part of a broader push away from oil dependence, while the African portion of this region remains early-stage and concentrated in agriculture and logistics automation pilots.
South America XX% share • XX% CAGR
The smallest base in this report. Brazil leads a comparatively small but steadily growing market, concentrated in automotive manufacturing and an emerging agriculture-robotics segment (precision spraying, autonomous harvesting), with white-space opportunity skewed toward component supply and integration rather than domestic robot manufacturing.
Read together, the regional split makes a specific strategic point: Asia-Pacific's installation share is heavily concentrated in one country, which means a supplier's "Asia-Pacific strategy" is, in practice, overwhelmingly a China strategy, with Japan, Korea and India as a materially smaller second tier. A go-to-market sequence that treats Asia-Pacific as a single homogeneous region risks misreading where the actual volume - and the actual competitive intensity from domestic Chinese suppliers - sits.
Robotics Market Dynamics - Drivers, Restraints & Opportunities
Demand Driver Impact - MMR Analysis
Driver 1 - Labour Scarcity & Demographics: Working-age population decline and skilled-labour shortages are a demographic fact, not a cyclical one, which means the baseline demand floor for automation rises every year even when industrial capex itself is soft - this is the single most durable driver underneath every segment in this report.
Driver 2 - Physical-AI & Humanoid Inflection: Humanoid and general-purpose robots have moved from lab demonstrations into funded industrial pilots at automotive, logistics and electronics sites, making this the fastest-growing operation category in the forecast even though it remains the smallest by installed base today.
Driver 3 - Reshoring & Industrial Policy: High-wage reshored and nearshored manufacturing is only cost-competitive when automated from day one, converting government reshoring policy into a direct, policy-linked robot-procurement driver rather than a purely commercial one.
Restraints - Robotics Market Challenges
Restraint 1: High Capex & Long SME Payback Periods
Robot and cell pricing, installation and integration costs still produce payback periods that discourage small- and mid-sized manufacturers, even where labour scarcity makes the long-run case compelling. The SME-adoption inflection point depends on standard cells, no-code programming and robots-as-a-service models maturing faster than they have to date.
Restraint 2: Precision-Component Bottlenecks & Lead Times
Reducers, bearings and precision actuators remain capacity-constrained relative to demand, particularly as humanoid-platform orders compete with industrial-robot and cobot demand for the same component suppliers. Component lead times are a direct cap on robot-output growth, independent of end-market demand strength.
Restraint 3: Regulatory Compliance Cost & Timeline
The EU's Machinery Regulation (applying from January 2027) and AI Act high-risk classification for safety-relevant robot components add conformity-assessment cost and timeline risk for every robot maker, integrator and component supplier selling into Europe, with comparable compliance regimes emerging in other major markets.
Opportunities - White Space Roadmap, 2025-2034
Of these four, the component-level opportunity is the most underpriced relative to its addressable size: it inherits demand growth from every robot category simultaneously (industrial, cobot, mobile, humanoid) rather than depending on the fortunes of any single robot type, and its qualification-driven moat (Highlight 3, Section 03) means early entrants are difficult to displace once qualified. The humanoid-actuation entry point carries the highest long-run payoff precisely because content-per-robot is highest there, even though the category is the smallest by installed base today.
Robotics Market Key Developments - Latest News & Industry Updates
| Date | Company | Development | Impact |
|---|---|---|---|
| 2024 | Figure AI | Closed a large Series B funding round backed by strategic technology investors to scale humanoid production | Accelerated the funding-to-commercialization timeline for general-purpose humanoid platforms |
| 2024 | Boston Dynamics | Unveiled a fully electric version of its Atlas humanoid, replacing the earlier hydraulic platform | Signaled an industry-wide shift toward electric actuation for factory-ready humanoid deployment |
| 2024-25 | Amazon | Began piloting third-party humanoid platforms inside select fulfilment centres | First large-scale validation of humanoid ROI in real-world logistics operations |
| 2025 | Hyundai Motor Group | Deepened integration with Boston Dynamics following its earlier majority acquisition | Strengthened automotive-OEM vertical integration into humanoid and legged robotics |
| 2025 | Tesla | Expanded pilot production of its Optimus humanoid platform | Marked a traditional automotive OEM's direct entry into humanoid manufacturing |
| 2024-25 | Unitree Robotics | Launched lower-cost humanoid and quadruped platforms aimed at broader commercial adoption | Intensified Chinese cost competition in the humanoid and legged-robot segment |
| 2024 | KUKA | Underwent ownership and structural changes under its Chinese parent, Midea Group | Reshaped the European industrial-robot OEM ownership landscape |
| 2025 | Physical Intelligence / Robot Foundation-Model Startups | Raised new funding rounds to advance general-purpose robot foundation models | Accelerated the embodied-AI software layer underpinning next-generation robot autonomy |
Entries are illustrative, sample developments compiled for this preview report; the complete report tracks 50+ developments per year across funding, M&A, product launches, partnerships and regulatory actions, each independently verified before publication.
Robotics Market Trade Flow & Top Country Markets
Top Countries by Robot Installations
Operational Stock - Top 2 Countries, 2025
Global 2025 operational stock: MMR estimate, figures pending final validation.
China's concentration is the central trade fact in this market: a majority of everything installed worldwide went into one country, and that country's own manufacturers now supply a rising share of it domestically. For a non-Chinese robot or component maker, this means the addressable import opportunity inside China is shrinking even as China's installed base keeps growing - the growth is increasingly captured by domestic suppliers, not international ones. Traditional exporter strength remains concentrated in Japan, Germany and South Korea, whose precision-manufacturing bases built the modern industrial-robot export trade; the open strategic question this report tracks is how fast Chinese robot and component exports scale into third markets, a trajectory several governments are already watching for echoes of the EV and solar precedents.
Robotics Market - Top 10 Country Markets
| Country | Installations (Units) | YoY Change | Key Domestic OEM(s) |
|---|---|---|---|
| China | XX | XX | Estun, Siasun, UBTECH, Unitree |
| Japan | XX | XX | FANUC, Yaskawa, Kawasaki, Denso, Epson |
| United States | XX | XX | Teradyne (UR, MiR), Boston Dynamics, Figure AI |
| South Korea | XX | XX | Doosan Robotics, Hyundai Robotics |
| Germany | XX | XX | KUKA, Neura Robotics, Franka Robotics |
| India | XX | XX | Addverb, emerging domestic base |
| Italy | XX | XX | Comau |
| Mexico | XX | XX | Import-dependent, US/Asia supply |
| Spain | XX | XX | PAL Robotics (service/humanoid) |
| France | XX | XX | Exotec, Wandercraft |
Installation figures and YoY change are placeholders pending the complete report's bottom-up/top-down triangulation. OEM mapping is MMR's own classification, illustrative.
Robotics Market Competitive Landscape & Key Players
The complete report benchmarks the top 50 profiled companies on market share, revenue, backlog, technology capability and regional dependency. The positioning map below plots 25 of them on market scale against technology innovation.
| Strategic Archetype | Revenue Scale | Backlog Quality | China Exposure | 2025-2034 Outlook |
|---|---|---|---|---|
| Scale Leader | Highest | Deep, funded | Medium-High | Margin pressure from Chinese price competition |
| Integrated Group | High | Strong | Medium | Scale advantage across robot categories |
| Specialty Innovator | Low-Medium | Fast-growing | Low | Best-positioned for humanoid/physical-AI premium growth |
| Niche Challenger | Low | Selective | Low | Niche premium, limited scale |
Scale Leaders dominate industrial-robot revenue but are the archetype most exposed to Chinese cost and scale competition as domestic Chinese OEMs capture a rising share of the world's largest single market. Integrated Groups have structural advantages serving customers who want a single supplier across industrial, cobot and mobile categories - a genuine moat for large program bundling, but one that moves slowly against nimbler entrants. Specialty Innovators are the best-positioned archetype for 2025-2034 premium growth precisely because their capability profile (software-first, humanoid/physical-AI focus, low China exposure) aligns with the fastest-growing segment identified elsewhere in this report. Niche Challengers command the highest per-contract margins in categories where they hold a genuine technology or regulatory edge, but have limited scale to compete for the largest industrial programs outright.
Companies Profiled in This Report
32 of the 50+ companies benchmarked in the complete report, spanning every region and strategic archetype covered in this analysis.
| Company | HQ / Region | Primary Focus | Archetype |
|---|---|---|---|
| FANUC | Japan | Industrial Robots | Scale Leader |
| ABB Robotics | Switzerland/Sweden | Industrial Robots | Scale Leader |
| Yaskawa Electric | Japan | Industrial Robots, Motors | Scale Leader |
| KUKA | Germany | Industrial Robots | Integrated Group |
| Kawasaki Robotics | Japan | Industrial Robots | Integrated Group |
| Denso Robotics | Japan | Industrial Robots | Integrated Group |
| Epson Robots | Japan | SCARA, Precision | Niche Challenger |
| Stäubli | Switzerland | Industrial Robots | Niche Challenger |
| Comau | Italy | Industrial Robots | Niche Challenger |
| Omron Adept | Japan | Industrial, Mobile | Integrated Group |
| Universal Robots (Teradyne) | Denmark / USA | Cobots | Integrated Group |
| MiR (Teradyne) | Denmark / USA | AMR | Integrated Group |
| Franka Robotics | Germany | Cobots, Research | Specialty Innovator |
| Neura Robotics | Germany | Cobots, Humanoid | Specialty Innovator |
| Agile Robots | Germany/China | Industrial AI, Vision | Specialty Innovator |
| Wandelbots | Germany | No-Code Robot Software | Specialty Innovator |
| RobCo | Germany | Modular Cobots | Specialty Innovator |
| Exotec | France | Warehouse Robotics | Specialty Innovator |
| Wandercraft | France | Exoskeletons, Humanoid | Specialty Innovator |
| PAL Robotics | Spain | Humanoid, Service | Niche Challenger |
| Doosan Robotics | South Korea | Cobots | Integrated Group |
| Hyundai Robotics | South Korea | Industrial Robots | Integrated Group |
| Techman Robot | Taiwan | Cobots | Niche Challenger |
| Locus Robotics | United States | Warehouse AMR | Specialty Innovator |
| Boston Dynamics (Hyundai) | United States | Legged, Humanoid | Specialty Innovator |
| Figure AI | United States | Humanoid | Specialty Innovator |
| Agility Robotics | United States | Humanoid | Specialty Innovator |
| Apptronik | United States | Humanoid | Specialty Innovator |
| 1X Technologies | Norway/USA | Humanoid | Specialty Innovator |
| Estun Automation | China | Industrial Robots | Scale Leader (regional) |
| UBTECH Robotics | China | Humanoid, Service | Specialty Innovator |
| Unitree Robotics | China | Legged, Humanoid | Specialty Innovator |
Archetype classification per MMR's Scale Leader / Integrated Group / Specialty Innovator / Niche Challenger framework (above). Full company-level revenue, backlog and technology-capability scoring is available in the complete report.
Robotics Technology Innovation Radar & Hype Cycle
The strategic read on this curve matters more than the curve itself. Technologies at the Peak of Inflated Expectations (humanoid factory deployment at scale, home robots) attract the most funding headlines but the longest and least certain path to fielded commercial value - a buyer or investor anchoring a near-term thesis there is underwriting hype-cycle risk, not technology risk. The Slope of Enlightenment categories (cobots, AMRs, vision-guided picking, digital twins) are where near-term, sub-two-year payoff actually concentrates, and where this report's White-Space recommendations (Section 07) are weighted most heavily. Articulated industrial robots, welding, palletizing and AGVs sit further along, on the Plateau of Productivity, which is precisely why they are the largest segment by value but no longer the fastest-growing one.
Robotics Market FAQ - Size, Growth, Trends & Key Players
What is the global robotics market size and forecast?
The global robotics market was valued at USD 92 Bn in 2025 and is forecast to reach USD 480.1 Bn by 2034, growing at a CAGR of 20.15% - among the steepest re-rating curves of any industrial-technology market MMR tracks. That trajectory is underpinned by a shift from pure industrial arms toward cobots, mobile robots and the still-early humanoid/physical-AI category, layered on a shipment base that is already large and growing - see Section 01 and Section 04 for the full basis.
Which country installs the most robots?
China, by a wide margin - the largest single market for annual installations and the largest operational robot stock of any country.
What's driving the humanoid and physical-AI robotics wave?
Humanoid and general-purpose robots have moved from lab demonstrations into funded industrial pilots at automotive, logistics and electronics sites. The near-term payoff cases are narrow repetitive tasks (tote handling, kitting, machine tending), not the "general-purpose labour" vision most funding decks promise - see Section 03, Highlight 1.
Why does the rare-earth and precision-component supply chain matter for robotics?
Nearly every servo motor and joint actuator depends on NdFeB rare-earth magnets and precision reducers/bearings dominated by a small number of Japanese, European and Chinese suppliers. China's licensing controls on heavy rare earths have already shown they can reprice robot bills of materials within a single quarter (Section 03, Highlights 3 and 4).
Which companies lead the global robotics OEM landscape?
FANUC, ABB Robotics, Yaskawa and KUKA lead industrial robotics by scale and installed base; Universal Robots and Teradyne's MiR lead cobots and mobile robots; Figure AI, Boston Dynamics, Agility Robotics, Unitree and UBTECH lead the humanoid/physical-AI challenger tier (Section 10).
What is the component-level opportunity in the robotics market?
Precision-motion components - reducers, bearings, ball screws and actuators - sit underneath nearly every robot segmented in this report, and content-per-robot rises sharply as the mix shifts toward humanoids. This is identified as one of the most underpriced opportunities in the market relative to its addressable size (Section 03, Highlight 3; Section 07 opportunities).
How reliable are the figures in this sample report?
Market size (USD 92 Bn, 2025), CAGR (20.15%) and the 2034 forecast (USD 480.1 Bn) are MMR's base-case estimates. Segment-share and country-level figures still marked "XX" are placeholders pending the full bottom-up/top-down triangulation and data validation in the complete report.
Robotics Market Analyst Perspective & Strategic Outlook
Call 1: Humanoid Shipments Cross from Pilots to Programmes of Record Before 2030
Most industry roadmaps still treat humanoid deployment as a late-2020s/early-2030s story. We think the crossover - where humanoid orders move from single-site pilots to multi-site, budgeted procurement programmes - arrives before 2030 for a narrow set of repetitive logistics and electronics-assembly tasks, well ahead of the "general-purpose labour" timeline most funding narratives imply.
Call 2: China's Domestic Supply Share Keeps Rising, Not Falling, Despite Western Reshoring Narratives
Western commentary often frames reshoring and trade friction as a headwind to China's robotics dominance. We think the more consequential trend is the opposite: China's domestic manufacturers' share of China's own robot sales has climbed sharply over the past decade, and that substitution curve is still rising - China is simultaneously the largest buyer and an increasingly self-sufficient supplier.
Call 3: Component Suppliers Out-Return Robot OEMs on Margin Through 2034
Reducers, bearings and precision actuators sit at a higher point on the margin cascade than most of the robots built on top of them, and content-per-robot rises as the category mix shifts toward humanoids. A qualified component supplier captures revenue across every robot category simultaneously without ever bidding for, or carrying the competitive risk of, the robot program itself. We expect returns on capital in this tier to outperform robot-OEM economics across the forecast window.
Call 4: Europe's Cobot and Software Lead Erodes Without a Scaled Humanoid Champion
Europe holds genuine strengths in safety, cobots and precision components, and its country-leadership scoring in this report reflects that. But without a European humanoid or physical-AI platform company reaching the scale of the leading US and Chinese entrants, we think Europe's current technology lead narrows over the forecast window rather than compounds - a gap Section 11's Technology Radar flags as the single most consequential one to close.
Call 5: Robots-as-a-Service Becomes the Default SME Entry Point, Not Ownership
Most market models still size robots-as-a-service (RaaS) and leasing as a minority revenue pool alongside traditional hardware sales. We think RaaS becomes the default adoption path for small- and mid-sized manufacturers specifically - not the broader market - because it is the only model that resolves the SME payback-period restraint identified in Section 07 without requiring the buyer to carry capex risk.