1. Industrial Gases Market Introduction
1.1. Study Assumption and Market Definition
1.2. Scope of the Study
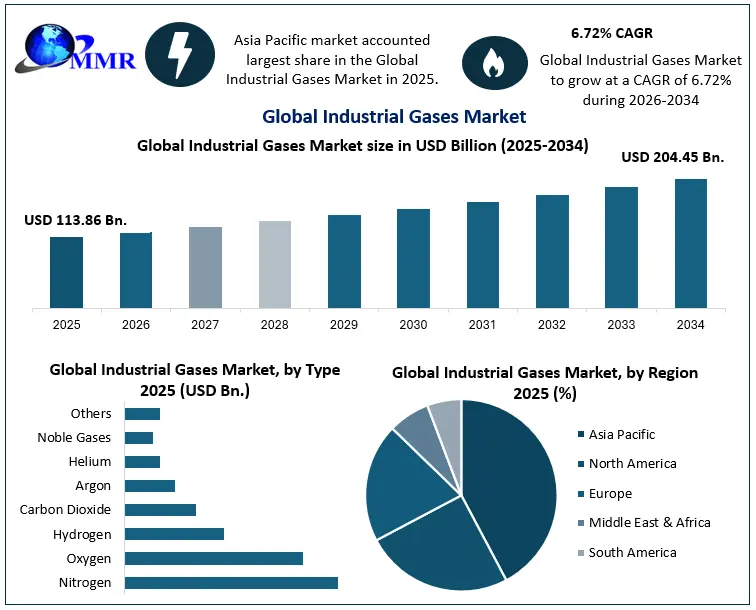
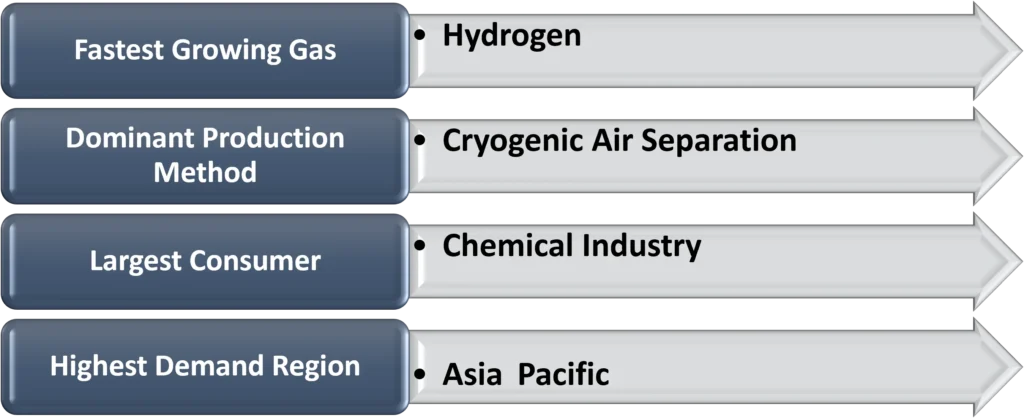
1.3. Executive Summary
2. Global Industrial Gases Market: Competitive Landscape
2.1. MMR Competition Matrix
2.2. Competitive Landscape
2.3. Key Players Benchmarking
2.3.1. Company Name
2.3.2. Business Segment
2.3.3. End-user Segment
2.3.4. Revenue (2025)
2.3.5. Company Locations
2.4. Leading Industrial Gases Market Companies, by market capitalization
2.5. Market Structure
2.5.1. Market Leaders
2.5.2. Market Followers
2.5.3. Emerging Players
2.6. Mergers and Acquisitions Details
3. Industrial Gases Market: Dynamics
3.1. Industrial Gases Market Trends by Region
3.1.1. North America Industrial Gases Market Trends
3.1.2. Europe Industrial Gases Market Trends
3.1.3. Asia Pacific Industrial Gases Market Trends
3.1.4. Middle East and Africa Industrial Gases Market Trends
3.1.5. South America Industrial Gases Market Trends
3.2. Industrial Gases Market Dynamics by Region
3.2.1. North America
3.2.1.1. North America Industrial Gases Market Drivers
3.2.1.2. North America Industrial Gases Market Restraints
3.2.1.3. North America Industrial Gases Market Opportunities
3.2.1.4. North America Industrial Gases Market Challenges
3.2.2. Europe
3.2.2.1. Europe Industrial Gases Market Drivers
3.2.2.2. Europe Industrial Gases Market Restraints
3.2.2.3. Europe Industrial Gases Market Opportunities
3.2.2.4. Europe Industrial Gases Market Challenges
3.2.3. Asia Pacific
3.2.3.1. Asia Pacific Industrial Gases Market Drivers
3.2.3.2. Asia Pacific Industrial Gases Market Restraints
3.2.3.3. Asia Pacific Industrial Gases Market Opportunities
3.2.3.4. Asia Pacific Industrial Gases Market Challenges
3.2.4. Middle East and Africa
3.2.4.1. Middle East and Africa Industrial Gases Market Drivers
3.2.4.2. Middle East and Africa Industrial Gases Market Restraints
3.2.4.3. Middle East and Africa Industrial Gases Market Opportunities
3.2.4.4. Middle East and Africa Industrial Gases Market Challenges
3.2.5. South America
3.2.5.1. South America Industrial Gases Market Drivers
3.2.5.2. South America Industrial Gases Market Restraints
3.2.5.3. South America Industrial Gases Market Opportunities
3.2.5.4. South America Industrial Gases Market Challenges
3.3. PORTER's Five Forces Analysis
3.4. PESTLE Analysis
3.5. Technology Roadmap
3.6. Regulatory Landscape by Region
3.6.1. North America
3.6.2. Europe
3.6.3. Asia Pacific
3.6.4. Middle East and Africa
3.6.5. South America
3.7. Key Opinion Leader Analysis in the Industrial Gases Market
3.8. Analysis of Government Schemes and Initiatives For Global Industry
3.9. Industrial Gases Market Trade Analysis
3.10. The Global Pandemic Impact on Industrial Gases Market
4. Industrial Gases Market: Global Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
4.1. Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
4.1.1. Oxygen
4.1.2. Carbon Dioxide
4.1.3. Nitrogen
4.1.4. Hydrogen
4.1.5. Noble Gas
4.1.6. Helium
4.1.7. Argon
4.1.8. Others (Neon, Krypton, Xenon, and Radon)
4.2. Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
4.2.1. Cryogenic Air Separation
4.2.2. Non-Cryogenic Air Separation
4.2.3. Steam Methane Reforming (SMR)
4.2.4. Electrolysis
4.2.5. Others
4.3. Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
4.3.1. Merchant (Bulk & Cylinder)
4.3.2. Tonnage (On-site Supply)
4.3.3. Packaged Gases
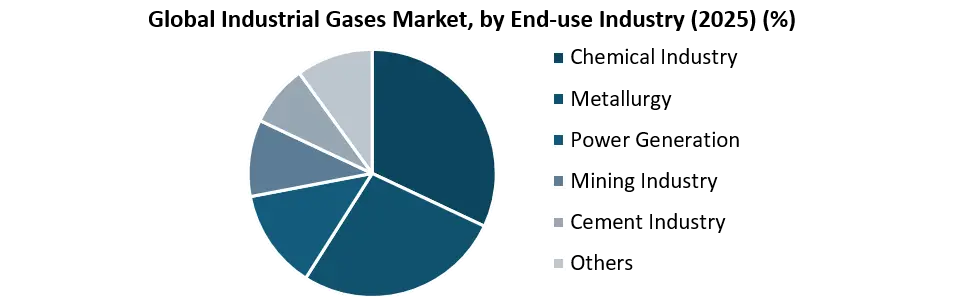
4.4. Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
4.4.1. Cement Industry
4.4.2. Mining Industry
4.4.3. Power Generation
4.4.4. Chemical Industry
4.4.5. Metallurgy
4.4.6. Others
4.5. Industrial Gases Market Size and Forecast, by Region (2025-2034)
4.5.1. North America
4.5.2. Europe
4.5.3. Asia Pacific
4.5.4. Middle East and Africa
4.5.5. South America
5. North America Industrial Gases Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
5.1. North America Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
5.1.1. Oxygen
5.1.2. Carbon Dioxide
5.1.3. Nitrogen
5.1.4. Hydrogen
5.1.5. Noble Gas
5.1.6. Helium
5.1.7. Argon
5.1.8. Others (Neon, Krypton, Xenon, and Radon)
5.2. North America Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
5.2.1. Cryogenic Air Separation
5.2.2. Non-Cryogenic Air Separation
5.2.3. Steam Methane Reforming (SMR)
5.2.4. Electrolysis
5.2.5. Others
5.3. North America Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
5.3.1. Merchant (Bulk & Cylinder)
5.3.2. Tonnage (On-site Supply)
5.3.3. Packaged Gases
5.4. North America Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
5.4.1. Cement Industry
5.4.2. Mining Industry
5.4.3. Power Generation
5.4.4. Chemical Industry
5.4.5. Metallurgy
5.4.6. Others
5.5. North America Industrial Gases Market Size and Forecast, by Country (2025-2034)
5.5.1. United States
5.5.1.1. United States Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
5.5.1.1.1. Oxygen
5.5.1.1.2. Carbon Dioxide
5.5.1.1.3. Nitrogen
5.5.1.1.4. Hydrogen
5.5.1.1.5. Noble Gas
5.5.1.1.6. Helium
5.5.1.1.7. Argon
5.5.1.1.8. Others (Neon, Krypton, Xenon, and Radon)
5.5.1.2. United States Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
5.5.1.2.1. Cryogenic Air Separation
5.5.1.2.2. Non-Cryogenic Air Separation
5.5.1.2.3. Steam Methane Reforming (SMR)
5.5.1.2.4. Electrolysis
5.5.1.2.5. Others
5.5.1.3. United States Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
5.5.1.3.1. Merchant (Bulk & Cylinder)
5.5.1.3.2. Tonnage (On-site Supply)
5.5.1.3.3. Packaged Gases
5.5.1.4. United States Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
5.5.1.4.1. Cement Industry
5.5.1.4.2. Mining Industry
5.5.1.4.3. Power Generation
5.5.1.4.4. Chemical Industry
5.5.1.4.5. Metallurgy
5.5.1.4.6. Others
5.5.2. Canada
5.5.2.1. Canada Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
5.5.2.1.1. Oxygen
5.5.2.1.2. Carbon Dioxide
5.5.2.1.3. Nitrogen
5.5.2.1.4. Hydrogen
5.5.2.1.5. Noble Gas
5.5.2.1.6. Helium
5.5.2.1.7. Argon
5.5.2.1.8. Others (Neon, Krypton, Xenon, and Radon)
5.5.2.2. Canada Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
5.5.2.2.1. Cryogenic Air Separation
5.5.2.2.2. Non-Cryogenic Air Separation
5.5.2.2.3. Steam Methane Reforming (SMR)
5.5.2.2.4. Electrolysis
5.5.2.2.5. Others
5.5.2.3. Canada Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
5.5.2.3.1. Merchant (Bulk & Cylinder)
5.5.2.3.2. Tonnage (On-site Supply)
5.5.2.3.3. Packaged Gases
5.5.2.4. Canada Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
5.5.2.4.1. Cement Industry
5.5.2.4.2. Mining Industry
5.5.2.4.3. Power Generation
5.5.2.4.4. Chemical Industry
5.5.2.4.5. Metallurgy
5.5.2.4.6. Others
5.5.3. Mexico
5.5.3.1. Mexico Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
5.5.3.1.1. Oxygen
5.5.3.1.2. Carbon Dioxide
5.5.3.1.3. Nitrogen
5.5.3.1.4. Hydrogen
5.5.3.1.5. Noble Gas
5.5.3.1.6. Helium
5.5.3.1.7. Argon
5.5.3.1.8. Others (Neon, Krypton, Xenon, and Radon)
5.5.3.2. Mexico Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
5.5.3.2.1. Cryogenic Air Separation
5.5.3.2.2. Non-Cryogenic Air Separation
5.5.3.2.3. Steam Methane Reforming (SMR)
5.5.3.2.4. Electrolysis
5.5.3.2.5. Others
5.5.3.3. Mexico Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
5.5.3.3.1. Merchant (Bulk & Cylinder)
5.5.3.3.2. Tonnage (On-site Supply)
5.5.3.3.3. Packaged Gases
5.5.3.4. Mexico Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
5.5.3.4.1. Cement Industry
5.5.3.4.2. Mining Industry
5.5.3.4.3. Power Generation
5.5.3.4.4. Chemical Industry
5.5.3.4.5. Metallurgy
5.5.3.4.6. Others
6. Europe Industrial Gases Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
6.1. Europe Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.1.1. Oxygen
6.1.2. Carbon Dioxide
6.1.3. Nitrogen
6.1.4. Hydrogen
6.1.5. Noble Gas
6.1.6. Helium
6.1.7. Argon
6.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.2. Europe Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.2.1. Cryogenic Air Separation
6.2.2. Non-Cryogenic Air Separation
6.2.3. Steam Methane Reforming (SMR)
6.2.4. Electrolysis
6.2.5. Others
6.3. Europe Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.3.1. Merchant (Bulk & Cylinder)
6.3.2. Tonnage (On-site Supply)
6.3.3. Packaged Gases
6.4. Europe Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.4.1. Cement Industry
6.4.2. Mining Industry
6.4.3. Power Generation
6.4.4. Chemical Industry
6.4.5. Metallurgy
6.4.6. Others
6.5. Europe Industrial Gases Market Size and Forecast, by Country (2025-2034)
6.5.1. United Kingdom
6.5.1.1. United Kingdom Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.1.1.1. Oxygen
6.5.1.1.2. Carbon Dioxide
6.5.1.1.3. Nitrogen
6.5.1.1.4. Hydrogen
6.5.1.1.5. Noble Gas
6.5.1.1.6. Helium
6.5.1.1.7. Argon
6.5.1.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.1.2. United Kingdom Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.1.2.1. Cryogenic Air Separation
6.5.1.2.2. Non-Cryogenic Air Separation
6.5.1.2.3. Steam Methane Reforming (SMR)
6.5.1.2.4. Electrolysis
6.5.1.2.5. Others
6.5.1.3. United Kingdom Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.1.3.1. Merchant (Bulk & Cylinder)
6.5.1.3.2. Tonnage (On-site Supply)
6.5.1.3.3. Packaged Gases
6.5.1.4. United Kingdom Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.1.4.1. Cement Industry
6.5.1.4.2. Mining Industry
6.5.1.4.3. Power Generation
6.5.1.4.4. Chemical Industry
6.5.1.4.5. Metallurgy
6.5.1.4.6. Others
6.5.2. France
6.5.2.1. France Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.2.1.1. Oxygen
6.5.2.1.2. Carbon Dioxide
6.5.2.1.3. Nitrogen
6.5.2.1.4. Hydrogen
6.5.2.1.5. Noble Gas
6.5.2.1.6. Helium
6.5.2.1.7. Argon
6.5.2.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.2.2. France Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.2.2.1. Cryogenic Air Separation
6.5.2.2.2. Non-Cryogenic Air Separation
6.5.2.2.3. Steam Methane Reforming (SMR)
6.5.2.2.4. Electrolysis
6.5.2.2.5. Others
6.5.2.3. France Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.2.3.1. Merchant (Bulk & Cylinder)
6.5.2.3.2. Tonnage (On-site Supply)
6.5.2.3.3. Packaged Gases
6.5.2.4. France Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.2.4.1. Cement Industry
6.5.2.4.2. Mining Industry
6.5.2.4.3. Power Generation
6.5.2.4.4. Chemical Industry
6.5.2.4.5. Metallurgy
6.5.2.4.6. Others
6.5.3. Germany
6.5.3.1. Germany Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.3.1.1. Oxygen
6.5.3.1.2. Carbon Dioxide
6.5.3.1.3. Nitrogen
6.5.3.1.4. Hydrogen
6.5.3.1.5. Noble Gas
6.5.3.1.6. Helium
6.5.3.1.7. Argon
6.5.3.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.3.2. Germany Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.3.2.1. Cryogenic Air Separation
6.5.3.2.2. Non-Cryogenic Air Separation
6.5.3.2.3. Steam Methane Reforming (SMR)
6.5.3.2.4. Electrolysis
6.5.3.2.5. Others
6.5.3.3. Germany Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.3.3.1. Merchant (Bulk & Cylinder)
6.5.3.3.2. Tonnage (On-site Supply)
6.5.3.3.3. Packaged Gases
6.5.3.4. Germany Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.3.4.1. Cement Industry
6.5.3.4.2. Mining Industry
6.5.3.4.3. Power Generation
6.5.3.4.4. Chemical Industry
6.5.3.4.5. Metallurgy
6.5.3.4.6. Others
6.5.4. Italy
6.5.4.1. Italy Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.4.1.1. Oxygen
6.5.4.1.2. Carbon Dioxide
6.5.4.1.3. Nitrogen
6.5.4.1.4. Hydrogen
6.5.4.1.5. Noble Gas
6.5.4.1.6. Helium
6.5.4.1.7. Argon
6.5.4.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.4.2. Italy Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.4.2.1. Cryogenic Air Separation
6.5.4.2.2. Non-Cryogenic Air Separation
6.5.4.2.3. Steam Methane Reforming (SMR)
6.5.4.2.4. Electrolysis
6.5.4.2.5. Others
6.5.4.3. Italy Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.4.3.1. Merchant (Bulk & Cylinder)
6.5.4.3.2. Tonnage (On-site Supply)
6.5.4.3.3. Packaged Gases
6.5.4.4. Italy Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.4.4.1. Cement Industry
6.5.4.4.2. Mining Industry
6.5.4.4.3. Power Generation
6.5.4.4.4. Chemical Industry
6.5.4.4.5. Metallurgy
6.5.4.4.6. Others
6.5.5. Spain
6.5.5.1. Spain Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.5.1.1. Oxygen
6.5.5.1.2. Carbon Dioxide
6.5.5.1.3. Nitrogen
6.5.5.1.4. Hydrogen
6.5.5.1.5. Noble Gas
6.5.5.1.6. Helium
6.5.5.1.7. Argon
6.5.5.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.5.2. Spain Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.5.2.1. Cryogenic Air Separation
6.5.5.2.2. Non-Cryogenic Air Separation
6.5.5.2.3. Steam Methane Reforming (SMR)
6.5.5.2.4. Electrolysis
6.5.5.2.5. Others
6.5.5.3. Spain Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.5.3.1. Merchant (Bulk & Cylinder)
6.5.5.3.2. Tonnage (On-site Supply)
6.5.5.3.3. Packaged Gases
6.5.5.4. Spain Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.5.4.1. Cement Industry
6.5.5.4.2. Mining Industry
6.5.5.4.3. Power Generation
6.5.5.4.4. Chemical Industry
6.5.5.4.5. Metallurgy
6.5.5.4.6. Others
6.5.6. Sweden
6.5.6.1. Sweden Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.6.1.1. Oxygen
6.5.6.1.2. Carbon Dioxide
6.5.6.1.3. Nitrogen
6.5.6.1.4. Hydrogen
6.5.6.1.5. Noble Gas
6.5.6.1.6. Helium
6.5.6.1.7. Argon
6.5.6.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.6.2. Sweden Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.6.2.1. Cryogenic Air Separation
6.5.6.2.2. Non-Cryogenic Air Separation
6.5.6.2.3. Steam Methane Reforming (SMR)
6.5.6.2.4. Electrolysis
6.5.6.2.5. Others
6.5.6.3. Sweden Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.6.3.1. Merchant (Bulk & Cylinder)
6.5.6.3.2. Tonnage (On-site Supply)
6.5.6.3.3. Packaged Gases
6.5.6.4. Sweden Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.6.4.1. Cement Industry
6.5.6.4.2. Mining Industry
6.5.6.4.3. Power Generation
6.5.6.4.4. Chemical Industry
6.5.6.4.5. Metallurgy
6.5.6.4.6. Others
6.5.7. Austria
6.5.7.1. Austria Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.7.1.1. Oxygen
6.5.7.1.2. Carbon Dioxide
6.5.7.1.3. Nitrogen
6.5.7.1.4. Hydrogen
6.5.7.1.5. Noble Gas
6.5.7.1.6. Helium
6.5.7.1.7. Argon
6.5.7.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.7.2. Austria Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.7.2.1. Cryogenic Air Separation
6.5.7.2.2. Non-Cryogenic Air Separation
6.5.7.2.3. Steam Methane Reforming (SMR)
6.5.7.2.4. Electrolysis
6.5.7.2.5. Others
6.5.7.3. Austria Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.7.3.1. Merchant (Bulk & Cylinder)
6.5.7.3.2. Tonnage (On-site Supply)
6.5.7.3.3. Packaged Gases
6.5.7.4. Austria Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.7.4.1. Cement Industry
6.5.7.4.2. Mining Industry
6.5.7.4.3. Power Generation
6.5.7.4.4. Chemical Industry
6.5.7.4.5. Metallurgy
6.5.7.4.6. Others
6.5.8. Rest of Europe
6.5.8.1. Rest of Europe Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
6.5.8.1.1. Oxygen
6.5.8.1.2. Carbon Dioxide
6.5.8.1.3. Nitrogen
6.5.8.1.4. Hydrogen
6.5.8.1.5. Noble Gas
6.5.8.1.6. Helium
6.5.8.1.7. Argon
6.5.8.1.8. Others (Neon, Krypton, Xenon, and Radon)
6.5.8.2. Rest of Europe Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
6.5.8.2.1. Cryogenic Air Separation
6.5.8.2.2. Non-Cryogenic Air Separation
6.5.8.2.3. Steam Methane Reforming (SMR)
6.5.8.2.4. Electrolysis
6.5.8.2.5. Others
6.5.8.3. Rest of Europe Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
6.5.8.3.1. Merchant (Bulk & Cylinder)
6.5.8.3.2. Tonnage (On-site Supply)
6.5.8.3.3. Packaged Gases
6.5.8.4. Rest of Europe Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
6.5.8.4.1. Cement Industry
6.5.8.4.2. Mining Industry
6.5.8.4.3. Power Generation
6.5.8.4.4. Chemical Industry
6.5.8.4.5. Metallurgy
6.5.8.4.6. Others
7. Asia Pacific Industrial Gases Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
7.1. Asia Pacific Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.1.1. Oxygen
7.1.2. Carbon Dioxide
7.1.3. Nitrogen
7.1.4. Hydrogen
7.1.5. Noble Gas
7.1.6. Helium
7.1.7. Argon
7.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.2. Asia Pacific Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.2.1. Cryogenic Air Separation
7.2.2. Non-Cryogenic Air Separation
7.2.3. Steam Methane Reforming (SMR)
7.2.4. Electrolysis
7.2.5. Others
7.3. Asia Pacific Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.3.1. Merchant (Bulk & Cylinder)
7.3.2. Tonnage (On-site Supply)
7.3.3. Packaged Gases
7.4. Asia Pacific Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.4.1. Cement Industry
7.4.2. Mining Industry
7.4.3. Power Generation
7.4.4. Chemical Industry
7.4.5. Metallurgy
7.4.6. Others
7.5. Asia Pacific Industrial Gases Market Size and Forecast, by Country (2025-2034)
7.5.1. China
7.5.1.1. China Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.1.1.1. Oxygen
7.5.1.1.2. Carbon Dioxide
7.5.1.1.3. Nitrogen
7.5.1.1.4. Hydrogen
7.5.1.1.5. Noble Gas
7.5.1.1.6. Helium
7.5.1.1.7. Argon
7.5.1.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.1.2. China Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.1.2.1. Cryogenic Air Separation
7.5.1.2.2. Non-Cryogenic Air Separation
7.5.1.2.3. Steam Methane Reforming (SMR)
7.5.1.2.4. Electrolysis
7.5.1.2.5. Others
7.5.1.3. China Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.1.3.1. Merchant (Bulk & Cylinder)
7.5.1.3.2. Tonnage (On-site Supply)
7.5.1.3.3. Packaged Gases
7.5.1.4. China Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.1.4.1. Cement Industry
7.5.1.4.2. Mining Industry
7.5.1.4.3. Power Generation
7.5.1.4.4. Chemical Industry
7.5.1.4.5. Metallurgy
7.5.1.4.6. Others
7.5.2. S Korea
7.5.2.1. S Korea Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.2.1.1. Oxygen
7.5.2.1.2. Carbon Dioxide
7.5.2.1.3. Nitrogen
7.5.2.1.4. Hydrogen
7.5.2.1.5. Noble Gas
7.5.2.1.6. Helium
7.5.2.1.7. Argon
7.5.2.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.2.2. S Korea Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.2.2.1. Cryogenic Air Separation
7.5.2.2.2. Non-Cryogenic Air Separation
7.5.2.2.3. Steam Methane Reforming (SMR)
7.5.2.2.4. Electrolysis
7.5.2.2.5. Others
7.5.2.3. S Korea Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.2.3.1. Merchant (Bulk & Cylinder)
7.5.2.3.2. Tonnage (On-site Supply)
7.5.2.3.3. Packaged Gases
7.5.2.4. S Korea Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.2.4.1. Cement Industry
7.5.2.4.2. Mining Industry
7.5.2.4.3. Power Generation
7.5.2.4.4. Chemical Industry
7.5.2.4.5. Metallurgy
7.5.2.4.6. Others
7.5.3. Japan
7.5.3.1. Japan Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.3.1.1. Oxygen
7.5.3.1.2. Carbon Dioxide
7.5.3.1.3. Nitrogen
7.5.3.1.4. Hydrogen
7.5.3.1.5. Noble Gas
7.5.3.1.6. Helium
7.5.3.1.7. Argon
7.5.3.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.3.2. Japan Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.3.2.1. Cryogenic Air Separation
7.5.3.2.2. Non-Cryogenic Air Separation
7.5.3.2.3. Steam Methane Reforming (SMR)
7.5.3.2.4. Electrolysis
7.5.3.2.5. Others
7.5.3.3. Japan Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.3.3.1. Merchant (Bulk & Cylinder)
7.5.3.3.2. Tonnage (On-site Supply)
7.5.3.3.3. Packaged Gases
7.5.3.4. Japan Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.3.4.1. Cement Industry
7.5.3.4.2. Mining Industry
7.5.3.4.3. Power Generation
7.5.3.4.4. Chemical Industry
7.5.3.4.5. Metallurgy
7.5.3.4.6. Others
7.5.4. India
7.5.4.1. India Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.4.1.1. Oxygen
7.5.4.1.2. Carbon Dioxide
7.5.4.1.3. Nitrogen
7.5.4.1.4. Hydrogen
7.5.4.1.5. Noble Gas
7.5.4.1.6. Helium
7.5.4.1.7. Argon
7.5.4.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.4.2. India Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.4.2.1. Cryogenic Air Separation
7.5.4.2.2. Non-Cryogenic Air Separation
7.5.4.2.3. Steam Methane Reforming (SMR)
7.5.4.2.4. Electrolysis
7.5.4.2.5. Others
7.5.4.3. India Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.4.3.1. Merchant (Bulk & Cylinder)
7.5.4.3.2. Tonnage (On-site Supply)
7.5.4.3.3. Packaged Gases
7.5.4.4. India Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.4.4.1. Cement Industry
7.5.4.4.2. Mining Industry
7.5.4.4.3. Power Generation
7.5.4.4.4. Chemical Industry
7.5.4.4.5. Metallurgy
7.5.4.4.6. Others
7.5.5. Australia
7.5.5.1. Australia Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.5.1.1. Oxygen
7.5.5.1.2. Carbon Dioxide
7.5.5.1.3. Nitrogen
7.5.5.1.4. Hydrogen
7.5.5.1.5. Noble Gas
7.5.5.1.6. Helium
7.5.5.1.7. Argon
7.5.5.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.5.2. Australia Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.5.2.1. Cryogenic Air Separation
7.5.5.2.2. Non-Cryogenic Air Separation
7.5.5.2.3. Steam Methane Reforming (SMR)
7.5.5.2.4. Electrolysis
7.5.5.2.5. Others
7.5.5.3. Australia Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.5.3.1. Merchant (Bulk & Cylinder)
7.5.5.3.2. Tonnage (On-site Supply)
7.5.5.3.3. Packaged Gases
7.5.5.4. Australia Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.5.4.1. Cement Industry
7.5.5.4.2. Mining Industry
7.5.5.4.3. Power Generation
7.5.5.4.4. Chemical Industry
7.5.5.4.5. Metallurgy
7.5.5.4.6. Others
7.5.6. Indonesia
7.5.6.1. Indonesia Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.6.1.1. Oxygen
7.5.6.1.2. Carbon Dioxide
7.5.6.1.3. Nitrogen
7.5.6.1.4. Hydrogen
7.5.6.1.5. Noble Gas
7.5.6.1.6. Helium
7.5.6.1.7. Argon
7.5.6.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.6.2. Indonesia Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.6.2.1. Cryogenic Air Separation
7.5.6.2.2. Non-Cryogenic Air Separation
7.5.6.2.3. Steam Methane Reforming (SMR)
7.5.6.2.4. Electrolysis
7.5.6.2.5. Others
7.5.6.3. Indonesia Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.6.3.1. Merchant (Bulk & Cylinder)
7.5.6.3.2. Tonnage (On-site Supply)
7.5.6.3.3. Packaged Gases
7.5.6.4. Indonesia Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.6.4.1. Cement Industry
7.5.6.4.2. Mining Industry
7.5.6.4.3. Power Generation
7.5.6.4.4. Chemical Industry
7.5.6.4.5. Metallurgy
7.5.6.4.6. Others
7.5.7. Malaysia
7.5.7.1. Malaysia Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.7.1.1. Oxygen
7.5.7.1.2. Carbon Dioxide
7.5.7.1.3. Nitrogen
7.5.7.1.4. Hydrogen
7.5.7.1.5. Noble Gas
7.5.7.1.6. Helium
7.5.7.1.7. Argon
7.5.7.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.7.2. Malaysia Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.7.2.1. Cryogenic Air Separation
7.5.7.2.2. Non-Cryogenic Air Separation
7.5.7.2.3. Steam Methane Reforming (SMR)
7.5.7.2.4. Electrolysis
7.5.7.2.5. Others
7.5.7.3. Malaysia Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.7.3.1. Merchant (Bulk & Cylinder)
7.5.7.3.2. Tonnage (On-site Supply)
7.5.7.3.3. Packaged Gases
7.5.7.4. Malaysia Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.7.4.1. Cement Industry
7.5.7.4.2. Mining Industry
7.5.7.4.3. Power Generation
7.5.7.4.4. Chemical Industry
7.5.7.4.5. Metallurgy
7.5.7.4.6. Others
7.5.8. Vietnam
7.5.8.1. Vietnam Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.8.1.1. Oxygen
7.5.8.1.2. Carbon Dioxide
7.5.8.1.3. Nitrogen
7.5.8.1.4. Hydrogen
7.5.8.1.5. Noble Gas
7.5.8.1.6. Helium
7.5.8.1.7. Argon
7.5.8.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.8.2. Vietnam Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.8.2.1. Cryogenic Air Separation
7.5.8.2.2. Non-Cryogenic Air Separation
7.5.8.2.3. Steam Methane Reforming (SMR)
7.5.8.2.4. Electrolysis
7.5.8.2.5. Others
7.5.8.3. Vietnam Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.8.3.1. Merchant (Bulk & Cylinder)
7.5.8.3.2. Tonnage (On-site Supply)
7.5.8.3.3. Packaged Gases
7.5.8.4. Vietnam Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.8.4.1. Cement Industry
7.5.8.4.2. Mining Industry
7.5.8.4.3. Power Generation
7.5.8.4.4. Chemical Industry
7.5.8.4.5. Metallurgy
7.5.8.4.6. Others
7.5.9. Taiwan
7.5.9.1. Taiwan Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.9.1.1. Oxygen
7.5.9.1.2. Carbon Dioxide
7.5.9.1.3. Nitrogen
7.5.9.1.4. Hydrogen
7.5.9.1.5. Noble Gas
7.5.9.1.6. Helium
7.5.9.1.7. Argon
7.5.9.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.9.2. Taiwan Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.9.2.1. Cryogenic Air Separation
7.5.9.2.2. Non-Cryogenic Air Separation
7.5.9.2.3. Steam Methane Reforming (SMR)
7.5.9.2.4. Electrolysis
7.5.9.2.5. Others
7.5.9.3. Taiwan Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.9.3.1. Merchant (Bulk & Cylinder)
7.5.9.3.2. Tonnage (On-site Supply)
7.5.9.3.3. Packaged Gases
7.5.9.4. Taiwan Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.9.4.1. Cement Industry
7.5.9.4.2. Mining Industry
7.5.9.4.3. Power Generation
7.5.9.4.4. Chemical Industry
7.5.9.4.5. Metallurgy
7.5.9.4.6. Others
7.5.10. Rest of Asia Pacific
7.5.10.1. Rest of Asia Pacific Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
7.5.10.1.1. Oxygen
7.5.10.1.2. Carbon Dioxide
7.5.10.1.3. Nitrogen
7.5.10.1.4. Hydrogen
7.5.10.1.5. Noble Gas
7.5.10.1.6. Helium
7.5.10.1.7. Argon
7.5.10.1.8. Others (Neon, Krypton, Xenon, and Radon)
7.5.10.2. Rest of Asia Pacific Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
7.5.10.2.1. Cryogenic Air Separation
7.5.10.2.2. Non-Cryogenic Air Separation
7.5.10.2.3. Steam Methane Reforming (SMR)
7.5.10.2.4. Electrolysis
7.5.10.2.5. Others
7.5.10.3. Rest of Asia Pacific Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
7.5.10.3.1. Merchant (Bulk & Cylinder)
7.5.10.3.2. Tonnage (On-site Supply)
7.5.10.3.3. Packaged Gases
7.5.10.4. Rest of Asia Pacific Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
7.5.10.4.1. Cement Industry
7.5.10.4.2. Mining Industry
7.5.10.4.3. Power Generation
7.5.10.4.4. Chemical Industry
7.5.10.4.5. Metallurgy
7.5.10.4.6. Others
8. Middle East and Africa Industrial Gases Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
8.1. Middle East and Africa Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
8.1.1. Oxygen
8.1.2. Carbon Dioxide
8.1.3. Nitrogen
8.1.4. Hydrogen
8.1.5. Noble Gas
8.1.6. Helium
8.1.7. Argon
8.1.8. Others (Neon, Krypton, Xenon, and Radon)
8.2. Middle East and Africa Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
8.2.1. Cryogenic Air Separation
8.2.2. Non-Cryogenic Air Separation
8.2.3. Steam Methane Reforming (SMR)
8.2.4. Electrolysis
8.2.5. Others
8.3. Middle East and Africa Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
8.3.1. Merchant (Bulk & Cylinder)
8.3.2. Tonnage (On-site Supply)
8.3.3. Packaged Gases
8.4. Middle East and Africa Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
8.4.1. Cement Industry
8.4.2. Mining Industry
8.4.3. Power Generation
8.4.4. Chemical Industry
8.4.5. Metallurgy
8.4.6. Others
8.5. Middle East and Africa Industrial Gases Market Size and Forecast, by Country (2025-2034)
8.5.1. South Africa
8.5.1.1. South Africa Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
8.5.1.1.1. Oxygen
8.5.1.1.2. Carbon Dioxide
8.5.1.1.3. Nitrogen
8.5.1.1.4. Hydrogen
8.5.1.1.5. Noble Gas
8.5.1.1.6. Helium
8.5.1.1.7. Argon
8.5.1.1.8. Others (Neon, Krypton, Xenon, and Radon)
8.5.1.2. South Africa Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
8.5.1.2.1. Cryogenic Air Separation
8.5.1.2.2. Non-Cryogenic Air Separation
8.5.1.2.3. Steam Methane Reforming (SMR)
8.5.1.2.4. Electrolysis
8.5.1.2.5. Others
8.5.1.3. South Africa Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
8.5.1.3.1. Merchant (Bulk & Cylinder)
8.5.1.3.2. Tonnage (On-site Supply)
8.5.1.3.3. Packaged Gases
8.5.1.4. South Africa Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
8.5.1.4.1. Cement Industry
8.5.1.4.2. Mining Industry
8.5.1.4.3. Power Generation
8.5.1.4.4. Chemical Industry
8.5.1.4.5. Metallurgy
8.5.1.4.6. Others
8.5.2. GCC
8.5.2.1. GCC Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
8.5.2.1.1. Oxygen
8.5.2.1.2. Carbon Dioxide
8.5.2.1.3. Nitrogen
8.5.2.1.4. Hydrogen
8.5.2.1.5. Noble Gas
8.5.2.1.6. Helium
8.5.2.1.7. Argon
8.5.2.1.8. Others (Neon, Krypton, Xenon, and Radon)
8.5.2.2. GCC Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
8.5.2.2.1. Cryogenic Air Separation
8.5.2.2.2. Non-Cryogenic Air Separation
8.5.2.2.3. Steam Methane Reforming (SMR)
8.5.2.2.4. Electrolysis
8.5.2.2.5. Others
8.5.2.3. GCC Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
8.5.2.3.1. Merchant (Bulk & Cylinder)
8.5.2.3.2. Tonnage (On-site Supply)
8.5.2.3.3. Packaged Gases
8.5.2.4. GCC Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
8.5.2.4.1. Cement Industry
8.5.2.4.2. Mining Industry
8.5.2.4.3. Power Generation
8.5.2.4.4. Chemical Industry
8.5.2.4.5. Metallurgy
8.5.2.4.6. Others
8.5.3. Nigeria
8.5.3.1. Nigeria Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
8.5.3.1.1. Oxygen
8.5.3.1.2. Carbon Dioxide
8.5.3.1.3. Nitrogen
8.5.3.1.4. Hydrogen
8.5.3.1.5. Noble Gas
8.5.3.1.6. Helium
8.5.3.1.7. Argon
8.5.3.1.8. Others (Neon, Krypton, Xenon, and Radon)
8.5.3.2. Nigeria Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
8.5.3.2.1. Cryogenic Air Separation
8.5.3.2.2. Non-Cryogenic Air Separation
8.5.3.2.3. Steam Methane Reforming (SMR)
8.5.3.2.4. Electrolysis
8.5.3.2.5. Others
8.5.3.3. Nigeria Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
8.5.3.3.1. Merchant (Bulk & Cylinder)
8.5.3.3.2. Tonnage (On-site Supply)
8.5.3.3.3. Packaged Gases
8.5.3.4. Nigeria Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
8.5.3.4.1. Cement Industry
8.5.3.4.2. Mining Industry
8.5.3.4.3. Power Generation
8.5.3.4.4. Chemical Industry
8.5.3.4.5. Metallurgy
8.5.3.4.6. Others
8.5.4. Rest of ME&A
8.5.4.1. Rest of ME&A Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
8.5.4.1.1. Oxygen
8.5.4.1.2. Carbon Dioxide
8.5.4.1.3. Nitrogen
8.5.4.1.4. Hydrogen
8.5.4.1.5. Noble Gas
8.5.4.1.6. Helium
8.5.4.1.7. Argon
8.5.4.1.8. Others (Neon, Krypton, Xenon, and Radon)
8.5.4.2. Rest of ME&A Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
8.5.4.2.1. Cryogenic Air Separation
8.5.4.2.2. Non-Cryogenic Air Separation
8.5.4.2.3. Steam Methane Reforming (SMR)
8.5.4.2.4. Electrolysis
8.5.4.2.5. Others
8.5.4.3. Rest of ME&A Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
8.5.4.3.1. Merchant (Bulk & Cylinder)
8.5.4.3.2. Tonnage (On-site Supply)
8.5.4.3.3. Packaged Gases
8.5.4.4. Rest of ME&A Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
8.5.4.4.1. Cement Industry
8.5.4.4.2. Mining Industry
8.5.4.4.3. Power Generation
8.5.4.4.4. Chemical Industry
8.5.4.4.5. Metallurgy
8.5.4.4.6. Others
9. South America Industrial Gases Market Size and Forecast by Segmentation (in USD Billion) 2025-2034
9.1. South America Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
9.1.1. Oxygen
9.1.2. Carbon Dioxide
9.1.3. Nitrogen
9.1.4. Hydrogen
9.1.5. Noble Gas
9.1.6. Helium
9.1.7. Argon
9.1.8. Others (Neon, Krypton, Xenon, and Radon)
9.2. South America Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
9.2.1. Cryogenic Air Separation
9.2.2. Non-Cryogenic Air Separation
9.2.3. Steam Methane Reforming (SMR)
9.2.4. Electrolysis
9.2.5. Others
9.3. South America Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
9.3.1. Merchant (Bulk & Cylinder)
9.3.2. Tonnage (On-site Supply)
9.3.3. Packaged Gases
9.4. South America Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
9.4.1. Cement Industry
9.4.2. Mining Industry
9.4.3. Power Generation
9.4.4. Chemical Industry
9.4.5. Metallurgy
9.4.6. Others
9.5. South America Industrial Gases Market Size and Forecast, by Country (2025-2034)
9.5.1. Brazil
9.5.1.1. Brazil Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
9.5.1.1.1. Oxygen
9.5.1.1.2. Carbon Dioxide
9.5.1.1.3. Nitrogen
9.5.1.1.4. Hydrogen
9.5.1.1.5. Noble Gas
9.5.1.1.6. Helium
9.5.1.1.7. Argon
9.5.1.1.8. Others (Neon, Krypton, Xenon, and Radon)
9.5.1.2. Brazil Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
9.5.1.2.1. Cryogenic Air Separation
9.5.1.2.2. Non-Cryogenic Air Separation
9.5.1.2.3. Steam Methane Reforming (SMR)
9.5.1.2.4. Electrolysis
9.5.1.2.5. Others
9.5.1.3. Brazil Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
9.5.1.3.1. Merchant (Bulk & Cylinder)
9.5.1.3.2. Tonnage (On-site Supply)
9.5.1.3.3. Packaged Gases
9.5.1.4. Brazil Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
9.5.1.4.1. Cement Industry
9.5.1.4.2. Mining Industry
9.5.1.4.3. Power Generation
9.5.1.4.4. Chemical Industry
9.5.1.4.5. Metallurgy
9.5.1.4.6. Others
9.5.2. Argentina
9.5.2.1. Argentina Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
9.5.2.1.1. Oxygen
9.5.2.1.2. Carbon Dioxide
9.5.2.1.3. Nitrogen
9.5.2.1.4. Hydrogen
9.5.2.1.5. Noble Gas
9.5.2.1.6. Helium
9.5.2.1.7. Argon
9.5.2.1.8. Others (Neon, Krypton, Xenon, and Radon)
9.5.2.2. Argentina Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
9.5.2.2.1. Cryogenic Air Separation
9.5.2.2.2. Non-Cryogenic Air Separation
9.5.2.2.3. Steam Methane Reforming (SMR)
9.5.2.2.4. Electrolysis
9.5.2.2.5. Others
9.5.2.3. Argentina Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
9.5.2.3.1. Merchant (Bulk & Cylinder)
9.5.2.3.2. Tonnage (On-site Supply)
9.5.2.3.3. Packaged Gases
9.5.2.4. Argentina Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
9.5.2.4.1. Cement Industry
9.5.2.4.2. Mining Industry
9.5.2.4.3. Power Generation
9.5.2.4.4. Chemical Industry
9.5.2.4.5. Metallurgy
9.5.2.4.6. Others
9.5.3. Rest Of South America
9.5.3.1. Rest Of South America Industrial Gases Market Size and Forecast, by Gas Type (2025-2034)
9.5.3.1.1. Oxygen
9.5.3.1.2. Carbon Dioxide
9.5.3.1.3. Nitrogen
9.5.3.1.4. Hydrogen
9.5.3.1.5. Noble Gas
9.5.3.1.6. Helium
9.5.3.1.7. Argon
9.5.3.1.8. Others (Neon, Krypton, Xenon, and Radon)
9.5.3.2. Rest Of South America Industrial Gases Market Size and Forecast, by Production Process (2025-2034)
9.5.3.2.1. Cryogenic Air Separation
9.5.3.2.2. Non-Cryogenic Air Separation
9.5.3.2.3. Steam Methane Reforming (SMR)
9.5.3.2.4. Electrolysis
9.5.3.2.5. Others
9.5.3.3. Rest Of South America Industrial Gases Market Size and Forecast, by Distribution Mode (2025-2034)
9.5.3.3.1. Merchant (Bulk & Cylinder)
9.5.3.3.2. Tonnage (On-site Supply)
9.5.3.3.3. Packaged Gases
9.5.3.4. Rest Of South America Industrial Gases Market Size and Forecast, by End Use Industry (2025-2034)
9.5.3.4.1. Cement Industry
9.5.3.4.2. Mining Industry
9.5.3.4.3. Power Generation
9.5.3.4.4. Chemical Industry
9.5.3.4.5. Metallurgy
9.5.3.4.6. Others
10. Company Profile: Key Players
10.1. AGA AB
10.1.1. Company Overview
10.1.2. Business Portfolio
10.1.3. Financial Overview
10.1.4. SWOT Analysis
10.1.5. Strategic Analysis
10.1.6. Scale of Operation (small, medium, and large)
10.1.7. Details on Partnership
10.1.8. Regulatory Accreditations and Certifications Received by Them
10.1.9. Awards Received by the Firm
10.1.10. Recent Developments
10.2. Airgas
10.3. Air Liquide
10.4. Air Products and Chemicals, Inc.
10.5. BASF SE
10.6. BOC
10.7. Gulf Cryo
10.8. Linde plc
10.9. Messer Group
10.10. MOX-Linde Gases
10.11. Praxair
10.12. Nippon Gases
10.13. Matheson Tri-Gas
10.14. Rotarex
10.15. Universal Industrial Gases, Inc.
10.16. Dubai Industrial Gases
10.17. Bristol Gases
10.18. INOX-Air Products Inc.
10.19. Iwatani Corporation
10.20. SOL Group
10.21. Taiyo Nippon Sanso Corporation
10.22. Air Water Inc.
10.23. Coregas Pty Ltd.
10.24. Ellenbarrie Industrial Gases Ltd.
10.25. Bhuruka Gases Limited
10.26. Buzwair Industrial Gases Factories
10.27. Asia Industrial Gases Pte. Ltd.
10.28. SIAD Group
10.29. Strandmøllen A/S
10.30. Yingde Gases Group
10.31. nexAir LLC
10.32. Sapio Group
10.33. PT Samator Indo Gas Tbk
10.34. SIG Gases Berhad
10.35. Gases Plus
10.36. Universal Boschi
10.37. Concorde-Corodex Group
10.38. Southern Industrial Gas Berhad
10.39. Airgas USA LLC
10.40. Cryogenic Industrial Solutions
10.41. Linde Engineering
10.42. Air Liquide Advanced Technologies
10.43. Air Products Membrane Solutions
10.44. Nippon Sanso Engineering
10.45. Hangyang Group
10.46. Sichuan Qiaoyuan Gas Co., Ltd.
10.47. Messer North America
10.48. Westfalen AG
10.49. SOL Nederland
10.50. Abdullah Hashim Industrial Gases & Equipment Co. Ltd.
11. Key Findings
12. Industry Recommendations
13. Industrial Gases Market: Research Methodology
14. Terms and Glossary