
Global Water Electrolysis Market Size by Technology Type and End User – Segment-Level Market Assessment, Growth Opportunity Analysis, Competitive Landscape & Forecast to 2034
Overview
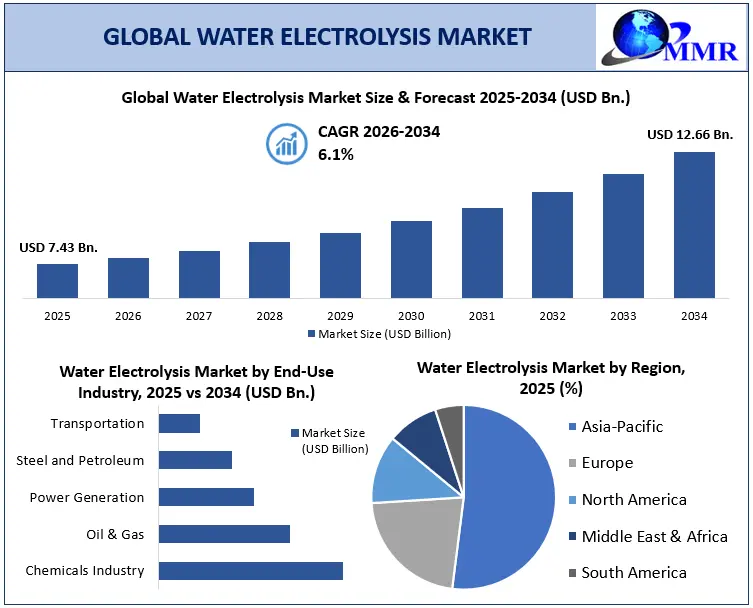
The Water Electrolysis Market size was valued at USD 7.43 Billion in 2025 and the total Water Electrolysis revenue is expected to grow at a CAGR of 6.1% from 2026 to 2034, reaching USD 12.66 Billion by 2034.
Water Electrolysis Market Overview
Water electrolysis is a hydrogen-production process in which electricity is used to split water into hydrogen and oxygen through an electrolyzer. The Water Electrolysis Market covers the equipment, systems, and technologies used for this process, including alkaline, proton exchange membrane (PEM), and emerging solid-oxide and anion exchange membrane systems. The technology is particularly important for producing low-emissions hydrogen when the electricity comes from renewable or nuclear sources.
The market matters because hydrogen is already widely used in refining, ammonia, methanol and other industrial processes, while new demand is developing in areas such as low-carbon steel, power generation, synthetic fuels and heavy transport. Global hydrogen demand surpassed 100 million tonnes in 2025, but low-emissions hydrogen still represents a small share of total production, leaving substantial scope for electrolysis-based production to expand.
The market is changing as electrolyzer projects move from small demonstrations toward larger commercial installations. Global installed electrolysis capacity more than doubled in 2025 to above 4 GW, while more than 2.5 GW was under construction. At the same time, manufacturers are working to reduce equipment costs, improve efficiency and durability, increase production scale, and develop technologies that can respond better to variable renewable electricity. China currently accounts for a major share of new installations, while Europe is also emerging as an important investment market.
The main buyers and users include hydrogen producers, oil refineries, chemical and fertilizer companies, steel manufacturers, energy utilities, renewable-energy developers and industrial gas companies. Refining and chemical applications currently represent the established demand base, while newer buyers are emerging around green steel, sustainable fuels, energy storage and clean-energy projects.
The opportunity is therefore concentrated across the electrolyzer equipment supply chain, large-scale hydrogen projects, renewable-energy integration and industrial decarbonization. Opportunities are also developing in PEM, alkaline, AEM and solid-oxide technologies, as companies seek different combinations of cost, efficiency, flexibility and operating performance. However, project economics remain important: high upfront costs, uncertain hydrogen demand, regulatory complexity, infrastructure gaps and competition from lower-cost fossil-based hydrogen continue to affect project development.
According to MMR's research, the Global Water Electrolysis Market was valued at USD 7.43 billion in 2025 and is projected to reach USD 12.66 billion by 2034, growing at a CAGR of 6.1% during 2026–2034. The research therefore points to a market moving from an emerging clean-hydrogen technology toward a broader industrial equipment market, supported by increasing hydrogen requirements, investment in electrolysis projects, technology improvements and the expansion of low-emissions hydrogen production. At the same time, the market's development will depend on how quickly project costs decline, infrastructure develops and industrial users commit to long-term hydrogen procurement.
Water Electrolysis Market Size, Share and Growth Analysis
To know about the Research Methodology :- Request Free Sample Report
Global Water Electrolysis Market Dynamics
Rising Demand for Low-Emission Hydrogen Is Accelerating the Deployment of Water Electrolysis Systems
The growing focus on reducing carbon emissions from industrial hydrogen production is increasing demand for water electrolysis technologies. Global hydrogen demand exceeded 100 million tonnes in 2025, while low-emissions hydrogen production continued to expand as governments and industries introduced decarbonization targets. Water electrolysis allows hydrogen to be produced using electricity and water, making it particularly suitable for projects connected to renewable power sources. Demand is developing across established applications such as refining, ammonia and methanol production, while new applications including green steel, sustainable fuels and energy storage are creating additional requirements for clean hydrogen. Increasing renewable power availability, government support for hydrogen projects and investments in large-scale electrolyzer facilities are therefore encouraging industrial users and energy companies to consider electrolysis as part of their long-term hydrogen supply strategies.
High Equipment Costs and Electricity Requirements Continue to Affect the Economic Viability of Water Electrolysis
The relatively high cost of electrolyzer systems and the electricity required to produce hydrogen remain important restraints for market adoption. Electrolyzer costs vary significantly depending on technology, manufacturing location, scale and project specifications. In 2024, electrolyzer installation costs outside China were estimated at around USD 2,000–2,600 per kW, compared with approximately USD 600–1,200 per kW for systems manufactured and installed in China. In addition to the initial equipment investment, project economics are strongly influenced by electricity prices because electricity represents a major component of hydrogen production costs. Developers also need to invest in hydrogen compression, storage, water treatment, power infrastructure and distribution facilities, increasing the overall capital requirement. These factors can make electrolysis-based hydrogen less competitive with conventional hydrogen production in regions where renewable electricity is expensive or financial support is limited.
Expansion of Large-Scale Hydrogen Projects Is Creating New Opportunities for Electrolyzer Manufacturers and System Suppliers
The development of large-scale low-emissions hydrogen projects is creating opportunities across the water electrolysis value chain, from electrolyzer manufacturers and component suppliers to engineering companies, renewable-energy developers and hydrogen infrastructure providers. By 2030, around 26 GW of electrolysis capacity had reached final investment decision or was under construction with planned operation by that year, demonstrating the increasing scale of projects moving beyond the demonstration stage. Growing investments in renewable power are also creating opportunities to integrate electrolyzers with solar and wind projects, allowing surplus or dedicated renewable electricity to be converted into hydrogen. In addition, industries such as steel, chemicals, refining and sustainable fuel production are exploring hydrogen as a way to reduce emissions from difficult-to-electrify processes. This expansion provides opportunities for companies to develop higher-efficiency electrolyzers, improve system durability, reduce manufacturing costs and offer integrated hydrogen production solutions for large industrial customers.
Project Delays, Financing Constraints and Uncertain Hydrogen Offtake Are Slowing Commercial Deployment
The water electrolysis market faces the challenge of converting the large number of announced hydrogen projects into financially viable and operational facilities. Developers must secure financing, suitable renewable electricity, regulatory approvals, infrastructure and reliable customers willing to purchase hydrogen over the long term. Uncertainty around future hydrogen prices and offtake agreements can make it difficult for developers to reach final investment decisions, particularly for projects requiring substantial upfront capital. In 2025, new final investment decisions for low-emissions hydrogen production fell below 0.8 million tonnes per year, compared with around 1 million tonnes per year in each of the previous two years. Project delays, changing government incentives, permitting requirements and the need to establish hydrogen transport and storage infrastructure can further extend development timelines. As a result, the market's expansion depends not only on electrolyzer technology improvements but also on the development of a reliable commercial ecosystem connecting electricity producers, hydrogen manufacturers and industrial end users.
Key Highlights of the Water Electrolysis Market
| Key Highlight | Market Insight |
| Electrolysis Investment Is Increasing | Capital spending on low-emissions hydrogen projects reached nearly USD 7 billion in 2025, almost double the 2024 level. Electrolysis-based projects attracted the larger share of this investment, reflecting increasing financial activity around electrolyzer deployment. |
| Manufacturing Capacity Has Expanded Rapidly | Global electrolyzer manufacturing capacity reached nearly 38 GW per year in 2024, representing a 40% increase from the previous year. However, actual production was only around 4 GW, indicating substantial unused manufacturing capacity and increasing pressure on manufacturers to secure projects. |
| Large Project Pipeline Creates Future Demand | More than 100 GW of announced electrolysis capacity could potentially miss the 2030 operating target if investment decisions are not secured before the end of 2027. This highlights the size of the future project pipeline while also showing the importance of financing and project execution. |
| Low-Emissions Hydrogen Production Is Expanding | Low-emissions hydrogen production reached almost 1 million tonnes in 2025 and is expected to record strong growth in 2026. This expanding production base is supporting additional demand for electrolyzers and related hydrogen-production infrastructure. |
Global Water Electrolysis Market Segment Analysis
By Technology Type
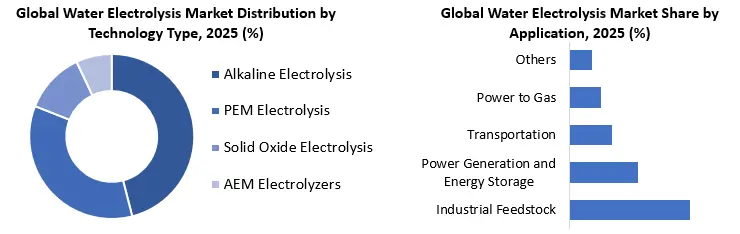
The Alkaline Electrolysis segment holds a leading position in the Water Electrolysis Market because of its established commercial use, relatively lower capital requirements, proven reliability, and suitability for large-scale hydrogen production. Alkaline systems are particularly relevant for industrial projects where hydrogen production is required at a steady operating rate. PEM Electrolysis is gaining importance because of its compact design, rapid response and ability to work effectively with variable renewable electricity, making it suitable for projects connected with solar and wind power. Solid Oxide Electrolysis is being developed for applications where high operating temperatures and integration with available heat sources can improve overall efficiency, while AEM Electrolyzers are an emerging technology that seeks to combine some of the advantages of alkaline and PEM systems with reduced dependence on expensive catalyst materials. MMR identifies alkaline electrolyzers as the largest technology segment, while PEM is expected to witness faster growth as renewable hydrogen projects expand.
By Application
The Industrial Feedstock segment represents the core application area for water electrolysis because hydrogen is extensively required in industrial processes such as ammonia, methanol and petroleum refining. As industries seek to reduce emissions associated with conventional hydrogen production, electrolyzers are increasingly being considered for supplying hydrogen directly to industrial facilities. Power Generation and Energy Storage applications are also gaining importance as hydrogen can be produced using electricity during periods of renewable power availability and subsequently stored or used for energy generation. Transportation is another emerging application, particularly for fuel-cell vehicles and hydrogen refueling infrastructure, while Power-to-Gas systems use electrolysis to convert electricity into hydrogen that can be stored, transported or potentially integrated into gas-related energy systems. The Others category covers additional uses where electrolytic hydrogen can support emerging clean-energy and industrial applications. MMR identifies industrial feedstock as the largest application segment and transportation as an application with strong growth potential.
Global Water Electrolysis Market Regional Insights
The Asia-Pacific region is the leading region for the Water Electrolysis Market, supported by strong electrolyzer manufacturing, large industrial hydrogen demand and government-backed clean hydrogen programs. China is the dominant country in the region and globally, accounting for nearly three-quarters of new electrolysis installations in 2025. China also has close to 60% of global electrolyzer manufacturing capacity, supported by large domestic projects and established clean-energy manufacturing capabilities. India is emerging as another important market, particularly because of its focus on green hydrogen for refining, fertilizers and other industrial applications. Japan and South Korea are developing hydrogen applications mainly around power generation and hydrogen-based fuels, while countries such as Australia are developing large renewable-hydrogen projects supported by abundant renewable resources. Southeast Asia also presents opportunities, with Indonesia, Malaysia and Vietnam focusing on hydrogen for ammonia, methanol and steel production, while Singapore is exploring hydrogen-based maritime fuels.
Europe represents an important market for water electrolysis because of its strong decarbonization policies, renewable-energy development and targets for replacing fossil-based hydrogen in industrial applications. The European Union has established a target of 40 GW of domestic electrolyzer capacity by 2030, while more than 2 GW of European electrolysis projects reached final investment decision between September 2023 and August 2024. Germany, Spain, the Netherlands and France are among the countries developing hydrogen and electrolyzer projects, with applications concentrated around refining, chemicals, steel and renewable-energy integration. Europe is also developing demand-side measures for hydrogen use in industry and transport, although slower policy implementation and project delays remain factors affecting the pace of deployment.
North America is developing its water electrolysis market through hydrogen hubs, industrial decarbonization programs and clean-energy investments. The United States has been emphasizing hydrogen hubs and financial incentives, although its low-emissions hydrogen development includes both electrolysis and carbon-capture-based production. The region's large refining, chemicals, steel and transportation industries provide potential demand for electrolytic hydrogen, while access to renewable electricity and existing energy infrastructure can support project development. Canada is also developing clean hydrogen projects using its renewable and low-carbon electricity resources, with opportunities extending across industrial applications, transportation and hydrogen exports.
Middle East & Africa is developing water electrolysis primarily through very large green hydrogen and hydrogen-derivative projects. Saudi Arabia is a key country in the region, with the NEOM Green Hydrogen Project targeting approximately 2.2 GW of electrolyzer capacity by 2027. The region benefits from strong solar resources and opportunities to combine renewable electricity with hydrogen production, particularly for ammonia and other export-oriented products. Oman, the United Arab Emirates and Egypt are also developing hydrogen projects linked to renewable energy and industrial or export applications. However, project financing, infrastructure development, water availability and the creation of reliable international offtake arrangements remain important considerations for large-scale deployment.
South America has significant long-term potential because countries such as Chile and Brazil have strong renewable-energy resources and established industrial sectors that can create demand for low-emissions hydrogen. Chile is developing projects around renewable hydrogen and ammonia, while Brazil has opportunities linked to industrial production, refining, steel and export-oriented hydrogen derivatives. The region is also part of the broader announced electrolysis pipeline, although many projects remain at development stages and face challenges related to financing, regulation, infrastructure and securing long-term offtake agreements.
Global Water Electrolysis Market Regional Outlook
Overall, Asia-Pacific is characterized by large-scale deployment and manufacturing, Europe by policy-driven demand and industrial decarbonization, North America by hydrogen hubs and incentives, the Middle East & Africa by large renewable-hydrogen export projects, and South America by renewable-resource-based project development. Globally, installed electrolysis capacity surpassed 4 GW in 2025, with more than 2.5 GW under construction and targeting operation in 2026. The IEA expects much of the near-term additional capacity to come from Europe, although deployment remains concentrated in a limited number of large projects.
Global Water Electrolysis Market Competitive Landscape
The Water Electrolysis Market is witnessing increasing competition as companies expand electrolyzer production, improve system efficiency and participate in large-scale hydrogen projects. The market includes established industrial technology companies as well as specialized hydrogen and electrolyzer manufacturers. Competition is mainly shaped by technology capabilities, production capacity, system efficiency, project scale, cost reduction and regional presence.
| Company | Key Competitive Focus | Major Technology / Strength |
| Nel ASA | Large-scale hydrogen production and technology development | Alkaline & PEM |
| thyssenkrupp nucera | Large industrial electrolysis projects | Alkaline & PEM |
| ITM Power plc | Large-scale renewable hydrogen projects | PEM |
| Siemens Energy AG | Renewable hydrogen and integrated energy systems | PEM |
| Plug Power Inc. | Green hydrogen production and integrated solutions | PEM |
| Cummins Inc. | Electrolyzer systems and industrial hydrogen applications | PEM & Alkaline |
| John Cockerill | Large-scale electrolyzer manufacturing and hydrogen projects | Alkaline |
| Asahi Kasei Corporation | Industrial hydrogen production and advanced alkaline systems | Alkaline |
| Sunfire GmbH | High-efficiency hydrogen production | Solid Oxide & Alkaline |
| Bloom Energy | High-temperature electrolysis technology | Solid Oxide |
| Enapter AG | Modular electrolyzer systems | AEM |
| McPhy Energy | Electrolyzers and hydrogen production infrastructure | Alkaline & PEM |
| Ohmium International | Modular green hydrogen systems | PEM |
| Topsoe A/S | High-temperature electrolysis and industrial applications | Solid Oxide |
The competitive landscape is moving toward larger electrolyzer capacities, lower production costs, higher efficiency and stronger integration with renewable-energy systems. Established companies are using manufacturing scale and industrial project experience, while specialized technology companies are differentiating through innovations in PEM, SOEC and AEM systems. As more hydrogen projects progress from planning to commercial deployment, companies with the ability to provide complete, scalable and cost-efficient electrolysis solutions are increasingly competing for large industrial and energy-sector contracts.
Recent Developments In Water Electrolysis Market
| Date | Company / Organization | Recent Development |
| September 2026 | Nel ASA | Nel entered a framework agreement with Hydrasun to establish dedicated European assembly and integration capabilities for its modular MC Series PEM electrolyzers. The arrangement is intended to expand Nel’s delivery capabilities in Europe while its PEM stacks continue to be manufactured in the United States. |
| July 2026 | thyssenkrupp nucera & BHEL | thyssenkrupp nucera and Bharat Heavy Electricals Limited (BHEL) signed a strategic collaboration to support the phased localization of alkaline water electrolyzer module fabrication in India and jointly participate in green hydrogen project tenders. |
| July 2026 | ITM Power | ITM Power received formal approval for a £46.5 million UK government grant, alongside a £40 million investment from Great British Energy, supporting its next-generation Chronos electrolyzer manufacturing capability in Sheffield. |
| May 2026 | Nel ASA | Nel commercially launched its next-generation pressurized alkaline electrolyzer platform, developed to simplify large-scale hydrogen projects while improving cost efficiency, scalability and system performance. The platform followed more than eight years of development and full-scale prototype testing. |
| May 2026 | Siemens Energy & BASF | BASF commissioned Germany's largest green hydrogen production facility at its Ludwigshafen chemical complex, using PEM electrolysis technology supplied by Siemens Energy. The project demonstrates the application of electrolytic hydrogen directly within a major chemical production environment. |
| March 2026 | thyssenkrupp nucera & Juno Joule | thyssenkrupp nucera received a contract to conduct a 260 MW FEED study for a green hydrogen project in India. The study focuses on integrating alkaline water electrolysis into the project's infrastructure, with a potential final investment decision targeted for FY 2026/27. |
Water Electrolysis Market Research Methodology
The Water Electrolysis Market study uses a combination of primary and secondary research to assess market size, trends, growth factors, competitive activity, and regional developments. Secondary research includes information from company websites, annual reports, government publications, industry associations, energy agencies, technical studies, and other reliable industry sources, while primary research involves discussions with industry participants, manufacturers, technology providers, and other relevant stakeholders. The collected information is cross-checked and validated to identify market trends, estimate segment and regional contributions, and develop the historical and forecast market outlook. The analysis covers the period from 2020 to 2034, with 2025 as the base year and forecasts extending through 2034.
Water Electrolysis Market Scope: Inquire Before Buying
| Global Water Electrolysis Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 7.43 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 6.1% | Market Size in 2034: | USD 12.66 Bn. |
| Segments Covered: | By Technology Type | Alkaline Electrolysis PEM (Proton Exchange Membrane) Electrolysis Solid Oxide Electrolysis Anion Exchange Membrane (AEM) Electrolyzers |
|
| By Capacity | Less than 500 kW 500kW - 2 MW Above 2 MW |
||
| By Application | Power Generation and Energy Storage Transportation Industrial Feedstock Power to Gas Others |
||
| by End Use- Industry | Chemicals Industry Power Generation Oil & Gas Steel and Petroleum Transportation |
||
Water Electrolysis Market, by Region:
1. North America (United States, Canada, and Mexico)
2. Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, and the Rest of Europe)
3. Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and the Rest of APAC)
4. Middle East and Africa (South Africa, GCC, Egypt, Nigeria, and the Rest of ME&A)
5. South America (Brazil, Argentina Rest of South America)
Water Electrolysis Market, Key Players
1. Nel ASA
2. Siemens Energy AG
3. Cummins Inc.
4. ITM Power plc
5. McPhy Energy S.A.
6. Plug Power Inc.
7. Toshiba Energy Systems & Solutions Corporation
8. Enapter AG
9. Giner ELX Inc.
10. Areva H2Gen
11. Green Hydrogen Systems A/S
12. Kobelco Eco-Solutions Co., Ltd.
13. Next Hydrogen Corporation
14. ERGOSUP
15. Ceres Power Holdings plc
16. thyssenkrupp nucera AG & Co. KGaA
17. John Cockerill
18. Sunfire GmbH
19. Bloom Energy Corporation
20. Topsoe A/S
21. HydrogenPro ASA
22. Ohmium International, Inc.
23. Asahi Kasei Corporation
24. PERIC Hydrogen Technologies Co., Ltd.
25. LONGi Hydrogen Technology Co., Ltd.
26. Sungrow Hydrogen
27. Hygreen Energy
28. H-TEC SYSTEMS GmbH
29. Electric Hydrogen Co.
30. H2B2 Electrolysis Technologies S.L.
31. OxEon Energy, LLC
32. Erre Due S.p.A.
33. Hysata Pty Ltd
34. Hydrogen Optimized Inc.
35. Elogen SAS
36. H2e Power Systems Pvt. Ltd.
37. Shandong AUYAN New Energy Technology Co., Ltd.
38. Beijing SinoHy Energy Co., Ltd.
39. Horizon Fuel Cell Technologies Pte. Ltd.
40. Air Liquide S.A.
Frequently Asked Questions:
1. What are the growth drivers for the Water Electrolysis market?
Ans: The primary growth drivers for the Water Electrolysis market include Increasing focus on renewable energy sources for hydrogen production. Government initiatives and policies promoting green hydrogen. Additionally, Growing demand for clean fuels in various industries like transportation and power generation.
2. What is the major restraint for the Water Electrolysis market growth?
Ans. One significant restraint for the Water Electrolysis market growth is the high initial capital investment required for establishing electrolysis facilities, hindering widespread adoption. Additionally, limitations in grid infrastructure for accommodating renewable energy sources can pose challenges in scaling up electrolysis operations. Regulatory complexities and the need for supportive policies also impede rapid market expansion.
3. Which region is expected to lead the global Water Electrolysis market during the forecast period?
Ans. Asia-Pacific is expected to lead the global Water Electrolysis market during the forecast period.
4. What is the projected market size & and growth rate of the Water Electrolysis Market?
Ans. The Water Electrolysis Market size was valued at USD 7.43 Billion in 2025 and the total Water Electrolysis revenue is expected to grow at a CAGR of 6.1% from 2026 to 2034, reaching USD 12.66 Billion by 2034.
5. What segments are covered in the Water Electrolysis Market report?
Ans. The segments covered in the Water Electrolysis market report are Technology Type, end user, and Region.