
Medical Robotics Market – Global Market Size, Strategic Growth Drivers, Risk Assessment Framework, Regulatory Landscape Review, Competitive Intensity Mapping & Long-Term Industry Outlook to 2034
Overview
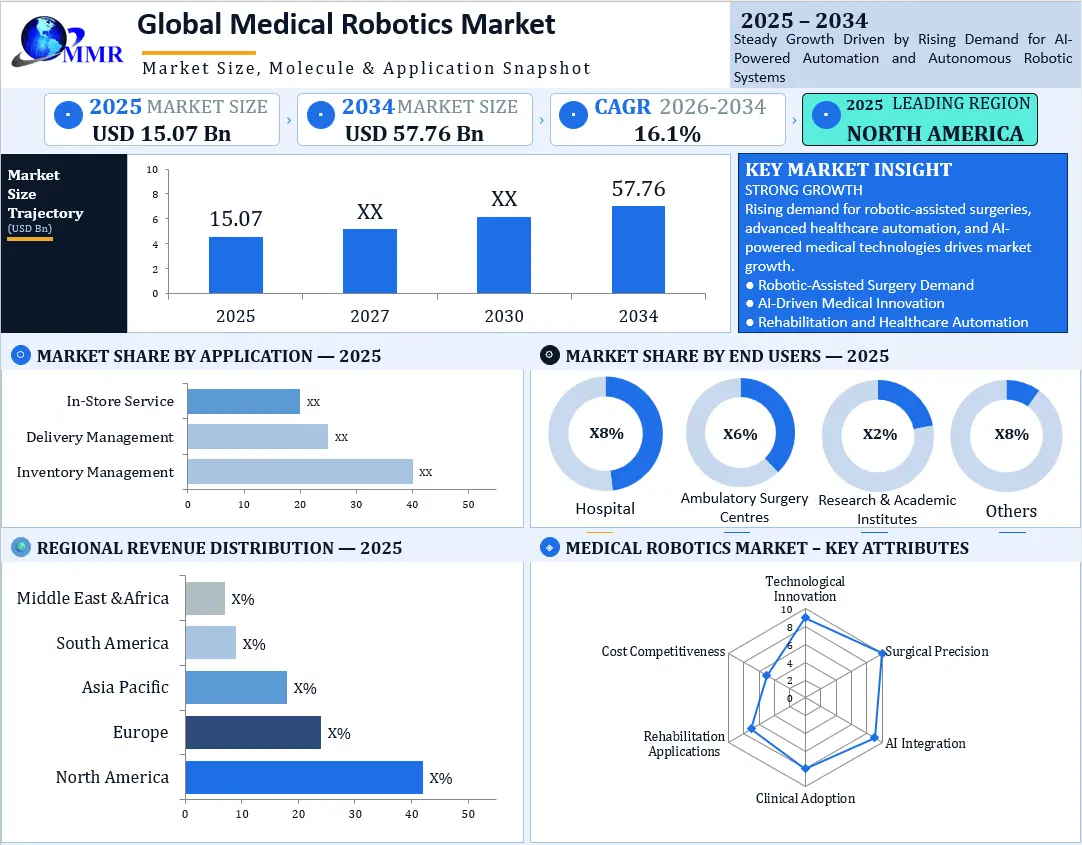
The Global Medical Robotics Market was valued at USD 15.07 Billion in 2025 and is projected to reach USD 57.76 Billion by 2034, growing at a CAGR of 16.1% during the forecast period (2026–2034).
Medical Robotics Market Overview
The Medical Robotics Market is expanding as healthcare providers increasingly adopt advanced technologies to improve surgical precision, treatment accuracy, patient safety, and operational efficiency. Medical robotics includes surgical robots, rehabilitation robots, hospital automation systems, robotic exoskeletons, and pharmacy automation solutions. These technologies assist healthcare professionals in performing complex procedures, supporting patient recovery, automating repetitive tasks, and improving clinical workflows.
Surgical robotics represents a major application area, enabling minimally invasive procedures, enhanced visualization, improved instrument control, and greater precision. Rehabilitation robotics supports patients recovering from neurological conditions, injuries, and mobility impairments through robotic-assisted therapy and personalized rehabilitation programs. Meanwhile, hospital and pharmacy robotics help automate medication dispensing, laboratory processes, material handling, and other routine healthcare operations.
The adoption of medical robotics is driven by rising demand for minimally invasive surgeries, increasing healthcare expenditure, an aging population, growing cases of chronic diseases, and continuous advancements in artificial intelligence, machine vision, sensors, and robotic control systems. Integration with digital healthcare platforms and data analytics further improves procedure planning, workflow management, and patient monitoring.
However, high installation and maintenance costs, complex regulatory requirements, cybersecurity concerns, and the need for specialized training can limit adoption, particularly in smaller hospitals and developing healthcare markets. Despite these challenges, ongoing technological innovation, expanding healthcare infrastructure, and increasing demand for efficient patient care create significant growth opportunities for the Global Medical Robotics Market.
Global Medical Robotics Market Growth Outlook
 To know about the Research Methodology :- Request Free Sample Report
Medical Robotics Market Scope and Research Methodology
The report highlights the competitive market view, segment analysis based on the Product, Application and geographical area. First, the market overview describes the market trends, key market drivers, market restraints, opportunities, and challenges for the Medical Robotics industry.
The Market is segmented by the product such as Surgical Robots, Telepresence Robots, Rehabilitation Robots and Others like pharmacy automation robots. It is also segmented by application including Neurosurgery, Laparoscopy, Orthopaedic Surgery, Cardiology and Pharmaceutical applications. The market size and trends for the Medical Robotics market were analysed by using both primary and secondary data. Top down approach is used to estimate market size of the Medical Robotics Market.
Market projections were based on historical data, present sector developments, and future market opportunities and challenges. The SWOT analysis of the major market players, which included their strengths, weaknesses, opportunities, and threats, was also included in the research to provide a thorough knowledge of the market dynamics. By employing the PESTLE analysis, the operating environment of an organization can be assessed. Porter's analysis were used to identify crucial factors that directly affect market profitability.
Global Medical Robotics Market Dynamics
Market Drivers
Increasing demand for precision and minimally invasive procedures drives market growth: Healthcare providers increasingly adopt medical robots to support surgical precision, improve visualisation, and perform complex procedures through minimally invasive techniques. Robotic-assisted systems help surgeons control instruments with greater accuracy while maintaining direct clinical control. According to the International Federation of Robotics (IFR), 8,400 surgical robots are sold globally in 2025, representing 57% growth. This expansion strengthens demand for surgical robotics, advanced medical equipment, and robotic technologies across hospitals and specialised healthcare facilities.
Growing need for healthcare automation accelerates adoption: Hospitals and healthcare facilities increasingly deploy medical robots to support surgery, rehabilitation, patient assistance, and repetitive clinical tasks. These systems help healthcare professionals manage workloads, improve operational efficiency, and support consistent care delivery. IFR reports that medical robot sales grow by 19% in 2025, reflecting increasing adoption of robotics across healthcare applications. Rising demand for healthcare services, workforce constraints, and the need to improve clinical productivity support further market expansion.
Market Opportunities
Integration of robotics with artificial intelligence and digital health creates opportunities: The integration of medical robotics with AI, connected medical devices, digital health platforms, and clinical data systems creates opportunities for more personalised and efficient care. AI-enabled robotics supports surgical planning, image-guided procedures, rehabilitation monitoring, and data-assisted clinical workflows. Healthcare providers increasingly explore connected robotic solutions that improve information sharing and support coordinated patient care, creating opportunities for manufacturers offering interoperable hardware and software platforms.
Expansion of robotic surgery and rehabilitation creates new growth avenues: Healthcare facilities increasingly invest in robotic-assisted surgery and rehabilitation technologies to support complex procedures and structured recovery programmes. Surgical robotics helps clinicians perform selected procedures with enhanced instrument control, while rehabilitation robots support repetitive, guided movement and therapy. Intuitive Surgical reports USD 10.1 billion in revenue in 2025, an increase of 21%, reflecting strong commercial activity in the robotic-assisted surgery segment. These developments create opportunities for robotic system manufacturers, medical device suppliers, and healthcare technology providers.
Market Restraints and Challenges
High acquisition and maintenance costs restrict adoption: Medical robotics systems require substantial capital investment, specialised installation, regular maintenance, and software upgrades. Healthcare providers also invest in compatible operating facilities, technical support, and staff training. These costs create barriers for smaller hospitals and healthcare facilities with limited budgets, particularly in developing markets. Financing requirements and uncertainty around the return-on-investment influence procurement decisions and can slow the adoption of advanced robotic platforms.
Complex integration, training, and regulatory requirements challenge deployment: Medical robotics systems require clinical validation, regulatory clearance, and integration with existing hospital infrastructure and workflows. Healthcare professionals need specialised training to operate robotic platforms safely and effectively. Concerns regarding cybersecurity, patient data protection, system reliability, and interoperability also influence adoption. Manufacturers must demonstrate device safety and performance while supporting healthcare providers with training, maintenance, and technical assistance, increasing deployment complexity and operating costs.
Medical Robotics Market Segment Analysis
Based on type, the Medical Robotics market is segmented into surgical robots, rehabilitation robots, pharmacy & disinfection robots, diagnostic robots, and others. Surgical robots dominated the market in 2025 due to their ability to perform minimally invasive procedures with high precision, reduced recovery time, and improved patient outcomes. Rehabilitation robots are increasingly used in physiotherapy and post-operative recovery, enhancing patient mobility and treatment efficiency. Pharmacy & disinfection robots are gaining traction in hospitals and clinics to automate repetitive tasks and maintain hygiene standards. Diagnostic robots are emerging in imaging and laboratory applications to enhance accuracy and reduce human error.
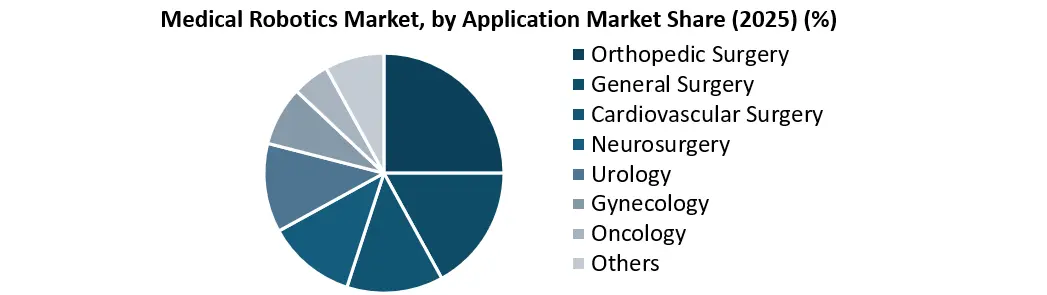
Based on application, the Medical Robotics market is segmented into orthopedic surgery, cardiovascular surgery, neurosurgery, general surgery, urology, gynecology, oncology, and others. Orthopedic surgeries account for a large portion of robotic deployments due to the complexity and precision required in these procedures. Neurosurgery is a growing segment, with robots assisting in high-precision brain and spinal operations. General surgery, urology, gynecology, and oncology also see increased adoption for minimally invasive procedures. The other segment includes emerging applications such as ENT surgeries and pediatric surgeries. Overall, application-driven demand is influenced by rising surgical volumes, aging populations, and increasing adoption of minimally invasive techniques.
Medical Robotics Market Regional Insights
North America leads the global medical robotics market, supported by advanced healthcare infrastructure, high healthcare expenditure, and the widespread adoption of robotic-assisted surgery. The region benefits from increasing demand for minimally invasive procedures, rising volumes of hip and knee replacement surgeries, and the growing prevalence of chronic and lifestyle-related diseases. Hospitals and specialised healthcare centres increasingly adopt surgical robots, rehabilitation robots, robotic imaging systems, and automated medical technologies to improve procedural precision, workflow efficiency, and patient care.
The presence of major medical robotics companies, including Intuitive Surgical, Stryker Corporation, and Zimmer Biomet Holdings, strengthens regional innovation through the development of advanced robotic-assisted surgical systems, orthopaedic robotics, and image-guided technologies. The United States represents a major contributor to the North American medical robotics market due to its established healthcare facilities, favourable investment environment, and increasing integration of robotics with artificial intelligence (AI), machine learning, and digital healthcare systems. Canada also supports regional growth through healthcare modernisation and the adoption of advanced medical technologies. Continued investment in surgical robotics, hospital automation, and precision medicine strengthens North America's leading position in the global medical robotics market.
Asia-Pacific represents a significant and rapidly expanding region in the global medical robotics market, driven by healthcare infrastructure development, a large patient population, rising healthcare expenditure, and increasing demand for advanced surgical procedures. China, Japan, India, and South Korea contribute to regional growth through investments in medical technology, robotics research, and healthcare modernisation. Japan benefits from its established robotics industry and growing demand for technologies that support an ageing population, including rehabilitation robots, assistive robots, and robotic surgical systems. China expands domestic medical robotics manufacturing and hospital adoption, while India creates growth opportunities through the expansion of private hospitals, multispecialty healthcare centres, and demand for minimally invasive surgery. Government initiatives, private-sector funding, and collaborations between hospitals, universities, and medical technology companies support the development of locally manufactured robotic systems. The integration of AI-enabled surgical robotics, medical imaging, rehabilitation technology, and automated hospital solutions further strengthens the Asia-Pacific medical robotics market.
Europe maintains a strong position in the global medical robotics market through advanced healthcare systems, established medical device manufacturers, and growing adoption of robotic-assisted procedures. Countries such as Germany, the United Kingdom, France, Italy, and Switzerland contribute to regional demand through investments in surgical innovation, orthopaedic robotics, rehabilitation systems, and healthcare automation. Germany benefits from its strong medical engineering and manufacturing base, while the United Kingdom and France support adoption through specialised hospitals, clinical research, and healthcare technology programmes. European healthcare providers increasingly use robotic-assisted surgery for selected urological, gynaecological, general, and orthopaedic procedures. The region also creates opportunities for rehabilitation robotics, assistive technologies, and robotic systems that support elderly care. Research collaborations, medical device innovation, and the integration of robotics with digital health platforms contribute to market development. Regulatory compliance, clinical safety requirements, and evidence-based procurement remain important considerations for medical robotics manufacturers operating across Europe.
The South America medical robotics market is developing as healthcare providers invest in advanced medical technologies, modernise hospital infrastructure, and expand access to specialised surgical procedures. Brazil and Argentina represent important markets, supported by established private healthcare networks, growing demand for minimally invasive surgery, and increasing investment in medical equipment. Brazil contributes to regional market development through its large patient population, major hospital networks, and adoption of robotic-assisted surgical systems. Argentina and Chile also create opportunities through investments in specialised healthcare services and advanced treatment technologies. Hospitals increasingly explore surgical robotics, orthopaedic robotics, rehabilitation robots, and AI-enabled medical technologies to improve procedural precision, support recovery, and enhance clinical efficiency. Collaborations with international medical device manufacturers and specialised training programmes help healthcare professionals adopt robotic systems. However, high acquisition and maintenance costs, limited reimbursement, unequal access to advanced healthcare infrastructure, and shortages of trained professionals constrain wider adoption. Continued investment in private hospitals, healthcare modernisation, and minimally invasive procedures supports future growth opportunities in the South America medical robotics market.
The Middle East & Africa medical robotics market develops as healthcare providers invest in modern hospitals, specialised treatment centres, and advanced medical technologies. Countries such as Saudi Arabia, the United Arab Emirates, and Israel support regional adoption through healthcare transformation programmes, private-sector investment, and the development of specialised surgical services. Hospitals in the Gulf region increasingly explore robotic-assisted surgery, advanced imaging, and automation to strengthen clinical capabilities and support medical tourism. Israel contributes through its medical technology innovation ecosystem, including robotics, digital health, and AI-enabled medical solutions. In Africa, adoption remains concentrated in selected hospitals and larger urban healthcare centres, where access to funding, specialist training, and technical support influences deployment. High capital expenditure, limited infrastructure in some areas, and shortages of trained personnel continue to challenge widespread adoption. Ongoing healthcare investment, international partnerships, and the expansion of specialised medical facilities support future opportunities for surgical robotics, rehabilitation robotics, and hospital automation across the region.
Global Medical Robotics Market – Competitive Landscape
The global medical robotics market features competition among established medical technology companies and specialised robotics manufacturers across North America, Europe, and Asia-Pacific. North America remains a major competitive hub, with US-based companies such as Intuitive Surgical, Stryker Corporation, Zimmer Biomet, Globus Medical, and PROCEPT BioRobotics focusing on robotic-assisted surgery, orthopaedic procedures, and surgical navigation. Medtronic, headquartered in Ireland, competes in robotic-assisted surgery and image-guided technologies, while Johnson & Johnson MedTech, based in the United States, expands its surgical robotics portfolio. Europe contributes through companies such as CMR Surgical in the United Kingdom, Smith+Nephew in the United Kingdom, Siemens Healthineers in Germany, Brainlab in Germany, and Distalmotion in Switzerland, which develop surgical systems, orthopaedic robotics, and image-guided solutions. Asia-Pacific strengthens its position through manufacturers such as MicroPort MedBot in China, Medicaroid in Japan, and SS Innovations in India, which expand robotic-assisted surgical technology and seek wider adoption across domestic and international healthcare markets.
Companies differentiate themselves through research and development, product launches, clinical validation, strategic partnerships, and expansion into new geographic markets. Intuitive Surgical strengthens its position in soft-tissue surgery through its da Vinci platform, while Stryker and Zimmer Biomet compete in orthopaedic robotics. CMR Surgical targets flexible robotic-assisted surgery with its Versius platform, and MicroPort MedBot and SS Innovations broaden competition through surgical robotics designed for different healthcare settings and market requirements. In rehabilitation robotics, companies such as CYBERDYNE in Japan and Wandercraft in France focus on robotic exoskeletons and mobility support. Meanwhile, Accuray in the United States and Elekta in Sweden compete in precision radiation-treatment technologies.
The competitive landscape also includes hospital automation providers such as Omnicell in the United States, ARxIUM in North America, and Swisslog Healthcare, which supply automated solutions for medication management, pharmacy operations, and healthcare logistics. Competition increasingly centres on improving procedural accuracy, integrating artificial intelligence and medical imaging, reducing system complexity, and strengthening clinician training and technical support. High capital investment, regulatory requirements, and the need for clinical evidence remain significant barriers to entry. As healthcare providers expand the adoption of robotic-assisted procedures and automated clinical workflows, established manufacturers and specialised regional players continue to compete through technological innovation, product differentiation, and international expansion.
Recent Developments in the Global Medical Robotics Market
| Date | Company/ Organisation | Development | Impact |
| October 2026 | Stryker and CMR Surgical | Announced a strategic alliance involving investment in CMR Surgical and US sales rights for its Versius surgical robotics portfolio. | Strengthens competition in robotic-assisted surgery and expands access to flexible surgical robotics in the US market. |
| September 2026 | Medtronic and Cornerstone Robotics | Announced a strategic partnership covering distribution of Cornerstone's Sentire surgical system in selected international markets. | Expands Medtronic's robotic surgery reach and increases competition in international markets. |
| July 2026 | MicroPort MedBot | Reported expected first-half profitability and demonstrated cross-continental telesurgery using its Toumai surgical robotic system. | Strengthens confidence in surgical robotics commercialisation and highlights the potential of remote robotic procedures. |
| June 2026 | Microbot Medical Inc. | Entered a manufacturing agreement with Sanmina to expand production capacity for its LIBERTY endovascular robotic system. | Supports manufacturing scale-up, product availability, and potential expansion into additional markets. |
| April 2026 | CMR Surgical | Submitted a US FDA 510(k) application to expand the clinical indications for its Versius Plus surgical robotic system to gynaecological procedures. | Creates potential for broader clinical use, subject to regulatory clearance, and increases competition across surgical specialties. |
Scope Of Medical Robotics Market : Inquire Before Buying
| Medical Robotics Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 15.07 USD Billion |
| Forecast Period 2026-2034 CAGR: | 16.1% | Market Size in 2034: | 57.76 USD Billion |
| Segments Covered: | by Type | Surgical Robots Rehabilitation Robots Pharmacy & Disinfection Robots Diagnostic Robots Others |
|
| by Application | Application Orthopedic Surgery Cardiovascular Surgery Neurosurgery General Surgery Urology Gynecology Oncology Others |
||
| by End User | Hospitals Ambulatory Surgery Centers Research & Academic Institutes Others |
||
Medical Robotics Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Key Players/Competitors Profiles Covered in Brief Medical Robotics Market Report in Strategic Perspective
1. Intuitive Surgical, Inc.
2. Stryker Corporation
3. Medtronic plc
4. Zimmer Biomet Holdings, Inc.
5. Smith+Nephew plc
6. Johnson & Johnson MedTech
7. Siemens Healthineers AG
8. Omnicell, Inc.
9. Accuray Incorporated
10. ARxIUM
11. Renishaw plc
12. CMR Surgical Ltd.
13. Becton, Dickinson and Company
14. Hocoma AG
15. CYBERDYNE Inc.
16. Blue Ocean Robotics
17. Stereotaxis, Inc.
18. Globus Medical, Inc.
19. THINK Surgical, Inc.
20. Microbot Medical Inc.
21. PROCEPT BioRobotics Corporation
22. Brainlab AG
23. Elekta AB
24. GE HealthCare Technologies Inc.
25. Koninklijke Philips N.V.
26. ABB Ltd.
27. Yaskawa Electric Corporation
28. FANUC Corporation
29. KUKA AG
30. Aethon, Inc.
31. Swisslog Healthcare
32. Ekso Bionics Holdings, Inc.
33. Lifeward Ltd.
34. Fourier Intelligence
35. Wandercraft
36. Rehab-Robotics Company Limited
37. Distalmotion SA
38. SS Innovations International, Inc.
39. Medicaroid Corporation
40. Meerecompany Co., Ltd.
Medical Robotics Market FAQs
1. What is the global medical robotics market?
Ans. The global medical robotics market includes robotic systems used in surgery, rehabilitation, diagnostics, pharmacy automation, and other healthcare applications to improve precision, efficiency, and patient care.
2. What are the key factors driving the medical robotics market?
Ans. The market is driven by increasing demand for minimally invasive procedures, rising surgical volumes, technological advancements in artificial intelligence, an ageing population, and growing adoption of robotic-assisted surgery.
3. Which segment dominates the medical robotics market?
Ans. Surgical robots represent a major segment of the medical robotics market due to their use in complex procedures, minimally invasive surgery, and precision-assisted treatments.
4. Which region dominates the global medical robotics market?
Ans. North America leads the global medical robotics market, supported by advanced healthcare infrastructure, high healthcare expenditure, strong research and development investment, and widespread adoption of robotic-assisted procedures.
5. Who are the key players in the medical robotics market?
Ans. Key players include Intuitive Surgical, Inc., Stryker Corporation, Medtronic plc, Zimmer Biomet Holdings, Inc., Johnson & Johnson MedTech, CMR Surgical, Siemens Healthineers AG, and Globus Medical, Inc.