Sulfur Market Size, Opportunities by Product, End Use Industry, Application, Sales Channel and Demand, Supply by Region with Competitive Landscape and Pricing

4%
CAGR (2026-2034)
6.56 USD Bn.
Forecast Market Size
314
Report Pages
139
Market Tables

Overview

The Sulfur Market size was valued at USD 6.56 Billion in 2025 and the total Sulfur revenue is expected to grow at a CAGR of 4% from 2025 to 2034, reaching USD 9.34 Billion by 2034.

Sulfur Market Overview:

Sulfur occurs naturally as an element in its purest form as well as in the form of sulphate or sulphide minerals. Mineral collectors can distinguish sulphur crystals from other crystal types thanks to their distinctive and vividly coloured polyhedron shapes. Sulfur was once mostly mined from salt domes, where it naturally occurs in pure form, but new technologies have rendered this approach obsolete.

Global Sulfur Market Size, Share and Growth Analysis
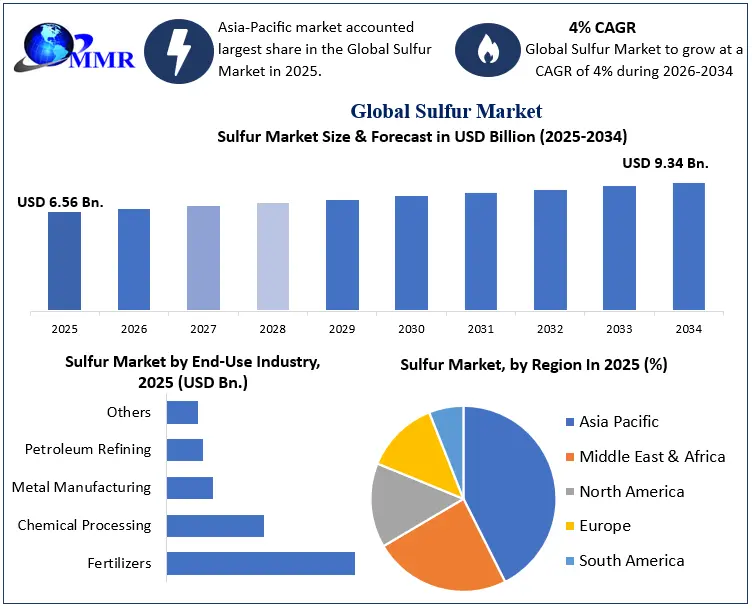
Sulfur Market Growth

To know about the Research Methodology :- Request Free Sample Report

Sulfur is one of the most important raw materials used in the chemical industry. It is mostly used as a derivative (in acid form) in a variety of industrial and chemical processes, and its single largest end use is the manufacturing of phosphate fertilizers requires a significant amount of it. The processing of rubber, cosmetics, and pharmaceutical applications are significant application areas. Owing to its importance to industrial economies and relative ease of transportation, it is a commodity of great interest.

It is a by-product of several processes, including petroleum refining, tar sands recovery, heavy oil and natural gas processing, coking and metallurgical operations. By using the Frasch method of traditional mining, elemental sulphur is extracted from the ores. It is acquired as a byproduct of the refining of sour crude, tar sand, and sour natural gas. 98.5% of the world's production of elemental sulphur comes from sulphur recovered during refining procedures.

Sulfur Market Report scope:

The study seeks to provide market players with a full understanding of the sulfur market. The research looks at market developments from the past, the present, and what is expected for the future. Additionally, it offers a clear interpretation of complicated data. New entrants, market leaders, and followers are a few of the important actors who actively and completely conduct research. The analysis also presents the findings of the PORTER and PESTEL analyses in addition to potential outcomes of the microeconomic components of the market. Once internal and external aspects that have a good or negative impact on the organisation have been taken into account, decision-makers will have a clear futuristic perspective of the market.

Investors are able understand the dynamics and structure of the sulphur market with the market segmentation analysis and market size projection from the study. By clearly laying out the comparative study of the top sulfur companies by price, financial status, product, product portfolio, growth plan, and geographic presence, the research acts as a buyer's guide.

Sulfur Market Research Methodology:

MMR began by gathering information on the revenues of the top suppliers in order to estimate and project the Sulfur market. In an effort to segment the market, providers' offers are taken into account by Product (Pharmaceutical Grade, Industrial Grade), By End Use Industry, and ( Fertilizers, Chemical Processing, Metal Manufacturing, Petroleum Refining, Others). After conducting primary research to confirm these divisions, extensive interviews with prominent individuals, including chief executive officers (CEOs), vice presidents (VPs), directors, and executives, were done.

The market's size is projected using bottom-up techniques. Primary and secondary research are used to identify the leading market participants in the sulphur market and determine their market revenues. Instead of conducting secondary research, the major manufacturers' annual and financial reports were analysed, and important opinion and business leaders in the industry, such as CEOs and marketing executives, were spoken with. In the global sulphur market, Nutrien, Ltd., Yara International ASA, The Mosaic Company, K+S, ICL, EuroChem Group and Nufarm Limited are the leading rivals. To enhance their market shares and growth potential, they will keep planning mergers and acquisitions over the course of the forecast year.

Sulfur Market Dynamics:

Market Drivers:

The market is growing as a result of increased fertiliser demand. Plants utilise a sizable amount of nitrogen, phosphorus, potassium, sulphur, calcium and magnesium. Nutrients are lost from the environment for a variety of reasons, including crop removal, erosion, leaching, soil fixation, and others. When creating critical proteins, lipids, and amino acids in the early stages of development, this is particularly crucial. Its most major contribution to crop production is the creation of protein molecules and amino acids, which are necessary for the development of chlorophyll, lignin, and pectin. This is accomplished by supporting photosynthesis, which is how plants turn solar energy into chemical energy. The production of agricultural fertiliser uses around 55% of all recovered product produced globally.

In addition to being a sizable industry, the fertiliser market also contributes significantly to global food production. This level of productivity would not be possible without intensive agriculture and the usage of fertilisers. Grain production is the primary end-use market for fertilisers, followed by cash crops like vegetables, fruit, flowers, and vines. Economic and population growth are the main factors driving an increase in fertiliser use. Production must maintain pace with consumption's ongoing growth. The demand for the sulfur market is expected to increase in the forecast years, owing to the increasing population.

Eventually, food prices must be high enough to encourage spending and production growth. The generation of H2 SO4, which is largely used to create fertiliser, is one of the many industrial uses for elemental sulphur. The demand for phosphorus (P20s) fertiliser was forecast to be 47,403 thousand tonnes in 2020, and it is expected to increase to 49,097 thousand tonnes in 2021, according to the world fertiliser outlook.

Market Restraints:

Market growth is being hampered by negative exposure reactions. SO is an air pollution-causing sulfur-oxygen gas. Burning fuels like coal, oil, or diesel releases SO2 into the atmosphere. The US Environmental Protection Agency estimates that around 6.5 million tonnes of SO were released into the atmosphere in the US from man-made sources. The main sources of SO2 emissions are industrial boilers, electricity generation, and other industrial processes including metal processing and petroleum refining. Important sources of diesel engines include old buses and cars, locomotives, ships, and off-road diesel machinery. The majority of SO2 exposure occurs among those who reside and work close to these significant sources.

The conversion of SO2 into sulphate particles, which travels hundreds of miles, occurs when it is released into the atmosphere. High-level exposure that is sustained worsens respiratory symptoms and impairs lung function. During exercise, fast breathing and lip breathing both help SO2 enter the lower respiratory tract. The market growth is expected to be hampered owing to this factors.

Market Opportunities:

Chemical processing is driving up demand. The largest market among end-user industries is expected to be chemical processing, which in 2021 accounted for around 90% of the world's sulphur market. Sulfur dioxide is created by using around 90% of the sulphur that is produced or extracted and is then transformed into sulfuric acid. The majority of the acid is employed in the manufacture of phosphate fertilisers, a vital part of the food and beverage sector.

Demand for sulphuric acid is rising on the international market as agricultural output rises. By 2026, it is expected that the average daily calorie availability in the least developed countries will be 2,455 kcal and will exceed 3,050 kcal in other developing nations. On the global market, this is expected to raise demand for agricultural products, increased demand for phosphate fertilisers, growing demand for sulphur in chemical production.Fertilizer demand has increased as a result of rising crop prices. The demand for fertilisers has also increased as a result of the favourable weather in the key agricultural regions. The sulphur market is expected to grow throughout the forecast period as a result of these favourable aspects.

Sulfur Market Segment Analysis:

Based on Product, The Pharmaceutical Grade segment is expected to grow at the highest CAGR during the forecast period. The solutions from Pharmaceutical grade are the result of more than 30 years of research and development aimed at understanding and harnessing the potential of the biological fraction of the soil to improve soil health and increase crop quality and yield.

Blends provide better soil health, more fertility, and higher yields by combining naturally occurring microorganisms with organic acids and nutrients. Pharmaceutical grade respects the delicate processes and balance of nature. Additionally Sulfur is used in the pharmaceutical sector to manufacture medications. The development of sulphur medicines had a huge influence on the growth of the pharmaceutical business. Many medications and organic items contain functional groups that are made from sulphur. Sulfonamides, thioethers, sulfones, and penicillin are the most often used scaffolds in pharmaceuticals containing sulphur.

Sulfur Market by Product

Based on End Use Industry, The Fertilizers segment is expected to grow at the highest CAGR during the forecast period. More than 55% of the market accounted by the fertilisers category. About 92–95 % of the collected elemental sulphur is used to create sulfuric acid. Thanks to fertilisers and derivatives of ammonium phosphate, this nutrient has gained in popularity recently. For around half of the world's output, fertilisers are the intended use. Around 88% of all fertilisers are made with phosphate, and a sizeable amount of ammonium sulphate is also produced. As a result, this industry is very dependent on the cyclical global phosphate fertiliser market.

The product is used in agriculture as a plant nutrient and also as a step in the production of phosphoric acid, which results in the production of phosphate fertilisers. H2S04, the most widely used inorganic chemical on the globe, is produced from almost all elements and is employed in a wide range of industrial, metallurgical, and agricultural processes.

Sulfur Market Regional Insights:

In 2025, the Asia-Pacific region dominated the global sulphur market. Owing to the rising demand for sulphur in fertiliser production and rubber processing from nations like China and India, the Asia-Pacific region led the market. The largest producer of sulphur internationally is China. The majority of the world's pyrites, or sulphur in all its forms, are produced in China (source). With 36% of all global imports coming from this nation, it is the top importer of sulphur, which is mostly used to make sulfuric acid.

Owing to its increasing concerns over its energy security, China is speeding up its oil and gas exploration efforts. At the moment, the nation imports 72% of the crude oil it refines. As a result, the nation is encouraging private and foreign enterprises to carry out oil and gas exploration and production in the area. Approximately two thirds of the sulfuric acid used in China is utilised in the manufacturing of fertilisers. Calcium, magnesium, and sulphur are examples of secondary fertilisers in the fertiliser sector. Yara China Limited and Nutrien Ltd are two businesses that sell secondary fertilizer-related products.

Additionally, nearly 95.05% of the demand for fertilisers in ASEAN is met by sugarcane, rubber, and oil palm. In the forecast years, plantations are expected to be the primary factor in the growth of the fertiliser business, which then influence the sulphur market.Natural rubber produced at plantations in Malaysia, Thailand, and Indonesia accounts for around one-third of all rubber use worldwide. One of the world's biggest producers and exporters of natural rubber is Thailand.

The aforementioned elements have a part in the region's rising demand for sulphur consumption.

The increased demand for the acid from end-use sectors, such as the chemical, pharmaceutical, and metal extraction industries, cause North America to experience significant growth. Mining activity growth supports market growth. The main use in metal extraction and purification processes is expected to see strong demand.

By the end of the forecast period, Europe is expected to have experienced tremendous growth. The main element affecting growth in the region is the high demand from end-use industries. Chemicals have a large consumer base, which is driving the demand for the product.

Sulfur Market Recent Industry Developments (2025–2026)

Date Company Development Impact
25 June 2026 Valgotech LLC Announced a new battery production facility in Noblesville, Indiana, focused on domestic manufacturing of advanced sulfur-based batteries, with an estimated production capacity of 0.5 MWh to 1 MWh. Supports the development of sulfur-based energy storage for drones, aerospace and industrial applications while expanding U.S. sulfur battery manufacturing.
22 June 2026 Global Sulfur Market Supply chains remained tight as disruptions around the Strait of Hormuz affected sulfur shipments. S&P Global reported that the waterway accounts for about 50% of global seaborne sulfur exports. Limited physical availability and disrupted logistics kept sulfur prices elevated and increased supply uncertainty for fertilizer and chemical producers.
18 May 2026 Numaligarh Refinery Ltd. Signed a commercial agreement with Progressive Fertichem Pvt. Ltd. for the annual sale of 52,500 metric tons of sulfur following its refinery expansion. Provides a long-term outlet for additional sulfur production and strengthens domestic sulfur supply for India's fertilizer industry.
March 2026 Madhya Bharat Agro Products Ltd. Commissioned a 165,000 metric tons/year sulfuric acid capacity at its Sagar facility along with a 90,000-tonne fertilizer expansion. Strengthens backward integration and improves the company's ability to secure sulfuric acid requirements for fertilizer manufacturing.
17 February 2026 Amarak Chemicals FZC Started operations at a fully automated 60,000-tonne/year sulfur facility at Jebel Ali Free Zone, Dubai, producing sulfur bentonite and other sulfur-based products. Expands regional production of sulfur fertilizers and improves supply availability for agricultural markets across international markets.
18 February 2026 SulphoTech Launched a new granular fertilizer production line for sulfur-containing fertilizers, increasing its production capability. Supports higher production of sulfur-based fertilizers and strengthens the company's ability to serve agricultural demand.
28 January 2026 Madhya Bharat Agro Products Ltd. Approved a major Dhule expansion including a 396,000-tonne/year sulfuric acid plant, alongside phosphoric acid and DAP/NPK fertilizer capacity. Strengthens vertical integration in fertilizer production and is expected to reduce dependence on externally sourced sulfuric acid inputs.

Sulfur Market Scope: Inquire before buying

Global Sulfur Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 6.56 Bn.
Forecast Period 2026 to 2034 CAGR: 4% Market Size in 2034: USD 9.34 Bn.
Segments Covered: by Product Pharmaceutical Grade
Industrial Grade
by End Use Industry Fertilizers
Chemical Processing
Metal Manufacturing
Petroleum Refining
Others
by Application Sulfuric Acid Synthesis
Sulphonate Surfactants Synthesis
Agrochemicals
Metal Extraction
Oil Refining
Others
by Sales Channel Direct Sale
Indirect Sale

Sulfur Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)

Sulfur Market, Key Players

North America
1. Nutrien Ltd.
2. The Mosaic Company
3. Koch Industries, Inc.
4. Compass Minerals
5. Kemin Industries
6. Tiger-Sul Products LLC
7. Suncor Energy Inc.
8. H.J. Baker & Bro., LLC
9. Marathon Petroleum Corporation
10. Valero Energy Corporation
11. Chevron Corporation
12. Freeport-McMoRan Inc.
13. Gulf Chemical & Metallurgical Corporation
14. Chemtrade Logistics Inc.
15. Motiva Enterprises LLC

Europe
16. K+S AG
17. EuroChem Group AG
18. Tessenderlo Group
19. Gazprom
20. Shell plc
21. ExxonMobil Corporation
22. TotalEnergies SE
23. BASF SE
24. OCI Global
25. Yara International ASA
26. Acron Group
27. PhosAgro
28. Uralchem Group
29. Treibacher Industrie AG
30. Grupa Azoty

Asia-Pacific
31. China Petroleum & Chemical Corporation (Sinopec)
32. China National Petroleum Corporation (CNPC)
33. PetroChina Company Limited
34. Indian Oil Corporation Limited (IOCL)
35. Hindustan Petroleum Corporation Limited (HPCL)
36. Bharat Petroleum Corporation Limited (BPCL)
37. Coromandel International Limited
38. Deepak Fertilisers & Petrochemicals Corporation Limited
39. Sulphur Mills Limited
40. Zuari Agro Chemicals Limited
41. Nufarm Limited
42. China Sunsine Chemical Holdings Ltd.

Middle East & Africa
43. Saudi Arabian Oil Company (Aramco)
44. Abu Dhabi National Oil Company (ADNOC)
45. QatarEnergy
46. Kuwait Petroleum Corporation (KPC)
47. Ma'aden
48. ICL Group Ltd.

South America
49. Petróleo Brasileiro S.A. (Petrobras)
50. Vale S.A.

Frequently Asked Questions:

1. Which is the potential market for the Sulfur in terms of the region?
Ans. In Asia Pacific region, the growing business and educational sectors are expected to help drive the use of collaborative screens.

2. What are the opportunities for new market entrants?
Ans. The key opportunity in the market is new initiatives from governments that provide funding for Sulfurs in educational institutes

3. What is expected to drive the growth of the Sulfur Market in the forecast period?
Ans. A major driver in the Sulfur Market is the prevalence of work from home and remote collaboration created by the COVID-19 pandemic

4. What is the projected market size & growth rate of the Sulfur Market?
Ans. The Sulfur Market size was valued at USD 6.56 Billion in 2025 and the total Sulfur revenue is expected to grow at a CAGR of 4% from 2026 to 2034, reaching nearly USD 9.34 Billion by 2034.

5. What segments are covered in the Sulfur Market report?
Ans. The segments covered are by Product, by End Use Industry, Application, Sales Channel, and, Region.

Table of Contents

1. Sulfur Market Introduction 1.1. Study Assumption and Market Definition 1.2. Scope of the Study 1.3. Executive Summary 2. Sulfur Market: Dynamics 2.1. Sulfur Market Trends by Region 2.1.1. North America Sulfur Market Trends 2.1.2. Europe Sulfur Market Trends 2.1.3. Asia Pacific Sulfur Market Trends 2.1.4. Middle East and Africa Sulfur Market Trends 2.1.5. South America Sulfur Market Trends 2.2. Sulfur Market Dynamics by Region 2.2.1. North America 2.2.1.1. North America Sulfur Market Drivers 2.2.1.2. North America Sulfur Market Restraints 2.2.1.3. North America Sulfur Market Opportunities 2.2.1.4. North America Sulfur Market Challenges 2.2.2. Europe 2.2.2.1. Europe Sulfur Market Drivers 2.2.2.2. Europe Sulfur Market Restraints 2.2.2.3. Europe Sulfur Market Opportunities 2.2.2.4. Europe Sulfur Market Challenges 2.2.3. Asia Pacific 2.2.3.1. Asia Pacific Sulfur Market Drivers 2.2.3.2. Asia Pacific Sulfur Market Restraints 2.2.3.3. Asia Pacific Sulfur Market Opportunities 2.2.3.4. Asia Pacific Sulfur Market Challenges 2.2.4. Middle East and Africa 2.2.4.1. Middle East and Africa Sulfur Market Drivers 2.2.4.2. Middle East and Africa Sulfur Market Restraints 2.2.4.3. Middle East and Africa Sulfur Market Opportunities 2.2.4.4. Middle East and Africa Sulfur Market Challenges 2.2.5. South America 2.2.5.1. South America Sulfur Market Drivers 2.2.5.2. South America Sulfur Market Restraints 2.2.5.3. South America Sulfur Market Opportunities 2.2.5.4. South America Sulfur Market Challenges 2.3. PORTER’s Five Forces Analysis 2.4. PESTLE Analysis 2.5. Technology Roadmap 2.6. Regulatory Landscape by Region 2.6.1. North America 2.6.2. Europe 2.6.3. Asia Pacific 2.6.4. Middle East and Africa 2.6.5. South America 2.7. Key Opinion Leader Analysis For Sulfur Industry 2.8. Analysis of Government Schemes and Initiatives For Sulfur Industry 2.9. Sulfur Market price trend Analysis (2025-2034) 2.10. Sulfur Market Trade Analysis 2.10.1. Global Import Analysis 2.10.1.1. Top Importer of Sulfur 2.10.2. Global Export Analysis 2.10.2.1. Top Exporter of Sulfur 2.11. Sulfur Production Analysis 2.12. The Global Pandemic Impact on Sulfur Market 3. Sulfur Market: Global Market Size and Forecast by Segmentation by Demand and Supply Side (by Value and Volume) 2025-2034 3.1. Sulfur Market Size and Forecast, by Product (2025-2034) 3.1.1. Pharmaceutical Grade 3.1.2. Industrial Grade 3.2. Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 3.2.1. Fertilizers 3.2.2. Chemical Processing 3.2.3. Metal Manufacturing 3.2.4. Petroleum Refining 3.2.5. Others 3.3. Sulfur Market Size and Forecast, by Application (2025-2034) 3.3.1. Sulfuric Acid Synthesis 3.3.2. Sulphonate Surfactants Synthesis 3.3.3. Agrochemicals 3.3.4. Metal Extraction 3.3.5. Oil Refining 3.3.6. Others 3.4. Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 3.4.1. Direct Sale 3.4.2. Indirect Sale 3.5. Sulfur Market Size and Forecast, by Region (2025-2034) 3.5.1. North America 3.5.2. Europe 3.5.3. Asia Pacific 3.5.4. Middle East and Africa 3.5.5. South America 4. North America Sulfur Market Size and Forecast by Segmentation (by Value and Volume) 2025-2034 4.1. North America Sulfur Market Size and Forecast, by Product (2025-2034) 4.1.1. Pharmaceutical Grade 4.1.2. Industrial Grade 4.2. North America Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 4.2.1. Fertilizers 4.2.2. Chemical Processing 4.2.3. Metal Manufacturing 4.2.4. Petroleum Refining 4.2.5. Others 4.3. North America Sulfur Market Size and Forecast, by Application (2025-2034) 4.3.1. Sulfuric Acid Synthesis 4.3.2. Sulphonate Surfactants Synthesis 4.3.3. Agrochemicals 4.3.4. Metal Extraction 4.3.5. Oil Refining 4.3.6. Others 4.4. North America Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 4.4.1. Direct Sale 4.4.2. Indirect Sale 4.5. North America Sulfur Market Size and Forecast, by Country (2025-2034) 4.5.1. United States 4.5.1.1. United States Sulfur Market Size and Forecast, by Product (2025-2034) 4.5.1.1.1. Pharmaceutical Grade 4.5.1.1.2. Industrial Grade 4.5.1.2. United States Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 4.5.1.2.1. Fertilizers 4.5.1.2.2. Chemical Processing 4.5.1.2.3. Metal Manufacturing 4.5.1.2.4. Petroleum Refining 4.5.1.2.5. Others 4.5.1.3. United States Sulfur Market Size and Forecast, by Application (2025-2034) 4.5.1.3.1. Sulfuric Acid Synthesis 4.5.1.3.2. Sulphonate Surfactants Synthesis 4.5.1.3.3. Agrochemicals 4.5.1.3.4. Metal Extraction 4.5.1.3.5. Oil Refining 4.5.1.3.6. Others 4.5.1.4. United States Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 4.5.1.4.1. Direct Sale 4.5.1.4.2. Indirect Sale 4.5.2. Canada 4.5.2.1. Canada Sulfur Market Size and Forecast, by Product (2025-2034) 4.5.2.1.1. Pharmaceutical Grade 4.5.2.1.2. Industrial Grade 4.5.2.2. Canada Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 4.5.2.2.1. Fertilizers 4.5.2.2.2. Chemical Processing 4.5.2.2.3. Metal Manufacturing 4.5.2.2.4. Petroleum Refining 4.5.2.2.5. Others 4.5.2.3. Canada Sulfur Market Size and Forecast, by Application (2025-2034) 4.5.2.3.1. Sulfuric Acid Synthesis 4.5.2.3.2. Sulphonate Surfactants Synthesis 4.5.2.3.3. Agrochemicals 4.5.2.3.4. Metal Extraction 4.5.2.3.5. Oil Refining 4.5.2.3.6. Others 4.5.2.4. Canada Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 4.5.2.4.1. Direct Sale 4.5.2.4.2. Indirect Sale 4.5.3. Mexico 4.5.3.1. Mexico Sulfur Market Size and Forecast, by Product (2025-2034) 4.5.3.1.1. Pharmaceutical Grade 4.5.3.1.2. Industrial Grade 4.5.3.2. Mexico Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 4.5.3.2.1. Fertilizers 4.5.3.2.2. Chemical Processing 4.5.3.2.3. Metal Manufacturing 4.5.3.2.4. Petroleum Refining 4.5.3.2.5. Others 4.5.3.3. Mexico Sulfur Market Size and Forecast, by Application (2025-2034) 4.5.3.3.1. Sulfuric Acid Synthesis 4.5.3.3.2. Sulphonate Surfactants Synthesis 4.5.3.3.3. Agrochemicals 4.5.3.3.4. Metal Extraction 4.5.3.3.5. Oil Refining 4.5.3.3.6. Others 4.5.3.4. Mexico Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 4.5.3.4.1. Direct Sale 4.5.3.4.2. Indirect Sale 5. Europe Sulfur Market Size and Forecast by Segmentation (by Value and Volume) 2025-2034 5.1. Europe Sulfur Market Size and Forecast, by Product (2025-2034) 5.2. Europe Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.3. Europe Sulfur Market Size and Forecast, by Application (2025-2034) 5.4. Europe Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5. Europe Sulfur Market Size and Forecast, by Country (2025-2034) 5.5.1. United Kingdom 5.5.1.1. United Kingdom Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.1.2. United Kingdom Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.1.3. United Kingdom Sulfur Market Size and Forecast, by Application(2025-2034) 5.5.1.4. United Kingdom Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.2. France 5.5.2.1. France Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.2.2. France Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.2.3. France Sulfur Market Size and Forecast, by Application(2025-2034) 5.5.2.4. France Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.3. Germany 5.5.3.1. Germany Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.3.2. Germany Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.3.3. Germany Sulfur Market Size and Forecast, by Application (2025-2034) 5.5.3.4. Germany Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.4. Italy 5.5.4.1. Italy Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.4.2. Italy Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.4.3. Italy Sulfur Market Size and Forecast, by Application(2025-2034) 5.5.4.4. Italy Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.5. Spain 5.5.5.1. Spain Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.5.2. Spain Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.5.3. Spain Sulfur Market Size and Forecast, by Application (2025-2034) 5.5.5.4. Spain Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.6. Sweden 5.5.6.1. Sweden Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.6.2. Sweden Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.6.3. Sweden Sulfur Market Size and Forecast, by Application (2025-2034) 5.5.6.4. Sweden Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.7. Austria 5.5.7.1. Austria Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.7.2. Austria Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.7.3. Austria Sulfur Market Size and Forecast, by Application (2025-2034) 5.5.7.4. Austria Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 5.5.8. Rest of Europe 5.5.8.1. Rest of Europe Sulfur Market Size and Forecast, by Product (2025-2034) 5.5.8.2. Rest of Europe Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 5.5.8.3. Rest of Europe Sulfur Market Size and Forecast, by Application (2025-2034) 5.5.8.4. Rest of Europe Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6. Asia Pacific Sulfur Market Size and Forecast by Segmentation (by Value and Volume) 2025-2034 6.1. Asia Pacific Sulfur Market Size and Forecast, by Product (2025-2034) 6.2. Asia Pacific Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.3. Asia Pacific Sulfur Market Size and Forecast, by Application (2025-2034) 6.4. Asia Pacific Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5. Asia Pacific Sulfur Market Size and Forecast, by Country (2025-2034) 6.5.1. China 6.5.1.1. China Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.1.2. China Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.1.3. China Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.1.4. China Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.2. S Korea 6.5.2.1. S Korea Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.2.2. S Korea Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.2.3. S Korea Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.2.4. S Korea Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.3. Japan 6.5.3.1. Japan Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.3.2. Japan Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.3.3. Japan Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.3.4. Japan Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.4. India 6.5.4.1. India Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.4.2. India Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.4.3. India Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.4.4. India Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.5. Australia 6.5.5.1. Australia Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.5.2. Australia Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.5.3. Australia Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.5.4. Australia Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.6. Indonesia 6.5.6.1. Indonesia Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.6.2. Indonesia Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.6.3. Indonesia Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.6.4. Indonesia Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.7. Malaysia 6.5.7.1. Malaysia Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.7.2. Malaysia Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.7.3. Malaysia Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.7.4. Malaysia Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.8. Vietnam 6.5.8.1. Vietnam Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.8.2. Vietnam Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.8.3. Vietnam Sulfur Market Size and Forecast, by Application(2025-2034) 6.5.8.4. Vietnam Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.9. Taiwan 6.5.9.1. Taiwan Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.9.2. Taiwan Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.9.3. Taiwan Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.9.4. Taiwan Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 6.5.10. Rest of Asia Pacific 6.5.10.1. Rest of Asia Pacific Sulfur Market Size and Forecast, by Product (2025-2034) 6.5.10.2. Rest of Asia Pacific Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 6.5.10.3. Rest of Asia Pacific Sulfur Market Size and Forecast, by Application (2025-2034) 6.5.10.4. Rest of Asia Pacific Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 7. Middle East and Africa Sulfur Market Size and Forecast by Segmentation (by Value and Volume) 2025-2034 7.1. Middle East and Africa Sulfur Market Size and Forecast, by Product (2025-2034) 7.2. Middle East and Africa Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 7.3. Middle East and Africa Sulfur Market Size and Forecast, by Application (2025-2034) 7.4. Middle East and Africa Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 7.5. Middle East and Africa Sulfur Market Size and Forecast, by Country (2025-2034) 7.5.1. South Africa 7.5.1.1. South Africa Sulfur Market Size and Forecast, by Product (2025-2034) 7.5.1.2. South Africa Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 7.5.1.3. South Africa Sulfur Market Size and Forecast, by Application (2025-2034) 7.5.1.4. South Africa Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 7.5.2. GCC 7.5.2.1. GCC Sulfur Market Size and Forecast, by Product (2025-2034) 7.5.2.2. GCC Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 7.5.2.3. GCC Sulfur Market Size and Forecast, by Application (2025-2034) 7.5.2.4. GCC Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 7.5.3. Nigeria 7.5.3.1. Nigeria Sulfur Market Size and Forecast, by Product (2025-2034) 7.5.3.2. Nigeria Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 7.5.3.3. Nigeria Sulfur Market Size and Forecast, by Application (2025-2034) 7.5.3.4. Nigeria Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 7.5.4. Rest of ME&A 7.5.4.1. Rest of ME&A Sulfur Market Size and Forecast, by Product (2025-2034) 7.5.4.2. Rest of ME&A Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 7.5.4.3. Rest of ME&A Sulfur Market Size and Forecast, by Application (2025-2034) 7.5.4.4. Rest of ME&A Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 8. South America Sulfur Market Size and Forecast by Segmentation (by Value and Volume) 2025-2034 8.1. South America Sulfur Market Size and Forecast, by Product (2025-2034) 8.2. South America Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 8.3. South America Sulfur Market Size and Forecast, by Application(2025-2034) 8.4. South America Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 8.5. South America Sulfur Market Size and Forecast, by Country (2025-2034) 8.5.1. Brazil 8.5.1.1. Brazil Sulfur Market Size and Forecast, by Product (2025-2034) 8.5.1.2. Brazil Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 8.5.1.3. Brazil Sulfur Market Size and Forecast, by Application (2025-2034) 8.5.1.4. Brazil Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 8.5.2. Argentina 8.5.2.1. Argentina Sulfur Market Size and Forecast, by Product (2025-2034) 8.5.2.2. Argentina Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 8.5.2.3. Argentina Sulfur Market Size and Forecast, by Application (2025-2034) 8.5.2.4. Argentina Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 8.5.3. Rest Of South America 8.5.3.1. Rest Of South America Sulfur Market Size and Forecast, by Product (2025-2034) 8.5.3.2. Rest Of South America Sulfur Market Size and Forecast, by End Use Industry (2025-2034) 8.5.3.3. Rest Of South America Sulfur Market Size and Forecast, by Application (2025-2034) 8.5.3.4. Rest Of South America Sulfur Market Size and Forecast, by Sales Channel (2025-2034) 9. Global Sulfur Market: Competitive Landscape 9.1. MMR Competition Matrix 9.2. Competitive Landscape 9.3. Key Players Benchmarking 9.3.1. Company Name 9.3.2. Business Segment 9.3.3. End-user Segment 9.3.4. Revenue (2022) 9.3.5. Production of 2022 9.3.6. Company Locations 9.4. Leading Sulfur Market Companies, by market capitalization 9.5. Analysis of Organized and Unorganized Key Players in Sulfur Industry 9.6. Market Structure 9.6.1. Market Leaders 9.6.2. Market Followers 9.6.3. Emerging Players 9.7. Mergers and Acquisitions Details 10. Company Profile: Key Players 10.1. Nutrien Ltd. 10.1.1. Company Overview 10.1.2. Business Portfolio 10.1.3. Financial Overview 10.1.4. SWOT Analysis 10.1.5. Strategic Analysis 10.1.6. Scale of Operation (small, medium, and large) 10.1.7. Details on Partnership 10.1.8. Regulatory Accreditations and Certifications Received by Them 10.1.9. Awards Received by the Firm 10.1.10. Recent Developments 10.2. The Mosaic Company 10.3. Koch Industries, Inc. 10.4. Compass Minerals 10.5. Kemin Industries 10.6. Tiger-Sul Products LLC 10.7. Suncor Energy Inc. 10.8. H.J. Baker & Bro., LLC 10.9. Marathon Petroleum Corporation 10.10. Valero Energy Corporation 10.11. Chevron Corporation 10.12. Freeport-McMoRan Inc. 10.13. Gulf Chemical & Metallurgical Corporation 10.14. Chemtrade Logistics Inc. 10.15. Motiva Enterprises LLC 10.16. K+S AG 10.17. EuroChem Group AG 10.18. Tessenderlo Group 10.19. Gazprom 10.20. Shell plc 10.21. ExxonMobil Corporation 10.22. TotalEnergies SE 10.23. BASF SE 10.24. OCI Global 10.25. Yara International ASA 10.26. Acron Group 10.27. PhosAgro 10.28. Uralchem Group 10.29. Treibacher Industrie AG 10.30. Grupa Azoty 10.31. China Petroleum & Chemical Corporation (Sinopec) 10.32. China National Petroleum Corporation (CNPC) 10.33. PetroChina Company Limited 10.34. Indian Oil Corporation Limited (IOCL) 10.35. Hindustan Petroleum Corporation Limited (HPCL) 10.36. Bharat Petroleum Corporation Limited (BPCL) 10.37. Coromandel International Limited 10.38. Deepak Fertilisers & Petrochemicals Corporation Limited 10.39. Sulphur Mills Limited 10.40. Zuari Agro Chemicals Limited 10.41. Nufarm Limited 10.42. China Sunsine Chemical Holdings Ltd. 10.43. Saudi Arabian Oil Company (Aramco) 10.44. Abu Dhabi National Oil Company (ADNOC) 10.45. QatarEnergy 10.46. Kuwait Petroleum Corporation (KPC) 10.47. Ma'aden 10.48. ICL Group Ltd. 10.49. Petróleo Brasileiro S.A. (Petrobras) 10.50. Vale S.A. 11. Key Findings 12. Industry Recommendations 13. Sulfur Market: Research Methodology 14. Terms and Glossary

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements