
Precast Concrete Market Size by Product, Application, Product Type and Region – Segment-Level Market Assessment, Growth Opportunity Analysis, Competitive Mapping & Forecast to 2034
Overview
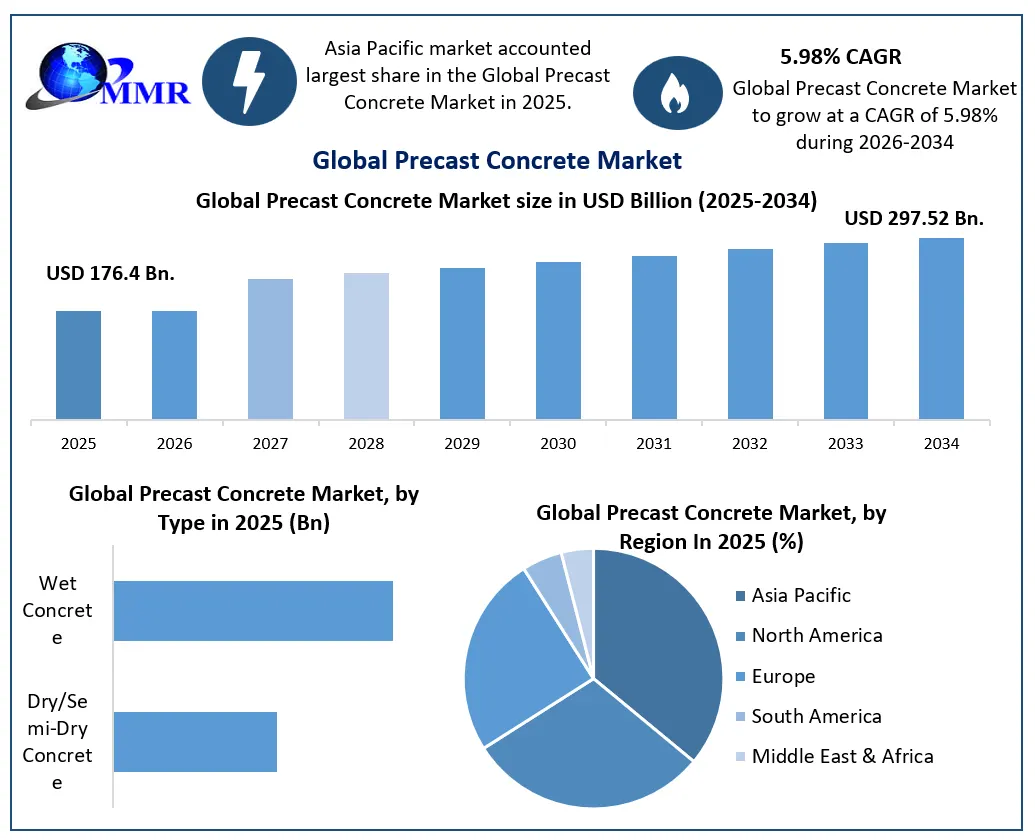
Precast Concrete Market was valued at USD 176.4 Billion in 2025, and it is expected to reach USD 297.52 Billion by 2034, exhibiting a CAGR of 5.98 % during the forecast period (2026-2034)
Wall panels, veneer, underground utility vaults, sound walls, pipes, water tanks, pavement slabs, manholes, highway barriers, bridges, ducts, tunnels, and building foundations are all made from precast concrete. The construction industry's shift toward green, energy-efficient structures, particularly in developing nations, is expected to boost Precast Concrete Market demand. Furthermore, the rising popularity of offsite building has resulted in greater demand.
The industry is also expanding as a result of increased residential and commercial building in developing nations, particularly China and India. A substantial portion of this expansion may also be ascribed to increased knowledge of the benefits of employing precast concrete among builders, architects, constructors, and end users.
Government actions in the Asia-Pacific region are expected to encourage building, hence promoting industrial growth. Government programmes such as OBOR and Bharatmala are intended to boost infrastructure development, particularly in China and India. Precast concrete requires less raw material than traditional building methods, saving a significant amount of money. Precast concrete construction takes less time to complete, which reduces labour costs.
Technological advances such as improved performance, lifespan, and durability are expected to drive Precast Concrete industry demand. Major players are always focusing on technical breakthroughs to enhance the overall performance of their products.
Because of the presence of key manufacturers covering major regions across the area, the precast concrete industry is characterised by fierce rivalry. To acquire a competitive edge, these players prioritise long-term relationships with application industry participants. Small-scale market firms are likewise employing similar techniques to boost their market penetration in a competitive market. Increasing investments and ongoing R&D have resulted in the production of precast products with increased durability and strength. Furthermore, architectural design and product adaptations to match with the particular structures of buildings and infrastructures have restraint the Precast Concrete industry.
To know about the Research Methodology :- Request Free Sample Report
Precast Concrete Market Trends
The construction industry is experiencing rapid technological and architectural improvement. To fulfil shifting standards and requirements, airports, transit lines, and even residential projects are experiencing enormous alterations. Other factors propelling the precast concrete industry include greater usage in flexible architectural design and historic structural maintenance. The global precast concrete industry is expected to grow considerably over the forecast period. Rapid industrialization and urbanisation in emerging economies are focused on the global production of high-quality infrastructure, with green building projects driving the sector.
The growing popularity of precast building is driving up demand for cement. This demand prompted enormous mining activities, which are wreaking havoc on the environment in a number of nations. Manufacturers have developed an innovative solution in the shape of "Recycled Concrete" to address severe government rules and laws.
1. Chemicals such as cement additives are being used to make the precast product more strong.
2. The CAD/CAM software are used to design the precast products in order to improve the compatibility of products.
3. American Section of the International Association for Testing Materials (ASTM) have various standards for precast concrete construction.
4. The department of Environmental protection regulates and controls VOC emission from production of precast concrete products.
5. The main raw material used in precast concrete are cement, aggregates and water. Price of cement and aggregates tends to fluctuate which may cause concern for precast products manufacturers.
6. There is increasing used in concrete additives which increases the strength and durability of precast concrete structures.
7. The commercial and infrastructure end use segment remain important segments.
8. Superior strength and design flexibility are the main reasons choosing precast concrete products over conventional method.
Precast Concrete Market Dynamics
Advantages of Precast Concrete Are Driving the Precast Concrete Industry Growth
Precast concrete provides various benefits over on-site cast concrete in infrastructure. The primary benefit of precast over traditional methods is greater quality. Technical management and perfect industrial conditions have resulted in enhanced quality. One of the most significant advantages of precast concrete over traditional concrete is its speed of construction. Precast concrete can save about one-third of overall building time.
An ordinary home system may be installed in less than a day's labour. The installation of wall panels and other components takes relatively little time since the use of precast concrete speeds up the building process. This reduces the amount of time and effort required. Furthermore, the great durability of precast concrete constructions is expected to drive demand even higher. As a result, demand for precast concrete products is increasing rapidly, and this trend is likely to continue during the forecast period.
When compared to traditional methods, the use of precast concrete in construction operations is less expensive. Precast structural walls are 20% less expensive than traditional casting methods. Precast concrete walls require 75% less formwork, 90% less wet concrete, and 75% to 90% less scaffolding than traditional cast-in-place concrete walls. However, the biggest cost savings come from reducing on-site labour. Precast construction can save up to 80% of on-site labour.
Precast concrete slabs are 23.22% less expensive than cast-in-place concrete construction on average, while precast columns are about 21.4% less expensive, especially for large-scale manufacturing. Precast concrete's low cost has led to its popularity in a variety of application categories, including residential, commercial, infrastructural, and industrial.
Gaining Prominence of Offsite Construction to Boost Precast Concrete Industry Growth
Offsite or prefabrication is a construction procedure that includes constructing civil structural components in a manufacturing facility and then moving the entire assembly to the construction site. Precast structures are cast and hardened before they are utilised in construction. Offsite construction relies heavily on precast concrete materials. Offsite building is gaining popularity in the construction industry because it saves time and reduces material waste.
The procedure may be carried out regardless of the weather. For example, bridges and flyovers are constructed using precast concrete. Cranes and trained manpower are used to transfer these prefabricated pillars and deck slabs to the job site and erect them. Offsite construction is expected to be a significant driver of development in the precast concrete industry over the forecast period. Because the regulatory landscape is continually changing, the adoption of more ecologically sustainable and regulatory-compliant building processes is projected to enhance prospects and revenues in established markets such as Western Europe and North America. Furthermore, in the post-COVID environment, offsite housing building is expected to increase. England is experiencing a housing scarcity as a result of construction activity being halted owing to the spread of COVID-19 and the adoption of lockdown.
The implementation of strong tracking and isolation mechanisms, together with preventative measures, will aid in the containment of the pandemic, which is expected to enhance demand for precast concrete.
Precast concrete provides a controlled atmosphere and in-factory quality inspections, lowering the defect rate. Construction waste and pollutant emissions are also decreased as a result of enhanced manufacturing and recycling capabilities. The previously mentioned advantage of precast concrete is expected to drive Precast Concrete Market growth over the forecast period.
High Cost of Machinery to Restraint the Growth of the Market
Despite the fact that precast concrete has significant benefits over traditional concrete, its usage in poor countries is limited owing to the large investment required. The gear and moulds required for the fabrication of precast concrete items are expensive. To manufacture precast concrete items, complex technology and highly skilled workers are required. Over the foreseeable term, the substantial initial investment is likely to constrain growth.
Even if the cost of producing precast concrete is decreasing, there are still costs that may limit the Precast Concrete Market. Because precast concrete is manufactured in factories, it must be delivered to the building site. The cost of transporting this precast product is enormous owing to its huge weight of the precast components and manpower required for handling the material.
The economic benefit of precast building is somewhat offset by the higher expenses. Precast construction's necessity for more trained labour and supervision, as compared to traditional methods, is expected to raise the cost. Furthermore, the expense of vast tracts of land places a greater economic strain on producers, as storage sites must be large enough to properly store precast concrete components, with enough room for lifting equipment and carrying trucks to navigate. Incorrect stacking and storage can cause damage to precast pieces. To prevent unintentional damage and discoloration, the stored and stacked units must be covered, and the support material must be non-staining.
New Industry Avenues Analysis
Precast concrete is increasingly being utilised to build grave liners and burial vaults. The funeral and burial business has a lesser Precast Concrete Market share. However, it currently has a consistent percentage of the whole precast concrete market. The burying business requires enormous concrete cages to protect the cascade from ground settling and earth weight. The upper sector of precast concrete is expected to have a significant share in locations with a mainly Christian population.
One of the primary Precast Concrete industry routes for precast concrete is hotel construction. The rapid growth of the tourist sector has produced demand for the construction of new hotels, which is contributing to global job creation and economic growth. Construction businesses and hotel operators see this trend since the tourist industry has enormous potential. This is expected to lead to healthy competition, since vendors in the tourist business will likely focus on providing inhabitants with amenities such as a comfortable stay.
Europe and the Middle East are the most popular tourist locations on the planet. The region of Europe receives the most tourists. Thailand is one of the most popular tourist destinations in the Asia-Pacific region. These factors are expected to drive precast concrete product demand for lodging space, hotels, restaurants, and other commercial buildings over the forecast period.
Another area of growth for precast concrete is transportation infrastructure. Growing urbanisation has increased global need for a better transportation infrastructure. The transport infrastructure industry is predicted to increase dramatically in the next years as governments establish various strategies to fulfil this need, with large demand coming from countries such as India and China.
Precast Concrete Market Segment Analysis
By Element, The market is segmented into columns and beams, floors and roofs, girders, walls and barriers, utility vaults, pipes, paving slabs, and others. Columns and beams provide structural support and load distribution in buildings and infrastructure, while floors and roofs form essential building surfaces and protective structures. Girders support heavy loads across large spans, whereas walls and barriers provide enclosure, separation, and safety. Utility vaults house underground utility connections and equipment, pipes support water supply, drainage, and other infrastructure networks, and paving slabs are used in roads, walkways, and outdoor surfaces. Other elements include additional precast components used across construction and infrastructure projects.
By Type, The market is segmented into dry/semi-dry concrete and wet concrete. Dry and semi-dry concrete uses low water content and supports the production of precast components through compaction and moulding, offering dimensional consistency and efficient manufacturing. Wet concrete contains higher water content and is poured into moulds before setting, making it suitable for producing complex shapes and components that require greater workability and surface finishing.
By Application, The market is segmented into structural building components, architectural building components, transportation products, waste and waste handling products, and others. Structural building components support the strength and stability of buildings through elements such as beams, columns, floors, and walls, while architectural building components provide aesthetic finishes and functional design features. Transportation products are used in roads, bridges, railways, and related infrastructure, whereas waste and waste handling products include components for drainage, sewage, and waste management systems. Other applications cover additional precast products used in construction, utilities, and infrastructure development.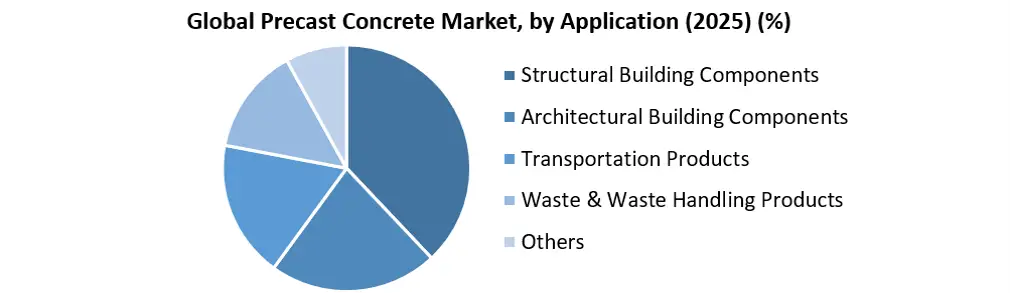
Precast Concrete Market Regional Insights
The Asia Pacific area is distinguished by a vast supply of trained labour at a low cost, as well as easy land availability. Despite declining growth in other wealthy countries such as the United States, the majority of Asian countries are expected to experience substantial economic growth over the forecast period. The change in the manufacturing environment toward developing economies, notably China and India, is expected to boost market growth during the forecast period.
Rising infrastructure development and government investments in megaprojects such as the Hong Kong-Zhuhai-Macao Bridge, the China-Pakistan Economic Corridor, the Navi Mumbai International Airport, the Hyderabad Metro Rail, and Japan's maglev High-Speed Rail are expected to drive demand for precast concrete in the region.
In the twentieth century, China saw significant urbanisation and industrialisation. Furthermore, since the late 1990s, the Chinese government has made significant investments in fixed assets. Rising urbanisation has led in increasing expenditures in transportation networks, ports, highways, and mega-factories, boosting demand for precast concrete over the forecast period. Because of strong consumption in residential and non-residential construction, structural building components were the dominating product type in the region.
Rising per capita income in middle-income nations such as China and India is expected to stimulate the residential building sector. The above reason is expected to boost regional precast concrete demand.
The rapidly developing construction sector in North American economies such as the United States, Canada, and Mexico, as well as increased demand for sustainable and innovative building techniques, are expected to fuel product demand. Furthermore, the country's rapid commercial expansion is expected to create new avenues for different sectors such as hospitality, retail, and others to expand markets, which is expected to help Precast Concrete Market growth for precast concrete in the region during the forecast period.
Over the forecast period, the stable residential sector in the United States and Canada is likely to fuel demand for precast concrete. However, the slow-moving residential market in Mexico on account of decreased demand for urban housing coupled with rising house prices is likely to limit the product market.
The increased private investment in developing countries is ascribed to the region's growth. The construction industry's considerable rebound, together with increased penetration of precast concrete products in the area, is likely to boost Precast Concrete Market growth. Increased building activity in Europe due to low mortgage rates is expected to drive demand for precast concrete products in both new construction and rehabilitation projects.
However, high labour costs are likely to have a detrimental impact on the region's construction sector, resulting in slow expansion of the precast concrete product industry over the forecast period. The Nordic nations of Europe were among the first in the world to use precast technology.
As a result, the precast concrete products are expected to witness high penetration in European construction industry over the forecast period. Severe impact of coronavirus pandemic on the construction industry in major economies of Spain, Italy and UK is expected to limit the growth in the estimated time.
Recent Industry Developments (2025–2026)
| Exact Date | Company | Development | Impact |
|---|---|---|---|
| 14 January 2025 | LafargeHolcim Ltd | The company inaugurated its advanced automated precast facility in North America to produce low-carbon structural elements. | The move significantly reduces embodied carbon in large-scale infrastructure projects across the region. |
| 22 February 2025 | Sika AG | Sika launched a new generation of admixtures specifically designed to increase the early strength of 3D-printed precast components. | This development accelerates production cycles and reduces the need for heat curing in precast plants. |
| 10 May 2025 | Cemex S.A.B. de C.V. | Cemex completed the acquisition of a specialized precast manufacturer in Central Europe to bolster its urban infrastructure portfolio. | The acquisition expands Cemex's regional market share and provides integrated solutions for smart city developments. |
| 18 September 2025 | Heidelberg Materials | The company announced the commercial rollout of recycled-aggregate precast blocks utilizing carbon capture technology. |
Precast Concrete Market Scope: Inquire before buying
| Precast Concrete Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 176.4 Billion |
| Forecast Period 2026-2034 CAGR: | 5.98% | Market Size in 2034: | USD 297.52 Billion |
| Segments Covered: | by Element | Columns & beams Floors & roofs Girders Walls & barriers Utility vaults Pipes Paving slabs Others |
|
| by Type | Dry/semi-dry concrete Wet concrete |
||
| by Installation Type | Permanent Precast Concrete Modular & Relocatable Precast Concrete |
||
| by Distribution Channel | Direct Sales (Manufacturers to Contractors/Developers) Precast Concrete Distributors & Dealers Construction Material Suppliers EPC & Infrastructure Contractors Online Procurement Platforms |
||
| by Application | Structural building components Architectural building components Transportation products Waste & waste handling products Others |
||
| by End-Use Industry | Residential Non-residential Tunnels Bridges Wind tower |
||
Precast Concrete Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Key players/ competitors profile covered in brief in Precast Concrete Market report in strategic perspective
North America
1. Tindall Corporation
2. Metromont Corporation
3. Gate Precast
4. High Concrete Group
5. Fabcon Precast
6. Jensen Precast
7. Smith-Midland Corporation
8. County Materials Corporation
9. Oldcastle Infrastructure
10. Cretex Companies
Europe
1. Consolis
2. Decomo
3. Spenncon
4. Bison Precast
5. FP McCann
6. Banagher Precast Concrete
7. Abetong
8. Etex
Asia-Pacific
1. Boral Limited
2. CSR Limited
3. Nippon Concrete Industries
4. Sekisui House
5. Taisei Corporation
6. Kajima Corporation
7. Larsen & Toubro
8. Ahluwalia Contracts
9. Everest Industries
10. Precast India Infrastructures
11. BBMG Corporation
12. China State Construction Engineering Corporation
13. Broad Homes
14. Shanghai Construction Group
15. Hume Concrete
Rest of the World
1. Saudi Readymix
2. Hard Precast Building Systems
3. RAK Precast
4. Dubai Precast
5. Qanbar Dywidag Precast Concrete
6. Concremat
7. Premoldeados de Argentina
8. Revaro
9. Cape Concrete Works
10.Consolis South Africa
11.Others
Frequently Asked Questions (FAQs)
1. What is the global precast concrete market size in 2025?
Ans. The global precast concrete market is valued at USD 176.4 billion in 2025.
2. What is the expected CAGR of the precast concrete market during 2026–2034?
Ans. The precast concrete market is expected to grow at a CAGR of 5.98% from 2026 to 2034.
3. Which region dominates the precast concrete market?
Ans. Asia Pacific leads the precast concrete market, driven by rapid urbanization, infrastructure development, and rising construction investments.
4. What are the key segments of the precast concrete market?
Ans. The market is segmented by element, type, installation type, distribution channel, application, and end-use industry.
5. Who are the key players in the global precast concrete market?
Ans. Key players include Tindall Corporation, Consolis, Boral Limited, Nippon Concrete Industries, Larsen & Toubro, and China State Construction Engineering Corporation.