
Global Industrial Control Robotics Market: by Payload (Up to 16 Kg, 16–60 Kg, 60–225 Kg, Above 225 Kg), by Type (Traditional, Collaborative), by Application (Handling, Welding, Assembling, Processing), by Industry (Automotive, Electronics, Food & Beverages, Others) - Forecast to 2034
Overview
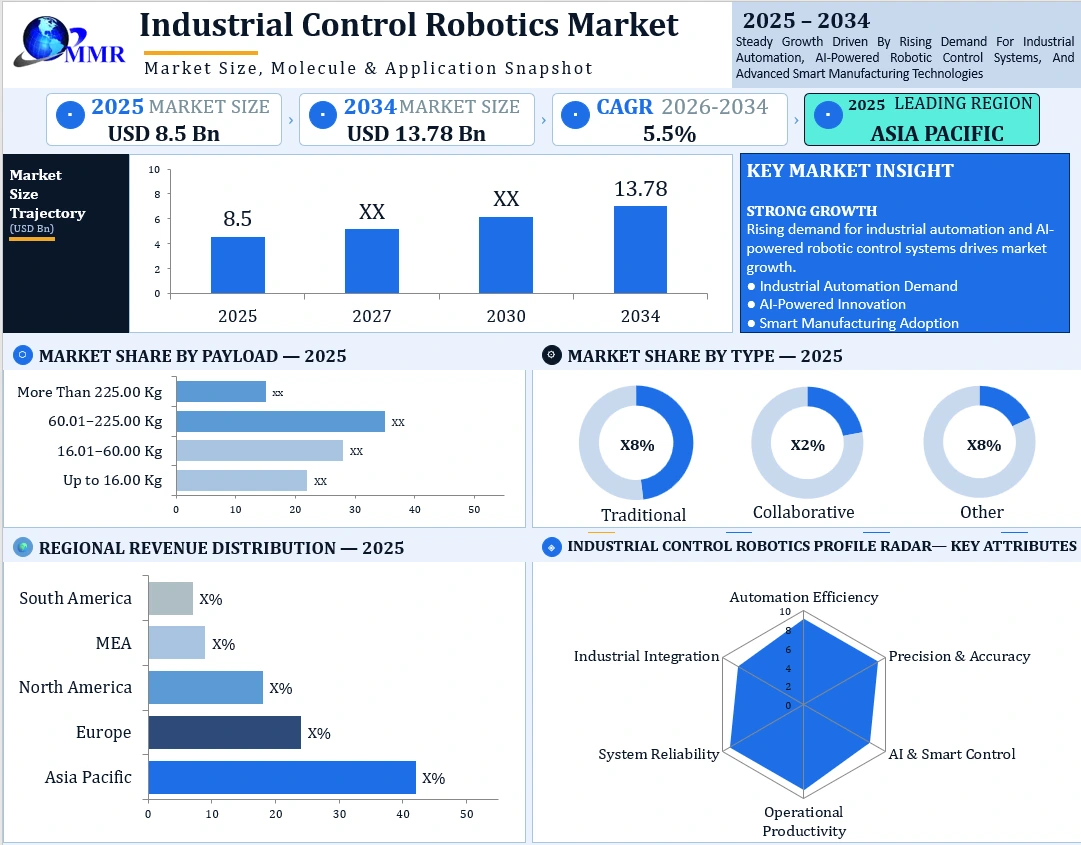
Global Industrial Control Robotics Market size was valued at USD 8.5 Bn. in 2025, and the total Industrial Control Robotics Market revenue is expected to grow by 5.5% from 2025 to 2034, reaching USD 13.78 Bn. by 2034
Global Industrial Control Robotics Market: Overview
The Industrial Control Robotics Market refers to the global industry focused on the development, production, and deployment of industrial robots and automated control systems used to improve manufacturing efficiency, precision, productivity, and operational safety. The market includes robotic arms, programmable industrial robots, collaborative robots (cobots), robotic controllers, sensors, machine vision systems, and software integrated with industrial automation technologies. Increasing adoption of smart manufacturing, Industry 4.0, artificial intelligence (AI), and the Industrial Internet of Things (IIoT) drives market growth across automotive, electronics, pharmaceuticals, food and beverage, and other industrial sectors.
The industrial Robots are in various forms such as delta robots, articulated robots and Cartesian robots; these types of robots are traditionally used in industries. The collaborative robots are getting more market share from the past few years. The application of robotics control in industries like automotive, electronics, electrical and metal industries is the major market for Global Industrial Control Robotics. This growth in this sector is owing to traditional robotics offering high volume of production capabilities.
Global Industrial Control Robotics Market Key Highlights
• Market Size: The global Industrial Control Robotics Market is valued at USD 8.5 billion in 2025 and is projected to reach USD 13.78 billion by 2034, registering a CAGR of 5.5% during 2025–2034.
• Regional Leadership: Asia Pacific holds the leading regional position in 2025, supported by strong manufacturing industries, particularly in China, Japan, South Korea, and India.
• Key Growth Drivers: Increasing industrial automation, Industry 4.0 investments, smart manufacturing, and the adoption of AI-enabled robotic control systems support market expansion.
• Payload Segmentation: The market covers four payload categories: up to 16 kg, 16.01–60 kg, 60.01–225 kg, and more than 225 kg, serving applications ranging from precision assembly to heavy-duty material handling.
• Type Segmentation: Traditional industrial robots remain important for high-volume manufacturing, while collaborative robots gain attention for flexible production, human–robot collaboration, and adaptable automation.
Global Industrial Control Robotics Market Size and Forecast Analysis
To know about the Research Methodology :- Request Free Sample Report
Industrial Control Robotics Market Dynamics
Industrial Control Robotics Market Drivers
• Increasing Industrial Automation: Rising adoption of industrial robots across automotive, pharmaceutical, electronics, food processing, and packaging industries drives market growth. Manufacturers deploy robotic systems to improve production speed, enhance accuracy, minimize human error, and reduce dependence on manual labor. Increasing demand for consistent product quality and efficient manufacturing processes further supports the adoption of industrial control robotics.
• Growing Industry 4.0 Investments: Increasing investments in smart factories, artificial intelligence (AI), machine vision, sensors, and connected control systems accelerate market expansion. Industrial robots integrated with programmable logic controllers (PLCs) and real-time monitoring software enable manufacturers to improve production visibility, optimize workflows, and implement predictive maintenance. These technologies support flexible manufacturing and improve overall operational efficiency.
Industrial Control Robotics Market Restraints
• High Initial Investment: The high cost of robotic equipment, controllers, sensors, installation, and system integration limits adoption, particularly among small and medium-sized enterprises (SMEs). Businesses also require investment in safety infrastructure, employee training, and production-line modifications before deploying industrial robotics. These financial requirements can delay automation projects and reduce adoption among companies operating with limited capital budgets.
• Maintenance and Integration Costs: Industrial robotics systems require regular servicing, software updates, component replacement, and technical support to maintain reliable performance. Integrating new robotic systems with existing manufacturing equipment and legacy control platforms can increase implementation complexity and costs. Unexpected equipment downtime and the need for specialized technicians further affect operational budgets and may discourage manufacturers from upgrading their automation infrastructure.
Industrial Control Robotics Market Opportunity
• Expansion in Emerging Economies: Growing industrialization, expanding manufacturing facilities, and increasing investments in domestic production create opportunities for industrial robotics suppliers in India, China, and other emerging economies. The automotive, electronics, pharmaceutical, and consumer goods industries increasingly adopt automated production technologies to improve efficiency and product quality. Government initiatives supporting advanced manufacturing and industrial modernisation further encourage robotics adoption.
• AI-Enabled Robotics: Increasing integration of AI, machine learning, computer vision, and intelligent control software creates opportunities for advanced industrial robotics solutions. These technologies enable robots to recognize objects, adapt to changing production conditions, detect defects, and perform complex tasks with greater precision. Demand for intelligent automation and predictive maintenance also encourages manufacturers to invest in connected robotic systems that improve productivity and reduce unplanned downtime.
Industrial Control Robotics Market Challenges
• Shortage of Skilled Professionals: The implementation of industrial control robotics requires skilled professionals in robot programming, control engineering, system integration, maintenance, and industrial software. A shortage of qualified technicians and engineers can delay installations, increase training expenses, and reduce the effectiveness of automation projects. Manufacturers need to invest in workforce development to operate and maintain increasingly sophisticated robotic systems.
• Cybersecurity and Compatibility Issues: Connected robotic systems exchange data with industrial networks, cloud platforms, sensors, and manufacturing software, increasing the importance of cybersecurity. Vulnerabilities in connected equipment can expose production systems to unauthorized access and operational disruptions. Compatibility issues between modern robotic controllers and legacy equipment can also complicate integration, requiring additional software development, infrastructure upgrades, and technical support.
Industrial Control Robotics Market Trends
• AI and Collaborative Robotics: Manufacturers increasingly adopt AI-enabled robots and collaborative robots (cobots) to automate repetitive, precision-sensitive, and potentially hazardous tasks. Cobots support human–robot collaboration in assembly, inspection, packaging, and material handling, while AI-powered vision systems improve object recognition and quality inspection. These developments increase demand for flexible robotic solutions that can adapt to changing production requirements.
• Smart Warehousing and Logistics: The expansion of e-commerce, distribution networks, and automated warehouses increases demand for autonomous mobile robots (AMRs), robotic picking systems, and automated material-handling equipment. These technologies support inventory movement, order fulfillment, sorting, and packaging while improving warehouse productivity and operational accuracy. The growing focus on faster deliveries, efficient inventory management, and reduced manual handling further strengthens this trend.
Global Industrial Control Robotics Market: Equipment
• The hazardous jobs in processing industries such as grinding, and milling should be done with less manpower. Thus, the manufacturers are looking for atomization solution with development and innovation in robotic technologies, the software advancement, torque, and force sensor. By using these manufacturers are installing robotics system heavily. The consistent result by compensation of wear and tear of tools gives reliable operation.
Industrial Control Robotics Market Segment Analysis
Global Market is segmented into Application (Handling , Assembling & Disassembling, Dispensing , Welding & Soldering, Processing ), By Payload (Up to 16.00 Kg, 16.01–60.00 Kg, 60.01–225.00 Kg, More Than 225.00 Kg), By Type (Traditional Industrial Robots, Collaborative Industrial Robots, Other Types), By Industry (Automotive, Electrical & Electronics, Plastics, Rubber, & Chemicals, Food & Beverages, Other industry) and Region (North America, Europe, Asia pacific, Middle East & Africa, and Latin America).
By Payload: The Industrial Robotics Market is segmented into up to 16.00 kg, 16.01–60.00 kg, 60.01–225.00 kg, and more than 225.00 kg. Robots with a payload capacity of up to 16.00 kg support electronics assembly, pharmaceutical production, precision handling, and small-component packaging due to their compact design and high accuracy. Robots in the 16.01–60.00 kg category perform machine tending, automotive component assembly, welding, packaging, and material handling, offering a balance of lifting capacity, speed, and flexibility. Robots with a payload capacity of 60.01–225.00 kg handle larger components in automotive manufacturing, metal fabrication, machine loading, and palletizing. Meanwhile, robots exceeding 225.00 kg serve heavy-duty applications in automotive manufacturing, foundries, metal processing, and large-scale material handling, where substantial lifting capacity and reliable performance are essential.
By Type: The Industrial Robotics Market is categorized into traditional industrial robots, collaborative industrial robots, and other types. Traditional industrial robots, including articulated, SCARA, Cartesian, and delta robots, support high-volume manufacturing through speed, precision, repeatability, and continuous operation across welding, painting, assembly, packaging, and material handling applications. Collaborative industrial robots (cobots) work alongside human operators in appropriately designed and safety-engineered environments, performing tasks such as inspection, machine tending, assembly, and packaging. Their flexibility makes them suitable for manufacturers requiring adaptable production processes. Other types include specialized robotic systems designed for cleanroom operations, precision manufacturing, and application-specific processing, where particular movement capabilities, environmental controls, and operating requirements support efficient industrial performance.
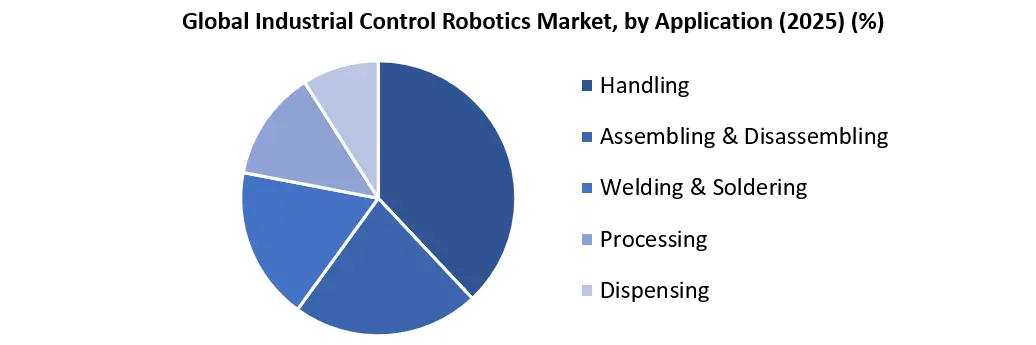
By Application: The Industrial Robotics Market is segmented into handling, assembling and disassembling, dispensing, welding and soldering, and processing. Handling robots perform picking and placing, component transfer, machine loading and unloading, packaging, and palletizing, helping manufacturers improve productivity and reduce manual labor. Assembling and disassembling robots perform component fitting, fastening, insertion, and product assembly with high precision, supporting automotive, electronics, and machinery manufacturing. Dispensing robots apply adhesives, sealants, lubricants, paints, and coatings in controlled quantities, improving application consistency and minimizing material waste. Welding and soldering robots automate joining operations across automotive manufacturing, metal fabrication, and electronics production, ensuring consistent quality and improved operational safety. Processing robots perform cutting, grinding, polishing, milling, deburring, and surface finishing, enabling manufacturers to improve product quality, maintain precision, and automate repetitive or physically demanding industrial tasks.
The report also helps in understanding Industrial Control Robotics Market dynamics, structure by analyzing the market segments and projects the Industrial Control Robotics Market size. Clear representation of competitive analysis of key players by Supply Chain, price, financial position, Product portfolio, growth strategies, and regional presence in the Industrial Control Robotics Market make the report investor’s guide.
Global Industrial Control Robotics Market Regional Overview
Global Market is segmented into regions Asia Pacific, North America, Europe, South America and Middle East & Africa. North America is the major player in the robotics and atomization industries owing to the fact that the labor cost is much higher in this region.
North America: North America benefits from investments in automotive manufacturing, aerospace, electronics, and advanced industrial automation. The United States installs approximately 38,500 industrial robots in 2025, an increase of 12% year over year. Canada records nearly 4,000 installations, up 5%, while Mexico records fewer than 5,200, reflecting a 7% decline. Demand for automation, productivity improvements, and reshoring of manufacturing operations supports regional adoption.
Europe: Europe maintains a substantial industrial robotics presence, supported by automotive manufacturing, machinery production, and precision engineering. Germany remains the region's largest market, recording fewer than 25,000 installations in 2025, down 8% year over year. Italy records approximately 7,800 installations, France nearly 4,500, and Spain approximately 4,300. These declines indicate softer demand in several established manufacturing economies, although industrial automation remains important for productivity and competitiveness.
Asia Pacific: Asia Pacific remains the largest regional market for industrial robotics in 2025, driven by manufacturing automation, electronics production, and automotive investments. China installs approximately 354,000 robots, accounting for 59% of global installations. Japan records 36,219 installations, South Korea approximately 30,000, and India nearly 10,500, with India's installations increasing 15% year over year. These figures demonstrate the region's strong manufacturing base and continued adoption of automated production technologies.
Middle East and Africa: The Middle East and Africa region offers opportunities for industrial robotics through investments in manufacturing diversification, infrastructure, logistics, and smart industrial facilities. Saudi Arabia and the United Arab Emirates continue to develop advanced manufacturing capabilities, while South Africa supports automation across automotive and metal-processing industries. However, a comparable region-wide installation figure for 2025 is not specified in the cited IFR release, so a precise regional volume or market share cannot be stated reliably.
South America: South America shows growing industrial robotics adoption, particularly in Brazil's automotive and manufacturing industries. Brazil installs approximately 4,300 industrial robots in 2025, representing 38% growth year over year. Automotive installations rise by 212% to nearly 2,100 units, reflecting increased investment in vehicle manufacturing and production automation. This expansion creates opportunities for robotics suppliers serving automotive assembly, material handling, welding, and other industrial applications
Global Industrial Control Robotics Market Competitive Landscape
The competitive landscape of the Global Industrial Control Robotics Market features several leading companies focusing on technological innovation, automation efficiency, and advanced robotic control systems.
• ABB offers industrial robots, collaborative robots (cobots), and digital robotics solutions, focusing on AI-enabled robotics, digital twins, and integrated automation platforms. Yaskawa specializes in welding, material handling, painting, and motion-control technologies, enhancing robot speed, precision, and motion-control integration.
• FANUC provides high-precision robots, CNC systems, and factory automation solutions, strengthening connected manufacturing, intelligent control, and predictive maintenance capabilities.
• KUKA focuses on automotive robotics and integrated manufacturing systems, expanding flexible production technologies, robot software, and AI-enabled automation.
• Mitsubishi Electric integrates industrial robots with programmable logic controllers (PLCs), servo drives, and factory automation platforms to support smart manufacturing.
• Kawasaki Heavy Industries specializes in heavy-duty robots, welding, and material handling, developing high-payload robots and application-specific automation solutions.
• DENSO focuses on compact industrial robots and precision assembly systems, emphasizing high-speed automation and compact robotic solutions for electronics manufacturing and other precision-oriented industrial applications.
Global Industrial Control Robotics Market Recent Developments
| Company | Date | Recent development | Market significance |
| ABB | April 2026 | Launches the PoWa collaborative robot family with payloads from 7 kg to 30 kg and speeds up to 5.8 m/s. | Strengthens its position in high-performance collaborative robotics for manufacturing and packaging. |
| ABB and NVIDIA | March 2026 | Integrate NVIDIA Omniverse simulation libraries into ABB's RobotStudio platform to support physical AI training and deployment. | Advances digital twins, simulation-based robot training, and AI-enabled industrial automation. |
| KUKA | October 2026 | Introduces iiQKA.AI Vision, an AI-powered industrial image-processing solution designed to simplify machine vision integration. | Makes vision-enabled automation more accessible to manufacturers and system integrators. |
| Yaskawa Electric | September 2026 | Launches the MOTOMAN-HC12 collaborative robot with a 12 kg payload capacity and 1,410 mm reach. | Expands flexible automation options for assembly, handling, and other industrial applications. |
| Universal Robots | September 2026 | Introduces its Gen 7 platform, featuring new robot arms, an upgraded controller, and hardware designed to support AI-powered applications. | Improves integration of sensing, force control, and AI-based automation in collaborative robotics. |
| FANUC, Yaskawa and Kawasaki Heavy Industries | July 2026 | Join Fujitsu's exploration of physical AI opportunities using NVIDIA technologies to connect AI systems with industrial robots. | Supports the development of intelligent robots for manufacturing, logistics, and other industrial applications. |
Industrial Control Robotics Market Scope: Inquire before buying
| Industrial Control Robotics Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 8.5 USD Billion |
| Forecast Period 2026-2034 CAGR: | 5.5% | Market Size in 2034: | 13.78 USD Billion |
| Segments Covered: | by Payload | Up to 16.00 Kg 16.01–60.00 Kg 60.01–225.00 Kg More Than 225.00 Kg |
|
| by Type | Traditional Industrial Robots Collaborative Industrial Robots Other Types |
||
| by Application | Handling Assembling & Disassembling Dispensing Welding & Soldering Processing |
||
| by Industry | Automotive Electrical & Electronics Plastics, Rubber, & Chemicals Food & Beverages Other industry |
||
Industrial Control Robotics Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Key players operating in Industrial Control Robotics Market
1. ABB
2. Yaskawa
3. FANUC
4. KUKA
5. Mitsubishi Electric
6. Kawasaki Heavy Industries
7. DENSO
8. NACHI-FUJIKOSHI
9. Epson
10. Dürr
11. Universal Robots
12. Omron Adept
13. b+m Surface Systems
14. Stäubli
15. Comau
16. Yamaha
17. IGM
18. ST Robotics
19. Franka Emika
20. CMA Robotics
21. Delta Electronics
22. Rethink Robotics
23. Techman Robots
24. Precise Automation
25. Siasun
26. Hirata Corporation
27. OTC Daihen Corporation
28. Panasonic Connect
29. Hyundai Robotics
30. Doosan Robotics
31. Rainbow Robotics
32. Hanwha Robotics
33. HD Hyundai Robotics
34. Estun Automation
35. Efort Intelligent Equipment
36. Inovance Technology
37. Guangzhou CNC Equipment
38. GSK CNC Equipment
39. STEP Electric Corporation
40. Siasun Robot & Automation
41. JAKA Robotics
42. AUBO Robotics
43. Elite Robots
44. Dobot
45. Agile Robots
Frequently Asked Questions:
Which region has the largest share in Global Industrial Control Robotics Market?
Ans: Asia Pacific region held the highest share in 2025.
What is the growth rate of Global Industrial Control Robotics Market?
Ans: The Global Industrial Control Robotics Market is growing at a CAGR of 5.5% during forecasting period 2025-2034.
What is scope of the Global Industrial Control Robotics Market report?
Ans: Global Industrial Control Robotics Market report helps with the PESTEL, PORTER, COVID-19 Impact analysis, Recommendations for Investors & Leaders, and market estimation of the forecast period.
Who are the key players in Global Industrial Control Robotics Market?
Ans: The important key players in the Global Industrial Control Robotics Market are – ABB, YASKAWAFANUC, KUKA, Mitsubishi Electric,Kawasaki Heavy Industries, DENSO NACHI-FUJIKOSHI, EPSON,Dürr, Universal Robots, Omron Adept, b+m Surface Systems, Stäubli,Comau, Yamaha.
What is the study period of this Market?
Ans: The Global Industrial Control Robotics Market is studied from 2020 to 2034.