
Global Industrial Robotics Market– Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning / Landscape Review & Global Market Size Forecast to 2034
Overview
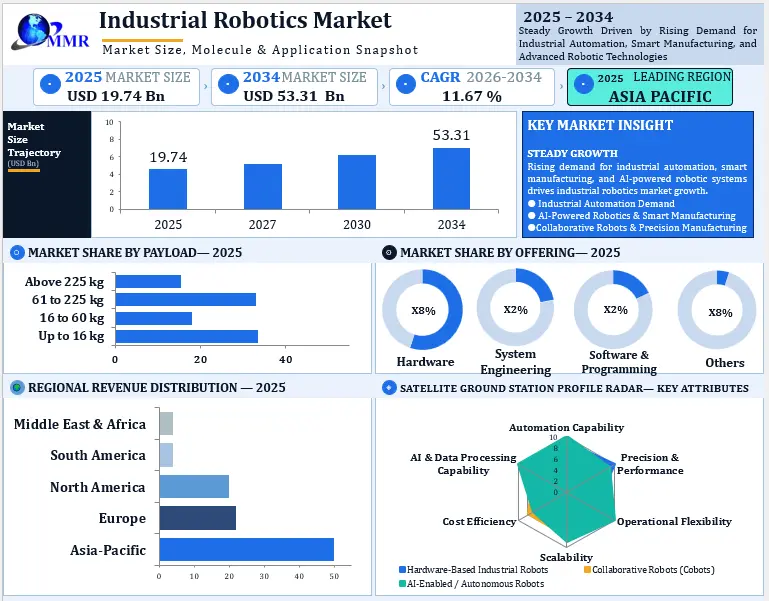
Global Industrial Robotics Market size was valued at USD 19.74 Billion in 2025, and the total Industrial Robotics Market revenue is expected to grow by 11.67% from 2026 to 2034, reaching nearly USD 53.31 Billion by 2034
Industrial Robotics Market Overview
The Industrial Robotics Market encompasses the development, production, and deployment of industrial robots that automate manufacturing, assembly, material handling, welding, painting, packaging, and inspection processes across various industries. Industrial robots integrate advanced technologies such as artificial intelligence (AI), machine vision, sensors, and automation software to improve productivity, operational efficiency, precision, and workplace safety.
Industrial robots are automated, programmable robotic machines designed to carry out manufacturing processes with speed, precision, and safety. These robotic systems are vital in industries such as automotive, electronics, aerospace, food & beverage, chemicals, and general manufacturing, where demand for automation continues to rise. The industrial robotics market has been expanding rapidly, driven by automation adoption, increasing labor costs, and a shortage of skilled workers. Companies are investing in robotics solutions to reduce costs, enhance product quality, and increase production efficiency. With strong R&D investment, the market is advancing toward AI-powered robots, smart automation, and collaborative robots (cobots) that work safely alongside humans in production environments.
Asia Pacific is the leading region in the global Industrial Robotics Market, supported by its strong manufacturing base, high concentration of automotive and electronics production facilities, and increasing investments in industrial automation. Countries such as China, Japan, and South Korea drive regional demand through the widespread adoption of robotic systems in manufacturing operations.
Industrial Robot Market Growth Outlook
To know about the Research Methodology :- Request Free Sample Report
Industrial Robotics Market: Key Highlights
• Market Size: The global Industrial Robotics Market reaches USD 19.74 billion in 2025 and is projected to reach USD 53.31 billion by 2034, registering a CAGR of 11.67% during 2026–2034.
• Leading Region: Asia Pacific dominates the market, driven by strong manufacturing capabilities, expanding automotive and electronics industries, and increasing investments in industrial automation.
• Dominant Robot Type: Articulated robots hold the leading position due to their flexibility, payload capacity, and suitability for welding, assembly, material handling, and dispensing applications.
• Key Growth Driver: Increasing demand for automation, rising labor costs, shortages of skilled workers, and the need to improve productivity and product quality accelerate market growth.
• Technology Trends: AI-enabled robotics, machine vision, collaborative robots (cobots), autonomous mobile robots (AMRs), predictive maintenance, and Robotics-as-a-Service (RaaS) shape market development.
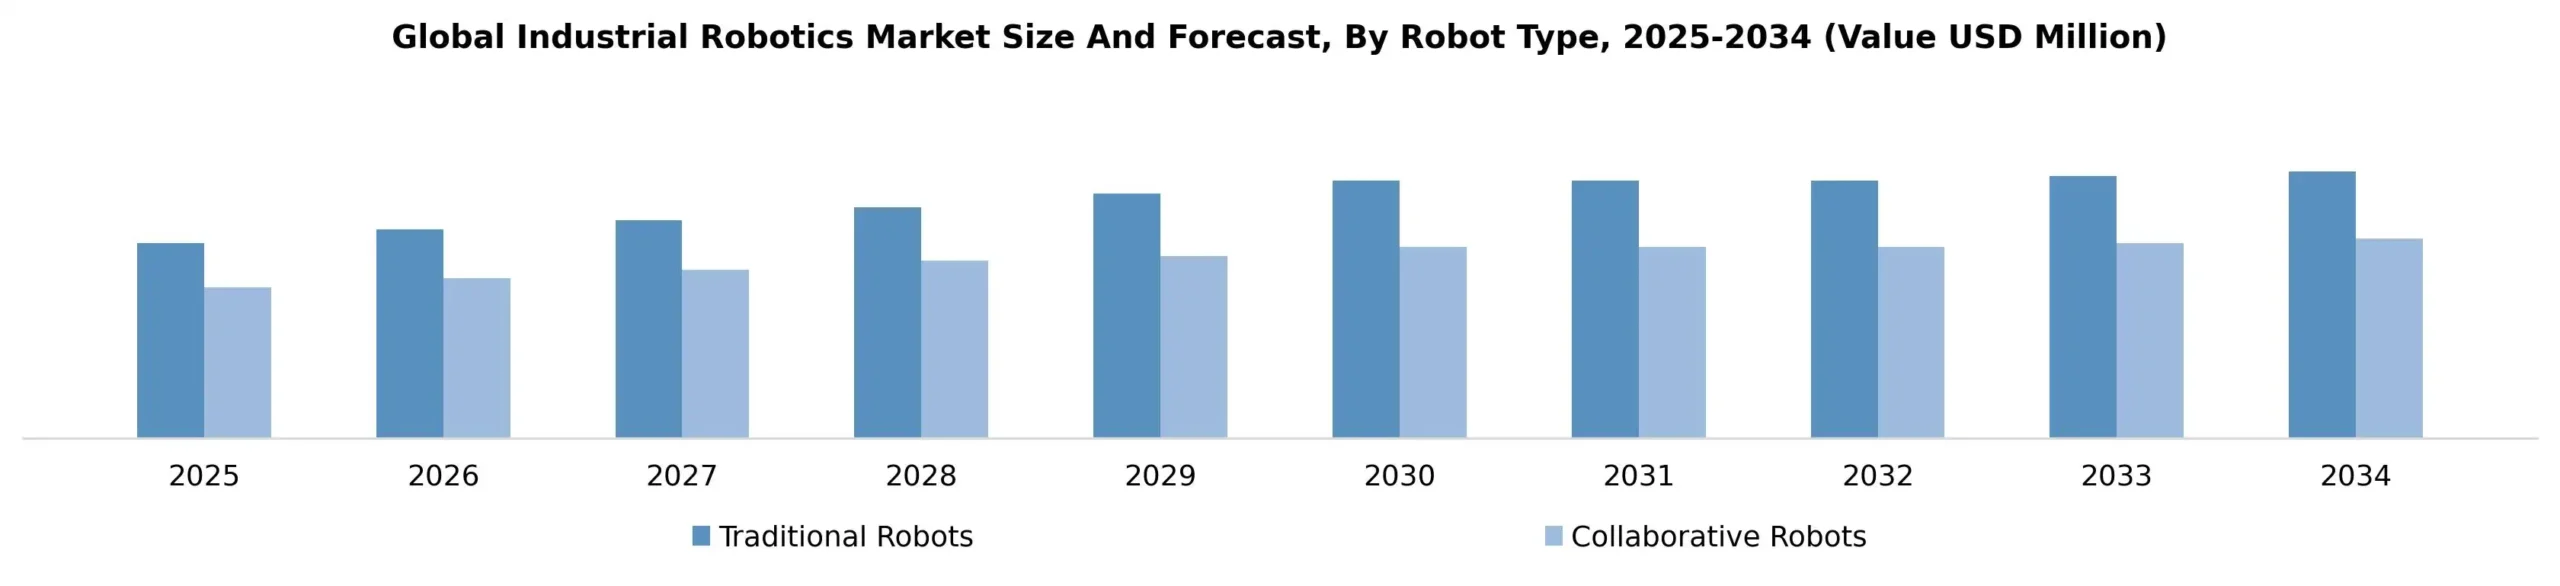
By Type, articulated robots dominate the industrial robotics market owing to their flexibility and wide range of applications. Other types include SCARA robots, Cartesian robots, and cylindrical robots, which are used for specialized functions. Key applications include welding and soldering, material handling, assembly and disassembly, painting and dispensing, milling, and processing. Leading industrial robotics companies such as ABB Ltd (Switzerland), FANUC Corporation (Japan), KUKA AG (Germany), and Yaskawa Electric Corporation (Japan) continue to dominate the competitive landscape through OEM partnerships, direct sales, and system integrators.
Industrial Robotics Market Dynamics
Industrial Robotics Market Driver
Growing Demand for Automation to Drive the Industrial Robotics Market: Companies increasingly adopt industrial robotics to reduce operating costs, improve productivity, enhance product quality, minimize human errors, and maintain competitiveness. Rising labor costs and shortages of skilled workers further accelerate the adoption of robotic automation across manufacturing industries. Increasing investments in research and development (R&D) also support the development of advanced industrial robots with artificial intelligence (AI), machine vision, and remote-monitoring capabilities.
Industrial Robotics Market Restraint
High Initial Investment and Installation Costs to Restrain the Industrial Robotics Market: The high costs of industrial robots, specialized hardware, software integration, installation, and ongoing maintenance limit market adoption, particularly among small and medium-sized enterprises (SMEs). Integrating robotic systems with existing production infrastructure also requires technical expertise and additional investment, which creates financial barriers for companies seeking to implement automation solutions.
Industrial Robotics Market Opportunity
Expansion into New Application Areas to Create Growth Opportunities: Increasing adoption of industrial robotics across food and beverages, electronics, pharmaceuticals, aerospace, agriculture, and logistics creates significant market opportunities. Emerging economies, particularly in Asia Pacific, South America, and the Middle East and Africa, offer strong growth potential through manufacturing expansion, smart factory initiatives, government support, and rising investments in industrial automation.
Industrial Robotics Market Challenge
Technical Complexity and Workforce Skill Gaps to Challenge Market Growth: The implementation and maintenance of industrial robotics systems require specialized skills in robotics programming, system integration, and troubleshooting. Compatibility issues with existing equipment, cybersecurity risks, operational disruptions during installation, and the need for employee training create challenges for companies adopting robotic automation. These factors can increase implementation time and operational costs.
Industrial Robotics Market Trend
Integration of AI, Machine Vision, and Collaborative Robots to Shape Market Trends: The Industrial Robotics Market increasingly incorporates AI-enabled robots, collaborative robots (cobots), autonomous mobile robots (AMRs), digital twins, and smart manufacturing technologies. Cloud connectivity, predictive maintenance, flexible automation, and Robotics-as-a-Service (RaaS) also gain traction by improving operational efficiency, minimizing downtime, and providing cost-effective automation solutions across diverse industries.
Industrial Robotics Market Segment Analysis
Based on Type, the Industrial Robotics Market is segmented into articulated, Cartesian, SCARA, cylindrical, and other types of industrial robots. The articulated robot’s segment is expected to hold the major Industrial Robotics Market share during the forecast period, owing to technological innovation, which has increased its flexibility to perform multiple functions and payload capability. Articulated robots are based on three rotary joints, thereby resembling movements similar to the human hand, and can be fixed or moving as per requirement.
These robots are able to operate in spherical space. These robots are highly advantageous in manufacturing industry for pick & assembly operations. An articulated robot can be used for various applications such as welding, material handling, & dispensing, among others. These robots can optimize warehouse operations through improved speed and accuracy, and are popular for their longevity.
Based on Payload, the Industrial Robotics Market is segmented into Up to 16 kg, 16 to 60 kg, 61 to 225 kg, and Above 225 kg. The 16 to 60 kg segment held the largest Industrial Robotics Market share in 2025 due to its versatility across a broad range of manufacturing applications. Robots within this payload range provide an optimal balance between lifting capacity, speed, and precision, making them suitable for assembly, machine tending, welding, packaging, and material handling operations. They are widely adopted across automotive, electronics, food & beverages, and metal fabrication industries where medium-duty automation is required. Increasing investments in flexible manufacturing systems and smart factories continue to drive demand for this payload category.
Based on Function, the industrial Robotics Market is segmented into soldering & welding; material handling, assembling & disassembling; painting & dispensing; milling, cutting, and processing; and others. Material handling was the largest segment by function, in terms of revenue, in the industrial robotics market in 2024. Currently, it accounts for over one-third of the global industrial Robotics Market and is expected to remain the largest segment during the forecast period, thanks to an increase in demand for industrial robots in the materials handling function.
All types of goods, including small, medium, and large, are stored in warehouses & manufacturing units in massive volumes. These goods are placed in large racks with heights and are navigated through the warehouse management system (WMS). To place and sort these goods, material handling is performed by robots. This has made the functioning faster, safer, and more productive. These factors drive the growth of this segment in the industrial robotics market.
Based on Offering, the Industrial Robotics Market is segmented into Hardware, System Engineering, Software & Programming, and Others. Hardware held the largest Industrial Robotics Market share in 2025, driven by the substantial investment required for robotic arms, end effectors, controllers, drive units, vision systems, sensors, and safety components. Hardware forms the foundation of every industrial robotic installation and represents the largest share of capital expenditure in automation projects. Growing adoption of advanced robotic systems across manufacturing facilities, coupled with continuous innovation in servo drives, machine vision, and end-of-arm tooling, continues to support the dominance of the hardware segment.
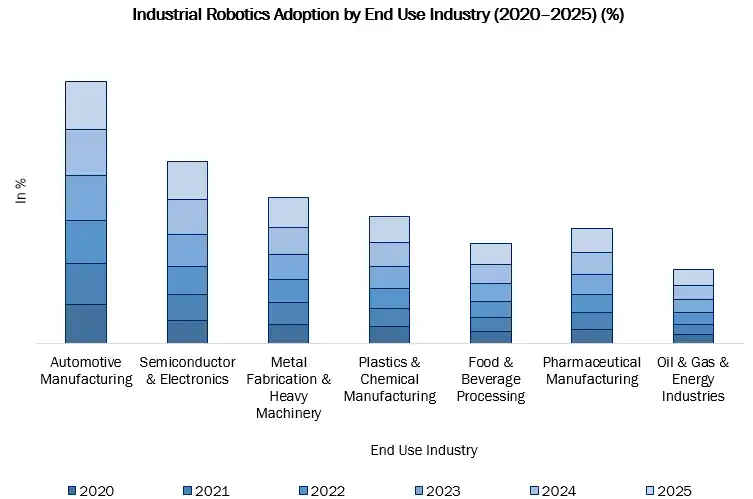
Based on End-Use Industry, the Industrial Robotics Market is segmented into Automotive, Electrical & Electronics, Metals & Machinery, Plastics, Rubber & Chemicals, Food & Beverages, Precision Engineering & Optics, Pharmaceuticals & Cosmetics, Oil & Gas, and Others. The Automotive segment held the largest Industrial Robotics Market share in 2025 due to its long-standing leadership in manufacturing automation. Automotive manufacturers extensively deploy industrial robots for welding, painting, assembly, machine tending, inspection, and material handling to improve production efficiency, product quality, and worker safety. The increasing production of electric vehicles, growing adoption of flexible manufacturing systems, and continuous investments in smart factories further reinforce the automotive industry's position as the largest consumer of industrial robotics globally.
Based on Application, the Industrial Robotics Market is segmented into Handling, Assembling & Disassembling, Welding & Soldering, Dispensing, Processing, Cleanroom, and Others. Handling held the largest Industrial Robotics Market share in 2025 owing to the growing automation of material movement across manufacturing and warehouse environments. Handling applications, including pick-and-place, material handling, packaging, and palletizing, require high-speed and repetitive operations that industrial robots perform with exceptional precision and consistency. Rising e-commerce activities, increasing warehouse automation, and the need to improve production efficiency while reducing labor costs continue to accelerate demand for robotic handling systems worldwide.
Industrial Robotics Market Regional Insights
Technological advancements, particularly in the developing regions of Asia-Pacific and South America, and Middle East, and Africa, coupled with increased investments in education and research infrastructure across the regions, propel the industrial robotics market.
In addition, the increase in demand for renewed and optimized robots, especially in North America and Europe, and rapid growth in the food and beverage industry, thanks to lifestyle changes worldwide, promote the development of the industrial robotics market. The Asia-Pacific dominance in the Industrial Robotics Market is expected to continue in the forecast period, followed by North America and Europe. Asia-Pacific is the most populous region, including countries such as China, India, Japan, Taiwan, and Australia, and has invested heavily in R&D activities, promoting the growth of the industrial robotics market. The end-user Asia-Pacific Industrial Robotics promotes the demand for plastic products and plastic materials in the market, and technological growth promotes development. Increase in adoption of automated systems in the growing food & beverage, logistics, pharmaceutical, and other sectors; improved & safe working conditions; and technological advancements foster the demand for packaging robots in this region. The Indian government emphasizes safety and security on the production floor, which accelerates the growth of the packaging robots market.
North America maintains a significant share of the Industrial Robotics Market, driven by increasing investments in factory automation, advanced manufacturing technologies, and smart production facilities. The United States leads the regional market due to its strong automotive, aerospace, electronics, pharmaceutical, and food and beverage industries, which increasingly adopt industrial robots for assembly, welding, material handling, packaging, and quality inspection.The growing adoption of collaborative robots, AI-enabled automation, and refurbished industrial robots further supports regional market development.
Europe represents an important region in the Industrial Robotics Market, supported by its established automotive industry, advanced engineering capabilities, and increasing emphasis on manufacturing efficiency. Germany leads regional demand through its strong automotive, machinery, electronics, and industrial automation sectors. The United Kingdom and France support market expansion through investments in aerospace, pharmaceutical manufacturing, food processing, and advanced robotics technologies. Italy and Spain demonstrate increasing adoption of industrial robots in automotive production, packaging, and metalworking, while Sweden and Austria benefit from advanced manufacturing infrastructure and automation expertise. The Rest of Europe contributes to market growth through industrial modernization, labor shortage mitigation, and increasing investments in smart factories, sustainable manufacturing, and collaborative robotic systems.
The Asia-Pacific dominance in the Industrial Robotics Market is expected to continue in the forecast period, followed by North America and Europe. Asia-Pacific is the most populous region, including countries such as China, India, Japan, Taiwan, and Australia, and has invested heavily in R&D activities, promoting the growth of the industrial robotics market. The end-user Asia-Pacific Industrial Robotics promotes the demand for plastic products and plastic materials in the market, and technological growth promotes development. Increase in adoption of automated systems in the growing food & beverage, logistics, pharmaceutical, and other sectors; improved & safe working conditions; and technological advancements foster the demand for packaging robots in this region. The Indian government emphasizes safety and security on the production floor, which accelerates the growth of the packaging robots market.
The Middle East and Africa Industrial Robotics Market experiences growth through industrial diversification, infrastructure development, and increasing investments in manufacturing automation. The GCC countries support adoption through investments in industrial facilities, logistics, petrochemicals, and advanced manufacturing as economies diversify beyond oil and gas. The Rest of ME&A supports future market expansion through growing industrial investment, although high equipment costs, limited technical expertise, and infrastructure constraints can slow adoption.
South America presents emerging growth opportunities in the Industrial Robotics Market as manufacturers increasingly adopt automation to improve productivity, product quality, and operational efficiency. Brazil leads regional demand through its automotive, food and beverage, agricultural processing, metalworking, and consumer goods industries. Increasing investments in manufacturing modernization and automated packaging systems support the adoption of industrial robots across production facilities. The Rest of South America offers additional opportunities through mining, logistics, packaging, and manufacturing applications. However, economic volatility, capital investment constraints, and shortages of skilled robotics professionals can limit the pace of market adoption across the region.
Industrial Robotics Market Competitive Landscape:
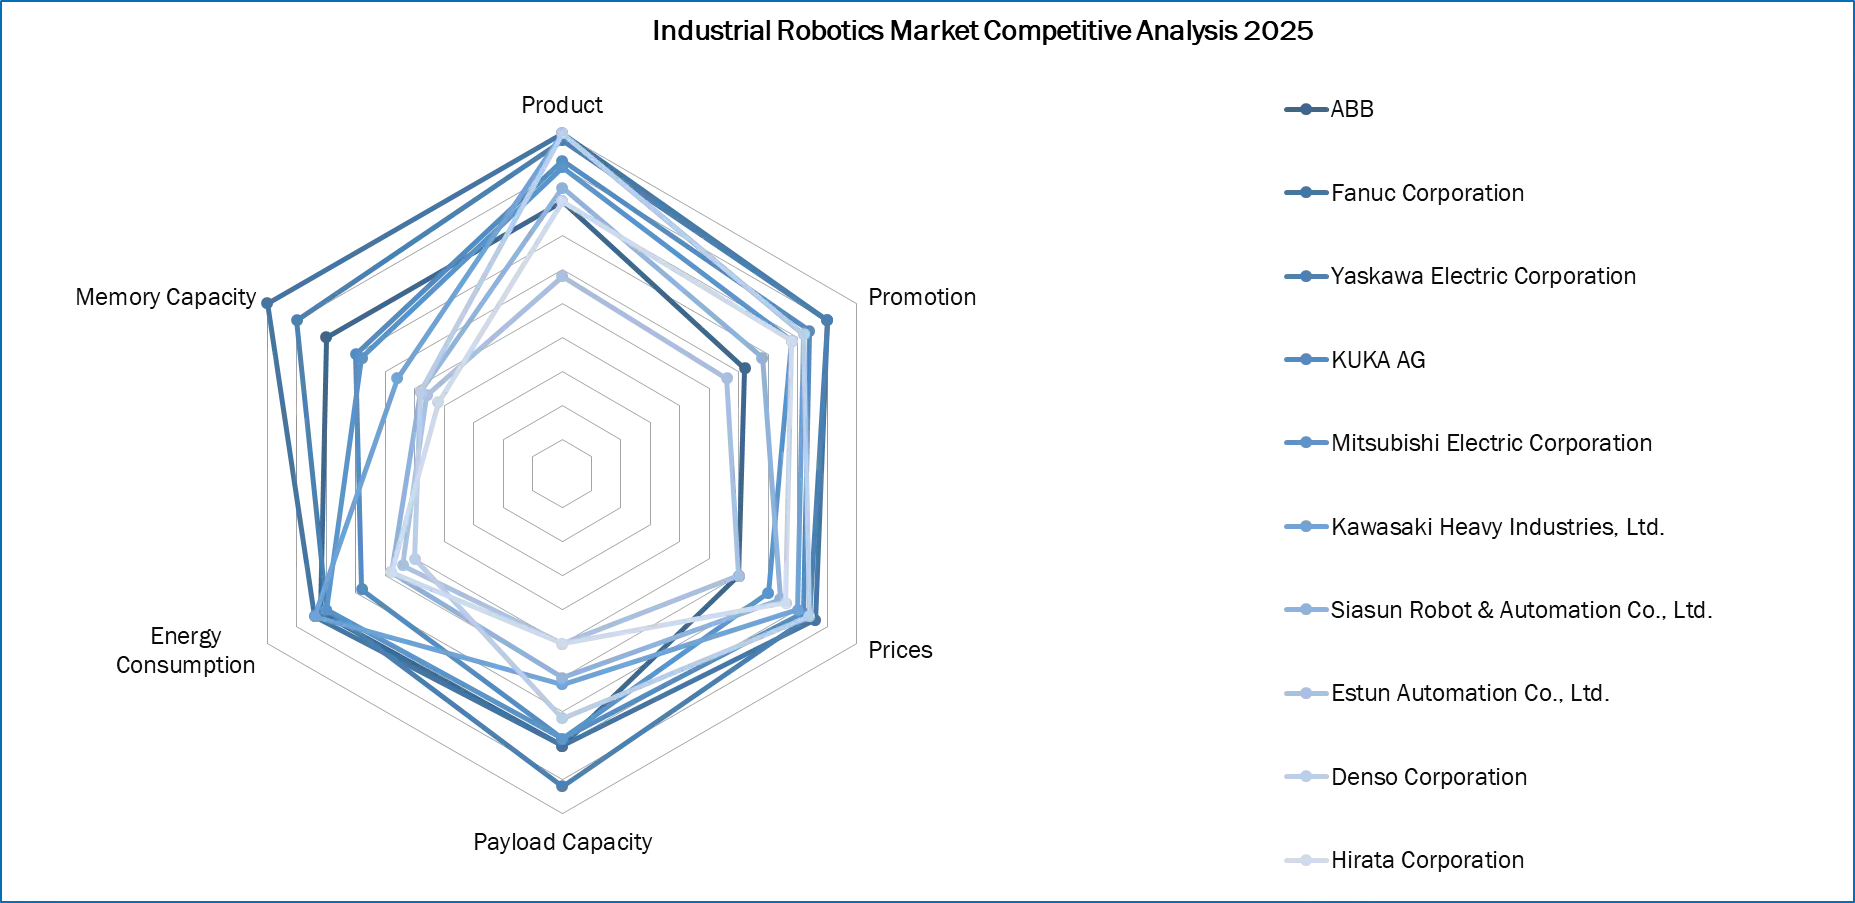
The industrial robots market consists of a mix of global industrial manufacturing corporations and automation specialists, with each manufacturer offering technological and innovative advantages. Many large companies have engineering expertise and market share, such as ABB Ltd. (Europe), and FANUC Corporation (Asia-Pacific). These two companies have very different ideas about how best to utilize robotics technology, and each offers a unique value proposition; ABB focuses on integrated automation systems and smart robotics, while FANUC offers the highest performance manufacturing robots with the broadest global reach.
ABB Ltd. is a dominant multinational player in industrial robots and a globally known company based in Switzerland that provides state-of-the-art automation solutions. ABB, with its heavy range of robots, has industry-best-in-class hardware equipment for nearly every global industry, including automotive, electronics, and logistics. A considerable point of differentiation for ABB is the global all-in-one automation ecosystem, since they are selling their hardware robotics equipment with their complete packaged software and digital services. ABB is still investing in the R&D of collaborative robots (cobots) that are AI-powered autonomous robots and integrated control systems. ABB partners closely with OEMs and system integrators to provide fully customizable automation solutions that can enhance both productivity and flexibility on the factory floor across a variety of sectors and is firmly established in Germany, North America, and Asia.
Industrial Robotics Market Key Developments:
| No. | Exact Date | Company | Key Development | Market Impact |
| 1 | 19 March 2026 | KUKA | Introduces the Automation Management Platform (AMP) at NVIDIA GTC 2026 to integrate physical AI into industrial automation. | Improves automation flexibility and supports AI-driven coordination of robots, production cells, and factory systems. |
| 2 | 22 April 2026 | ABB Robotics | Launches the PoWa collaborative robot family, offering payload capacities of 7–30 kg and speeds of up to 5.8 m/s for selected models. | Expands collaborative automation in machine tending, palletizing, welding, and manufacturing. |
| 3 | 13 February 2026 | Nikon | Announces an investment in Trener Robotics to accelerate AI-powered industrial automation and natural-language robot programming. | Simplifies robot programming and supports flexible automation of complex production tasks. |
| 4 | 14 September 2026 | Universal Robots | Unveils its Gen 7 robotics platform at IMTS 2026, designed for AI-ready industrial automation and physical AI deployment. | Supports advanced AI-powered applications and more adaptable industrial robotic operations. |
| 5 | 23 June 2026 | Kawasaki Robotics | Expands its collaboration with Dexterity to scale physical AI applications using its RL030N eight-degree-of-freedom robot arm platform. | Strengthens robotic automation for warehouse logistics, including trailer loading and unloading. |
| 6 | 8 January 2026 | International Federation of Robotics (IFR) | Publishes its top five global robotics trends for 2026, highlighting AI, technological innovation, and emerging business applications. | Highlights the growing role of intelligent robotics and advanced automation in industrial operations. |
Industrial Robotics Market Key Trends:
• AI-enabled Autonomy and Modular Robotics Platforms
Organizations, such as ABB, are producing significantly capable AI-enabled autonomy platforms (e.g., OBniCore) as well as autonomous versatile robots that can execute a number of tasks in a standalone fashion. This shows that there is a persistent pattern of significant advancements in intelligent, multi-use, adaptable, and energy-efficient robotic systems that can easily serve numerous industries that offer flexibility in application.
• Collaborating Growth in Humanoid and Specialized Robotics
The callback to launching investments in humanoid and specialized robots is seen in the rise of projects like Kawasaki’s AI-based robotic horse and the K-Humanoid Alliance in South Korea. This is yet another opportunity to launch collaboration that shows the interests of not only industry, but also, governments and academia to help accelerate innovation in humanlike and task-specific robots while expanding globally (i.e., Doosan robotics expanding to the growing European market).
Industrial Robotics Market Scope: Inquire before buying
| Industrial Robotics Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 19.74 USD Billion |
| Forecast Period 2026-2034 CAGR: | 11.67% | Market Size in 2034: | 53.31 USD Billion |
| Segments Covered: | by Robot Type | Articulated Robots SCARA Robots Cartesian (Gantry) Robots Delta (Parallel) Robots Collaborative Robots (Cobots) Mobile Robots (AMRs/AGVs) |
|
| by Payload | Low Payload (<10 kg) Medium Payload (10–100 kg) High Payload (>100 kg) |
||
| by Level of Automation | Pre-Programmed Robots Sensor-Based Adaptive Robots AI-Enabled / Intelligent Robots Collaborative Robots (Human-Robot Interaction) |
||
| by Application | Welding (Spot & Arc) Material Handling (Pick & Place, Palletizing) Assembly & Disassembly Painting & Coating Inspection & Quality Control Packaging & Labeling Additive Manufacturing Others |
||
| by End-Use Industry | Automotive Electrical & Electronics Food & Beverage Pharmaceuticals Metals & Machinery Plastics & Chemicals Logistics & Warehousing Aerospace & Defense Construction Others |
||
| by Component | Hardware Robot Arm / Manipulator End-Effector (Grippers, Tools) Sensors (Vision, Force, Proximity) Control System Robot Controllers PLC (Programmable Logic Controllers) Motion Control Systems Drives & Servo Motors Software Programming Software Simulation & Digital Twin Software AI & Machine Learning Systems Path Planning & Optimization Software |
||
Industrial Robotics Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Industrial Robotics Market, Key Players
Asia Pacific
1.FANUC Corporation
2.Yaskawa Electric Corporation (Motoman)
3.Kawasaki Heavy Industries (Kawasaki Robotics)
4.Seiko Epson Corporation (Epson Robots)
5.Denso Wave Inc.
6.Nachi-Fujikoshi Corp.
7.Mitsubishi Electric Corporation
8.Omron Corporation
9.Yamaha Motor Co., Ltd. (Robotics)
10.Kawada Robotics Corporation
11.Estun Automation Co., Ltd.
12.Siasun Robot & Automation Co., Ltd.
13.EFORT Intelligent Equipment Co., Ltd.
14.Shenzhen Inovance Technology Co., Ltd.
15.JAKA Robotics Co., Ltd.
16.AUBO Robotics
17.Elite Robot (Suzhou Elite Robot Co.)
18.Unitree Robotics Co., Ltd.
19.HD Hyundai Robotics
20.Doosan Robotics Inc.
21.Hanwha Robotics Co., Ltd.
22.Rainbow Robotics Co., Ltd.
23.Techman Robot Inc.
24.Delta Electronics, Inc. (Delta Robotics)
25.TAL Manufacturing Solutions Ltd. (Tata Motors)
Europe
26.ABB Ltd (Robotics & Discrete Automation)
27.KUKA AG
28.Stäubli International AG
29.Comau S.p.A.
30.Universal Robots A/S
31.Franka Robotics GmbH (Franka Emika)
32.Neura Robotics GmbH
33.Carl Cloos Schweisstechnik GmbH
34.Güdel Group AG
North America
35.Teradyne, Inc.
36.Standard Bots, Inc.
37.Lincoln Electric Automation
38.Genesis Systems Group
39.Vention Inc.
40.Precise Automation, Inc.
Others
Frequently Asked Questions:
Q1.What is the size of the Industrial Robotics Market?
Ans: The Industrial Robotics market was valued at USD 19.74 billion in 2025 and is projected to reach USD 53.31 billion by 2034, driven by AI advancements, automation demand, and global labor shortages.
Q2. What is the CAGR of Industrial Robotics Market?
Ans: The Industrial Robotics market is expected to grow at a CAGR of 11.67% during 2025–2034 due to increasing adoption across manufacturing, logistics, healthcare, and personal assistance applications.
Q3. Which region dominates Industrial Robotics Market?
Ans: Asia Pacific dominates the Industrial Robotics Market, driven by its strong manufacturing base, increasing adoption of factory automation, and significant investments in robotics technology.
Q4. Who are key players in Industrial Robotics Market?
Ans: The key players in the Industrial Robotics Market include ABB Ltd., FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, Mitsubishi Electric Corporation, Kawasaki Heavy Industries, Ltd., Denso Corporation, Omron Corporation, Seiko Epson Corporation, Nachi-Fujikoshi Corp., Universal Robots A/S, Stäubli International AG, Comau S.p.A., Delta Electronics