Helicopter Market Size by Type, Weight, Number of Engine, Application, Region – Segment-Level Market Assessment, Growth Opportunity Analysis, Competitive Mapping & Forecast to 2034

4.7%
CAGR (2026-2034)
34.9 USD Bn.
Forecast Market Size
307
Report Pages
155
Market Tables

Overview

The Helicopter Market size was valued at USD 34.90 Billion in 2025 and the total Helicopter revenue is expected to grow at a CAGR of 4.7% from 2026 to 2034, reaching nearly USD 52.76 Billion by 2034.

Helicopter Market Overview:

Looking ahead, the Helicopter Market is expected to continue consistent performance in, with stable deliveries hovering nearby the 500-unit mark. Despite continuing resolutions, supply chain issues may persist into 2025. Preceding the leased helicopter operations are North America and Europe, among a focus on offshore oil & gas, emergency medical services (EMS), and search and rescue roles. South America and Asia are also playing substantial roles in catering to this demand.

Helicopters are required for air ambulance services owing to their ability to reach remote areas faster than conventional automobiles and traditional aircraft. They can access distant, inaccessible places, like military bases deep in forests or oil rigs in the middle of the sea, within a short period. The early medical treatment of patients, permitted by quick emergency transport by helicopters, significantly increases the survival rate in serious cases.
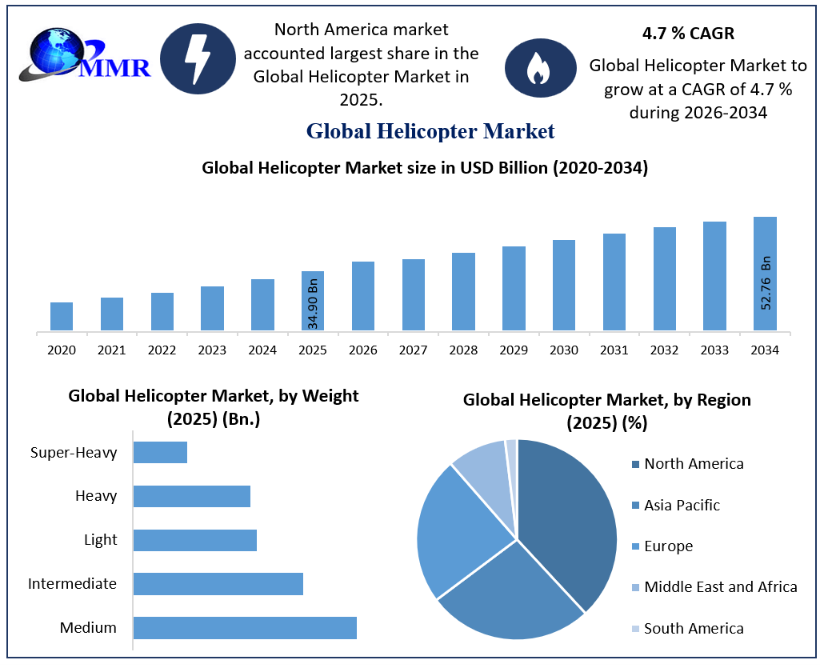
Helicopter Market Growth Outlook

To know about the Research Methodology :-Request Free Sample Report

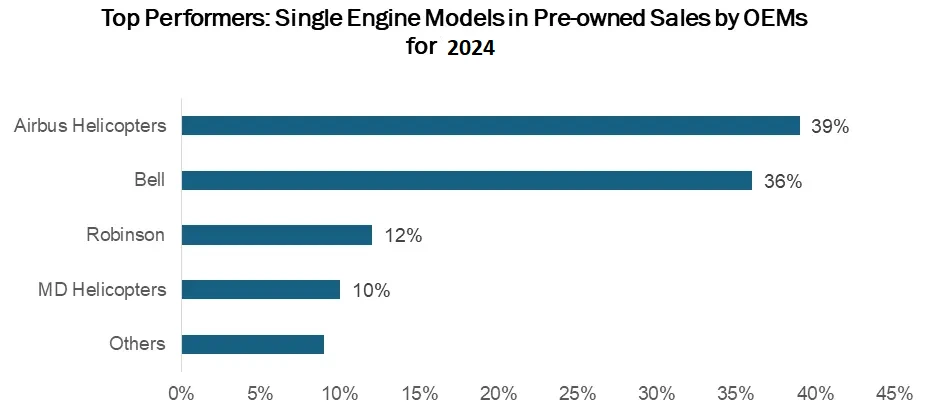
Airbus Helicopters Reports Robust Sales Growth in 2024:

Airbus Helicopters recorded 410 gross orders (net: 393), highlighting a steady recovery in the Helicopter Market with a strong performance for light twin and medium twin helicopters in . Orders were placed by 179 buyers across 47 countries. The company brought 346 helicopters in , resulting in a beginning 54% share of the civil and parapublic market.

In  “Airbus Helicopter’ order intake with an increase nearby 10% in units compared to , focuses its stable growth despite the ongoing global context of inflation and geopolitical instability, The was a year of many firsts for Airbus Helicopters, counting the first flight of the DisruptiveLab demonstrator featuring a new aerodynamic architecture pointed at reducing fuel feasting and the first flight of the NH90 Sea Tiger, a state-of-the-art anti-submarine warfare helicopter for the German Navy. Furthermore, the company welcomed a new member to the Airbus family with the Spanish Navy taking delivery of their first H135 helicopters.
Helicopter Market1

Helicopter Market Dynamics:

Helicopter Utilization in Military Applications on the Rise:

Military helicopters are most used to transport personnel, nonetheless they can also be modified for many additional duties, with being armed with weaponry to strike ground targets, conducting medical removal (MEDEVAC), serving as airborne command posts, or performing combat search & rescue (CSAR) missions. Governments of both developed and developing nations are enhancing investments in their military forces to found battlefield dominance and perform rescue missions with enhanced helicopters.
Such as, in June , Poland stated plans to purchase several AW149 military helicopters, joined by the Italian company Leonardo.

Moreover, in December , the French Armament General Directorate (DGA) signed a contract with Airbus Helicopters, a France-based company and one of the foremost helicopter manufacturers, for the growth and obtaining of the H160M as part of the Light Joint Helicopter Program (HIL). The contract contains the development of several prototypes and the delivery of the first batch of 30 aircraft, with 21 for the army, 8 for the navy, and 1 for the air force. The rise in adoption of helicopters by military forces is expected to drive the growth of the Helicopter Market.

Demand for Customized and Luxurious Helicopters in the Transportation Sector is Growing:

In recent years, helicopter air transportation has risen, with updated, expanded, and increased services. Speed is fundamental in helicopter air travel, driving heightened demand thanks to its efficiency and convenience. This growing demand is fueling growth in the Helicopter Market within the transportation sector.

Helicopters boast simpler take-off and landing operations compared to conventional aircraft, and they are unchanged by geographical constraints, making them ideal for short-distance travel and transportation. Furthermore, the introduction of luxurious helicopters by industry leaders for public transportation is poised to further stimulate Helicopter Market growth. Such as, Airbus launched the ACH160, a $14 million luxury helicopter devised for business or private use, helping up to 10 passengers in sept . The mounting demand for customized and luxurious helicopters, coupled with current innovations, is expected to drive robust growth in the global Helicopter Market during forecast period.


Helicopter Market Trends:

The integration of developed AI systems and automation capabilities in helicopters is a pivotal trend driving the growth of the Helicopter Market globally. Modern helicopters are now equipped with advanced sensors that increase accuracy and precision across various tasks. These advanced control systems confirm safe and reliable operation of these aerial vehicles.

Manufacturers have also started combining advanced features aimed at improving safety, efficiency, and versatility. Modern helicopter designs incorporate advanced automation capabilities, significantly reducing the need for manual labour and allowing personnel to focus on more critical tasks. Automation not only enhances efficiency but also minimizes errors, leading to quicker turnaround times at construction sites. Furthermore, helicopters consume less energy and produce fewer emissions compared to traditional ground-based cranes, making them an ecologically friendly choice for construction projects. The introduction of advanced technologies and automation capabilities has made helicopters more efficient, precise, and dependable, driving growth in the Helicopter Market throughout the forecast period.

Helicopter Market Segmentation Insight:

By Type, the Civil and Commercial segment held the largest Helicopter Market share of about 65% for the Helicopter Market in 2025 and is expected to dominate the market at the end of the forecast period. The growth is driven by growing need for emergency services and a rising need for air transportation. The demand for quick transportation and efficient grows as the population raises and urban areas expand.
The military segment is expected to grow moderately over 2026-2034. The Helicopter Market is growing as an aging fleet is replaced and modernized, including increased use in disaster relief and humanitarian missions.
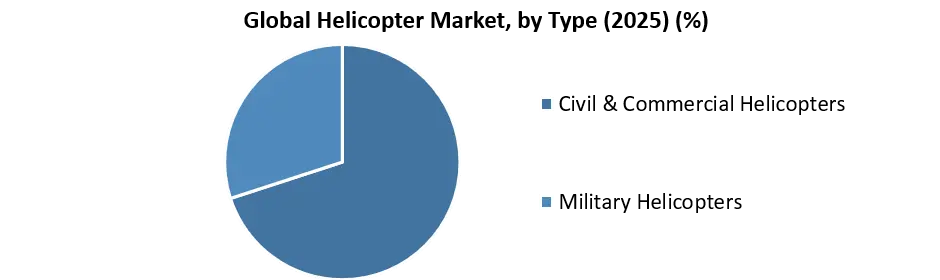
Helicopter market by Type


By Weight, The global helicopter market is segmented by weight class into light, intermediate, medium, heavy, and super-heavy/heavy-lift helicopters. Light helicopters are widely used for pilot training, private transport, aerial observation, emergency medical services, and law enforcement. Intermediate helicopters support utility operations, corporate transportation, and regional missions. Medium helicopters serve military transport, offshore oil and gas, search and rescue, and public safety applications. Heavy helicopters handle demanding cargo transport, military logistics, and industrial operations, while super-heavy/heavy-lift helicopters are designed for oversized cargo, heavy construction, and specialized military missions. Demand across these categories depends on payload capacity, operating range, mission requirements, and fleet modernization.

Helicopter Market Regional Insight:

Geographically, North America held the largest market share of about xx% in 2025 for the Helicopter Market and is expected to dominate the market at the end of the forecast period. This dominance is attributed to the U.S. having the largest helicopter fleet and a raising reliance on helicopters for air ambulance services. The U.S. presently operates a fleet of nearly 7,014 helicopters, with over 1,000 dedicated to air ambulance duties. The increase in demand for helicopter services is further propelled by the developing offshore wind farm projects across the country, driven by developing demands for cleaner and more viable energy sources. This has led to a surge in new contracts and partnerships, substantially boosting Helicopter Market value.

For example, Orsted and Eversource awarded HeliService International Inc. a contract for helicopter crew changes operations for their joint offshore wind projects in the Northeast United States in . Using Leonardo AW169 helicopters, this agreement underscores the industry's response to developing offshore activity. Furthermore, the uptick in revenue from the oil & gas sector has directly correlated with enhanced demand for helicopter services in offshore operations. Conversely, the influx of private equity investors into the air ambulance industry, aimed at improving service quality, also poses challenges like potential increases in operational costs passed on to customers. Also, across Canada, rising demands for helicopters span various applications with emergency medical services, search and rescue operations, leisure charters, and more, contributing to regional Helicopter Market growth.

Developments in the Helicopter Market by Key Industry Players:

1. Vertical Aerospace and Rolls-Royce: Signed a partnership agreement in July 2023 to jointly develop and certify an electric vertical takeoff and landing (eVTOL) aircraft for urban air mobility applications.

2. Cicare USA: Announced in July 2023 that its Cicare 8 helicopter had received certification under the LTF-ULH regulations for ultralight helicopters, applicable to helicopters with a maximum take-off weight under 600 kg or 1320 lbs.

3. Leonardo Helicopters and Collins Aerospace: Collaborated on a digital solutions project for helicopter health and usage monitoring, enhancing maintenance efficiency and safety, announced in August 2023.

Helicopter Market Scope: Inquiry Before Buying

Helicopter Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 34.90 Bn.
Forecast Period 2026 to 2034 CAGR: 4.7% Market Size in 2034: USD 52.76 Bn.
Segments Covered: by Type Civil & Commercial Helicopters
Military Helicopters
by Propulsion Type Turboshaft
Piston
Hybrid-Electric
Fully Electric
Others
by Engine Configuration Single-Engine
Twin-Engine
Multi-Engine
by Weight Class Light
Intermediate
Medium
Heavy
Super-Heavy/Heavy-Lift
by Ownership Model Direct Ownership
Leasing
by Sales Type New Helicopter Sales
Pre-Owned Helicopter Sales
by Application Passenger Transport & Charter
Emergency Medical Services
Search & Rescue
Law Enforcement & Public Safety
Firefighting
Offshore Oil & Gas Support
Construction & Heavy-Lift Operations
Agriculture
Tourism & Sightseeing
Aerial Survey, Inspection & Observation
Military & Defense Operations
Others

Helicopter Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Helicopter Market, Key Players:

North America
1.Bell Textron Inc.
2.Sikorsky Aircraft Corporation
3.The Boeing Company
4.Robinson Helicopter Company
5.MD Helicopters LLC
6.Kaman Corporation
7.Enstrom Helicopter Corporation
8.Erickson Incorporated
9.Schweizer RSG, LLC
10.Airbus Helicopters SAS
11.Leonardo S.p.A.
12.JSC Russian Helicopters / Rostec
13.Hélicoptères Guimbal SAS
14.Kopter Group AG

Europe
1.Airbus Helicopters SAS
2.Leonardo S.p.A.
3.JSC Russian Helicopters / Rostec
4.Hélicoptères Guimbal SAS
5.Kopter Group AG
6.Kazan Helicopters
7.Mil Moscow Helicopter Plant
8.Kamov Design Bureau
9.Dynali Helicopter Company
10.Curti Aerospace
11.CH7 Helisport
12.Konner Helicopters
13.Fama Helicopters

Asia-Pacific
1.Hindustan Aeronautics Limited (HAL)
2.Kawasaki Heavy Industries, Ltd.
3.Korea Aerospace Industries (KAI)
4.Aviation Industry Corporation of China (AVIC)
5.Changhe Aircraft Industries Group
6.Harbin Aircraft Industry Group
7.Mitsubishi Heavy Industries, Ltd.
8.Subaru Corporation
9.PT Dirgantara Indonesia
10.Motor Sich JSC
11.Indian Rotorcraft Limited
12.Brantly International

Middle East & Africa
1.Turkish Aerospace Industries (TAI)
2.Denel Aeronautics / Denel SOC Ltd.
3.Gulf Helicopters Company

South America
1.Helibras / Airbus Helicopters Brasil
2.Cicaré Helicópteros
Others

FAQs:
1] What segments are covered in the Global Helicopter Market report?
Ans. The segments covered in the Helicopter Market report are based on Type, Wight, Engine Configuration, Application and Region.

2] Which region is expected to hold the highest share in the Global Helicopter Market?
Ans. North America region is expected to hold the highest share of the Helicopter Market.

3] What is the market size of the Global Helicopter Market by 2034?
Ans. The market size of the Helicopter Market by 2034 is expected to reach USD 52.76 Bn.

4] What is the forecast period for the Global Helicopter Market?
Ans. The forecast period for the Helicopter Market is 2026-2034.

5] What was the Global Helicopter Market size in 2025?
Ans:
The Global Helicopter Market size was USD 34.90 Billion in 2025.

Table of Contents

1. Executive Helicopter Market Landscape & Industry Overview 1.1 Global Helicopter Market Size (Value USD Mn & Volume in Units), 2026–2034 1.2 Civil and military helicopter demand across major regions 1.3 Fleet modernization driven by aging aircraft replacement requirements 1.4 Helicopter utilization across commercial and specialized missions 1.5 Production trends among leading helicopter original equipment manufacturers 1.6 Market growth influenced by defense and commercial aviation 1.7 CAGR Analysis Helicopter Market (2025–2034) 2. Global Helicopter Market Dynamics 2.1 Market Trends 2.2 DROC Analysis 2.3 Drivers 2.4 Restraints 2.5 Opportunities 2.6 Challenges 2.7 PORTER'S Five Forces 2.8 PESTLE Analysis 3. Helicopter Acquisition Cost, Economics & Pricing Dynamics 3.1 Purchase price differences across helicopter classes and configurations 3.2 Operating costs by mission profile and aircraft category 3.3 Maintenance expenses influencing total helicopter ownership economics 3.4 Leasing structures supporting commercial fleet acquisition requirements 3.5 Resale values across major helicopter models globally 3.6 Revenue economics across passenger, utility, and specialized operations 4. Helicopter Manufacturing Supply Chain & Component Ecosystem 4.1 Procurement networks supporting helicopter manufacturing and final assembly 4.2 Availability of engines, avionics, rotors, and transmissions 4.3 Supplier dependencies across critical aerospace component categories 4.4 Long-lead components affecting helicopter production delivery schedules 4.5 Tier-one and tier-two aerospace supplier ecosystem analysis 4.6 Localization strategies across emerging helicopter manufacturing regions 5. Helicopter Demand Analysis by Mission Requirements 5.1 Passenger transport requirements across corporate and commercial operators 5.2 Offshore transportation demand from energy industry operations 5.3 Emergency medical missions requiring specialized helicopter configurations 5.4 Search-and-rescue operations driving mission-ready fleet requirements 5.5 Utility operations supporting infrastructure and remote-area access 5.6 Defense missions influencing tactical helicopter procurement globally 6. Helicopter Configuration, Design & Airframe Development 6.1 Airframe configurations optimized for specific mission requirements 6.2 Single-engine and twin-engine architecture adoption patterns 6.3 Cabin layouts supporting passenger, cargo, and medical missions 6.4 Lightweight materials improving helicopter payload and efficiency 6.5 Modular cabin systems enabling rapid mission reconfiguration 6.6 Aerodynamic design improvements enhancing helicopter performance characteristics 7. Helicopter Engine, Rotor & Propulsion Technology Evolution 7.1 Turboshaft engine selection across helicopter performance requirements 7.2 Engine power ratings influencing payload and range capabilities 7.3 Main rotor configurations affecting lift and maneuverability 7.4 Tail rotor technologies improving directional control and safety 7.5 Composite rotor blades reducing weight and maintenance requirements 7.6 Hybrid-electric propulsion research targeting future helicopter applications 8. Avionics, Flight Controls & Navigation Systems 8.1 Glass cockpit adoption across modern helicopter platforms 8.2 Flight management systems improving navigation and operational efficiency 8.3 Digital engine controls optimizing powerplant performance and monitoring 8.4 Synthetic vision supporting low-visibility helicopter flight operations 8.5 Advanced autopilot systems reducing pilot workload during missions 8.6 Satellite navigation integration enabling precision helicopter operations 9. Helicopter Safety, Certification & Airworthiness Systems 9.1 Type certification requirements governing helicopter market entry 9.2 Airworthiness directives influencing fleet maintenance and modifications 9.3 Crashworthiness standards shaping airframe and cabin design 9.4 Emergency flotation systems supporting offshore helicopter safety 9.5 Health monitoring technologies improving component failure detection 9.6 Operator safety management systems reducing mission-related accident risks 10. Helicopter Maintenance, Repair & Overhaul Ecosystem 10.1 Preventive maintenance schedules across commercial helicopter fleets 10.2 Engine overhaul requirements influencing lifecycle operating costs 10.3 Component repair networks supporting global fleet availability 10.4 Maintenance tracking systems improving aircraft serviceability management 10.5 Spare-parts availability affecting helicopter operational continuity 10.6 Predictive maintenance technologies reducing unscheduled maintenance events 11. Helicopter Fleet Utilization, Operations & Mission Economics 11.1 Annual flight hours across major helicopter operator categories 11.2 Fleet utilization differences between commercial and military missions 11.3 Mission duration influencing operating cost and aircraft selection 11.4 Dispatch reliability affecting operator productivity and revenue generation 11.5 Crew requirements influencing helicopter operational economics 11.6 Fleet scheduling optimization across geographically dispersed operations 12. Civil Helicopter Applications & Commercial Operations 12.1 Corporate transportation demand across executive aviation operators 12.2 Tourism operations utilizing helicopters for premium sightseeing experiences 12.3 Charter services supporting regional passenger transportation requirements 12.4 Helicopter emergency medical services across developed markets 12.5 Utility aviation supporting construction, forestry, and infrastructure 12.6 News gathering and aerial filming helicopter applications 13. Military Helicopter Applications & Defense Procurement 13.1 Attack helicopter procurement supporting battlefield strike capabilities 13.2 Transport helicopters enabling tactical troop and equipment mobility 13.3 Reconnaissance helicopters supporting surveillance and battlefield intelligence 13.4 Naval helicopters performing maritime patrol and anti-submarine missions 13.5 Search-and-rescue helicopters supporting military recovery operations 13.6 Modernization programs replacing aging military helicopter fleets 14. Helicopter Fleet Base, Helipad Infrastructure & Air Traffic (2025) 14.1 Global helicopter fleet distribution across major operating regions 14.2 Civil and military helicopter fleet composition patterns 14.3 Helicopter fleet age and replacement requirements 14.4 Global helipad infrastructure supporting helicopter operations 14.5 Helipad distribution across urban and remote locations 14.6 Air traffic activity influencing helicopter operational capacity 14.7 Airspace integration requirements for helicopter operations 15. Helicopter Trade Flow, Distribution & Regional Connectivity 15.1 Helicopter exports across major manufacturing and operating countries 15.2 Import dependency patterns across emerging aviation markets 15.3 International distribution networks supporting helicopter deliveries 15.4 Cross-border logistics for aircraft and replacement components 15.5 Regional maintenance hubs supporting international helicopter operators 15.6 Geopolitical factors influencing helicopter trade and deliveries 16. Helicopter Leasing, Financing & Ownership Structures 16.1 Operating leases supporting commercial helicopter fleet expansion 16.2 Finance leasing structures for aircraft acquisition programs 16.3 Manufacturer-backed financing supporting helicopter purchasing decisions 16.4 Fractional ownership models across corporate helicopter operations 16.5 Government financing supporting military helicopter procurement programs 16.6 Used helicopter transactions influencing secondary-market development 17. Helicopter Regulatory Framework & Operational Compliance 17.1 Civil aviation regulations governing helicopter commercial operations 17.2 Military procurement regulations affecting defense helicopter acquisitions 17.3 Pilot licensing requirements influencing operator workforce availability 17.4 Noise regulations affecting helicopter operations near populated areas 17.5 Maintenance certification requirements governing repair organizations globally 17.6 Import controls affecting international helicopter market participation 18. Helicopter Technology Innovation, SAF & Future Development 18.1 Autonomous flight technologies transforming future helicopter operations 18.2 Advanced composite technologies improving airframe efficiency 18.3 Sustainable aviation fuel adoption across helicopter platforms 18.4 SAF compatibility with existing helicopter engine architectures 18.5 Hybrid-electric propulsion development for future helicopter platforms 18.6 Artificial intelligence supporting predictive flight and maintenance 18.7 Advanced rotor systems improving efficiency and performance 19. Helicopter Sustainability, Electrification & Emissions Reduction 19.1 Sustainable aviation fuel adoption across helicopter operators 19.2 Fuel-efficient engines reducing helicopter lifecycle emissions 19.3 Hybrid-electric propulsion development for future helicopter platforms 19.4 Lightweight materials reducing fuel consumption during operations 19.5 Carbon reporting requirements influencing operator fleet strategies 19.6 Electrification opportunities across short-range helicopter missions 20. Helicopter Market Risks, Resilience & Supply Continuity 20.1 Supply disruptions affecting engines and critical components 20.2 Skilled technician shortages constraining helicopter maintenance capacity 20.3 Geopolitical tensions disrupting international aircraft supply chains 20.4 Economic downturns reducing discretionary helicopter utilization 20.5 Regulatory changes affecting fleet operations and acquisitions 20.6 Business continuity strategies supporting critical helicopter missions 21. Helicopter Aftermarket, Spare Parts & Service Support 21.1 Genuine spare-parts demand across active helicopter fleets 21.2 Independent aftermarket competition across replacement component categories 21.3 Component availability affecting aircraft maintenance turnaround times 21.4 Service contracts supporting long-term operator maintenance requirements 21.5 Technical support networks influencing manufacturer customer retention 21.6 Digital parts platforms improving aftermarket procurement efficiency 22. Helicopter Investment & Government Policies 22.1 Government investment supporting helicopter fleet modernization 22.2 Defense spending influencing military helicopter procurement 22.3 Public funding for emergency helicopter services 22.4 Infrastructure investment supporting helipad development 22.5 Government incentives accelerating low-emission helicopter technologies 22.6 Aviation policies influencing helicopter industry investments 22.7 Public-private partnerships expanding helicopter aviation infrastructure 22.8 Government procurement policies supporting domestic helicopter manufacturing 23. Global Helicopter Market Size and Forecast by Segmentation (by Value USD Million and Volume in Units) (2025-2034) 23.1 Global Helicopter Market Size And Forecast, By Type 23.1.1 Civil & Commercial Helicopters 23.1.2 Military Helicopters 23.2 Global Helicopter Market Size And Forecast, By Propulsion Type 23.2.1 Turboshaft 23.2.2 Piston 23.2.3 Hybrid-Electric 23.2.4 Fully Electric 23.2.5 Others 23.3 Global Helicopter Market Size And Forecast, By Engine Configuration 23.3.1 Single-Engine 23.3.2 Twin-Engine 23.3.3 Multi-Engine 23.4 Global Helicopter Market Size And Forecast, By Weight Class 23.4.1 Light 23.4.2 Intermediate 23.4.3 Medium 23.4.4 Heavy 23.4.5 Super-Heavy/Heavy-Lift 23.5 Global Helicopter Market Size And Forecast, By Ownership Model 23.5.1 Direct Ownership 23.5.2 Leasing 23.6 Global Helicopter Market Size And Forecast, By Application 23.6.1 Passenger Transport & Charter 23.6.2 Emergency Medical Services 23.6.3 Search & Rescue 23.6.4 Law Enforcement & Public Safety 23.6.5 Firefighting 23.6.6 Offshore Oil & Gas Support 23.6.7 Construction & Heavy-Lift Operations 23.6.8 Agriculture 23.6.9 Tourism & Sightseeing 23.6.10 Aerial Survey, Inspection & Observation 23.6.11 Military & Defense Operations 23.6.12 Others 23.7 Global Helicopter Market Size And Forecast, By Sales Type 23.7.1 New Helicopter Sales 23.7.2 Pre-Owned Helicopter Sales 23.8 Global Helicopter Market Size and Forecast, By Region & Country 23.8.1 North America 23.8.1.1 United States 23.8.1.2 Canada 23.8.1.3 Mexico 23.8.2 Europe 23.8.2.1 United Kingdom 23.8.2.2 France 23.8.2.3 Germany 23.8.2.4 Italy 23.8.2.5 Spain 23.8.2.6 Sweden 23.8.2.7 Russia 23.8.2.8 Rest of Europe 23.8.3 Asia Pacific 23.8.3.1 China 23.8.3.2 South Korea 23.8.3.3 India 23.8.3.4 Japan 23.8.3.5 Australia 23.8.3.6 Indonesia 23.8.3.7 Philippines 23.8.3.8 Malaysia 23.8.3.9 Vietnam 23.8.3.10 Thailand 23.8.3.11 Rest of Asia Pacific 23.8.4 Middle East & Africa 23.8.4.1 South Africa 23.8.4.2 Saudi Arabia 23.8.4.3 United Arab Emirates 23.8.4.4 Qatar 23.8.4.5 Kuwait 23.8.4.6 Bahrain 23.8.4.7 Oman 23.8.4.8 Egypt 23.8.4.9 Nigeria 23.8.4.10 Rest of Middle East & Africa 23.8.5 South America 23.8.5.1 Brazil 23.8.5.2 Argentina 23.8.5.3 Chile 23.8.5.4 Colombia 23.8.5.5 Rest of South America 24. Helicopter Market Competitive Landscape 24.1 Competitive Matrix 24.2 Key Player Benchmarking 24.2.1 Company Name 24.2.2 Headquarters 24.2.3 Helicopter Product Portfolio 24.2.4 Rotorcraft Design & Engineering 24.2.5 Propulsion System Technology 24.2.6 Avionics & Flight Control Systems 24.2.7 Mission Capability & Configuration 24.2.8 Manufacturing & Production Capacity 24.2.9 Safety & Certification Standards 24.2.10 Aftermarket Service & Support Network 24.2.11 Revenue 24.2.12 Market Share 24.2.13 R&D Investment 24.2.14 Operating Margin 24.2.15 Year-on-Year Growth 24.2.16 Geographic Presence 24.3 Market Structure 24.3.1 Market Leaders 24.3.2 Market Followers 24.3.3 Emerging Players 24.4 Mergers & Acquisitions Details 24.5 Recent Key Developments 25. Company Profiles: Key Players 25.1 Overview 25.2 Business Portfolio 25.3 Financial Overview 25.4 SWOT Analysis 25.5 Strategic Analysis 25.6 Recent Developments 26. Global Helicopter Market Company Profiles: 40+ Key Players 26.1 Bell Textron Inc. 26.2 Sikorsky Aircraft Corporation 26.3 The Boeing Company 26.4 Robinson Helicopter Company 26.5 MD Helicopters LLC 26.6 Kaman Corporation 26.7 Enstrom Helicopter Corporation 26.8 Erickson Incorporated 26.9 Schweizer RSG, LLC 26.10 Airbus Helicopters SAS 26.11 Leonardo S.p.A. 26.12 JSC Russian Helicopters / Rostec 26.13 Hélicoptères Guimbal SAS 26.14 Kopter Group AG 26.15 Kazan Helicopters 26.16 Mil Moscow Helicopter Plant 26.17 Kamov Design Bureau 26.18 Dynali Helicopter Company 26.19 Curti Aerospace 26.20 CH7 Helisport 26.21 Konner Helicopters 26.22 Fama Helicopters 26.23 Hindustan Aeronautics Limited (HAL) 26.24 Kawasaki Heavy Industries, Ltd. 26.25 Korea Aerospace Industries (KAI) 26.26 Aviation Industry Corporation of China (AVIC) 26.27 Changhe Aircraft Industries Group 26.28 Harbin Aircraft Industry Group 26.29 Mitsubishi Heavy Industries, Ltd. 26.30 Subaru Corporation 26.31 PT Dirgantara Indonesia 26.32 Motor Sich JSC 26.33 Indian Rotorcraft Limited 26.34 Brantly International 26.35 Turkish Aerospace Industries (TAI) 26.36 Denel Aeronautics / Denel SOC Ltd. 26.37 Gulf Helicopters Company 26.38 Helibras / Airbus Helicopters Brasil 26.39 Cicaré Helicópteros 26.40 Others 27. Helicopter Fleet & Product Portfolio Benchmarking 27.1 Fleet size comparison among leading helicopter operators 27.2 Aircraft model diversity across manufacturer portfolios 27.3 Civil versus military product portfolio positioning 27.4 Light, medium, and heavy helicopter portfolio comparison 27.5 Mission-specific aircraft capability benchmarking across competitors 27.6 New aircraft programs and development pipeline comparison 28. Helicopter Technology & Performance Benchmarking 28.1 Engine power and performance capability comparison 28.2 Maximum payload and range benchmarking across models 28.3 Avionics and cockpit technology comparison 28.4 Rotor technology and aerodynamic performance benchmarking 28.5 Flight-control automation capabilities across competing helicopters 28.6 Safety and survivability technology comparison 29. Manufacturing, Production & Supply Chain Benchmarking 29.1 Production capacity across leading helicopter manufacturers 29.2 Assembly facility locations and regional manufacturing footprints 29.3 Critical component sourcing strategies among manufacturers 29.4 Supplier diversification across engines and avionics 29.5 Production backlog and delivery performance comparison 29.6 Localization strategies across emerging manufacturing markets 30. Aftermarket, Maintenance & Service Benchmarking 30.1 Global maintenance network coverage among manufacturers 30.2 Authorized service center availability across operating regions 30.3 Spare-parts distribution capabilities and delivery performance 30.4 Maintenance contract offerings for major helicopter fleets 30.5 Training and technical support capabilities comparison 30.6 Digital maintenance solutions and predictive service adoption 31. Commercial Strategy & Customer Relationship Benchmarking 31.1 Pricing strategies across comparable helicopter models 31.2 Financing and leasing support offered to customers 31.3 Customer segmentation across civil and defense operators 31.4 Long-term service agreements supporting customer retention 31.5 Distributor networks supporting regional market penetration 31.6 Fleet modernization partnerships with major operators 32. Financial & Investment Benchmarking 32.1 Revenue comparison among leading helicopter manufacturers 32.2 Helicopter segment profitability and operating-margin analysis 32.3 Research and development investment intensity comparison 32.4 Capital expenditure across production and facility expansion 32.5 Defense contract backlog and revenue visibility 32.6 Strategic acquisitions and investment activity comparison 33. Key Insights, Strategic Outlook & Methodological Framework 33.1 Key Findings 33.2 Strategic Moves & Industry Outlook 33.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements