Global Engineering Plastics Market by Type, By End-use Industry & Forecast to 2034

7.4%
CAGR (2026-2034)
125.10 USD Bn.
Forecast Market Size
324
Report Pages
162
Market Tables

Overview

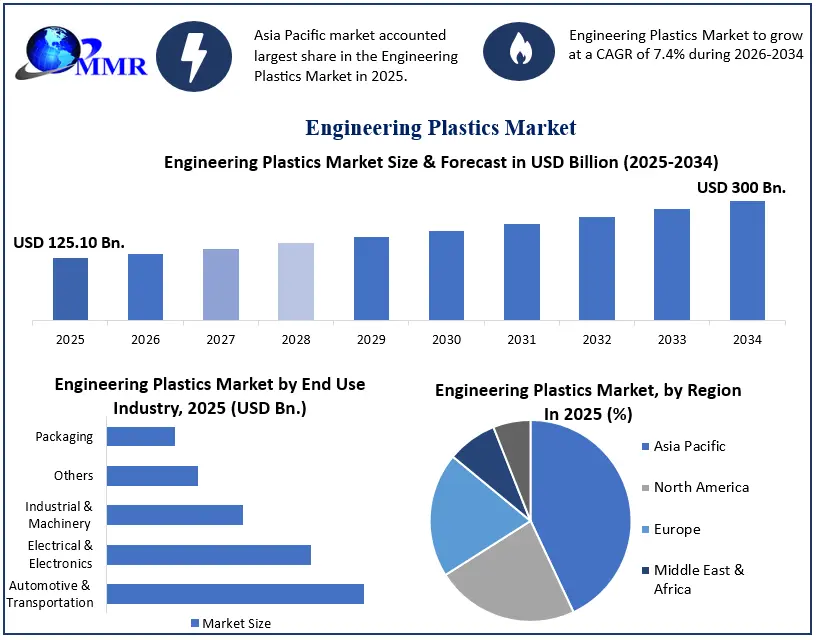
Global Engineering Plastics Market size was valued at USD 125.10 Bn. in 2025 and the total Global Engineering Plastics Market revenue is expected to grow at a CAGR of 7.4% from 2025 to 2034, reaching nearly USD 300 Bn. by 2034.
Global Engineering Plastics Market Overview:

The Global Engineering Plastics Market is witnessing strong growth, driven by increasing demand for lightweight, high-performance materials across the automotive, electrical & electronics, industrial machinery, healthcare, aerospace, and consumer goods industries. Engineering plastics offer superior mechanical strength, heat resistance, chemical resistance, dimensional stability, and electrical insulation compared to conventional plastics, making them ideal substitutes for metals and other traditional materials in demanding applications. Rapid industrialization, increasing production of electric vehicles (EVs), rising miniaturization of electronic devices, and the growing emphasis on energy-efficient and lightweight product designs are significantly accelerating market demand. Additionally, continuous advancements in polymer engineering and the development of specialty engineering plastics with enhanced thermal and mechanical properties are expanding their adoption across high-value industrial applications.

The market is expected to experience sustained expansion during the forecast period, supported by technological innovations, increasing investments in sustainable materials, and the growing adoption of recyclable and bio-based engineering plastics. Manufacturers are focusing on developing advanced polyamide (PA), polycarbonate (PC), polyoxymethylene (POM), polybutylene terephthalate (PBT), polyphenylene sulfide (PPS), and polyether ether ketone (PEEK) materials to meet the evolving performance requirements of industries such as electric mobility, renewable energy, medical devices, and industrial automation. Furthermore, increasing integration of engineering plastics in battery components, lightweight vehicle structures, electronic connectors, medical equipment, and additive manufacturing is creating new growth opportunities. Although fluctuations in raw material prices, environmental regulations concerning plastic waste, and recycling challenges remain key constraints, continuous innovation in high-performance polymers, circular economy initiatives, and expanding end-use applications are expected to support long-term growth in the

Global Engineering Plastics Market Growth Outlook

Engineering Plastics Market Growth (1)

To know about the Research Methodology :- Request Free Sample Report

Engineering Plastics Market Dynamics

Growing demand for lightweight and high-performance materials is accelerating market expansion

The increasing need to reduce product weight while maintaining superior mechanical strength, thermal stability, and chemical resistance is driving the adoption of engineering plastics across automotive, aerospace, electrical & electronics, industrial machinery, and consumer goods industries. Automakers are increasingly replacing metal components with engineering plastics to improve fuel efficiency and extend electric vehicle driving range, while electronics manufacturers are utilizing advanced polymers to produce compact, durable, and heat-resistant components. Continuous industrial automation and growing demand for high-performance materials are further supporting market growth.

Rapid expansion of electric vehicles and advanced electronics is creating significant growth opportunities

The accelerating adoption of electric vehicles (EVs), 5G infrastructure, renewable energy systems, and smart electronic devices is significantly increasing demand for engineering plastics such as polyamide (PA), polycarbonate (PC), polybutylene terephthalate (PBT), polyphenylene sulfide (PPS), and polyether ether ketone (PEEK). These materials provide excellent electrical insulation, flame resistance, dimensional stability, and lightweight properties, making them essential for battery systems, charging infrastructure, electronic connectors, sensors, and high-performance electrical components. Increasing investments in next-generation mobility and electronics manufacturing continue to create new growth avenues for the market.

Raw material price volatility and environmental regulations remain key market challenges

Engineering plastics are largely derived from petrochemical feedstocks, making manufacturers vulnerable to fluctuations in crude oil prices and raw material costs. Additionally, increasingly stringent environmental regulations regarding plastic waste management, recycling requirements, and carbon emissions are encouraging manufacturers to invest in sustainable production processes and recyclable polymer solutions. High production costs for specialty engineering plastics and limited recycling infrastructure for certain high-performance polymers continue to pose challenges for market expansion.

Advancements in sustainable polymers and high-performance composites are strengthening long-term market potential

Continuous innovation in bio-based engineering plastics, recycled polymer technologies, fiber-reinforced composites, and advanced polymer formulations is expanding application opportunities across healthcare, aerospace, renewable energy, industrial automation, and additive manufacturing. Manufacturers are increasingly investing in circular economy initiatives, closed-loop recycling technologies, and next-generation high-performance materials that offer enhanced durability, lower environmental impact, and improved processability. These technological advancements are expected to drive long-term growth while supporting global sustainability objectives.

Engineering Plastics Market Trends:

  • Lightweight material substitution is accelerating across automotive and electric vehicle manufacturing, with engineering plastics increasingly replacing metals in structural, interior, under-the-hood, and battery system components to improve fuel efficiency, reduce vehicle weight, extend EV driving range, and lower manufacturing costs while maintaining high mechanical performance and safety standards.
  • Demand for high-performance engineering plastics is increasing in electrical and electronics applications, driven by rapid growth in electric vehicles, 5G infrastructure, consumer electronics, industrial automation, and smart devices. Materials such as polycarbonate (PC), polyamide (PA), polybutylene terephthalate (PBT), polyphenylene sulfide (PPS), and PEEK are witnessing strong adoption due to their excellent electrical insulation, flame retardancy, thermal stability, and dimensional accuracy.
  • Sustainability is driving innovation in bio-based, recycled, and circular engineering plastics, with manufacturers investing in chemically recycled polymers, renewable feedstocks, and closed-loop recycling technologies to meet increasingly stringent environmental regulations and corporate ESG commitments. The development of sustainable engineering plastics with performance comparable to virgin materials is becoming a key competitive differentiator.
  • Advanced polymer formulations and composite engineering are expanding high-value industrial applications, as manufacturers develop glass fiber-reinforced, carbon fiber-reinforced, flame-retardant, and wear-resistant engineering plastics for use in aerospace, medical devices, industrial machinery, robotics, renewable energy systems, and additive manufacturing. These innovations are enabling engineering plastics to penetrate applications traditionally dominated by metals and specialty alloys.

Global Engineering Plastics Market Segment Analysis:
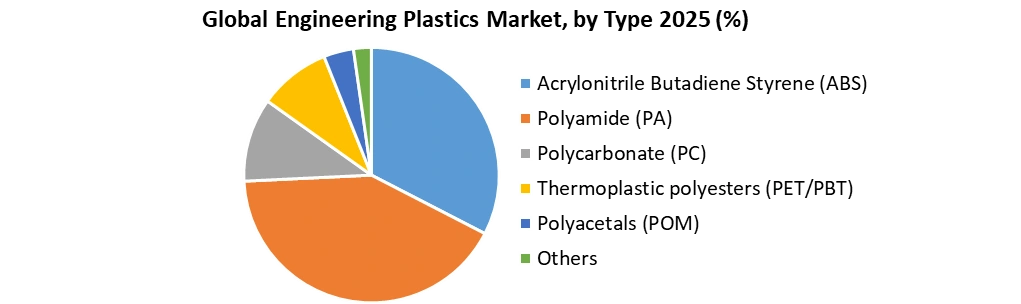
Based on Type, the Engineering Plastics Market is divided into Acrylonitrile Butadiene Styrene (ABS), Polyamide (PA), Polycarbonate (PC), Thermoplastic Polyesters (PET/PBT), Polyacetals (POM), and Others. Polyamide (PA) dominated the market in 2025, owing to its excellent mechanical strength, wear resistance, heat resistance, and chemical stability, making it one of the most widely used engineering plastics across automotive, electrical & electronics, industrial machinery, and consumer goods applications. The increasing demand for lightweight automotive components, electric vehicle battery systems, gears, bearings, connectors, and under-the-hood applications has significantly boosted the consumption of polyamide. Its superior durability, fatigue resistance, and compatibility with glass-fiber reinforcement continue to support its dominant market position. Furthermore, continuous advancements in bio-based polyamide and high-performance PA grades are expanding its application scope across advanced industrial sectors.

Global Engineering Plastics Market by Type

Polycarbonate (PC) is expected to register the fastest growth during the forecast period, driven by rising demand for lightweight, impact-resistant, and transparent materials across electric vehicles, consumer electronics, medical devices, and construction applications. Polycarbonate offers exceptional optical clarity, flame resistance, dimensional stability, and electrical insulation, making it highly suitable for electronic housings, LED lighting, battery enclosures, and safety components. Thermoplastic Polyesters (PET/PBT) continue to witness strong adoption in electrical connectors, automotive electrical systems, and industrial equipment due to their excellent electrical properties and heat resistance. Acrylonitrile Butadiene Styrene (ABS) remains extensively utilized in automotive interiors, appliances, and consumer electronics because of its balanced mechanical performance and ease of processing, while Polyacetals (POM) are increasingly preferred for precision engineering components requiring low friction, high stiffness, and dimensional accuracy. The Others segment, including polyphenylene sulfide (PPS), polyether ether ketone (PEEK), polyetherimide (PEI), and liquid crystal polymers (LCP), is steadily expanding due to growing demand for ultra-high-performance polymers in aerospace, healthcare, electronics, and industrial automation.

Based on End-use Industry, the Engineering Plastics Market is divided into Automotive & Transportation, Electrical & Electronics, Industrial & Machinery, Packaging, and Others. Automotive & Transportation dominated the market in 2025, driven by the increasing use of engineering plastics to reduce vehicle weight, improve fuel efficiency, extend electric vehicle driving range, and replace conventional metal components. Engineering plastics are extensively used in engine components, battery housings, interior trims, fuel systems, lighting systems, structural parts, and electronic modules due to their high strength-to-weight ratio, corrosion resistance, and design flexibility. The rapid expansion of electric vehicle production and stringent emission regulations continue to strengthen the dominance of this segment.

Electrical & Electronics is expected to witness the fastest growth during the forecast period, supported by rising production of electric vehicles, consumer electronics, industrial automation equipment, 5G infrastructure, and renewable energy systems. Engineering plastics are increasingly utilized in connectors, switches, circuit breakers, battery components, semiconductor equipment, electrical insulation, and smart electronic devices due to their superior thermal stability, flame retardancy, and electrical insulation properties. Industrial & Machinery continues to account for a significant market share owing to the increasing adoption of wear-resistant and high-strength polymers in gears, bearings, valves, pumps, conveyor systems, and automation equipment. Packaging is witnessing steady growth with increasing demand for durable, lightweight, and high-barrier packaging solutions for food, healthcare, and industrial products. Meanwhile, the Others segment, comprising healthcare, aerospace & defense, consumer goods, construction, and renewable energy applications, is expected to expand steadily as advanced engineering plastics gain wider acceptance in high-performance and technologically demanding industries.

Engineering Plastics Market Regional Insights:

Asia Pacific dominated the Engineering Plastics Market in 2025 and is expected to maintain its leading position throughout the forecast period, driven by its strong manufacturing base, rapid industrialization, and expanding automotive, electrical & electronics, and consumer goods industries. China, Japan, South Korea, and India account for a substantial share of regional demand due to their large-scale production of automobiles, electric vehicles, consumer electronics, industrial machinery, and electrical equipment. The region also benefits from the presence of leading engineering plastics manufacturers, abundant raw material availability, cost-effective manufacturing capabilities, and increasing investments in advanced polymer production. Furthermore, government initiatives supporting electric mobility, renewable energy, and industrial automation are accelerating the adoption of high-performance engineering plastics across multiple end-use industries.

North America is expected to register the fastest growth during the forecast period, supported by increasing demand for lightweight materials in electric vehicles, aerospace, medical devices, and industrial automation applications. Growing investments in sustainable polymers, advanced composites, and high-performance engineering plastics, coupled with continuous innovation in additive manufacturing and precision engineering, are driving regional market expansion. Europe continues to account for a significant market share owing to stringent fuel efficiency and carbon emission regulations, increasing adoption of lightweight automotive materials, and strong demand from the automotive, aerospace, and electrical & electronics sectors. Latin America is witnessing steady growth due to expanding automotive manufacturing, improving industrial infrastructure, and increasing investments in consumer goods and packaging industries. Meanwhile, the Middle East & Africa is expected to experience gradual growth, supported by industrial diversification initiatives, growing infrastructure development, rising demand for engineering plastics in construction and electrical applications, and increasing investments in manufacturing and petrochemical industries.

Global Engineering Plastics Market Recent Developments:

Date Company Recent Development
January 2026 BASF BASF showcased sustainable engineering plastics and advanced material solutions at PlastIndia 2026, targeting automotive, e-mobility, electronics, packaging and industrial applications.
January 2026 Covestro Covestro supplied Bayblend® RE polycarbonate containing 25% bio-circular attributed raw materials for BLUETTI’s Elite 100 V2 portable power station, supporting more sustainable product design.
April 2026 Covestro At CHINAPLAS 2026, Covestro presented engineering plastics for humanoid robots, eVTOL aircraft, EV charging, medical wearables, electronics and data-center applications.
May 2026 Covestro Covestro highlighted polycarbonate solutions for AI servers, data centers, semiconductor handling, cooling systems, robotics and smart electronics at COMPUTEX 2026.
June 2026 Toray Industries Toray announced plans for a 3,000-ton-per-year PPS compound production facility in Sri City, India, with operations targeted for early 2027 to strengthen local supply of high-performance engineering plastics.

Engineering Plastics Market Competitive Landscape:

The Engineering Plastics Market is highly competitive, with leading manufacturers focusing on product innovation, capacity expansion, sustainability, and strategic collaborations to strengthen their market positions. Companies are investing significantly in the development of high-performance engineering plastics with enhanced thermal stability, chemical resistance, flame retardancy, and lightweight properties to address the evolving requirements of the automotive, electrical & electronics, healthcare, aerospace, and industrial machinery sectors. The growing demand for electric vehicles, renewable energy systems, and miniaturized electronic components is encouraging manufacturers to expand production capacities, develop bio-based and recycled engineering plastics, and enhance their global distribution networks. In addition, mergers, acquisitions, joint ventures, and long-term supply agreements remain key strategies for improving market competitiveness and expanding regional presence.

Leading companies including BASF SE, SABIC, Covestro AG, Celanese Corporation, DuPont de Nemours, Inc., LANXESS AG, Mitsubishi Engineering-Plastics Corporation, Solvay S.A., LG Chem Ltd., and Toray Industries, Inc. are continuously expanding their engineering plastics portfolios through advanced polymer technologies, specialty resin development, and sustainable material innovations. Manufacturers are increasingly introducing high-performance grades of polyamide (PA), polycarbonate (PC), polybutylene terephthalate (PBT), polyoxymethylene (POM), polyphenylene sulfide (PPS), and polyether ether ketone (PEEK) to meet the growing demand from electric mobility, industrial automation, consumer electronics, and medical applications. As sustainability regulations become more stringent, companies are also investing in circular economy initiatives, chemically recycled polymers, and low-carbon manufacturing processes to strengthen their long-term competitive advantage.

Engineering Plastics Market Scope: Inquiry Before Buying

Engineering Plastics Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 125.10 Bn.
Forecast Period 2026 to 2034 CAGR: 7.4% Market Size in 2034: USD 300 Bn.
Segments Covered: by Material Type Polycarbonate
Polyamide
Polyoxymethylene
Polyethylene Terephthalate
Acrylonitrile Butadiene Styrene
Others
by End-use Industry Automotive
Electrical and Electronics
Building and Construction
Medical Devices
Aerospace
Packaging
Others
by Processing Method Injection Molding
Extrusion
Blow Molding
Thermoforming
3D Printing
Others
by Product Form Sheets
Films
Rod
Pipes
Granules
by Application Abrasion Resistant Liners
Acid Trays
Anti-Corrosive Liners
Braking Tray Liners
Bearings
Bench Top
Boat Chopping Board
Boat Windscreen
Bolts and Nuts
Others

Global Engineering Plastics Market by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Global Engineering Plastics Market Key Players

North America
1. DuPont de Nemours, Inc. – United States
2. Celanese Corporation – United States
3. Eastman Chemical Company – United States
4. RTP Company – United States
5. Ensinger Inc. – United States
6. Avient Corporation – United States
7. Lubrizol Corporation – United States
8. Dow Inc. – United States
9. Huntsman Corporation – United States
10. Ascend Performance Materials – United States
11. Solvay Specialty Polymers USA, LLC – United States
12. Avient Corporation – United States
Europe
13. BASF SE – Germany
14. Covestro AG – Germany
15. LANXESS AG – Germany
16. Arkema S.A. – France
17. LyondellBasell Industries N.V. – Netherlands
18. EMS-CHEMIE Holding AG – Switzerland
19. Syensqo – Belgium
20. Evonik Industries AG – Germany
21. Victrex plc – United Kingdom
22. Envalior – Netherlands
23. Röchling SE & Co. KG – Germany
24. Radici Group – Italy
25. Kuraray Co., Ltd. – Germany/Europe
26. INEOS Styrolution Group GmbH – Germany
27. DOMO Chemicals GmbH – Germany
Asia Pacific
28. Mitsubishi Chemical Group Corporation – Japan
29. Toray Industries, Inc. – Japan
30. Teijin Limited – Japan
31. LG Chem Ltd. – South Korea
32. Sumitomo Chemical Co., Ltd. – Japan
33. Idemitsu Kosan Co., Ltd. – Japan
34. Formosa Plastics Corporation – Taiwan
35. Chi Mei Corporation – Taiwan
36. KOLON ENP, Inc. – South Korea
37. Asahi Kasei Corporation – Japan
38. Polyplastics Co., Ltd. – Japan
39. Daicel Corporation – Japan
40. Mitsui Chemicals, Inc. – Japan
41. UBE Corporation – Japan
42. JSR Corporation – Japan
43. LOTTE Chemical Corporation – South Korea
44. Zhejiang NHU Co., Ltd. – China
45. Tosoh Corporation – Japan
46. Nilit Ltd. – Israel
Middle East & Africa
47. SABIC – Saudi Arabia
48. Borouge – United Arab Emirates
49. QAPCO (Qatar Petrochemical Company) – Qatar
South America
50. Braskem S.A. – Brazil

Frequently Asked Questions;

1. Which region has the largest share in the Global Engineering Plastics Market?
Ans: The Asia Pacific region held the highest share in 2025 in the Global Engineering Plastics Market.

2. What are the key factors driving the growth of the Global Engineering Plastics Market?
Ans: Rising Demand in Automotive Sector to boost the global Engineering Plastics Market growth.

3. Who are the key competitors in the Global Engineering Plastics Market?
Ans: BASF SE, SABIC, Solvay, and Covestro are the key competitors in the Global Engineering Plastics Market.

4. What are the opportunities for the Global Engineering Plastics Market?
Ans: Electric Vehicles (EVs) & Lightweighting Create Opportunities for Engineering Plastics Market Growth.

5. Which type segment dominates the Global Engineering Plastics Market?
Ans: The polyacetals segment dominated the Global Engineering Plastics Market.

Table of Contents

1. Global Engineering Plastics Market Introduction 1.1. Executive Market Landscape and Industry Overview 1.1.1. Global Engineering Plastics Market Size (Value USD Million & Volume in Metric Tons) and Growth Outlook 1.1.2. Historical Market Size Trends Across Engineering Plastics 1.1.3. Forecast Revenue Projections Through 2034 With Growth Drivers 1.1.4. Global Demand-Supply Balance Across Engineering Plastic Markets 1.1.5. Macroeconomic Indicators Influencing Engineering Plastics Market Expansion 1.1.6. Evolution of Engineering Plastics Across Major Industries 1.1.7. Transition Toward Lightweight and High-Performance Engineering Materials 1.1.8. Long-Term Market Outlook Highlighting Emerging Growth Opportunities 1.1.9. CAGR Analysis of Global Engineering Plastics Market 1.2. Engineering Plastics Market Dynamics 1.2.1. Engineering Plastics Market Trends 1.2.2. Engineering Plastics Market Dynamics 1.2.3. Drivers 1.2.4. Restraints 1.2.5. Opportunities 1.2.6. Challenges 1.2.7. PORTER’s Five Forces Analysis 1.2.8. PESTLE Analysis 1.3. Engineering Plastics Pricing Structure and Value Chain Profitability 1.3.1. Comprehensive Engineering Plastics Cost Structure Across Value Chain 1.3.2. Raw Material Costs Influencing Engineering Plastics Production Economics 1.3.3. Polymerization and Compounding Costs Across Manufacturing Processes 1.3.4. Margin Distribution Across Producers, Compounders, and Distributors 1.3.5. Impact of Feedstock Price Fluctuations on Plastic Pricing 1.3.6. Regional Pricing Differences Across Major Engineering Plastics Markets 1.3.7. Premium Pricing Dynamics for High-Performance Plastic Grades 1.3.8. Profitability Trends Across Major Industry Value Chain Participants 1.4. Engineering Plastics Feedstock Procurement and Supply Dynamics 1.4.1. Key Feedstocks Supporting Global Engineering Plastics Production 1.4.2. Polyamide Feedstock Supply Dynamics Across Major Regions 1.4.3. Polycarbonate Feedstock Availability Supporting Global Production 1.4.4. PBT and POM Feedstock Procurement Dynamics 1.4.5. Feedstock Supplier Dependency and Procurement Risk Assessment 1.4.6. Global Feedstock Price Volatility Affecting Production Economics 1.4.7. Regional Availability of Engineering Plastic Raw Materials 1.4.8. Long-Term Feedstock Contracting and Strategic Procurement Strategies 1.5. Engineering Plastics Chemistry and Material Performance Evolution 1.5.1. Molecular Structure Influencing Engineering Plastic Material Performance 1.5.2. Molecular Weight Distribution Across Engineering Plastic Grades 1.5.3. Crystallinity Effects on Mechanical and Thermal Performance 1.5.4. Density and Melt Flow Characteristics Across Plastic Grades 1.5.5. Chemical Resistance Requirements Across Engineering Plastic Applications 1.5.6. Thermal Stability Requirements for High-Performance Plastic Materials 1.5.7. Mechanical Strength and Toughness Requirements Across Applications 1.6. Engineering Plastics Grade Development and Material Innovation 1.6.1. Standard Engineering Plastic Grade Development Across Industries 1.6.2. High-Performance Engineering Plastic Grade Development Trends 1.6.3. Specialty Engineering Plastic Material Development Across Applications 1.6.4. Reinforced Engineering Plastic Grade Development Across Industries 1.6.5. Flame-Retardant Engineering Plastic Formulation Development Trends 1.6.6. Electrically Conductive Engineering Plastic Material Development 1.6.7. High-Temperature Engineering Plastic Grade Innovation Trends 1.6.8. Chemical-Resistant Engineering Plastic Material Development 1.7. Engineering Plastics Modification and Compounding Technology Evolution 1.7.1. Polymer Blending Technologies Supporting Engineering Plastic Performance 1.7.2. Glass Fiber Reinforcement Across Engineering Plastic Applications 1.7.3. Carbon Fiber Reinforcement Supporting Lightweight Engineering Applications 1.7.4. Mineral-Filled Engineering Plastics Improving Material Performance 1.7.5. Impact Modification Technologies Improving Plastic Material Toughness 1.7.6. Flame-Retardant Formulations Supporting Safety-Critical Engineering Applications 1.7.7. UV and Thermal Stabilizers Enhancing Plastic Durability 1.8. Engineering Plastics Manufacturing and Processing Technology Evolution 1.8.1. Advances in Polymerization Technologies Supporting Production Efficiency 1.8.2. Advanced Compounding Processes Improving Engineering Plastic Performance 1.8.3. Extrusion Technologies Supporting Engineering Plastic Product Manufacturing 1.8.4. Injection Molding Optimization Improving Product Quality and Productivity 1.8.5. Blow Molding Technologies Supporting Specialized Plastic Product Manufacturing 1.8.6. Thermoforming Technologies Supporting Advanced Engineering Plastic Applications 1.9. Engineering Plastics Application Evolution and Industry Adoption 1.9.1. Automotive Applications Driving Engineering Plastics Demand Growth 1.9.2. Electrical Electronics Applications Supporting Engineering Plastic Consumption 1.9.3. Industrial Machinery Applications Driving Advanced Plastic Material Demand 1.9.4. Construction Applications Supporting Engineering Plastic Market Expansion 1.9.5. Consumer Durable Goods Increasing Plastic Material Adoption 1.9.6. Healthcare Applications Requiring Specialized Engineering Plastic Materials 1.9.7. Aerospace Applications Supporting Lightweight Engineering Plastic Development 1.10. Engineering Plastics Material Substitution and Competitive Dynamics 1.10.1. Replacement of Conventional Metals With Engineering Plastic Materials 1.10.2. Polymer-to-Polymer Substitution Across Competitive Material Applications 1.10.3. Composite-to-Polymer Substitution Across Engineering Material Applications 1.10.4. Cost-Performance Comparison Across Engineering Material Alternatives 1.10.5. Lightweighting Opportunities Through Engineering Plastic Material Substitution 1.10.6. Performance Requirements Influencing Engineering Material Selection Decisions 1.10.7. Lifecycle Cost Advantages Supporting Engineering Plastic Adoption 1.11. Engineering Plastics Sustainability and Circularity Development Trends 1.11.1. Growing Demand for Sustainable Engineering Plastic Material Solutions 1.11.2. Mechanical Recycling Across Post-Industrial Plastic Waste Streams 1.11.3. Chemical Recycling Technologies Supporting Engineering Plastic Circularity 1.11.4. Recycled Content Integration Across Engineering Plastic Applications 1.11.5. Bio-Based Feedstocks Supporting Sustainable Plastic Material Development 1.11.6. Carbon Emission Reduction Across Plastic Manufacturing Operations 1.11.7. Sustainable Compounding and Processing Technology Development 1.11.8. Circular Economy Models Supporting Sustainable Plastic Value Chains 1.11.9. Corporate ESG Initiatives Influencing Engineering Plastics Sustainability 1.12. Global Engineering Plastics Trade Analysis and Supply Flows 1.12.1. Global Engineering Plastics Trade Flow Trends Analysis 1.12.2. Import-Export Patterns Across Major Plastic-Producing Countries 1.12.3. Regional Trade Dependencies Affecting Engineering Plastic Stability 1.12.4. Cross-Border Plastic Pricing and Arbitrage Dynamics Analysis 1.12.5. Tariff Barriers Affecting International Engineering Plastics Trade 1.12.6. Geopolitical Factors Influencing Global Plastic Trade Routes 1.12.7. Supply Chain Disruptions Affecting Engineering Plastic Availability 1.13. Engineering Plastics Supply Chain and Distribution 1.13.1. Global Engineering Plastics Supply Chain Structure Analysis 1.13.2. Producer-to-Processor Distribution Models Across Regional Markets 1.13.3. Distributor and Compounder Networks Supporting Market Accessibility 1.13.4. Regional Manufacturing Networks Supporting Engineering Plastic Supply 1.13.5. Bulk and Packaged Plastic Transportation Systems Analysis 1.13.6. Warehousing and Inventory Management Strategies Across Regions 1.13.7. Regional Plastic Supply Hubs Supporting Market Distribution 1.13.8. Supply Chain Digitization Improving Plastic Distribution Visibility 1.14. Engineering Plastics Quality and Grade Differentiation Analysis 1.14.1. Engineering Plastic Grade Classification Based on Performance 1.14.2. Mechanical Performance Benchmarking Across Engineering Plastic Grades 1.14.3. Thermal Performance Requirements Across High-Temperature Applications 1.14.4. Chemical and Environmental Resistance Across Plastic Materials 1.14.5. Dimensional Stability Requirements Across Precision Applications 1.14.6. Long-Term Durability Requirements for Engineering Plastic Components 1.14.7. Processing Consistency Across Different Plastic Grade Formulations 1.15. Engineering Plastics Research, Development and Innovation 1.15.1. R&D Investment Trends Across Engineering Plastic Manufacturers 1.15.2. Development of Advanced Plastic Grades and Formulations 1.15.3. Advanced Polymerization Research Supporting Material Performance Improvements 1.15.4. High-Temperature Plastic Development for Demanding Applications 1.15.5. Nanocomposite Technologies Supporting Advanced Plastic Material Performance 1.15.6. Polymer Blends Supporting Enhanced Engineering Material Properties 1.16. Engineering Plastics Regulatory Framework and Compliance Analysis 1.16.1. Global Regulations Governing Engineering Plastic Manufacturing Operations 1.16.2. Chemical Registration Requirements Across Major Plastic Markets 1.16.3. Product Safety Standards Governing Engineering Plastic Materials 1.16.4. Automotive Material Standards Influencing Plastic Product Development 1.16.5. Electrical Material Standards Supporting Engineering Plastic Applications 1.16.6. Medical-Grade Plastic Certification Requirements Across Global Markets 1.17. Engineering Plastics Material Selection and End-Use Demand 1.17.1. Material Selection Criteria Across Engineering Plastic Applications 1.17.2. Automotive Industry Demand for Advanced Plastic Materials 1.17.3. Electrical Electronics Demand for Engineering Plastic Components 1.17.4. Industrial Machinery Demand for High-Performance Plastic Materials 1.17.5. Construction Industry Adoption of Engineering Plastic Solutions 1.17.6. Healthcare Industry Requirements for Specialized Plastic Materials 1.18. Emerging Engineering Plastics Technologies and Future Opportunities 1.18.1. High-Temperature Plastic Technologies Supporting Advanced Applications 1.18.2. High-Strength Lightweight Plastic Materials Supporting Industrial Design 1.18.3. Self-Lubricating Plastic Materials Improving Component Performance 1.18.4. Electrically Conductive Plastic Technologies Supporting Advanced Electronics 1.18.5. Flame-Retardant Engineering Materials Supporting Safety-Critical Applications 1.18.6. Wear-Resistant Plastic Technologies Improving Component Durability 1.19. Regional Engineering Plastics Production and Consumption Landscape 1.19.1. North American Engineering Plastics Manufacturing Ecosystem Analysis 1.19.2. European Engineering Plastics Technology and Regulatory Landscape 1.19.3. Asia Pacific Engineering Plastics Manufacturing and Demand Dynamics 1.19.4. China Engineering Plastics Production and Consumption Trends 1.19.5. Japan Engineering Plastics Technology and Application Landscape 1.19.6. South Korea Engineering Plastics Manufacturing and Demand Trends 1.19.7. India Engineering Plastics Manufacturing and Consumption Expansion 1.20. Engineering Plastics Market: Market Size and Forecast by Segmentation (by Value USD Million & Volume in Metric Tons) (2025–2034) 1.20.1. Engineering Plastics Market Size and Forecast by Material Type 1.20.1.1. Polycarbonate 1.20.1.2. Polyamide 1.20.1.3. Polyoxymethylene 1.20.1.4. Polyethylene Terephthalate 1.20.1.5. Acrylonitrile Butadiene Styrene 1.20.1.6. Others 1.20.2. Engineering Plastics Market Size and Forecast by Processing Methods 1.20.2.1. Injection Molding 1.20.2.2. Extrusion 1.20.2.3. Blow Molding 1.20.2.4. Thermoforming 1.20.2.5. 3D Printing 1.20.2.6. Others 1.20.3. Engineering Plastics Market Size and Forecast by Product Form 1.20.3.1. Sheets 1.20.3.2. Films 1.20.3.3. Rod 1.20.3.4. Pipes 1.20.3.5. Granules 1.20.4. Engineering Plastics Market Size and Forecast by Application 1.20.4.1. Abrasion Resistant Liners 1.20.4.2. Acid Trays 1.20.4.3. Anti-Corrosive Liners 1.20.4.4. Braking Tray Liners 1.20.4.5. Bearings 1.20.4.6. Bench Top 1.20.4.7. Boat Chopping Board 1.20.4.8. Boat Windscreen 1.20.4.9. Bolts and Nuts 1.20.4.10. Others 1.20.5. Engineering Plastics Market Size and Forecast by End User 1.20.5.1. Automotive 1.20.5.2. Electrical and Electronics 1.20.5.3. Building and Construction 1.20.5.4. Medical Devices 1.20.5.5. Aerospace 1.20.5.6. Packaging 1.20.5.7. Others 1.20.6. Engineering Plastics Market Size and Forecast by Region 1.20.6.1. North America 1.20.6.1.1. United States 1.20.6.1.2. Canada 1.20.6.1.3. Mexico 1.20.6.2. Europe 1.20.6.2.1. United Kingdom 1.20.6.2.2. France 1.20.6.2.3. Germany 1.20.6.2.4. Italy 1.20.6.2.5. Switzerland 1.20.6.2.6. Spain 1.20.6.2.7. Sweden 1.20.6.2.8. Russia 1.20.6.2.9. Rest of Europe 1.20.6.3. Asia Pacific 1.20.6.3.1. China 1.20.6.3.2. South Korea 1.20.6.3.3. Japan 1.20.6.3.4. India 1.20.6.3.5. Australia 1.20.6.3.6. Indonesia 1.20.6.3.7. Philippines 1.20.6.3.8. Malaysia 1.20.6.3.9. Vietnam 1.20.6.3.10. Thailand 1.20.6.3.11. Rest of Asia Pacific 1.20.6.4. Middle East and Africa 1.20.6.4.1. South Africa 1.20.6.4.2. Turkey 1.20.6.4.3. Saudi Arabia 1.20.6.4.4. UAE 1.20.6.4.5. Qatar 1.20.6.4.6. Egypt 1.20.6.4.7. Nigeria 1.20.6.4.8. Rest of Middle East and Africa 1.20.6.5. South America 1.20.6.5.1. Brazil 1.20.6.5.2. Argentina 1.20.6.5.3. Chile 1.20.6.5.4. Colombia 1.20.6.5.5. Rest of South America 2. Competitive Intelligence & Industrial Ecosystem 2.1. Competitive Landscape 2.1.1. MMR Competition Matrix 2.1.2. Competitive Positioning of Leading Key Players [Revenue and Market Share (%)] 2.1.3. Key Players Benchmarking 2.1.3.1. Company Name 2.1.3.2. Headquarter 2.1.3.3. Product Portfolio 2.1.3.4. Product Quality & Reliability 2.1.3.5. Technology Innovation & Differentiation 2.1.3.6. Manufacturing Capacity 2.1.3.7. Raw Material & Feedstock Supply Chain Strength 2.1.3.8. Distribution Network 2.1.3.9. End-Use Industry Coverage 2.1.3.10. Revenue (2025) 2.1.3.11. R&D Investment (%) 2.1.3.12. Profit Margin (%) 2.1.3.13. Growth Rate (Y-o-Y %) 2.1.3.14. Geographic Presence 2.1.4. Market Structure 2.1.4.1. Market Leaders 2.1.4.2. Market Followers 2.1.4.3. Emerging Players 2.1.5. Growth Rate/Y-o-Y (%) of Companies 2.1.6. Profit Margin (%) of Companies 2.1.7. R&D Investments (%) of Companies 2.1.8. Mergers and Acquisitions Details 2.1.9. Recent Key Developments 2.2. Engineering Plastics Competitive Landscape and Industry Structure 2.2.1. Market Concentration Across Global Engineering Plastics Industry 2.2.2. Competitive Intensity Among Leading Plastic Manufacturers 2.2.3. Competitive Positioning Strategies Across Major Producers 2.2.4. Entry Barriers Facing New Plastic Industry Participants 2.2.5. Production Scale Advantages Supporting Competitive Market Positioning 2.2.6. Technology Differentiation Across Engineering Plastic Manufacturers 2.2.7. Product Portfolio Differentiation Across Major Industry Players 2.2.8. Competitive Benchmarking Across Quality, Pricing and Innovation 2.3. Engineering Plastics Company Market Share and Positioning 2.3.1. Revenue-Based Market Share Comparison Across Leading Companies 2.3.2. Market Share Distribution Across Major Plastic Types 2.3.3. High-Performance Plastic Market Positioning Across Key Players 2.3.4. Regional Market Positioning Across Major Plastic Producers 2.3.5. Product Portfolio Breadth Across Leading Manufacturers 2.3.6. Capacity Expansion Supporting Future Market Share Growth 2.3.7. Product Differentiation Strategies Across Competitive Market Segments 2.3.8. Application Portfolio Comparison Across Leading Industry Participants 2.4. Engineering Plastics Strategic Initiatives and Expansion Strategies 2.4.1. Mergers and Acquisitions Shaping Competitive Industry Structure 2.4.2. Capacity Expansion Supporting Engineering Plastic Production Growth 2.4.3. New Manufacturing Facilities Across Strategic Regional Markets 2.4.4. Global Market Entry and Geographic Expansion Strategies 2.4.5. Strategic Partnerships Supporting Plastic Technology Development 2.4.6. Vertical Integration Across Engineering Plastic Value Chains 2.4.7. High-Performance Plastic Portfolio Diversification Strategies 2.4.8. Investment in Advanced Plastic Product Development 2.4.9. Sustainability Investments Supporting Long-Term Market Positioning 2.5. Engineering Plastics Sustainability and ESG Performance Benchmarking 2.5.1. Sustainability Strategies Across Leading Engineering Plastic Manufacturers 2.5.2. Recycled Material Integration Across Plastic Product Portfolios 2.5.3. Chemical Recycling Investments Supporting Circular Plastic Development 2.5.4. Carbon Emission Reduction Initiatives Across Manufacturing Facilities 2.5.5. Energy Efficiency Programs Supporting Sustainable Plastic Production 2.5.6. Circular Economy Initiatives Across Leading Industry Participants 2.5.7. Sustainable Feedstock Adoption Across Plastic Manufacturing Operations 2.5.8. ESG Performance Benchmarking Across Major Engineering Plastic Companies 2.5.9. Sustainable Product Development Supporting Future Competitive Positioning 2.6. Engineering Plastics Financial Performance and Profitability Benchmarking 2.6.1. Revenue Growth Trends Across Leading Plastic Manufacturers 2.6.2. Profit Margin Analysis Across Major Industry Participants 2.6.3. Engineering Plastic Production Cost Structure Comparison 2.6.4. Research and Development Investment Trends Across Companies 2.6.5. Capacity Utilization and Operational Efficiency Comparison 2.6.6. Financial Resilience During Engineering Plastic Market Disruptions 2.6.7. Premium Product Contribution to Company Profitability 2.6.8. Cost Optimization Strategies Supporting Long-Term Profitability 2.7. Company Profile: 30+ Key Players 2.7.1. Company Profile Parameters 2.7.1.1. Overview 2.7.1.2. Business Portfolio 2.7.1.3. Financial Overview 2.7.1.4. SWOT Analysis 2.7.1.5. Strategic Analysis 2.7.1.6. Recent Developments 2.7.2. North America 2.7.2.1. DuPont de Nemours, Inc. 2.7.2.2. Celanese Corporation 2.7.2.3. Eastman Chemical Company 2.7.2.4. Chevron Phillips Chemical Company LLC 2.7.2.5. Ascend Performance Materials 2.7.2.6. Avient Corporation 2.7.2.7. Teknor Apex Company 2.7.2.8. RTP Company 2.7.2.9. Trinseo PLC 2.7.3. Europe 2.7.3.1. BASF SE 2.7.3.2. Covestro AG 2.7.3.3. Syensqo SA 2.7.3.4. Solvay SA 2.7.3.5. Arkema S.A. 2.7.3.6. LANXESS AG 2.7.3.7. Envalior 2.7.3.8. Evonik Industries AG 2.7.3.9. EMS-Chemie Holding AG 2.7.3.10. DOMO Chemicals 2.7.3.11. LEHVOSS Group 2.7.3.12. RadiciGroup S.p.A. 2.7.3.13. Victrex plc 2.7.3.14. INEOS Group Holdings S.A. 2.7.3.15. Others 2.7.4. Asia Pacific 2.7.4.1. LG Chem Ltd. 2.7.4.2. Toray Industries, Inc. 2.7.4.3. Teijin Limited 2.7.4.4. Asahi Kasei Corporation 2.7.4.5. Sumitomo Chemical Co., Ltd. 2.7.4.6. Mitsubishi Engineering-Plastics Corporation (Mitsubishi Chemical Group) 2.7.4.7. Polyplastics Co., Ltd. (Joint Venture: Celanese Corporation / Daicel Corporation) 2.7.4.8. Bhansali Engineering Polymers Limited 2.7.4.9. Gujarat Fluorochemicals Limited 2.7.4.10. Hindustan Fluorocarbons Limited 2.7.5. South America 2.7.5.1. Braskem S.A. 2.7.5.2. Others 2.7.6. Middle East & Africa 2.7.6.1. Saudi Basic Industries Corporation (SABIC) 2.7.6.2. Others 3. Key Insights, Strategic Outlook & Methodological Framework 3.1. Key Findings 3.2. Strategic Moves & Industry Outlook 3.3. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements