Global Data Center Generator Market Size by Fuel Type , by Power Rating, by Operating Duty, by Redundancy Architecture, by Data Center Type, By Data Center Tier, by Installation Type, by Region and Forecast 2034

6.6%
CAGR (2026-2034)
9 USD Bn.
Forecast Market Size
318
Report Pages
125
Market Tables

Overview

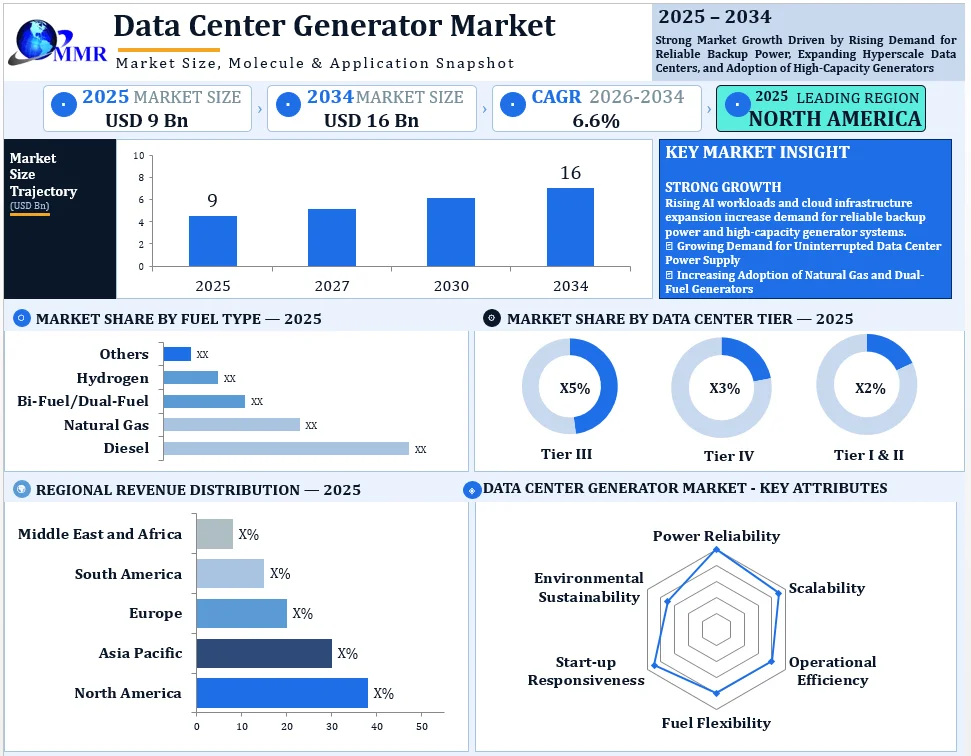
The Global Data Center Generator Market is valued at USD 9 billion in 2025 and is projected to reach USD 16 billion by 2034, growing at a CAGR of 6.6% during the forecast period (2026–2034).

Data Center Generator Market Overview:

The global data center generator market comprises generator systems that provide reliable backup power during utility outages and grid disruptions. These systems maintain uninterrupted power supply, operational continuity, and infrastructure reliability across hyperscale, colocation, enterprise, and edge data centers. Diesel generators maintain a significant market presence due to their high power output, rapid start-up capabilities, and reliability, while natural gas generators gain attention as alternative power solutions.

Increasing adoption of artificial intelligence (AI), cloud computing, high-performance computing (HPC), and digital services drives demand for dependable data center power infrastructure. Rising electricity consumption, grid constraints, and expanding hyperscale facilities encourage operators to strengthen backup generation capacity. Technological advancements in modular generators, automated controls, fuel optimization, and intelligent monitoring further support market development. Additionally, combined heat and power (CHP), combined cooling, heat and power (CCHP), and lower-emission generator technologies gain attention as operators focus on energy efficiency and sustainability.

Data Center Generator Market Size, Growth and Share Analysis
Data Center Generator Market Growth

To know about the Research Methodology :- Request Free Sample Report

Global Data Center Generator Market: Key Highlights

• The global data center generator market is valued at USD 9 billion in 2025 and is projected to reach USD 16 billion by 2034, growing at a CAGR of 6.6% during 2026–2034.
• Diesel generators maintain a significant market presence due to their high power output, rapid start-up capabilities, and reliability in emergency backup applications.
• North America dominates the market, supported by established data center infrastructure, hyperscale facility expansion, and increasing investments in AI-ready data centers.
• Growing adoption of AI, cloud computing, and high-performance computing (HPC) increases demand for high-capacity generators and uninterrupted power supply systems.
• Natural gas, dual-fuel, hydrogen, and CHP/CCHP technologies create opportunities for fuel diversification, improved energy efficiency, and lower-emission power generation.

Global Data Center Generator Market Dynamics:

Global Data Center Generator Market Drivers

Growing Demand for AI and Hyperscale Data Centers

The increasing adoption of artificial intelligence (AI), cloud computing, and high-performance computing (HPC) drives demand for reliable backup power systems across data centers. AI workloads require high-density computing infrastructure and greater electricity capacity, increasing the importance of dependable generator installations. According to the International Energy Agency (IEA), global data center electricity consumption reaches 485 TWh in 2025 and is projected to increase to 950 TWh by 2030. This rising electricity requirement encourages operators to strengthen backup power infrastructure through high-capacity diesel generators, natural gas generators, and modular generator systems.

Increasing Need for Uninterrupted Power Supply

The growing dependence on digital services, financial transactions, cloud platforms, and enterprise applications increases the need for continuous data center operations. Power interruptions create risks of data loss, equipment disruption, and service downtime, making backup generators essential components of data center infrastructure. According to Uptime Institute's 2025 Global Data Center Survey, power-related issues remain the leading cause of impactful data center outages. Consequently, operators invest in redundant generator configurations, automatic transfer switches, and advanced monitoring systems to improve power reliability.

Global Data Center Generator Market Restraints

High Capital and Installation Costs

The deployment of data center generator systems requires substantial investment in generator equipment, fuel storage, electrical infrastructure, exhaust systems, cooling arrangements, and installation. Large hyperscale facilities require multiple high-capacity generators to support redundancy and critical power requirements, increasing initial infrastructure expenditure. Additionally, regular servicing, fuel management, component replacement, and emissions compliance increase operational costs. These expenses create financial barriers for smaller data center operators and organizations with limited infrastructure budgets.

Environmental Regulations and Emission Concerns

Diesel-powered generators produce carbon dioxide, nitrogen oxides, particulate matter, and other emissions, creating environmental and regulatory challenges for data center operators. Increasing emphasis on decarbonization and energy efficiency encourages operators to evaluate alternative fuels and lower-emission generation technologies. The European Commission also highlights the environmental impact of data centers through their electricity consumption and associated carbon emissions. Compliance with emissions standards, permitting requirements, and operating restrictions increases generator deployment complexity, particularly in densely populated locations.

Global Data Center Generator Market Opportunities

Expansion of Natural Gas and Alternative-Fuel Generators

The increasing focus on energy security and lower-emission power generation creates opportunities for natural gas generators, renewable-compatible systems, and alternative-fuel technologies. According to the IEA, natural gas currently supplies 26% of global data center electricity consumption, making it an important component of the sector's energy mix. Generator manufacturers can capitalize on this demand through fuel-efficient natural gas systems, dual-fuel generators, and solutions that integrate with onsite energy infrastructure.

Growing Adoption of CHP and CCHP Systems

The increasing focus on energy efficiency creates opportunities for combined heat and power (CHP) and combined cooling, heat and power (CCHP) systems in data center facilities. CHP systems generate electricity while recovering useful heat, whereas CCHP systems also use recovered heat to support cooling requirements. These technologies improve overall energy utilization where suitable operating conditions and thermal demand exist. Their integration with conventional generator infrastructure provides opportunities for manufacturers and energy solution providers to offer more efficient onsite power systems.

Global Data Center Generator Market Challenges

Fuel Availability and Supply Chain Constraints

Data center operators depend on reliable fuel availability to maintain backup generator readiness during extended power interruptions. Fuel storage capacity, transportation disruptions, supply limitations, and changing fuel prices create operational challenges, particularly for large facilities with extensive backup power requirements. Manufacturers and operators also face supply chain constraints involving engines, alternators, control systems, and other critical generator components, which can affect installation schedules and infrastructure expansion.

Balancing Power Reliability with Sustainability Requirements

Data center operators face the challenge of maintaining high power reliability while reducing emissions and improving energy efficiency. Conventional diesel generators provide dependable emergency power but create environmental concerns, while alternative technologies require suitable infrastructure, fuel availability, and integration planning. The IEA projects that electricity consumption from AI-focused data centers triples between 2025 and 2030, increasing pressure on operators to develop scalable and reliable power infrastructure without compromising sustainability objectives.

Global Data Center Generator Market: Segment Analysis

By Fuel Type

The global data center generator market by fuel type includes Diesel, Natural Gas, Bi-Fuel/Dual-Fuel, Hydrogen, and Others. Diesel generators maintain a significant market presence due to their high power output, rapid start-up capabilities, established fuel infrastructure, and reliability in emergency backup applications. Natural gas generators gain attention as operators explore lower-emission power solutions and on-site generation, particularly in regions with established gas infrastructure. Bi-fuel and dual-fuel generators offer fuel flexibility by combining diesel and natural gas, helping operators manage fuel availability and operational requirements. Hydrogen generators represent an emerging segment, supported by growing interest in low-carbon energy technologies, although infrastructure availability and storage costs influence adoption. Other fuel types address specialized operational and regional requirements.

By Data Center Type

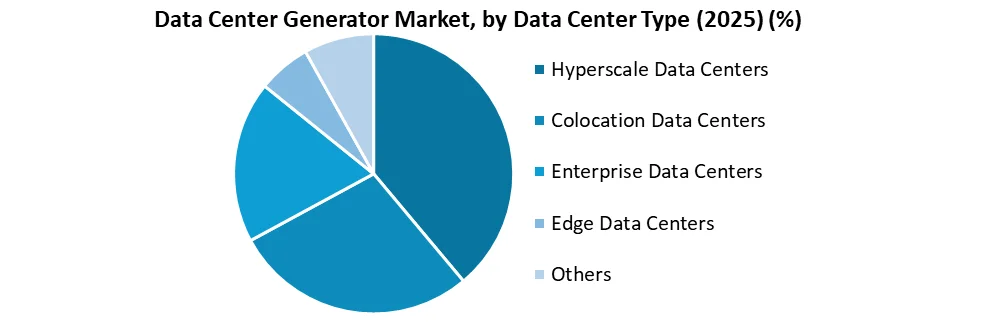
The market by data center type comprises Hyperscale Data Centers, Colocation Data Centers, Enterprise Data Centers, Edge Data Centers, and Others. Hyperscale data centers generate substantial demand for high-capacity generator systems due to their extensive computing infrastructure and increasing AI, cloud computing, and high-performance computing workloads. Colocation facilities require reliable backup power to maintain service availability for multiple customers, while enterprise data centers use generators to protect internal IT infrastructure and critical business applications. Edge data centers create demand for compact, modular, and remotely monitored generators as distributed computing expands alongside 5G, IoT, and industrial automation. Other facilities, including specialized, government, and institutional data centers, also require dependable backup power to maintain operational continuity.
Data Center Generator Market by data center type

By Installation Type

The market by installation type includes New/Greenfield Installation, Expansion/Capacity Addition, and Replacement/Retrofit. New or greenfield installations create demand for generator systems during the development of data center facilities, supported by investments in hyperscale infrastructure, cloud computing, and AI-ready facilities. Expansion and capacity addition drive the installation of additional or higher-capacity generators as operators increase computing capacity and accommodate rising electricity requirements. Replacement and retrofit activities involve upgrading aging generator systems with modern, fuel-efficient, and technologically advanced equipment to improve reliability, meet evolving emission requirements, and support changing power loads across existing data centers.

Global Data Center Generator Market: Regional Insights

North America dominates the global data center generator market, supported by its mature data center infrastructure, strong presence of hyperscale cloud service providers, and increasing investments in artificial intelligence (AI) infrastructure. The United States leads regional demand through extensive data center development across Northern Virginia, Texas, California, and other emerging hubs. North America accounts for 52.2 GW of installed data center IT capacity in 2025, representing approximately 45% of global capacity. Rising electricity consumption, grid constraints, and the need for uninterrupted power supply encourage operators to invest in high-capacity diesel generators, natural gas generators, and redundant backup power systems. Increasing development of AI-ready data centers further supports demand for reliable generator infrastructure.

Asia Pacific represents a major growth region for the global data center generator market, driven by rapid digitalization, expanding cloud computing services, rising internet penetration, and increasing AI investments. China, India, Japan, Singapore, Australia, and Malaysia support regional demand through hyperscale and colocation data center development. The region records 42.9 GW of installed data center IT capacity in 2025, accounting for approximately 37% of global capacity. Growing investments in data center infrastructure, particularly in India and Southeast Asia, increase the requirement for diesel and natural gas generators, modular backup power systems, and advanced generator monitoring technologies. Power availability and grid infrastructure also influence generator deployment across emerging data center markets.

Europe maintains a significant position in the global data center generator market, supported by established digital infrastructure, increasing cloud adoption, data localization requirements, and investments in AI computing facilities. The United Kingdom, Germany, France, the Netherlands, Ireland, and the Nordic countries represent important data center markets. Europe records 16.2 GW of installed data center IT capacity in 2025, representing approximately 14% of global capacity. Growing demand for uninterrupted power supply and operational resilience encourages data center operators to adopt efficient backup generators and advanced power management systems. Additionally, strict environmental regulations and decarbonization targets increase interest in natural gas generators, alternative fuels, and lower-emission power technologies.

The Middle East and Africa region presents emerging opportunities for the data center generator market, supported by digital transformation initiatives, cloud adoption, government investments, and expanding telecommunications infrastructure. The United Arab Emirates, Saudi Arabia, and South Africa contribute to regional data center development through investments in digital infrastructure and colocation facilities. The region records 2.6 GW of installed data center IT capacity in 2025. Increasing data center construction, high operating temperatures, and the need for reliable electricity supply support demand for robust backup generators, fuel-efficient systems, and advanced cooling-compatible power infrastructure. Investments in hyperscale facilities and digital economy initiatives further strengthen the regional market outlook.

South America experiences gradual growth in the global data center generator market, driven by increasing cloud computing adoption, digital services, telecommunications expansion, and investments in colocation infrastructure. Brazil, Chile, and other developing digital hubs support regional demand for reliable backup power solutions. The region records 2.1 GW of installed data center IT capacity in 2025. Growing data center investments and the need to maintain uninterrupted operations encourage the deployment of diesel generators, natural gas systems, and modular backup power equipment. Improvements in digital infrastructure and increasing demand for secure data storage and processing services further support market development.

Global Data Center Generator Market: Competitive Landscape

The global data center generator market features established power generation manufacturers competing through high-capacity generator portfolios, fuel flexibility, operational reliability, rapid deployment, and global service networks. Competition is driven by the growing requirement for uninterrupted power supply, high-power backup systems, data center continuous-rated generators, and scalable power infrastructure. Leading manufacturers strengthen their market positions through product innovation, integrated power solutions, customized generator configurations, and long-term maintenance support. The market also includes regional manufacturers and specialized power solution providers that serve specific capacity requirements and geographical markets.

Key Players and Competitive Positioning

Company Competitive Positioning Key Areas of Focus
Caterpillar Inc. Strong presence in high-capacity
backup power and mission-critical applications.
Diesel and natural gas generators,
integrated power systems, energy storage, hydrogen-fuelled generation, and
global dealer support.
Cummins Inc. Broad generator portfolio with
dedicated data center continuous-rated solutions.
High-horsepower generator sets,
containerized systems, paralleling controls, natural gas generation, and
lifecycle services.
Rolls-Royce plc (mtu Solutions) Focuses on high-performance power
generation for large and mission-critical facilities.
Large diesel and gas generator
systems, integrated power solutions, and advanced control technologies.
Rehlko Competes through industrial generator
systems and mission-critical power applications.
High-capacity diesel generators,
customized configurations, and data center backup power solutions.
Generac Power Systems, Inc. Strengthens its position in
distributed and backup power solutions.
Industrial generators, modular power
systems, switchgear, enclosures, and energy management technologies.
Atlas Copco AB Offers generator solutions for
standby, temporary, and distributed power requirements.
Portable and industrial generators,
rental power, and modular power equipment.
HIMOINSA S.L. Serves international markets through
industrial generator manufacturing and distribution.
Diesel and gas generator sets, containerized
solutions, and customized power systems.
Mitsubishi Heavy Industries, Ltd. Participates in large-scale power
generation and industrial energy infrastructure.
Heavy-duty power generation
equipment, gas turbines, and integrated energy solutions.
Wärtsilä Corporation Focuses on flexible power generation
and energy system integration.
Gas and multi-fuel engines, flexible
generation, and hybrid power solutions.
Aggreko Ltd. Supports temporary and rapidly
deployable power requirements.
Rental generators, modular power
packages, temporary power infrastructure, and energy services.

Global Data Center Generator Market: Recent Developments

Date Company Development Market Impact
January 28, 2026 Caterpillar Inc. Enters a strategic alliance with
American Intelligence & Power and Boyd CAT, supporting an order for 2
GW of fast-response natural gas generator sets
for the Monarch Compute
Campus.
Strengthens Caterpillar's position in
large-scale natural gas power generation for hyperscale and AI data centers.
February 11, 2026 BorgWarner Inc. Signs a Master Supply Agreement with
TurboCell to supply modular turbine generator systems for AI-driven data
center campuses.
Expands competition in modular
on-site power generation for high-capacity data center infrastructure.
March 5, 2026 Generac Power Systems Partners with EPC Power to deploy
integrated energy solutions combining battery systems, controllers, and power
conversion technologies for data centers.
Strengthens integrated backup power
and energy management capabilities for AI data center applications.
April 23, 2026 INNIO Demonstrates a 3 MW, 100% hydrogen
backup power system
for data centers in collaboration with the Net Zero
Innovation Hub.
Advances hydrogen-based backup
generation and supports lower-carbon power alternatives for data centers.
June 18, 2026 Cummins Inc. Expands its high-horsepower Centum
Series generator portfolio with QSK78-powered solutions for 50 Hz markets.
Strengthens its generator offering
for international data centers and other mission-critical facilities.
July 20, 2026 Everllence Introduces the 175D GenSet,
delivering 2.4 MWe of standby power for data centers, with HVO compatibility
and methanol-ready capability.
Broadens the availability of
high-power backup generators with alternative-fuel compatibility.

Data Center Generator Market Scope: Inquire before buying

Data Center Generator Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 9 USD Billion
Forecast Period 2026-2034 CAGR: 6.6% Market Size in 2034: 16 USD Billion
Segments Covered: by Fuel Type Diesel
Natural Gas
Bi-Fuel/Dual-Fuel
Hydrogen
Others
by Power Rating ≤1 MW
1–2 MW
2–3 MW
>3 MW
by Operating Duty Standby/Emergency Power
Prime Power
Continuous Power
by Redundancy Architecture N
N+1
2N
2N+1
Others
by Data Center Type Hyperscale Data Centers
Colocation Data Centers
Enterprise Data Centers
Edge Data Centers
Others
by Data Center Tier Tier I & II
Tier III
Tier IV
Non-Tier/Other
by Installation Type New/Greenfield Installation
Expansion/Capacity Addition
Replacement/Retrofit

Data Center Generator Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Data Center Generator Market Key Players

1. Aggreko plc
2. Atlas Copco AB
3. Caterpillar Inc.
4. Cummins Inc.
5. DEUTZ AG
6. Euro-Diesel
7. Generac Power Systems, Inc.
8. HITEC Power Protection
9. HITZINGER GmbH
10. INMESOL S.L.U.
11. INNIO Group
12. Kirloskar Oil Engines Limited (KOEL)
13. Rehlko (formerly Kohler Energy / KOHLER-SDMO)
14. Mitsubishi Heavy Industries, Ltd.
15. ONIS VISA
16. Perkins Engines Company Limited
17. Rolls-Royce Power Systems (mtu)
18. Yanmar Holdings Co., Ltd.
19. Aksa Power Generation
20. Alterra Power Systems
21. Ausonia S.r.l.
22. CK Power
23. DCS Technology
24. Detroit Diesel Corporation
25. FG Wilson
26. Genesal Energy
27. JCB Power Products
28. Mainspring Energy, Inc.
29. Plug Power Inc.
30. Vital Power
31. HIMOINSA S.L.
32. Wärtsilä Corporation
33. GE Vernova Inc.
34. Doosan Portable Power
35. Weichai Power Co., Ltd.
36. Teksan Generator
37. Pramac S.p.A.
38. Volvo Penta
39. Ashok Leyland Limited
40. Mahindra Powerol
41. Jakson Group
42. Powerica Limited
43. Sudhir Power Limited
44. Sterling Generators
45. OJUS Power and Technologies
46. Pinnacle Generators
47. RAI Power

Frequently Asked Questions:

1. What is the global data center generator market size in 2025?
Ans. The global data center generator market is valued at USD 9 billion in 2025.

2. What is the projected market size by 2034?
Ans. The market is projected to reach USD 16 billion by 2034.

3. What is the CAGR of the global data center generator market?
Ans. The market grows at a CAGR of 6.6% during the forecast period 2026–2034.

4. Which region dominates the global data center generator market?
Ans. North America dominates the market due to its established data center infrastructure and strong hyperscale and AI infrastructure investments.

5. What are the major factors driving the data center generator market?
Ans. Increasing AI adoption, cloud computing, rising electricity consumption, grid constraints, and the need for uninterrupted power supply drive market growth.

Table of Contents

1. Data Center Generator Market Introduction 1.1. Study Assumption and Market Definition 1.2. Scope of the Study 1.3. Executive Summary 2. Global Data Center Generator Market: Competitive Landscape 2.1. MMR Competition Matrix 2.2. Competitive Landscape 2.3. Key Players Benchmarking 2.3.1. Company Name 2.3.2. Business Segment 2.3.3. End-user Segment 2.3.4. Revenue (2025) 2.3.5. Company Locations 2.4. Leading Data Center Generator Market Companies, by market capitalization 2.5. Market Structure 2.5.1. Market Leaders 2.5.2. Market Followers 2.5.3. Emerging Players 2.6. Mergers and Acquisitions Details 3. Data Center Generator Market: Dynamics 3.1. Data Center Generator Market Trends by Region 3.1.1. North America Data Center Generator Market Trends 3.1.2. Europe Data Center Generator Market Trends 3.1.3. Asia Pacific Data Center Generator Market Trends 3.1.4. Middle East and Africa Data Center Generator Market Trends 3.1.5. South America Data Center Generator Market Trends 3.2. Data Center Generator Market Dynamics by Region 3.2.1. North America 3.2.1.1. North America Data Center Generator Market Drivers 3.2.1.2. North America Data Center Generator Market Restraints 3.2.1.3. North America Data Center Generator Market Opportunities 3.2.1.4. North America Data Center Generator Market Challenges 3.2.2. Europe 3.2.2.1. Europe Data Center Generator Market Drivers 3.2.2.2. Europe Data Center Generator Market Restraints 3.2.2.3. Europe Data Center Generator Market Opportunities 3.2.2.4. Europe Data Center Generator Market Challenges 3.2.3. Asia Pacific 3.2.3.1. Asia Pacific Data Center Generator Market Drivers 3.2.3.2. Asia Pacific Data Center Generator Market Restraints 3.2.3.3. Asia Pacific Data Center Generator Market Opportunities 3.2.3.4. Asia Pacific Data Center Generator Market Challenges 3.2.4. Middle East and Africa 3.2.4.1. Middle East and Africa Data Center Generator Market Drivers 3.2.4.2. Middle East and Africa Data Center Generator Market Restraints 3.2.4.3. Middle East and Africa Data Center Generator Market Opportunities 3.2.4.4. Middle East and Africa Data Center Generator Market Challenges 3.2.5. South America 3.2.5.1. South America Data Center Generator Market Drivers 3.2.5.2. South America Data Center Generator Market Restraints 3.2.5.3. South America Data Center Generator Market Opportunities 3.2.5.4. South America Data Center Generator Market Challenges 3.3. PORTER's Five Forces Analysis 3.4. PESTLE Analysis 3.5. Technology Roadmap 3.6. Regulatory Landscape by Region 3.6.1. North America 3.6.2. Europe 3.6.3. Asia Pacific 3.6.4. Middle East and Africa 3.6.5. South America 3.7. Key Opinion Leader Analysis For Data Center Generator Industry 3.8. Analysis of Government Schemes and Initiatives For Data Center Generator Industry 3.9. Data Center Generator Market Trade Analysis 3.10. The Global Pandemic Impact on Data Center Generator Market 4. Data Center Generator Market: Global Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 4.1. Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 4.1.1. Diesel 4.1.2. Natural Gas 4.1.3. Bi-Fuel/Dual-Fuel 4.1.4. Hydrogen 4.1.5. Others 4.2. Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 4.2.1. ≤1 MW 4.2.2. 1–2 MW 4.2.3. 2–3 MW 4.2.4. >3 MW 4.3. Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 4.3.1. Standby/Emergency Power 4.3.2. Prime Power 4.3.3. Continuous Power 4.4. Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 4.4.1. N 4.4.2. N+1 4.4.3. 2N 4.4.4. 2N+1 4.4.5. Others 4.5. Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 4.5.1. Hyperscale Data Centers 4.5.2. Colocation Data Centers 4.5.3. Enterprise Data Centers 4.5.4. Edge Data Centers 4.5.5. Others 4.6. Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 4.6.1. Tier I & II 4.6.2. Tier III 4.6.3. Tier IV 4.6.4. Non-Tier/Other 4.7. Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 4.7.1. New/Greenfield Installation 4.7.2. Expansion/Capacity Addition 4.7.3. Replacement/Retrofit 4.8. Data Center Generator Market Size and Forecast, by Region (2025-2034) 4.8.1. North America 4.8.2. Europe 4.8.3. Asia Pacific 4.8.4. Middle East and Africa 4.8.5. South America 5. North America Data Center Generator Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 5.1. North America Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 5.1.1. Diesel 5.1.2. Natural Gas 5.1.3. Bi-Fuel/Dual-Fuel 5.1.4. Hydrogen 5.1.5. Others 5.2. North America Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 5.2.1. ≤1 MW 5.2.2. 1–2 MW 5.2.3. 2–3 MW 5.2.4. >3 MW 5.3. North America Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 5.3.1. Standby/Emergency Power 5.3.2. Prime Power 5.3.3. Continuous Power 5.4. North America Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 5.4.1. N 5.4.2. N+1 5.4.3. 2N 5.4.4. 2N+1 5.4.5. Others 5.5. North America Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 5.5.1. Hyperscale Data Centers 5.5.2. Colocation Data Centers 5.5.3. Enterprise Data Centers 5.5.4. Edge Data Centers 5.5.5. Others 5.6. North America Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 5.6.1. Tier I & II 5.6.2. Tier III 5.6.3. Tier IV 5.6.4. Non-Tier/Other 5.7. North America Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 5.7.1. New/Greenfield Installation 5.7.2. Expansion/Capacity Addition 5.7.3. Replacement/Retrofit 5.8. North America Data Center Generator Market Size and Forecast, by Country (2025-2034) 5.8.1. United States 5.8.1.1. United States Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 5.8.1.1.1. Diesel 5.8.1.1.2. Natural Gas 5.8.1.1.3. Bi-Fuel/Dual-Fuel 5.8.1.1.4. Hydrogen 5.8.1.1.5. Others 5.8.1.2. United States Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 5.8.1.2.1. ≤1 MW 5.8.1.2.2. 1–2 MW 5.8.1.2.3. 2–3 MW 5.8.1.2.4. >3 MW 5.8.1.3. United States Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 5.8.1.3.1. Standby/Emergency Power 5.8.1.3.2. Prime Power 5.8.1.3.3. Continuous Power 5.8.1.4. United States Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 5.8.1.4.1. N 5.8.1.4.2. N+1 5.8.1.4.3. 2N 5.8.1.4.4. 2N+1 5.8.1.4.5. Others 5.8.1.5. United States Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 5.8.1.5.1. Hyperscale Data Centers 5.8.1.5.2. Colocation Data Centers 5.8.1.5.3. Enterprise Data Centers 5.8.1.5.4. Edge Data Centers 5.8.1.5.5. Others 5.8.1.6. United States Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 5.8.1.6.1. Tier I & II 5.8.1.6.2. Tier III 5.8.1.6.3. Tier IV 5.8.1.6.4. Non-Tier/Other 5.8.1.7. United States Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 5.8.1.7.1. New/Greenfield Installation 5.8.1.7.2. Expansion/Capacity Addition 5.8.1.7.3. Replacement/Retrofit 5.8.2. Canada 5.8.2.1. Canada Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 5.8.2.1.1. Diesel 5.8.2.1.2. Natural Gas 5.8.2.1.3. Bi-Fuel/Dual-Fuel 5.8.2.1.4. Hydrogen 5.8.2.1.5. Others 5.8.2.2. Canada Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 5.8.2.2.1. ≤1 MW 5.8.2.2.2. 1–2 MW 5.8.2.2.3. 2–3 MW 5.8.2.2.4. >3 MW 5.8.2.3. Canada Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 5.8.2.3.1. Standby/Emergency Power 5.8.2.3.2. Prime Power 5.8.2.3.3. Continuous Power 5.8.2.4. Canada Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 5.8.2.4.1. N 5.8.2.4.2. N+1 5.8.2.4.3. 2N 5.8.2.4.4. 2N+1 5.8.2.4.5. Others 5.8.2.5. Canada Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 5.8.2.5.1. Hyperscale Data Centers 5.8.2.5.2. Colocation Data Centers 5.8.2.5.3. Enterprise Data Centers 5.8.2.5.4. Edge Data Centers 5.8.2.5.5. Others 5.8.2.6. Canada Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 5.8.2.6.1. Tier I & II 5.8.2.6.2. Tier III 5.8.2.6.3. Tier IV 5.8.2.6.4. Non-Tier/Other 5.8.2.7. Canada Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 5.8.2.7.1. New/Greenfield Installation 5.8.2.7.2. Expansion/Capacity Addition 5.8.2.7.3. Replacement/Retrofit 5.8.3. Mexico 5.8.3.1. Mexico Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 5.8.3.1.1. Diesel 5.8.3.1.2. Natural Gas 5.8.3.1.3. Bi-Fuel/Dual-Fuel 5.8.3.1.4. Hydrogen 5.8.3.1.5. Others 5.8.3.2. Mexico Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 5.8.3.2.1. ≤1 MW 5.8.3.2.2. 1–2 MW 5.8.3.2.3. 2–3 MW 5.8.3.2.4. >3 MW 5.8.3.3. Mexico Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 5.8.3.3.1. Standby/Emergency Power 5.8.3.3.2. Prime Power 5.8.3.3.3. Continuous Power 5.8.3.4. Mexico Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 5.8.3.4.1. N 5.8.3.4.2. N+1 5.8.3.4.3. 2N 5.8.3.4.4. 2N+1 5.8.3.4.5. Others 5.8.3.5. Mexico Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 5.8.3.5.1. Hyperscale Data Centers 5.8.3.5.2. Colocation Data Centers 5.8.3.5.3. Enterprise Data Centers 5.8.3.5.4. Edge Data Centers 5.8.3.5.5. Others 5.8.3.6. Mexico Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 5.8.3.6.1. Tier I & II 5.8.3.6.2. Tier III 5.8.3.6.3. Tier IV 5.8.3.6.4. Non-Tier/Other 5.8.3.7. Mexico Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 5.8.3.7.1. New/Greenfield Installation 5.8.3.7.2. Expansion/Capacity Addition 5.8.3.7.3. Replacement/Retrofit 6. Europe Data Center Generator Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 6.1. Europe Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.2. Europe Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.3. Europe Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.4. Europe Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.5. Europe Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.6. Europe Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.7. Europe Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8. Europe Data Center Generator Market Size and Forecast, by Country (2025-2034) 6.8.1. United Kingdom 6.8.1.1. United Kingdom Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.1.2. United Kingdom Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.1.3. United Kingdom Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.1.4. United Kingdom Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.1.5. United Kingdom Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.1.6. United Kingdom Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.1.7. United Kingdom Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.2. France 6.8.2.1. France Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.2.2. France Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.2.3. France Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.2.4. France Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.2.5. France Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.2.6. France Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.2.7. France Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.3. Germany 6.8.3.1. Germany Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.3.2. Germany Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.3.3. Germany Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.3.4. Germany Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.3.5. Germany Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.3.6. Germany Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.3.7. Germany Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.4. Italy 6.8.4.1. Italy Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.4.2. Italy Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.4.3. Italy Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.4.4. Italy Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.4.5. Italy Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.4.6. Italy Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.4.7. Italy Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.5. Spain 6.8.5.1. Spain Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.5.2. Spain Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.5.3. Spain Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.5.4. Spain Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.5.5. Spain Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.5.6. Spain Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.5.7. Spain Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.6. Sweden 6.8.6.1. Sweden Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.6.2. Sweden Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.6.3. Sweden Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.6.4. Sweden Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.6.5. Sweden Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.6.6. Sweden Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.6.7. Sweden Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.7. Austria 6.8.7.1. Austria Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.7.2. Austria Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.7.3. Austria Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.7.4. Austria Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.7.5. Austria Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.7.6. Austria Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.7.7. Austria Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 6.8.8. Rest of Europe 6.8.8.1. Rest of Europe Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 6.8.8.2. Rest of Europe Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 6.8.8.3. Rest of Europe Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 6.8.8.4. Rest of Europe Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 6.8.8.5. Rest of Europe Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 6.8.8.6. Rest of Europe Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 6.8.8.7. Rest of Europe Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7. Asia Pacific Data Center Generator Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 7.1. Asia Pacific Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.2. Asia Pacific Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.3. Asia Pacific Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.4. Asia Pacific Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.5. Asia Pacific Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.6. Asia Pacific Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.7. Asia Pacific Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8. Asia Pacific Data Center Generator Market Size and Forecast, by Country (2025-2034) 7.8.1. China 7.8.1.1. China Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.1.2. China Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.1.3. China Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.1.4. China Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.1.5. China Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.1.6. China Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.1.7. China Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.2. S Korea 7.8.2.1. S Korea Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.2.2. S Korea Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.2.3. S Korea Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.2.4. S Korea Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.2.5. S Korea Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.2.6. S Korea Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.2.7. S Korea Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.3. Japan 7.8.3.1. Japan Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.3.2. Japan Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.3.3. Japan Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.3.4. Japan Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.3.5. Japan Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.3.6. Japan Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.3.7. Japan Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.4. India 7.8.4.1. India Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.4.2. India Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.4.3. India Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.4.4. India Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.4.5. India Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.4.6. India Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.4.7. India Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.5. Australia 7.8.5.1. Australia Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.5.2. Australia Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.5.3. Australia Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.5.4. Australia Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.5.5. Australia Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.5.6. Australia Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.5.7. Australia Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.6. Indonesia 7.8.6.1. Indonesia Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.6.2. Indonesia Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.6.3. Indonesia Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.6.4. Indonesia Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.6.5. Indonesia Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.6.6. Indonesia Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.6.7. Indonesia Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.7. Malaysia 7.8.7.1. Malaysia Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.7.2. Malaysia Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.7.3. Malaysia Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.7.4. Malaysia Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.7.5. Malaysia Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.7.6. Malaysia Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.7.7. Malaysia Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.8. Vietnam 7.8.8.1. Vietnam Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.8.2. Vietnam Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.8.3. Vietnam Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.8.4. Vietnam Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.8.5. Vietnam Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.8.6. Vietnam Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.8.7. Vietnam Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.9. Taiwan 7.8.9.1. Taiwan Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.9.2. Taiwan Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.9.3. Taiwan Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.9.4. Taiwan Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.9.5. Taiwan Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.9.6. Taiwan Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.9.7. Taiwan Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 7.8.10. Rest of Asia Pacific 7.8.10.1. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 7.8.10.2. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 7.8.10.3. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 7.8.10.4. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 7.8.10.5. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 7.8.10.6. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 7.8.10.7. Rest of Asia Pacific Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 8. Middle East and Africa Data Center Generator Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 8.1. Middle East and Africa Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 8.2. Middle East and Africa Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 8.3. Middle East and Africa Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 8.4. Middle East and Africa Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 8.5. Middle East and Africa Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 8.6. Middle East and Africa Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 8.7. Middle East and Africa Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 8.8. Middle East and Africa Data Center Generator Market Size and Forecast, by Country (2025-2034) 8.8.1. South Africa 8.8.1.1. South Africa Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 8.8.1.2. South Africa Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 8.8.1.3. South Africa Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 8.8.1.4. South Africa Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 8.8.1.5. South Africa Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 8.8.1.6. South Africa Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 8.8.1.7. South Africa Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 8.8.2. GCC 8.8.2.1. GCC Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 8.8.2.2. GCC Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 8.8.2.3. GCC Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 8.8.2.4. GCC Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 8.8.2.5. GCC Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 8.8.2.6. GCC Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 8.8.2.7. GCC Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 8.8.3. Nigeria 8.8.3.1. Nigeria Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 8.8.3.2. Nigeria Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 8.8.3.3. Nigeria Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 8.8.3.4. Nigeria Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 8.8.3.5. Nigeria Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 8.8.3.6. Nigeria Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 8.8.3.7. Nigeria Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 8.8.4. Rest of ME&A 8.8.4.1. Rest of ME&A Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 8.8.4.2. Rest of ME&A Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 8.8.4.3. Rest of ME&A Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 8.8.4.4. Rest of ME&A Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 8.8.4.5. Rest of ME&A Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 8.8.4.6. Rest of ME&A Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 8.8.4.7. Rest of ME&A Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 9. South America Data Center Generator Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 9.1. South America Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 9.2. South America Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 9.3. South America Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 9.4. South America Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 9.5. South America Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 9.6. South America Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 9.7. South America Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 9.8. South America Data Center Generator Market Size and Forecast, by Country (2025-2034) 9.8.1. Brazil 9.8.1.1. Brazil Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 9.8.1.2. Brazil Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 9.8.1.3. Brazil Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 9.8.1.4. Brazil Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 9.8.1.5. Brazil Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 9.8.1.6. Brazil Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 9.8.1.7. Brazil Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 9.8.2. Argentina 9.8.2.1. Argentina Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 9.8.2.2. Argentina Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 9.8.2.3. Argentina Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 9.8.2.4. Argentina Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 9.8.2.5. Argentina Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 9.8.2.6. Argentina Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 9.8.2.7. Argentina Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 9.8.3. Rest Of South America 9.8.3.1. Rest Of South America Data Center Generator Market Size and Forecast, by Fuel Type (2025-2034) 9.8.3.2. Rest Of South America Data Center Generator Market Size and Forecast, by Power Rating (2025-2034) 9.8.3.3. Rest Of South America Data Center Generator Market Size and Forecast, by Operating Duty (2025-2034) 9.8.3.4. Rest Of South America Data Center Generator Market Size and Forecast, by Redundancy Architecture (2025-2034) 9.8.3.5. Rest Of South America Data Center Generator Market Size and Forecast, by Data Center Type (2025-2034) 9.8.3.6. Rest Of South America Data Center Generator Market Size and Forecast, by Data Center Tier (2025-2034) 9.8.3.7. Rest Of South America Data Center Generator Market Size and Forecast, by Installation Type (2025-2034) 10. Company Profile: Key Players 10.1. Aggreko plc 10.1.1. Company Overview 10.1.2. Business Portfolio 10.1.3. Financial Overview 10.1.4. SWOT Analysis 10.1.5. Strategic Analysis 10.1.6. Scale of Operation (small, medium, and large) 10.1.7. Details on Partnership 10.1.8. Regulatory Accreditations and Certifications Received by Them 10.1.9. Awards Received by the Firm 10.1.10. Recent Developments 10.2. Atlas Copco AB 10.3. Caterpillar Inc. 10.4. Cummins Inc. 10.5. DEUTZ AG 10.6. Euro-Diesel 10.7. Generac Power Systems, Inc. 10.8. HITEC Power Protection 10.9. HITZINGER GmbH 10.10. INMESOL S.L.U. 10.11. INNIO Group 10.12. Kirloskar Oil Engines Limited (KOEL) 10.13. Rehlko (formerly Kohler Energy / KOHLER-SDMO) 10.14. Mitsubishi Heavy Industries, Ltd. 10.15. ONIS VISA 10.16. Perkins Engines Company Limited 10.17. Rolls-Royce Power Systems (mtu) 10.18. Yanmar Holdings Co., Ltd. 10.19. Aksa Power Generation 10.20. Alterra Power Systems 10.21. Ausonia S.r.l. 10.22. CK Power 10.23. DCS Technology 10.24. Detroit Diesel Corporation 10.25. FG Wilson 10.26. Genesal Energy 10.27. JCB Power Products 10.28. Mainspring Energy, Inc. 10.29. Plug Power Inc. 10.30. Vital Power 10.31. HIMOINSA S.L. 10.32. Wärtsilä Corporation 10.33. GE Vernova Inc. 10.34. Doosan Portable Power 10.35. Weichai Power Co., Ltd. 10.36. Teksan Generator 10.37. Pramac S.p.A. 10.38. Volvo Penta 10.39. Ashok Leyland Limited 10.40. Mahindra Powerol 11. Key Findings 12. Industry Recommendations 13. Data Center Generator Market: Research Methodology 14. Terms and Glossary

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements