
Agricultural Robots Market by Type, Application and Region - Global Market Size Estimation, Industry-Wide Analysis, Competitive Landscape Assessment & Long-Term Forecast to 2034
Overview
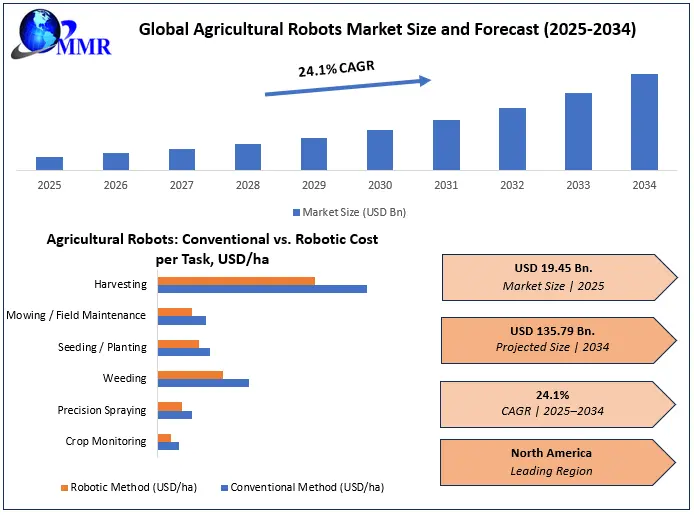
The Global Agricultural Robots Market was valued at USD 19.45 billion in 2025 and is projected to reach USD 135.79 billion by 2034, expanding at a 24.1% CAGR from 2025 to 2034. The Agricultural Robots Market comprises autonomous and semi-autonomous robotic systems used to automate agricultural activities, including planting, seeding, crop monitoring, weeding, spraying, harvesting, sorting, and farm logistics. The Agricultural Robots Market is moving from experimental automation toward practical, field-level deployment as farmers increasingly use robotics for planting, spraying, weeding, harvesting, crop monitoring, milking, and other repetitive operations. The combination of AI, computer vision, machine learning, GPS, IoT, and autonomous navigation is giving agricultural equipment greater ability to perceive field conditions and make task-level decisions. For example, John Deere has continued expanding autonomous agricultural machinery, while its Blue River Technology business has developed AI-powered See & Spray systems that identify crops and weeds in real time.
The report provides a comprehensive assessment of the Agricultural Robots Market segmentation by technology type, offering, farm size, application, deployment model, technology readiness and end-user, along with market dynamics, competitive landscape, technological developments, and strategic opportunities. The analysis covers market size, growth, and opportunity by region and country, highlighting differences in adoption, investment, technological readiness, and application potential. It also evaluates potential market gaps, emerging opportunities, and comparative performance across segments and geographies. North America is leading region, a key technology and adoption hub in Agricultural Robots Market, while Asia-Pacific offers significant growth opportunities driven by farm modernization, labor constraints, and increasing adoption of precision agriculture.
Global Agricultural Robots Market Size and Forecast (2025-2034)
To know about the Research Methodology:-Request Free Sample Report
Agricultural Robots Market Dynamics
Driver — Growing demand for farm productivity and operational efficiency:
The increasing need to improve farm productivity, reduce dependence on manual intervention, and maintain consistent field operations is accelerating the adoption of autonomous agricultural robots. These systems can perform repetitive activities such as seeding, weeding, spraying, monitoring, and harvesting with greater operational consistency. Economic assessments indicate potential labor-cost reductions of 20–30%, while individual robotic platforms can operate across 4–12 acres within 8–10 hours, depending on the task, crop, and operating conditions. This is strengthening the economic case for robotic automation, particularly in labor-intensive farming activities.
Restraint — High initial investment and limited affordability are slowing agricultural robot adoption among small and medium-sized farms.
Agricultural robots require substantial spending on robotic equipment, sensors, software, connectivity, and maintenance. A commercially deployed autonomous agricultural robotic system can involve investment ranging from tens of thousands to several hundred thousand US dollars, depending on its functionality and level of autonomy. These upfront costs can be difficult to justify for smaller farms with limited capital and uncertain returns on investment. As a result, RaaS, leasing and cooperative ownership models are becoming increasingly relevant for reducing the initial financial burden.
Opportunity — Advances in AI, computer vision, and autonomous navigation are creating new opportunities for precision-based agricultural robotics.
The integration of AI and advanced sensing technologies is allowing robots to identify crops, weeds, pests, and field conditions with greater accuracy. Modern robotic systems can combine multiple sensing technologies, including RGB cameras, multispectral cameras, LiDAR, radar and GNSS/RTK, to support real-time decisions. Precision robotics can potentially reduce unnecessary chemical application by 20–50% in specific targeted spraying or weeding applications, depending on crop type, field conditions and system performance. This is opening opportunities for targeted spraying, autonomous harvesting, precision weeding, and real-time crop monitoring.
Challenge — Difficult field conditions and the diversity of crops make it challenging to develop robots that can operate reliably across different agricultural environments.
Uneven terrain, changing weather, varying crop structures, soil conditions, and differences in farming practices can affect robotic performance. Agricultural robots may need to operate across fields ranging from relatively uniform open farmland to highly variable orchards, vineyards and vegetable plots, making universal robotic designs difficult to achieve. In addition, harvesting systems may need to recognize and handle hundreds or even thousands of individual crops or plants during a single operating cycle, while avoiding damage to produce. Manufacturers therefore need to develop adaptable systems capable of functioning reliably across multiple crops and field conditions.
Agricultural Robots Market Key Market Trends
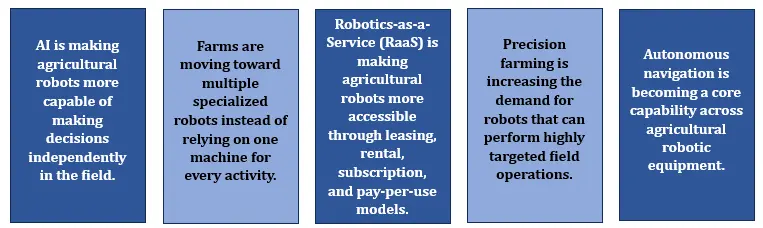
The agricultural robots market is increasingly shifting toward intelligent, autonomous, and task-specific solutions that improve efficiency and precision across farming operations. AI is enabling robots to interpret field conditions and perform operational decisions with reduced human intervention, while farms are increasingly adopting specialized robotic systems designed for activities such as weeding, spraying, harvesting, and crop monitoring. Robotics-as-a-Service (RaaS) is emerging as an alternative deployment model by lowering the upfront investment through rental, subscription, and pay-per-use arrangements. At the same time, the expansion of precision farming is creating demand for robots capable of targeted field operations, supported by advances in autonomous navigation, machine vision, sensor integration, and real-time data processing.
Agricultural Robots Market Key Market Trends
Agricultural Robots Market – Segment Analysis
The Agricultural Robotics Market segmentation covers Robot Type, Offering, Farming Environment, Farm Size, Application, and End-User.
By Technology Type
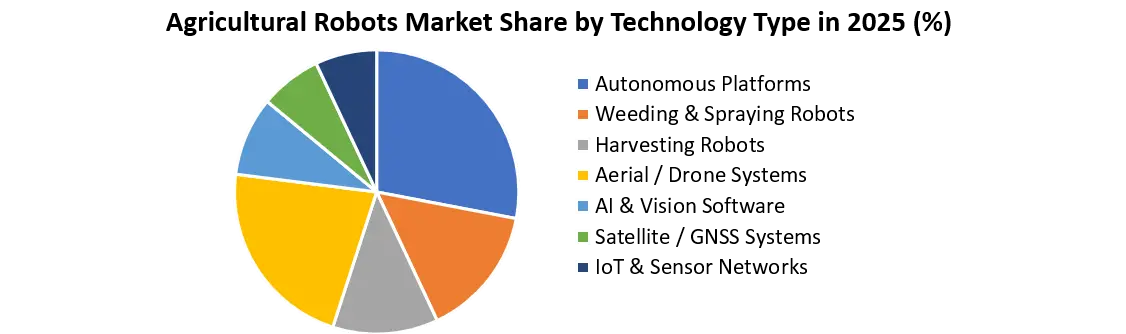
The Agricultural Robots Market is segmented into autonomous platforms, weeding and spraying robots, harvesting robots, aerial/drone systems, AI and vision software, satellite/GNSS systems, and IoT & sensor networks. Autonomous platforms form the foundation of farm automation, while weeding, spraying and harvesting robots are gaining traction for labor-intensive activities. Aerial systems support crop monitoring and precision application, whereas AI, vision, GNSS and sensor technologies are increasingly being integrated into robots to improve navigation, crop identification and decision-making. The market is gradually shifting from standalone robotic machines toward connected systems combining robotics, AI, positioning and farm data.
By Application
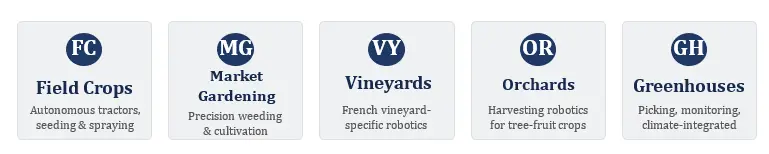
The market covers field crops, market gardening, vineyards, orchards, and greenhouses. Field crops remain a major application area because large farms benefit from autonomous machinery, precision spraying and automated monitoring across extensive acreage. At the same time, orchards, vineyards and greenhouses are becoming attractive areas for specialized robots because they involve labor-intensive and precision-sensitive activities such as harvesting, pruning, crop inspection and targeted treatment. As robotic systems become smaller and more capable of handling delicate tasks, their use is expected to expand beyond large open fields into high-value and controlled farming environments.
Agricultural Robots Market Application Landscape
| “The commercial value of agricultural robots is shifting from simple labour replacement toward precision-based farm management, where robots combine physical operations with real-time crop and field intelligence.”
-Krishna Ghorpade |
Agricultural Robots Market Commercial Use Case
| Commercial Use Case | How Agricultural Robots Are Used | Commercial Benefit |
| Autonomous Crop Monitoring | Monitor crop health and detect stressed areas. | Faster problem detection |
| Precision Weeding | Identify and remove weeds using AI. | Lower chemical and labor costs |
| Automated Harvesting | Identify and pick mature crops. | Reduces seasonal labor needs |
| Autonomous Spraying | Apply inputs to targeted areas. | Less input wastage |
| Autonomous Planting & Seeding | Place seeds at precise depths and spacing. | Better planting consistency |
| Greenhouse Automation | Inspect, transport, and harvest crops. | Lower routine labor |
| Dairy Farm Automation | Automate milking and monitor animals. | Reduced manual workload |
| Autonomous Farm Transportation | Move crops and materials around farms. | Saves time and labor |
| Livestock Monitoring | Track animal movement and behavior. | Earlier issue detection |
| Orchard & Vineyard Management | Monitor, spray, prune, and harvest crops. | Better specialty-crop efficiency |
Regional Analysis – Agricultural Robots Market
North America remains a leading region for agricultural robotics, supported by large-scale commercial farming, high labor costs, advanced mechanization, and strong investment in autonomous equipment. The region has a well-developed ecosystem spanning autonomous tractors, precision agriculture, robotic milking, machine vision, and connected farm machinery. The presence of large farms allows producers to spread technology investments across higher operating areas, improving the commercial viability of expensive robotic systems. The region is also moving beyond basic automation toward AI-enabled autonomous field operations, strengthening its position as a technology and commercialization hub for agricultural robotics.
Europe represents a mature and innovation-driven agricultural robotics market, with adoption closely linked to labor availability, sustainable farming practices, and the need to improve input efficiency. The region has developed strong capabilities in precision weeding, vineyard robotics, autonomous field platforms, dairy automation, and robotic harvesting. European farms and technology developers are increasingly focused on robots that can reduce chemical inputs, improve resource utilization, and perform specialized tasks in challenging agricultural environments. France, Germany, the Netherlands, and other technology-intensive agricultural markets are contributing to the development of specialized robotic solutions, while sustainability objectives and agricultural modernization are supporting continued adoption.
Asia Pacific is emerging as a high-growth center for agricultural robotics, driven by extensive agricultural activity, rising mechanization, labor availability challenges, and rapid adoption of AI, drones, sensors, and autonomous technologies. China has established a strong position in agricultural drone deployment, while Japan is advancing robotics for labor-intensive farming and an aging agricultural workforce. India is also gaining momentum through precision spraying, crop monitoring, autonomous equipment, and technology-led farm mechanization. The region's combination of large agricultural production bases and diverse farming conditions creates substantial opportunities for both high-capacity autonomous machinery and lower-cost robotic platforms designed for smaller farms.
South America offers significant long-term potential for agricultural robotics, particularly because of its extensive commercial farming operations and large cultivated areas. Brazil represents the region's key adoption market, where large-scale soybean, corn, sugarcane, and other crop production can support the economics of autonomous machinery and precision technologies. Agricultural drones, automated spraying, crop monitoring, precision planting, and autonomous field equipment are gaining relevance as producers seek higher productivity and more efficient use of land, labor, and agricultural inputs. The region is expected to increasingly adopt robotics where large farm sizes and repetitive field operations provide a strong return-on-investment opportunity.
Middle East & Africa represents an emerging agricultural robotics market with application-led growth opportunities. Water scarcity, climatic stress, limited arable land in several markets, labor constraints, and increasing investment in controlled-environment agriculture are creating demand for technologies that can improve productivity while optimizing resource consumption. Robotics is gaining relevance in greenhouse operations, precision irrigation, agricultural drones, crop monitoring, and automated field activities. Countries investing in smart agriculture and controlled-environment farming are likely to create early adoption pockets, while the wider regional market can develop as robotic technologies become more affordable and adaptable to local farming conditions.
Recent Developments in the Agricultural Robots Industry
• February 2026 – John Deere expanded its startup collaboration ecosystem: John Deere selected a new group of technology startups for its 2026 collaborator program, focusing on AI, advanced sensing, analytics, and automation. This shows that major agricultural-equipment companies are increasingly using partnerships with startups to accelerate robotics and intelligent-farming capabilities.
• January 2026 – Naïo Technologies increased its focus on commercializing specialty-crop robots: Naïo Technologies entered 2026 with a new financing and expansion plan aimed at increasing robot production. Its portfolio covers autonomous machines for vegetables, vineyards, and other specialty crops, indicating growing commercialization of smaller task-specific agricultural robots.
• August 2026 – Low-cost robotics is emerging as a solution for smaller farms: Researchers developed a modular agricultural robot using second-life electric-vehicle components, combined with on-device AI for weed detection. The approach demonstrates how recycled components and edge AI could substantially reduce the hardware cost of agricultural automation.
• August 2026 – AI-powered navigation is improving autonomous field operations: A new autonomous tractor approach combines LiDAR, computer vision, GNSS, IMU, wheel odometry, and AI-based weed detection to maintain navigation when satellite signals deteriorate. This development is particularly relevant for precision farming in dense crops where conventional GPS-based navigation can become unreliable.
• May 2026 – Robotic harvesting is becoming more intelligent through AI and simulation: Recent strawberry-harvesting research combined computer vision, deep reinforcement learning, and robotic manipulation to improve the ability of robots to identify and pick delicate fruit. This highlights the industry's movement toward crop-specific robots capable of handling complex harvesting environments.
Agricultural Robots Market Technology Landscape
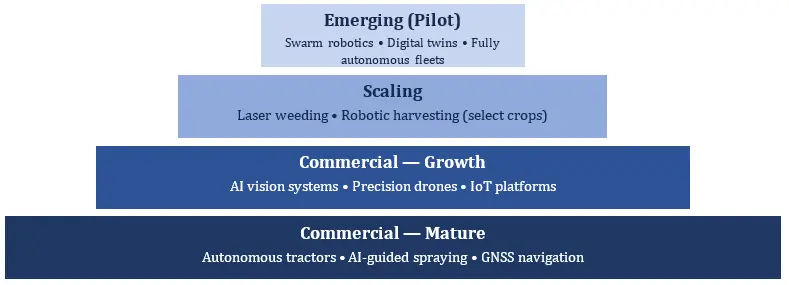
Commercial – Mature: Agricultural robotics is currently anchored by commercially proven technologies such as autonomous tractors, GNSS/RTK navigation, AI-guided spraying, agricultural drones, and IoT-enabled farm systems. These solutions have established applications across field operations, crop monitoring, spraying, and precision agriculture. Their adoption is supported by improving automation capabilities, established hardware ecosystems, and increasing integration with farm management platforms.
Commercial – Growth: AI vision systems, precision spraying and weeding, sensor-fusion navigation, and fleet-management platforms are moving into broader commercial adoption. These technologies enable robots to identify crops and weeds, navigate changing field conditions, and perform targeted operations with greater accuracy. Their integration is helping shift agricultural robots from basic automated equipment toward intelligent, data-driven systems.
Scaling: Laser weeding, robotic harvesting, multi-tool autonomous platforms, and vision-based crop navigation are progressing from field validation toward wider commercial deployment. These technologies address labor-intensive activities where conventional automation has limitations. Adoption is expected to expand as improvements in computer vision, robotic manipulation, navigation, and platform flexibility enhance reliability across different crops and farming environments.
Emerging (Pilot): Swarm robotics, digital twins, fully autonomous fleets, and multi-robot coordination represent the emerging frontier of agricultural automation. These technologies aim to enable multiple machines to communicate, coordinate tasks, and adapt operations with limited human intervention. Although primarily at pilot and early-development stages, they could support the transition from individual robotic machines to integrated autonomous farm ecosystems.
Agricultural Robots Market Technology Landscape Pyramid
Agricultural Robots Market Competitive Landscape
The Agricultural Robots Market is becoming increasingly innovation-driven, with competition centered on AI, computer vision, autonomous navigation, precision agriculture, edge computing, and robotics-as-a-service (RaaS). Leading companies are moving beyond standalone machines by integrating robots with farm-management software, real-time field data, IoT connectivity, and autonomous decision-making. John Deere, CNH Industrial, AGCO, Kubota, DJI Agriculture, XAG, Naïo Technologies, Carbon Robotics, Lely, and DeLaval are strengthening their offerings across autonomous tractors, agricultural drones, precision weeding, harvesting, and dairy automation. A notable competitive shift is toward multi-task robotic platforms, crop-specific automation, AI-powered precision operations, and lower-cost service-based models, enabling companies to address both large commercial farms and smaller agricultural operations.
Agricultural Robots Market Major Companies
Competitive Positioning
Large Agricultural OEMs:
John Deere, CNH Industrial, AGCO and Kubota are competing through autonomous tractors, precision equipment, connected machinery and integrated farm-management platforms. Their major advantage is their existing equipment base and distribution network.
Agricultural Drone Leaders:
DJI and XAG are strengthening the aerial-robotics segment through automated spraying, crop monitoring, route planning and precision application. Their technology is particularly relevant where farmers need relatively flexible automation without replacing conventional farm machinery.
Specialized Robotics Companies:
Naïo Technologies, Carbon Robotics and ecoRobotix are targeting specific problems such as weeding, crop protection and specialty-crop management. Their competitive advantage comes from specialized AI, sensing and robotic mechanisms rather than broad agricultural-equipment portfolios.
Dairy Automation Players:
Lely and DeLaval have established strong positions in robotic milking, animal monitoring and automated dairy operations, making livestock automation an important competitive niche within the wider agricultural robotics industry.
Agricultural Robots Market Scope: Inquire before buying
| Agricultural Robots Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2032 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 19.45 Bn. |
| Forecast Period 2026 to 2032 CAGR: | 24.1% | Market Size in 2032: | USD 135.79 Bn. |
| Segments Covered: | by Technology Type | Autonomous Platforms Weeding & Spraying Robots Harvesting Robots Aerial / Drone Systems AI & Vision Software Satellite / GNSS Systems IoT & Sensor Networks |
|
| by Application | Field Crops Market Gardening Vineyards Orchards Greenhouses |
||
| by Farm Size | Small (<20 ha) Mid — 100-ha Reference Class Large (>150 ha) |
||
| by Offering / Component | Hardware AI & Vision Software Navigation (RTK/GNSS) Farm Management Platforms Service & Maintenance |
||
| by Deployment Model | Outright Purchase Robot-as-a-Service (RaaS) Leasing / Financing Cooperative / Shared-Use |
||
| by Technology Readiness | Commercial — Mature Commercial — Growth Scaling Pilot / Emerging |
||
| by End-User Type | Vocational Training Institutes Commercial Farms Cooperatives Research Institutions |
||
Agricultural Robots Market Key Players
1. AgXeed (Netherlands)
2. Monarch Tractor (USA)
3. Sabanto (USA)
4. Fendt — AGCO (Germany)
5. Kubota (Japan)
6. Yanmar (Japan)
7. CNH Industrial — Case IH / New Holland (USA/Italy)
8. Naïo Technologies (France)
9. Carbon Robotics (USA)
10. FarmWise (USA)
11. ecoRobotix (Switzerland)
12. Bilberry — AGCO (France)
13. GUSS Automation (USA)
14. Advanced Farm Technologies (USA)
15. Tortuga AgTech (USA)
16. Four Growers (USA)
17. Agrobot (Spain)
18. Vineyard & Specialty-Crop Robotics (France-relevant)
19. VitiBot — Bakus (France)
20. Meropy (France)
21. Agreenculture (France)
22. Blue River Technology — John Deere (USA)
23. Taranis (Israel)
24. Prospera Technologies — Valmont (Israel)
25. Solinftec (Brazil)
26. Verdant Robotics (USA)
27. XAG (China)
28. DJI Agriculture (China)
29. Parrot (France)
30. Delair (France)
31. Sentera (USA)
32. Trimble (USA)
33. Planet Labs (USA)
34. Hexagon Agriculture (Sweden)
35. CropX (Israel)
36. Netafim (Israel)
37. Sencrop (France)
38. Weenat (France)
39. Autonomous Farm Logistics
40. Burro (USA)
41. Small Robot Company (UK)