Battery Energy Storage System Market- Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

25.03%
CAGR (2026-2034)
13.89 USD Bn.
Forecast Market Size
311
Report Pages
164
Market Tables

Overview

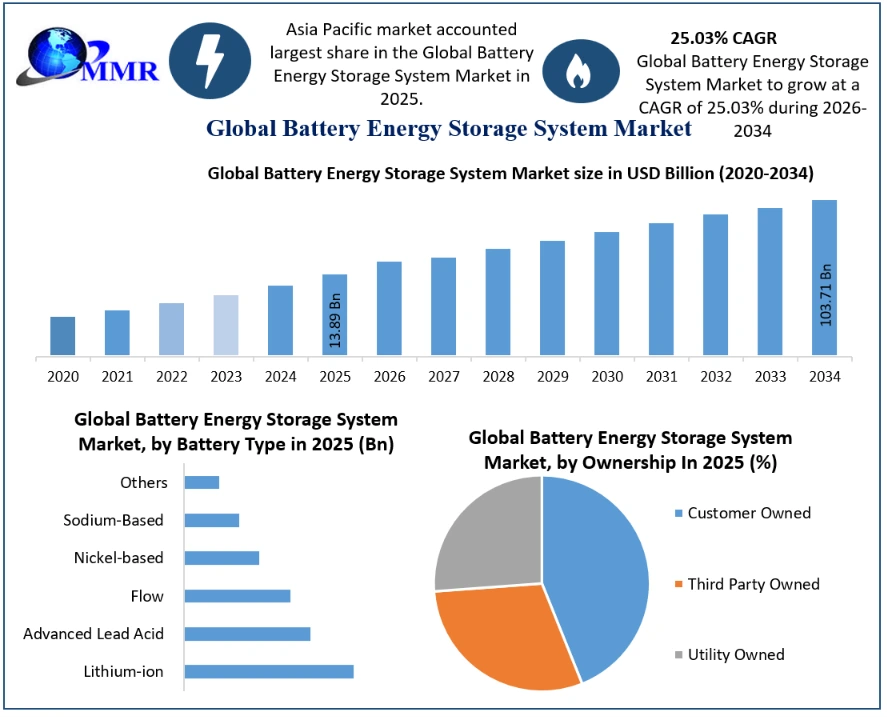
The Battery Energy Storage System Market size was valued at USD 13.89 Billion in 2025 and the total Battery Energy Storage System revenue is expected to grow at a CAGR of 25.03% from 2026 to 2034, reaching nearly USD 103.71 Billion.

The global Battery Energy Storage System (BESS) industry has experienced a substantial surge in recent years, driven by the accelerating transition to renewable energy sources, increasing grid modernization efforts, and the global push toward decarbonizationCompetitive dynamics in the BESS market are intensifying, with major global players such as Tesla Inc., LG Energy Solution, Panasonic Holdings, BYD Company Ltd., and Samsung SDI dominating the landscape. These companies lead in technological innovation, manufacturing capacity, and global distribution. However, the market also sees strong participation from regional specialists and new entrants, particularly in emerging economies, fostering a robust ecosystem characterized by vertical integration, strategic partnerships, and aggressive R&D investments.

In terms of regional penetration, Asia-Pacific remains the largest market, accounting for over 45% of global revenue share, primarily driven by China, Japan, South Korea, and India. China holds a dominant position both as the largest producer and leading consumer, owing to its massive manufacturing infrastructure, strong policy support, and booming electric vehicle (EV) and renewable energy sectors. North America, led by the United States, is experiencing rapid growth due to favorable regulatory policies such as the Inflation Reduction Act (IRA), grid resilience concerns, and increased residential and commercial adoption. Europe, particularly Germany, the UK, and the Nordics, is advancing due to aggressive decarbonization targets, clean energy mandates, and strong investment inflows.From a demand-supply perspective, there is currently a demand-supply imbalance, especially in high-capacity lithium-ion battery systems. The supply chain remains sensitive to raw material fluctuations, especially for lithium, cobalt, and nickel. While efforts to diversify supply and ramp up local production are underway, Asia continues to dominate upstream processing and cell manufacturing.

Consumer behavior is shifting from centralized, utility-scale storage to decentralized and behind-the-meter solutions, driven by energy independence goals, net metering benefits, and declining battery costs. Industrial and commercial users are also investing in BESS for peak shaving, backup power, and energy arbitrage.
Key industry investors and stakeholders—such as BlackRock, Brookfield Renewable Partners, Siemens Financial Services, and SoftBank Energy—are pouring capital into large-scale BESS projects, especially in hybrid renewable energy parks and microgrid setups. These investments are accelerating innovations in flow batteries, solid-state batteries, and second-life EV batteries, unlocking new market opportunities.

In conclusion, the BESS industry stands at a pivotal juncture, where market fundamentals, technological disruption, policy alignment, and sustainability goals are converging. Investors and stakeholders seeking future-proof, high-growth opportunities should not miss this transformative energy segment. This report offers a deep dive into market size, player strategies, cost trends, regional outlooks, and innovation pipelines — ideal for corporates, financial institutions, and policy makers.

Battery Energy Storage System Market Growth OutlookBattery Energy Storage System Market Growth
To know about the Research Methodology :- Request Free Sample Report

Battery Energy Storage System Market Dynamics 

 Accelerating Adoption of Battery Energy Storage Systems

The Battery Energy Storage System (BESS) market is primarily driven by the rapid growth of renewable energy integration, particularly solar and wind power, which require efficient energy storage solutions to manage intermittency. Increasing investments in grid-scale energy storage systems and utility-scale battery storage are supporting grid stability, frequency regulation, and peak load management. Governments worldwide are implementing energy storage policies, battery storage incentives, and decarbonization targets, which are boosting market demand. Additionally, the rising deployment of electric vehicle (EV) infrastructure is increasing the need for advanced battery storage systems to manage power demand and enable vehicle-to-grid (V2G) integration. Technological advancements in lithium-ion battery energy storage, along with improvements in battery management systems (BMS), are enhancing efficiency, safety, and lifecycle performance. Furthermore, the expansion of smart grids and distributed energy resources (DERs) is strengthening the role of BESS in modern energy ecosystems, making it a critical component for achieving reliable and sustainable power supply.

 Challenges Impacting BESS Market Growth

Despite strong growth potential, the BESS market faces several restraints that may hinder its expansion. One of the key challenges is the high initial investment cost associated with battery energy storage systems, including installation, integration, and maintenance expenses. Although lithium-ion battery costs are declining, large-scale deployment still requires significant capital, limiting adoption in cost-sensitive markets. Additionally, concerns related to battery safety, thermal runaway risks, and fire hazards pose operational challenges, especially in densely populated areas. The limited availability of raw materials such as lithium, cobalt, and nickel also creates supply chain constraints and price volatility in the battery storage market. Furthermore, the lack of standardized regulations and complex grid interconnection policies in certain regions can delay project approvals. Environmental concerns related to battery recycling and disposal also remain critical issues. These factors collectively act as barriers, impacting the widespread adoption of energy storage systems, particularly in emerging economies.

Expanding Applications and Technological Advancements

The BESS market presents significant opportunities driven by advancements in energy storage technologies and expanding application areas. The increasing adoption of renewable energy storage systems and the development of hybrid energy projects are creating strong demand for grid-scale battery storage. Emerging technologies such as solid-state batteries, flow batteries, and next-generation energy storage solutions are expected to enhance performance and reduce long-term costs. The growing focus on commercial and industrial (C&I) energy storage, residential battery storage systems, and microgrid energy storage solutions is opening new revenue streams. Additionally, the rise of electric vehicle integration, EV charging infrastructure, and vehicle-to-grid (V2G) systems is further expanding market potential. In developing regions, increasing demand for off-grid energy storage systems and backup power solutions is driving adoption. Strategic collaborations, investments, and innovations in AI-based energy management systems and battery analytics are also accelerating market growth, positioning BESS as a key enabler of the global clean energy transition.

Battery Energy Storage System Market Segment Analysis

Based on the type,Lithium-ion batteries accounted for nearly 53.5% of market revenue in 2025, driven by high energy density, long lifespan, and declining costs. Their extensive use in utility-scale renewable storage, commercial and industrial backup, microgrids, and EV charging highlights strong scalability and technological maturity. Continuous advancements in LFP and NMC chemistries have enhanced safety, thermal stability, and efficiency, reinforcing their dominance in short- to medium-duration applications. A robust global supply chain and supportive renewable energy policies further sustain growth.

Meanwhile, the flywheel segment is projected to grow at a CAGR of about 30.7%, supported by rising demand for rapid-response storage. Its high cycle life, fast charge-discharge capability, and reliability make it suitable for frequency regulation and critical power applications.

Based on the connection type, the on-grid connection segment is expected to grow at a significant CAGR between 2025 and 2034. The on-grid connection is used for supplying electricity to consumers, and it also used to reduce energy bills. Further, the factors contributed the growth of the market for on-grid battery energy storage systems are the load leveling, peak shaving, and power demand management are the main applications of any on-grid connected battery energy storage system installed with electrical grids.

Based on the application, the utilities application segment is expected to hold the major shares of the global battery storage system market during the forecast period. The generation and consumption of electricity need to be matched at all times. If the lead is mismatched then the voltage and frequency deviate and it causes power outages and damage to the equipment. To overcome this problem, the utilities install battery energy storage systems with the electric grids, which control the voltage and frequency deviations.

Battery Energy Storage System Market Regional Insights

The Asia-Pacific battery energy storage systems market accounted for around 44.5% of global share in 2025, supported by rapid renewable energy deployment, grid modernization, and increasing electrification. China dominates the region with strong manufacturing capabilities, aggressive solar and wind expansion, and favorable policies promoting energy storage integration across utility and distributed networks. Countries such as Japan, South Korea, and Australia are accelerating storage adoption to improve grid flexibility, enable peak load management, and support clean hydrogen development. Meanwhile, India is expanding battery storage capacity to stabilize renewable-heavy grids and strengthen rural microgrid infrastructure. Rising demand for grid reliability, growing digital infrastructure, and increasing public and private investments in clean energy continue to drive Asia-Pacific’s leadership in global BESS capacity expansion.

Battery Energy Storage System Industry Ecosystem

Battery Energy Storage System Market

Battery Energy Storage System Market Recent Developments:

Date Company Development Impact
15 June 2026 Wärtsilä Wärtsilä entered into a joint venture agreement with RCT Solutions GmbH to manage and scale its global Battery Energy Storage System (BESS) operations. The collaboration leverages U.S. manufacturing capabilities and vertical supply chain integration to accelerate long-duration BESS deployments.
16 September 2026 BYD Energy Storage BYD unveiled GC Block, a standardized station-level BESS architecture delivering up to 62 MWh capacity for gigawatt-scale grid-forming projects. The modular system utilizes high-capacity 1,980 Ah Blade Battery cells to reduce battery management complexity by 69.4% and cut maintenance workloads.
20 September 2026 Envision Energy Envision Energy successfully energized a 25 MW / 125 MWh LFP battery energy storage system at OCP Green Energy's Benguerir mining facility in Morocco. The milestone establishes Morocco's first large-scale lithium iron phosphate grid-balancing infrastructure dedicated to industrial mining operations.
14 October 2026 Sungrow Sungrow integrated onsemi's EliteSiC silicon carbide hybrid power modules into its next-generation PowerTitan 3.0 BESS platform. The high-density power architecture boosts inverter-level efficiency by 0.4% to meet escalating power demand from AI data centers and utility grids.
29 October 2026 CATL CATL globally launched its TENER+ 9 MWh ultra-high capacity storage system and TENER Sodium-ion BESS alongside three utility partnerships in Australia. The high-density design reduces container unit requirements by 40% while opening commercial deployments for sodium-ion BESS in high-temperature environments.

Battery Energy Storage System Market Scope Inquire before buying

Battery Energy Storage System Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 13.89 USD Billion
Forecast Period 2026-2034 CAGR: 25.03% Market Size in 2034: 103.71 USD Billion
Segments Covered: by Battery Type Lithium-ion Battery
Advanced Lead Acid Battery
Flow Battery
Nickel-based Battery
Sodium-Based Battery
Others
by Ownership Customer Owned
Third Party Owned
Utility Owned
by Energy Capacity Below 500 MWh
Between 100 MWh to 500 MWh
Above 500 MW
by Connection Type On Grid
Off Grid
by End User Utilities
Renewable Energy Developers
Commercial & Industrial (C&I)
Residential
Data Centers
Telecom Industry
Manufacturing Sector
Healthcare Facilities
Government & Defense
Transportation & Mobility
Others
by Application Renewable Energy Integration
Peak Shaving
Load Shifting
Frequency Regulation
Grid Stabilization
Backup Power
Energy Arbitrage
EV Charging Infrastructure
Microgrid Support
Others
by Deployment Type Front-of-the-Meter (FTM)
Behind-the-Meter (BTM
by System Hardware
Battery Packs/Modules
   Battery Management System (BMS)
   Power Conversion System (PCS)
    Inverters
    Energy Management System (EMS)
    Thermal Management System
    Transformers
    Containerized Storage Systems
Software
  Energy Optimization Software
    AI-Based Predictive Analytics Software
    Grid Monitoring & Control Platforms
Services
    Installation & Integration
    Maintenance & Monitoring
    Consulting & Engineering Services

Battery Energy Storage System Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest)

Key Players are:

Battery/Cell Manufacturers
1. CATL (Contemporary Amperex Technology Co., Limited)
1. BYD Company Ltd.
2. LG Energy Solution
3. Samsung SDI
4. Panasonic Energy
5. SK On
6. EVE Energy
7. CALB (China Aviation Lithium Battery)
8. Gotion High-Tech
9. Hithium
10. REPT BATTERO
11. Narada Power
Integrated BESS / System Manufacturers
13. Tesla Energy
14. Fluence Energy
15. Sungrow Power Supply Co., Ltd.
16. Trina Storage
17. Canadian Solar (e-STORAGE)
18. Envision Energy
19. Ampace
20. Kehua Tech
21. Pylontech (Pylon Technologies)
22. JinkoSolar
Industrial Conglomerates / Power & Grid Equipment
23. Wärtsilä Energy Storage
24. Hitachi Energy
25. GE Vernova
26. Siemens Energy
27. ABB Ltd.
28. Schneider Electric
29. Nidec ASI
30. Johnson Controls
31. Eaton Corporation
32. Vertiv Holdings
33. Delta Electronics
34. Huawei Digital Power
Specialty Battery / Storage
35. Saft (TotalEnergies)
36. EnerSys
37. Exide Industries
Residential/Commercial Storage
38. Enphase Energy
39. Bloom Energy
40. Generac Power Systems

Frequently Asked Questions:

1.Which region has the largest share in Global Battery Energy Storage System Market?

Ans: Asia Pacific region held the highest share in 2025.

2.What is the growth rate of Global Battery Energy Storage System Market?

Ans: The Global Battery Energy Storage System Market is growing at a CAGR of 25.03% during forecasting period 2026-2034.

3.What is scope of the Global Battery Energy Storage System Market report?

Ans: Global Battery Energy Storage System Market report helps with the PESTEL, PORTER, COVID-19 Impact analysis, Recommendations for Investors & Leaders, and market estimation of the forecast period.

4.Who are the key players in Global Battery Energy Storage System Market?

Ans: The important key players in the Global Battery Energy Storage System Market are – Tesla, Inc., BYD Company Ltd., Contemporary Amperex Technology Co., Limited (CATL), LG Energy Solution, Samsung SDI Co., Ltd., Fluence Energy, Inc., Saft (TotalEnergies), General Electric Company, Siemens Energy AG, Toshiba Corporation, Panasonic Holdings Corporation, and Sungrow Power Supply Co., Ltd.

5.What is the study period of this Market?

Ans: The Global Battery Energy Storage System Market is studied from 2020 to 2034.

Table of Contents

1. SECTION A – BATTERY ENERGY STORAGE SYSTEM MARKET INTRODUCTION 1.1 Executive Market Landscape and Industry Overview 1.1.1 Battery Energy Storage System Market Size Estimation and Growth Outlook (2025–2034) 1.1.2 Comprehensive Definition of the Battery Energy Storage System Market Ecosystem 1.1.3 Scope Boundaries Covering Cell Chemistry, Materials, Manufacturing Technologies, and End-use Applications 1.1.4 Competitive Landscape Overview: Global Manufacturers, Regional Players, New Entrants, and Technology Innovators 1.2 Battery Energy Storage System Market Dynamics 1.2.1 Battery Energy Storage System Market Trends 1.2.2 Drivers 1.2.2.1 Rapid Renewable Energy Capacity Expansion Globally 1.2.2.2 Increasing Grid Instability and Peak Demand Management Requirements 1.2.2.3 Government Incentives and Energy Transition Policies 1.2.2.4 Declining Lithium-Ion Battery Prices and Storage System Costs 1.2.3 Restraints 1.2.3.1 High Upfront Capital Investment for Large-Scale Projects 1.2.3.2 Battery Degradation and Replacement Concerns 1.2.3.3 Supply Chain Dependency on Critical Minerals 1.2.3.4 Regulatory Uncertainty in Energy Trading Markets 1.2.4 Opportunities 1.2.4.1 Energy Arbitrage and Merchant Storage Business Models 1.2.4.2 AI-Enabled Energy Optimization Platforms 1.2.4.3 Hybrid Renewable + Storage Project Expansion 1.2.4.4 Virtual Power Plants (VPPs) and Decentralized Energy Systems 1.2.5 Challenges 1.2.5.1 Grid Interconnection Bottlenecks 1.2.5.2 Fire Safety and Thermal Runaway Risks 1.2.5.3 Revenue Uncertainty Across Ancillary Service Markets 1.2.5.4 Limited Recycling Infrastructure for Storage Batteries 1.2.6 PORTER’s Five Forces Analysis 1.2.6.1 Supplier Power 1.2.6.2 Buyer Power 1.2.6.3 Threat of Substitutes 1.2.6.4 Threat of New Entrants 1.2.6.5 Competitive Rivalry 1.2.7 PESTLE Analysis 1.3 Battery Energy Storage System Industry Ecosystem Analysis Overview 1.3.1 Raw Material Suppliers 1.3.2 Lithium-Ion Battery Cell Production Ecosystem 1.3.3 LFP, NMC, Sodium-Ion, and Flow Battery Manufacturing 1.3.4 Cylindrical, Prismatic, and Pouch Cell Production 1.3.5 Battery Manufacturers 1.3.6 Battery Module and Rack Assembly 1.3.7 Containerized BESS Integration 1.3.8 Battery Management System (BMS) Integration 1.3.9 Energy Management & Digital Platform Providers 1.3.10 Energy Management System (EMS) Platforms 1.3.11 AI-Based Energy Optimization Ecosystem 1.3.12 Predictive Maintenance and Analytics Systems 1.3.13 Renewable Energy Developers & Utilities 1.3.14 Solar + Storage Project Ecosystem 1.3.15 Wind + Storage Integration Landscape 1.3.16 Grid Balancing and Ancillary Services Participation 1.3.17 End-Users 1.3.18 Utility-Scale Storage Procurement Strategy 1.3.19 Commercial & Industrial (C&I) Energy Optimization 1.3.20 Data Center and Telecom Backup Applications 1.3.21 EV Charging Infrastructure Integration 1.4 Battery Energy Storage System Industry Value Chain Analysis Overview 1.4.1 Generation 1.4.1.1 Storage as an Alternative to Conventional Peaking Power Plants 1.4.1.2 Grid-Scale Energy Balancing and Backup Capacity Support 1.4.1.3 Renewable Energy Stabilization and Power Quality Enhancement 1.4.2 Transmission & Distribution 1.4.2.1 Deferred Transmission & Distribution Infrastructure Investments 1.4.2.2 Grid Congestion Management and Reliability Enhancement 1.4.2.3 Renewable Energy Integration into Transmission Networks 1.4.3 Renewable Energy Integration 1.4.3.1 Renewable Intermittency Management 1.4.3.2 Renewable Energy Dispatch Optimization 1.4.3.3 Renewable Energy Curtailment Reduction 1.4.4 Consumers 1.4.4.1 Behind-the-Meter Energy Management Optimization 1.4.4.2 Power Reliability and Backup Energy Systems 1.4.4.3 Smart Commercial and Industrial Energy Optimization 1.4.5 ISO / Grid Operators 1.4.5.1 Grid Stability and Balancing Optimization 1.4.5.2 Dynamic Demand-Supply Management 1.4.5.3 Ancillary Services and Reserve Capacity Support 1.5 Battery Energy Storage Manufacturing Process and Technology Analysis 1.5.1 Battery Cell Manufacturing Process (Mixing, Coating, Calendaring, Assembly, Formation) 1.5.2 Module and Pack Integration Process Analysis 1.5.3 Containerized BESS Manufacturing Architecture 1.5.4 Differences Between Cylindrical, Prismatic, and Pouch Cell Technologies 1.5.5 LFP vs NMC Manufacturing Process Benchmarking 1.5.6 Automation Trends in Gigafactories and Smart Battery Production Facilities 1.5.7 AI-Enabled Quality Control and Defect Detection Systems 1.5.8 Yield Optimization and Manufacturing Efficiency Strategies 1.5.9 Thermal Management and Fire Protection System Integration 1.6 Battery Energy Storage System Volume & Capacity Statistics 1.6.1 Installed BESS Capacity (GWh) – Global (2020–2025) 1.6.2 Annual Deployment Capacity Additions (GWh Added per Year) 1.6.3 Installed Base by Battery Chemistry 1.6.3.1 LFP 1.6.3.2 NMC 1.6.3.3 Sodium-Ion 1.6.3.4 Flow Battery 1.6.4 Installed Base by Application 1.6.4.1 Utility-Scale 1.6.4.2 Commercial & Industrial 1.6.4.3 Residential 1.6.5 Installed Base by Power Rating 1.6.5.1 Below 100 MWh 1.6.5.2 100–500 MWh 1.6.5.3 Above 500 MWh 1.6.6 Installed Base by End-User Industry 1.6.7 Regional BESS Deployment Capacity Comparison 1.7 Technology Advancements in Battery Energy Storage Systems 1.7.1 Development of High-Density and Long-Duration Energy Storage Technologies 1.7.2 Advancements in Solid-State and Sodium-Ion Batteries 1.7.3 Integration of AI and Predictive Analytics in Energy Storage Systems 1.7.4 Fast-Response Frequency Regulation Technologies 1.7.5 Improvement in Battery Safety Systems and Thermal Management 1.7.6 Development of Modular and Scalable BESS Architecture 1.7.7 Cloud-Based EMS and Real-Time Monitoring Advancements 1.8 Innovation Trends Shaping Future Battery Energy Storage Development 1.8.1 Development of Next-Generation Storage Technologies 1.8.2 AI-Enabled Energy Dispatch and Optimization Systems 1.8.3 Integration of Digital Twins in BESS Operations 1.8.4 Vehicle-to-Grid (V2G) and Bidirectional Charging Developments 1.8.5 Development of Long-Duration Energy Storage Systems (LDES) 1.8.6 Hybrid Solar + Wind + Storage Deployment Models 1.8.7 Carbon-Neutral and Low-Emission Battery Manufacturing Initiatives 1.9 Demand and Consumption Pattern Analysis (2025) 1.9.1 Strong Demand from Utility-Scale Renewable Projects 1.9.2 Rising Deployment in Commercial & Industrial Energy Optimization 1.9.3 Increasing Adoption in Residential Backup Power Systems 1.9.4 High Integration in EV Charging Infrastructure 1.9.5 Increasing Deployment in Microgrids and Remote Energy Systems 1.9.6 Growing Adoption in Data Centers and Telecom Infrastructure 1.9.7 Defense, Marine, and Critical Infrastructure Energy Storage Demand 1.10 Demand-Supply Gap Analysis (2025) 1.10.1 Projected BESS Demand (GWh) vs Manufacturing Capacity 1.10.2 Supply Deficit/Surplus Analysis by Year 1.10.3 Regional Manufacturing Imbalance Analysis 1.10.4 Battery Cell Supply-Demand Outlook 1.10.5 Impact of Raw Material Shortages on Deployment Economics 1.10.6 Impact on Pricing, Procurement, and Project Execution Timelines 1.10.7 Regional Dependency on Chinese Battery Manufacturing Ecosystem 1.11 Battery Energy Storage System Integration Across Applications (2025) 1.11.1 Utility-Scale Grid Stabilization and Renewable Integration 1.11.2 Commercial & Industrial Peak Shaving and Load Management 1.11.3 Residential Solar + Storage Integration 1.11.4 EV Fast-Charging Infrastructure Integration 1.11.5 Microgrid and Island Electrification Deployment 1.11.6 Data Center and Telecom Backup Applications 1.11.7 Defense and Mission-Critical Infrastructure Applications 1.12 Growth of Battery Energy Storage System Market by End User (2025–2034) 1.12.1 Utility and Renewable Energy Developer Growth Outlook 1.12.2 Commercial & Industrial Storage Growth Rate by Region 1.12.3 Residential Storage Demand Outlook 1.12.4 Data Center and Telecom Sector Adoption Trends 1.12.5 EV Infrastructure-Linked Storage Deployment Outlook 1.12.6 Industrial Manufacturing Sector Storage Adoption 1.12.7 Government and Defense Energy Resilience Investment Outlook 1.13 Pricing Analysis and Cost Structure Evaluation (2025) 1.13.1 Raw Material Cost Contribution (Lithium, Nickel, Cobalt, Graphite) 1.13.2 Battery Cell, Module, PCS, Inverter, and EMS Cost Structure Analysis 1.13.3 Utility-Scale Project CAPEX Benchmarking 1.13.4 Cost Comparison by Battery Chemistry 1.13.5 Overview of BESS Pricing Trends by Region 1.13.6 Impact of Battery Degradation on Lifecycle Economics 1.13.7 Energy Storage LCOE (Levelized Cost of Energy) Analysis 1.14 Energy Storage Procurement and Distribution Channel Analysis (2025) 1.14.1 Direct Procurement Agreements Between Utilities and BESS Manufacturers 1.14.2 EPC and System Integrator Procurement Ecosystem 1.14.3 Distribution Channels for Commercial & Industrial Storage Systems 1.14.4 Utility-Scale Project Procurement Models 1.14.5 Renewable Developer Storage Sourcing Strategies 1.14.6 Government Tender-Based Procurement Mechanisms 1.14.7 Supply Agreements Between Battery Suppliers and Grid Operators 1.14.8 Procurement Trends in Emerging Economies 1.15 Renewable Energy Integration Impact Analysis (2025) 1.15.1 Correlation Between Renewable Energy Capacity Additions and BESS Demand 1.15.2 Solar + Storage Hybrid Deployment Analysis 1.15.3 Assessment of Battery Energy Storage System Integration with Utility-Scale, Commercial & Industrial, Residential, and Off-Grid Solar Photovoltaic Installations 1.15.4 Analysis of Solar Photovoltaic Generation Profiles, Battery Charging Strategies, and Renewable Energy Optimization 1.15.5 Assessment of Power Conversion Systems, Energy Management Systems, and Grid Interconnection Requirements for Solar-Integrated Battery Energy Storage Systems 1.15.6 Comparative Analysis of AC-Coupled and DC-Coupled Solar Photovoltaic Battery Energy Storage Configurations 1.15.7 Wind + Storage Integration Economics 1.15.8 Assessment of Battery Energy Storage System Integration with Onshore, Offshore, Utility-Scale, and Distributed Wind Power Installations 1.15.9 Analysis of Wind Generation Variability, Battery Dispatch Strategies, and Renewable Energy Balancing 1.15.10 Assessment of Energy Management Systems, Grid Synchronization, and Power Quality Optimization for Wind-Integrated Battery Energy Storage Systems 1.15.11 Comparative Analysis of Onshore and Offshore Wind Battery Energy Storage Configurations Across Major Regions 1.15.12 Evaluation of Peak Shaving, Load Shifting, Renewable Curtailment Reduction, and Grid Balancing Support for Renewable Intermittency 1.15.13 Impact of Renewable Energy Policies, Incentives, and Subsidies on BESS Adoption 1.15.14 Decentralized Renewable Energy Storage Deployment Trends 1.15.15 Long-Term Renewable-Driven Battery Energy Storage System Demand Outlook 1.15.16 Curtailment Reduction Through Storage Integration 1.15.17 Grid Balancing Support for Renewable Intermittency 1.15.18 Impact of Renewable Subsidies on BESS Adoption 1.15.19 Long-Term Renewable-Driven Storage Demand Outlook 1.15.20 Decentralized Renewable Energy Storage Deployment Trends 1.16 Battery Lifecycle, Maintenance, and Performance Optimization Analysis (2025) 1.16.1 Battery Degradation Analysis Across Lifecycle Stages 1.16.2 Predictive Maintenance and AI-Enabled Diagnostics 1.16.3 Thermal Management Optimization Strategies 1.16.4 Battery Augmentation and Replacement Economics 1.16.5 Performance Optimization Under Varying Load Conditions 1.16.6 Remote Monitoring and Cloud-Based Analytics Adoption 1.16.7 Warranty Structures and Lifecycle Guarantees 1.16.8 Service Ecosystem for Utility-Scale Storage Systems 1.17 Recycling and Circular Economy Ecosystem Analysis 1.17.1 Battery Recycling Technologies 1.17.1.1 Hydrometallurgical Recycling 1.17.1.2 Pyrometallurgical Recycling 1.17.2 Key Recycling Companies and Capacity Expansion Plans 1.17.3 Recovery Rates of Lithium, Cobalt, Nickel, and Graphite 1.17.4 Economics of Battery Recycling and Recovered Materials 1.17.5 Second-Life Battery Deployment in ESS Applications 1.17.6 Circular Economy Integration in Battery Lifecycle Management 1.17.7 Regulatory Push for Battery Recycling 1.17.7.1 EU Battery Regulation 1.17.7.2 IRA 1.17.7.3 India Battery Waste Management Rules 1.17.8 Closed-Loop Battery Manufacturing Ecosystem Development 1.18 Second-Life Battery Energy Storage Market Analysis (2025) 1.18.1 EV Battery Repurposing Trends for Stationary Storage 1.18.2 Applications in Grid-Scale and Residential ESS 1.18.3 Cost Advantages Compared to New Battery Systems 1.18.4 Lifecycle Extension Benefits and Economics 1.18.5 Challenges in Standardization and Performance Degradation 1.18.6 Utility Adoption of Repurposed Battery Systems 1.18.7 Emerging Business Models in Second-Life Storage 1.19 Battery-as-a-Service (BaaS) and Emerging Business Models (2025) 1.19.1 Battery-as-a-Service (BaaS) Model Analysis 1.19.2 Energy Storage-as-a-Service (ESaaS) Ecosystem 1.19.3 Subscription-Based Storage Deployment Models 1.19.4 Shared Energy Storage Business Frameworks 1.19.5 Utility-Owned vs Third-Party-Owned BESS Comparison 1.19.6 Cost-Benefit Comparison of Leasing vs Ownership Models 1.19.7 Emerging Storage Monetization Strategies 1.19.8 Challenges in Scalability and Standardization 1.20 Gigafactory Landscape and Capacity Expansion Analysis (2025) 1.20.1 Global BESS-Related Battery Manufacturing Capacity (GWh) by Region 1.20.2 Planned vs Operational Gigafactory Analysis (2025–2034) 1.20.3 Key Manufacturers’ Capacity Expansion Strategies 1.20.4 Regional Manufacturing Concentration Analysis 1.20.5 Localization Strategies Driven by IRA, EU Battery Regulation, and India PLI Schemes 1.20.6 Planned Battery Storage Manufacturing Investments 1.20.7 Regional Production Capacity Share (%) 1.20.8 Supply Chain Localization and Import Dependency Reduction Strategies 1.21 Intellectual Property (IP) and Patent Landscape Analysis 1.21.1 Patent Filing Trends by Leading BESS Companies 1.21.2 Technology Ownership Trends 1.21.2.1 Battery Chemistry 1.21.2.2 EMS 1.21.2.3 BMS 1.21.2.4 Thermal Systems 1.21.3 Competitive Advantage Through Proprietary Technologies 1.21.4 Patent Wars and Litigation Risks 1.21.5 Innovation Clusters by Region 1.21.6 AI and Software-Related Energy Optimization Patents 1.21.7 Storage Inverter and Power Electronics Innovation Landscape 1.22 Qualification, Certification, and Regulatory Compliance Analysis 1.22.1 Battery Certification Standards and Approval Timelines 1.22.2 UL, IEC, NFPA, IEEE, and Regional Compliance Frameworks 1.22.3 Safety Testing and Thermal Runaway Compliance Requirements 1.22.4 Grid Interconnection Certification Processes 1.22.5 Regulatory Delays Affecting Commercialization 1.22.6 ESG and Carbon Compliance Requirements 1.22.7 Cybersecurity Standards for Smart Energy Storage Systems 1.22.8 Impact of Compliance Costs on Project Economics 1.23 AI, Digitalization, and Smart Energy Optimization Analysis 1.23.1 AI-Enabled Battery Dispatch Optimization 1.23.2 Predictive Analytics for Storage Performance Enhancement 1.23.3 Digital Twin Integration in Energy Storage Operations 1.23.4 Cloud-Based EMS and BMS Platforms 1.23.5 Real-Time Energy Trading Optimization Algorithms 1.24 Long Duration Energy Storage (LDES) Opportunity Analysis 1.24.1 Growth Outlook for Long-Duration Storage Technologies 1.24.2 Comparison Between Lithium-Ion and LDES Systems 1.24.3 Flow Battery Commercialization Analysis 1.24.4 Hydrogen-Based Storage Opportunities 1.24.5 Utility-Scale Long-Duration Deployment Trends 1.24.6 Grid Resilience and Backup Duration Enhancement Strategies 1.24.7 Investment Landscape for LDES Startups 1.24.8 Future Competitiveness Against Conventional BESS Systems 1.25 Regional Policy and Incentive Analysis 1.25.1 U.S. Inflation Reduction Act (IRA) Impact on BESS Deployment 1.25.2 EU Battery Regulation and Carbon Footprint Rules 1.25.3 China Energy Storage Policy and Subsidies 1.25.4 India PLI Scheme and Storage Incentive Programs 1.25.5 Renewable Integration Mandates Driving BESS Demand 1.25.6 Localization Mandates and Domestic Manufacturing Policies 1.25.7 Ancillary Service Market Reforms Supporting Storage Adoption 1.25.8 Net Metering and Distributed Storage Incentive Analysis 1.26 Risk Assessment and Market Challenges Overview 1.26.1 Raw Material Price Volatility and Supply Constraints 1.26.2 Supply Chain Disruptions and Geopolitical Risks 1.26.3 Fire Safety and Thermal Runaway Risks 1.26.4 High Capital Investment Requirements 1.26.5 Technology Obsolescence Risk Analysis 1.26.6 Recycling Infrastructure Limitations 1.26.7 Grid Infrastructure and Interconnection Bottlenecks 1.26.8 Revenue Uncertainty Across Merchant Energy Markets 1.26.9 Regulatory and Certification Challenges 1.27 Investment and Funding Trends in Battery Energy Storage System Market 1.27.1 Government Funding and Subsidy Analysis 1.27.2 Venture Capital and Private Equity Investment Trends 1.27.3 Infrastructure Fund Participation in Storage Projects 1.27.4 Strategic Investments in AI-Enabled Storage Optimization 1.27.5 Financing Models for Utility-Scale Energy Storage Deployments 1.27.6 IPO and Startup Ecosystem Analysis in BESS Sector 1.28 Sustainability Trends and Environmental Impact Analysis (2025) 1.28.1 Shift Toward Low-Carbon Battery Manufacturing Processes 1.28.2 Reduction in Carbon Footprint Across BESS Value Chain 1.28.3 ESG Commitments by Utilities and Battery Manufacturers 1.28.4 Renewable-Powered Gigafactory Initiatives 1.28.5 Sustainable Mining and Ethical Sourcing Practices 1.28.6 Water Consumption and Emissions Analysis in Battery Production 1.28.7 Lifecycle Emissions Assessment of BESS Deployments 1.28.8 Net-Zero Energy Storage Transition Strategies 1.29 Battery Energy Storage System Market: Market Size and Forecast by Segmentation (By Value USD Billion and Volume in GWh) (2025–2034) 1.29.1 Battery Energy Storage System Market Size and Forecast, By Battery Type 1.29.1.1 Lithium-Ion Battery 1.29.1.2 Advanced Lead Acid Battery 1.29.1.3 Flow Battery 1.29.1.4 Nickel-Based Battery 1.29.1.5 Sodium-Based Battery 1.29.1.6 Others 1.29.2 Battery Energy Storage System Market Size and Forecast, By Component 1.29.2.1 Hardware 1.29.2.1.1 Battery Packs/Modules 1.29.2.1.2 Battery Management System (BMS) 1.29.2.1.3 Power Conversion System (PCS) 1.29.2.1.4 Inverters 1.29.2.1.5 Energy Management System (EMS) 1.29.2.1.6 Thermal Management System 1.29.2.1.7 Transformers 1.29.2.1.8 Containerized Storage Systems 1.29.2.2 Software 1.29.2.2.1 Energy Optimization Software 1.29.2.2.2 AI-Based Predictive Analytics Software 1.29.2.2.3 Grid Monitoring & Control Platforms 1.29.2.3 Services 1.29.2.3.1 Installation & Integration 1.29.2.3.2 Maintenance & Monitoring 1.29.2.3.3 Consulting & Engineering Services 1.29.3 Battery Energy Storage System Market Size and Forecast, By Energy Capacity 1.29.3.1 Below 500 MWh 1.29.3.2 Between 100 MWh to 500 MWh 1.29.3.3 Above 500 MWh 1.29.4 Battery Energy Storage System Market Size and Forecast, By Connection Type 1.29.4.1 On-Grid 1.29.4.2 Off-Grid 1.29.5 Battery Energy Storage System Market Size and Forecast, By Ownership 1.29.5.1 Customer Owned 1.29.5.2 Third Party Owned 1.29.5.3 Utility Owned 1.29.6 Battery Energy Storage System Market Size and Forecast, By Deployment Type 1.29.6.1 Front-of-the-Meter (FTM) 1.29.6.2 Behind-the-Meter (BTM) 1.29.7 Battery Energy Storage System Market Size and Forecast, By Application 1.29.7.1 Renewable Energy Integration 1.29.7.2 Peak Shaving 1.29.7.3 Load Shifting 1.29.7.4 Frequency Regulation 1.29.7.5 Grid Stabilization 1.29.7.6 Backup Power 1.29.7.7 Energy Arbitrage 1.29.7.8 EV Charging Infrastructure 1.29.7.9 Microgrid Support 1.29.8 Battery Energy Storage System Market Size and Forecast, By End User 1.29.8.1 Utilities 1.29.8.2 Renewable Energy Developers 1.29.8.3 Commercial & Industrial (C&I) 1.29.8.4 Residential 1.29.8.5 Data Centers 1.29.8.6 Telecom Industry 1.29.8.7 Manufacturing Sector 1.29.8.8 Healthcare Facilities 1.29.8.9 Government & Defense 1.29.8.10 Transportation & Mobility 1.29.8.11 Others 1.29.9 Battery Energy Storage System Market Size and Forecast, By Region 1.29.9.1 North America 1.29.9.1.1 United States 1.29.9.1.2 Canada 1.29.9.1.3 Mexico 1.29.9.2 Europe 1.29.9.2.1 United Kingdom 1.29.9.2.2 France 1.29.9.2.3 Germany 1.29.9.2.4 Italy 1.29.9.2.5 Spain 1.29.9.2.6 Sweden 1.29.9.2.7 Russia 1.29.9.2.8 Rest of Europe 1.29.9.3 Asia Pacific 1.29.9.3.1 China 1.29.9.3.2 South Korea 1.29.9.3.3 India 1.29.9.3.4 Japan 1.29.9.3.5 Australia 1.29.9.3.6 Indonesia 1.29.9.3.7 Philippines 1.29.9.3.8 Malaysia 1.29.9.3.9 Vietnam 1.29.9.3.10 Thailand 1.29.9.3.11 Rest of Asia Pacific 1.29.9.4 Middle East and Africa 1.29.9.4.1 South Africa 1.29.9.4.2 Bahrain 1.29.9.4.3 Kuwait 1.29.9.4.4 Oman 1.29.9.4.5 Qatar 1.29.9.4.6 Saudi Arabia 1.29.9.4.7 United Arab Emirates 1.29.9.4.8 Nigeria 1.29.9.4.9 Egypt 1.29.9.4.10 Rest of Middle East and Africa 1.29.9.5 South America 1.29.9.5.1 Brazil 1.29.9.5.2 Argentina 1.29.9.5.3 Chile 1.29.9.5.4 Colombia 1.29.9.5.5 Rest of South America 2. SECTION B – INTEGRATED BESS FINANCIAL MODELLING & ENERGY REVENUE OPTIMIZATION STUDY 2.1 Global Competitive Landscape and Market Positioning 2.1.1 Global Competitive Landscape Across Leading Battery Storage Companies 2.1.2 Market Positioning Analysis Based on Technology and Capabilities 2.1.3 Competitive Intensity Assessment Across Regional and Global Markets 2.1.4 Industry Consolidation Trends Reshaping Competitive Market Environment 2.1.5 Strategic Differentiation Through Innovation and Product Development 2.1.6 Competitive Benchmarking Across Integrated Energy Storage Solution Providers 2.2 Company Market Share Analysis 2.2.1 Global Market Share Analysis of Leading Industry Participants 2.2.2 Revenue-Based Competitive Positioning Across Major Global Companies 2.2.3 Installed Battery Storage Capacity Benchmark by Leading Manufacturers 2.2.4 Regional Market Share Distribution Across Key Industry Participants 2.2.5 Technology Portfolio Influence on Competitive Market Leadership 2.2.6 Future Market Share Outlook Based on Expansion Strategies 2.3 CAPEX Benchmarking Analysis 2.3.1 Battery Cell and Module Cost Benchmarking 2.3.2 Containerized BESS System Cost Structure Analysis 2.3.3 Power Conversion System (PCS) and Inverter Cost Analysis 2.3.4 Energy Management System (EMS) Integration Cost Benchmarking 2.3.5 Utility-Scale Project Installation and EPC Cost Analysis 2.3.6 Regional CAPEX Comparison Across North America, Europe, China, and India 2.3.7 Cost Reduction Roadmap for Next-Generation Storage Systems 2.4 Operational Expenditure (OPEX) Analysis 2.4.1 Battery Maintenance and Augmentation Costs 2.4.2 Thermal Management and Cooling Operational Costs 2.4.3 Software, EMS, and Monitoring Platform Costs 2.4.4 Warranty and Long-Term Servicing Cost Analysis 2.4.5 Battery Degradation and Lifecycle Operational Impact 2.4.6 Annual Operating Cost Benchmarking by Deployment Type 2.4.7 Total Cost of Ownership (TCO) Analysis 2.5 Global & Regional Energy Procurement Landscape 2.5.1 Global Electricity Procurement Market Overview 2.5.2 Industrial and Commercial Electricity Consumption Trends 2.5.3 Grid Modernization and Decentralized Energy Transition Analysis 2.5.4 Open Access and Merchant Electricity Market Evolution 2.5.5 Renewable Energy Procurement Transformation Trends 2.5.6 Regional Procurement Competitiveness Benchmarking 2.6 Energy Procurement Optimization Framework 2.6.1 Integrated Energy Procurement Optimization Methodology 2.6.2 Electricity Sourcing and Procurement Modelling Framework 2.6.3 Procurement Cost Benchmarking and Optimization Approach 2.6.4 Load Forecasting and Energy Demand Assessment 2.6.5 Battery Dispatch Optimization for Procurement Efficiency 2.6.6 AI-Driven Procurement Optimization Analytics 2.6.7 Scenario-Based Procurement Strategy Modelling 2.7 Peak Shaving & Load Management Optimization 2.7.1 Peak Demand Reduction Modelling 2.7.2 Load Shifting Optimization Analysis 2.7.3 Demand Charge Reduction Benchmarking 2.7.4 Intelligent Battery Dispatch for Peak Load Management 2.7.5 Industrial Energy Consumption Optimization Analysis 2.7.6 Commercial Building Energy Optimization Framework 2.7.7 Multi-Site Load Balancing and Energy Orchestration Strategies 2.8 Open Access & Renewable Energy Procurement Analysis 2.8.1 Open Access Electricity Procurement Framework 2.8.2 Captive Power vs Grid Procurement Economics 2.8.3 Renewable Open Access Optimization Analysis 2.8.4 Solar + BESS Procurement Optimization 2.8.5 Wind + Storage Balancing Analysis 2.8.6 Renewable Energy Scheduling and Forecasting Optimization 2.8.7 Round-the-Clock (RTC) Renewable Procurement Strategy 2.8.8 Wheeling and Banking Charge Impact Assessment 2.9 Commercial & Industrial (C&I) Procurement Optimization 2.9.1 Industrial Energy Procurement Benchmarking 2.9.2 Manufacturing Sector Electricity Optimization Analysis 2.9.3 Data Center Energy Procurement Assessment 2.9.4 Telecom Infrastructure Energy Optimization Strategies 2.9.5 Commercial Real Estate Energy Procurement Modelling 2.9.6 Process Industry Energy Optimization Benchmarking 2.9.7 Multi-Location Enterprise Procurement Strategy Analysis 2.10 AI-Based Energy Procurement Optimization 2.10.1 AI-Enabled Electricity Procurement Systems 2.10.2 Predictive Demand Forecasting Models 2.10.3 Machine Learning Applications in Procurement Planning 2.10.4 Automated Dispatch and Load Scheduling Algorithms 2.10.5 Digital Twin Integration in Energy Procurement Optimization 2.10.6 Real-Time Pricing Optimization Systems 2.10.7 Autonomous Energy Procurement and Balancing Frameworks 2.11 Integrated Revenue Maximization Framework 2.11.1 Energy Sale Revenue Optimization Methodology 2.11.2 Multi-Revenue Stream Monetization Framework 2.11.3 Battery Dispatch and Revenue Optimization Modelling 2.11.4 Dynamic Pricing and Load Forecasting Integration 2.11.5 AI-Enabled Trading and Energy Optimization Systems 2.11.6 Revenue Forecasting and Profitability Assessment Models 2.11.7 Scenario-Based Revenue Optimization Framework 2.12 Energy Arbitrage Revenue Analysis 2.12.1 Peak vs Off-Peak Electricity Trading Analysis 2.12.2 Intraday and Day-Ahead Market Participation Modelling 2.12.3 Real-Time Energy Trading Optimization 2.12.4 Price Spread Analysis and Arbitrage Profitability Assessment 2.12.5 Battery Charge-Discharge Cycle Optimization for Revenue Generation 2.12.6 Merchant Market Participation Benchmarking 2.12.7 Regional Energy Arbitrage Opportunity Analysis 2.13 Renewable Energy Firming & Dispatch Optimization 2.13.1 Solar + Storage Revenue Optimization Analysis 2.13.2 Wind + Storage Dispatch Profitability Assessment 2.13.3 Renewable Intermittency Balancing Monetization 2.13.4 Round-the-Clock (RTC) Renewable Power Optimization 2.13.5 Curtailment Reduction Value Analysis 2.13.6 Hybrid Renewable Energy Project Revenue Enhancement 2.13.7 Renewable PPA Optimization Through BESS Integration 2.14 Commercial & Industrial (C&I) Revenue Optimization 2.14.1 Industrial Energy Resale and Optimization Analysis 2.14.2 Peak Shaving Monetization Opportunities 2.14.3 Demand Response Participation Economics 2.14.4 Commercial Building Energy Revenue Optimization 2.14.5 Data Center and Telecom Energy Monetization Assessment 2.14.6 Industrial Microgrid Profitability Benchmarking 2.14.7 Multi-Site Energy Balancing and Revenue Orchestration Analysis 2.15 Company Profiles: Key Players 2.15.1 Company Overview 2.15.2 Business Portfolio 2.15.3 Financial Overview 2.15.4 SWOT Analysis 2.15.5 Strategic Analysis 2.15.6 Recent Developments 2.15.7 Battery/Cell Manufacturers 2.15.7.1 CATL (Contemporary Amperex Technology Co., Limited) 2.15.7.2 BYD Company Ltd. 2.15.7.3 LG Energy Solution 2.15.7.4 Samsung SDI 2.15.7.5 Panasonic Energy 2.15.7.6 SK On 2.15.7.7 EVE Energy 2.15.7.8 CALB (China Aviation Lithium Battery) 2.15.7.9 Gotion High-Tech 2.15.7.10 Hithium 2.15.7.11 REPT BATTERO 2.15.7.12 Narada Power 2.15.8 Integrated BESS / System Manufacturers 2.15.8.1 Tesla Energy 2.15.8.2 Fluence Energy 2.15.8.3 Sungrow Power Supply Co., Ltd. 2.15.8.4 Trina Storage 2.15.8.5 Canadian Solar (e-STORAGE) 2.15.8.6 Envision Energy 2.15.8.7 Ampace 2.15.8.8 Kehua Tech 2.15.8.9 Pylontech (Pylon Technologies) 2.15.8.10 JinkoSolar 2.15.9 Industrial Conglomerates / Power & Grid Equipment 2.15.9.1 Wärtsilä Energy Storage 2.15.9.2 Hitachi Energy 2.15.9.3 GE Vernova 2.15.9.4 Siemens Energy 2.15.9.5 ABB Ltd. 2.15.9.6 Schneider Electric 2.15.9.7 Nidec ASI 2.15.9.8 Johnson Controls 2.15.9.9 Eaton Corporation 2.15.9.10 Vertiv Holdings 2.15.9.11 Delta Electronics 2.15.9.12 Huawei Digital Power 2.15.10 Specialty Battery / Storage 2.15.10.1 Saft (TotalEnergies) 2.15.10.2 EnerSys 2.15.10.3 Exide Industries 2.15.11 Residential/Commercial Storage 2.15.11.1 Enphase Energy 2.15.11.2 Bloom Energy 2.15.11.3 Generac Power Systems 3. SECTION C – STRATEGIC OUTLOOK 3.1 Key Findings 3.2 Analyst Recommendation 3.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements