Gas Turbine Market by Type, by Technology, by Power Rating, by Application and Regional Insights 2034

4.6%
CAGR (2026-2034)
23.80 USD Bn.
Forecast Market Size
326
Report Pages
129
Market Tables

Overview

Global Gas Turbine Market size was valued at USD 23.80 Billion in 2025 and the total Gas Turbine revenue is expected to grow by 4.6 % from 2026 to 2034, reaching USD 35.80 Billion by 2034.

Gas Turbine Market Overview:

A Gas Turbine is a type of internal combustion engine that transfers chemical energy in the form of rotational power into mechanical energy. This mechanical energy may be employed to drive a variety of industrial activities. A Gas Turbine has several advantages, including great dependability, low operating costs, and high power density. The Gas Turbine may also be powered by clean and renewable energy, lowering carbon emissions. Gas Turbines used in cogeneration or Combined Heat and Power (CHP) processes improve plant efficiency by using exhaust gases to create steam, which may then be utilized for a variety of Technologies without the usage of extra fuel. Because of these advantages, as well as others such as higher efficiency, severe carbon emission laws, and cost savings provided by the use of these turbines, Gas Turbine demand is likely to rise further in the coming years.

Asia-Pacific is witnessing strong demand as utilities shift from coal to natural gas, while petrochemical and industrial facilities increasingly integrate combined heat and power (CHP) and cogeneration systems into new projects. In North America, the market benefits from coal-to-gas switching, aging power infrastructure, abundant natural gas availability, and increasing requirements for fast-ramping generation to complement variable renewable energy. Gas turbines therefore continue to play an important role in balancing power systems as solar and wind penetration increases.

Technological innovation is further strengthening the gas turbine market outlook. Manufacturers are focusing on hydrogen-ready turbines, low-emission combustion systems, advanced turbine controls, digital twins, predictive maintenance, and high-efficiency combined-cycle technology. For example, in December 2025, Mitsubishi Power and Mitsubishi Electric complete functional testing of a next-generation gas turbine control system designed to support stable power output, rapid load changes, renewable-energy integration, and multiple fuel types including hydrogen.

Gas Turbine Market Key Highlights:

• Market Size and Growth: The global gas turbine market reaches USD 23.80 billion in 2025 and is projected to reach USD 35.80 billion by 2034, registering a CAGR of 4.6% during 2025–2034.

• Regional Dominance: Asia Pacific holds a 41% market share in 2025, driven by industrialization, rising electricity demand, and gas-fired power-generation investments across China, India, Japan, Indonesia, and Thailand.

• Technology Leadership: Combined Cycle technology accounts for approximately 78% revenue share, supported by fuel efficiency, waste-heat recovery, and overall system efficiency of approximately 60%–80%.

• Market Opportunities: Distributed power generation and combined heat and power (CHP) systems create opportunities. CHP systems achieve approximately 80%–90% total efficiency, compared with 35%–45% for separate electricity and heat generation.

• Technology Trends: Manufacturers focus on hydrogen-ready turbines, ammonia combustion, advanced controls, predictive maintenance, and high-efficiency combined-cycle systems. GE Vernova and IHI develop technology targeting 100% ammonia firing in F-class gas turbines by 2030.

• Recent Industry Developments: China’s 1,686 MW Anji Meixi gas-fired power project reaches full-capacity operation in January 2026. GE Vernova also advances ammonia-firing technology, while Siemens Energy expands its involvement in gas-fired power and distributed-generation projects.

Gas Turbine Market Growth Outlook
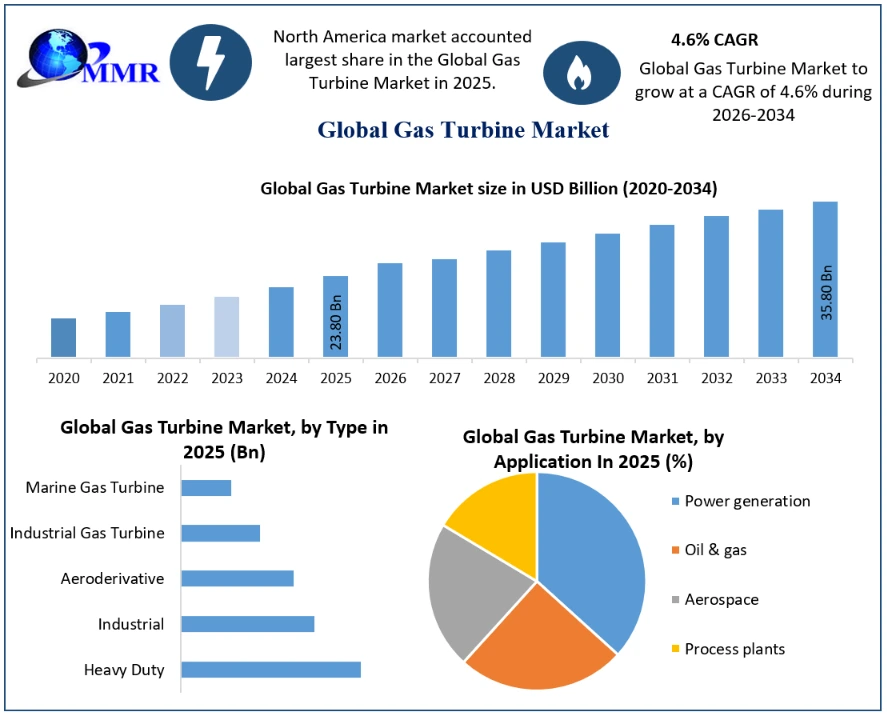
Gas Turbine Market Growth

To know about the Research Methodology :- Request Free Sample Report

Gas Turbine Market Research Methodology

The research report highly depends on both primary and secondary data sources. The research process involves the investigation of various factors affecting the industry, such as government policy, market environment, competitive landscape, historical data, current market trends, technological innovation, upcoming technologies, and technical progress in related industries, as well as market risks, opportunities, market barriers, and challenges. All conceivable elements influencing the markets included in this research study have been considered, examined in depth, validated through primary research, and evaluated to provide the final quantitative and qualitative data. The market size for top-level markets and sub-segments is normalised, and the impact of inflation, economic downturns, regulatory & policy changes, and other variables is factored into the market forecast.

This data is combined and added with detailed inputs and analysis, and presented in the report. Extensive primary research was conducted to acquire information and verify and confirm the crucial numbers arrived at after comprehensive market engineering and calculations for market statistics; market size estimations; market forecasts; market breakdown; and data triangulation. The bottom-up technique is widely employed in the whole market engineering process, along with multiple data triangulation methodologies, to perform market estimation and forecasting for the overall market segments and sub-segments covered in this research.

Global Gas Turbine Market Dynamics

Gas Turbine Market Drivers

• Rising Demand for Reliable and Efficient Power Generation: The rising global demand for reliable and efficient power generation is a major driver of the gas turbine market. Combined-cycle gas turbines achieve thermal efficiencies of more than 60%, making them an important technology for high-capacity and dispatchable electricity generation. Electricity demand is also increasing as smart cities, smart buildings, manufacturing facilities, and digital infrastructure expand.

• Accelerating Coal-to-Gas Transition: The transition from coal-fired generation to natural-gas-based combined-cycle power generation is strengthening the gas turbine market outlook. Approximately 2,044 GW of coal-fired power capacity is operational globally, while China operates around 1,082 coal-fired power plants as of the cited period, creating substantial potential for cleaner and more efficient replacement technologies. on January 20, 2026, China’s Guoneng Zhejiang Anji Meixi gas-fired power project achieves full-capacity operation with 1,686 MW of installed capacity across two 9H-class combined-cycle units.

Gas Turbine Market Restraints

• Volatility in Natural Gas Prices: Natural gas price volatility remains a major restraint for the global gas turbine market because fuel costs directly influence the operating economics of gas-fired power plants. Germany's RWE delays approximately 1,800 MW of projects in 2024, while Italy's Enel withdraws a 1,200 MW plant in 2025 after failing to secure PPAs above EUR 80/MWh. These developments demonstrate how fuel economics and power-market conditions influence gas turbine investment decisions.

Gas Turbine Market Opportunities

• Growth of Distributed Power Generation: The increasing adoption of distributed power generation creates a major opportunity for gas turbine manufacturers. Gas turbines provide reliable onsite electricity and backup power while offering high efficiency and dependable generation capacity. This opportunity is particularly relevant for remote industrial facilities, mining operations, islands, commercial facilities, and critical infrastructure.

• Expansion of Combined Heat and Power Systems: The growing deployment of CHP systems provides a significant opportunity because gas turbines can simultaneously generate electricity and useful thermal energy. CHP systems achieve approximately 80–90% total efficiency, compared with 35–45% for separate-generation systems. The opportunity is particularly strong across petrochemical, chemical, refining, food-processing, and manufacturing industries.

Gas Turbine Market Challenges

• Rapid Expansion of Renewable Energy: The rapid expansion of solar and wind energy presents a structural challenge to the gas turbine market. Renewable power capacity increasingly meets incremental electricity demand in several markets, reducing the requirement for conventional thermal generation. The challenge is particularly significant as the IEA indicates that additional global electricity demand during 2025–2027 is met by low-emission technologies such as renewables and nuclear.

• Limited Natural Gas Reserves and Energy Transition: The cited BP Statistical Review estimates global natural gas reserves at approximately 186.6 trillion cubic meters, equivalent to around 55 years of supply at the stated consumption rate. Increased exports and consumption can reduce the reserve-to-production ratio. At the same time, solar and wind power continue to expand as alternative energy sources, increasing pressure on fossil-fuel-based generation.

Gas Turbine Market Trends

• Technological Advancements in High-Efficiency Turbines: Gas turbine manufacturers are increasingly focusing on advanced cooling, improved materials, optimized combustion, and sophisticated control systems. Combined-cycle power plants are achieving efficiency levels exceeding 60%, while advanced H-class and J-class configurations approach approximately 65% HHV efficiency.

• Hydrogen and Ammonia-Fired Gas Turbines: The industry is increasingly shifting toward alternative-fuel capability. In June 2025, GE Vernova and IHI launch a large-scale combustion test facility at IHI's Aioi Works in Japan to develop combustors capable of 100% ammonia firing in F-class gas turbines by 2030, with full-scale prototype testing beginning in summer 2025.

Gas Turbine Market Segment Analysis:

Based on Type, The Heavy Duty segment dominates the Gas Turbine Market due to its large power-generation capacity, cost-effective operation, and suitability for continuous utility and industrial applications, while ongoing advancements in efficiency, flexibility, and reliability further support its adoption. Meanwhile, the Aeroderivative segment is projected to grow at an 8.1% CAGR during the forecast period, supported by its aircraft-engine-based design, compact and lightweight configuration, faster startup, easier installation, and high operational flexibility for distributed, backup, and peak-power generation applications.

Based on Technology, The Combined Cycle segment dominates the Gas Turbine Market with approximately 78% revenue share, supported by lower fuel consumption, efficient waste-heat utilization, and overall power-generation efficiency. Combined-cycle systems achieve approximately 60%–80% efficiency and increasingly support renewable energy integration by complementing variable solar and wind generation. Meanwhile, the Open Cycle segment remains important for rapid-start, peak-load, backup, and emergency power generation, as its simple configuration provides high operational flexibility and quick response to changes in electricity demand. Rising demand for flexible and rapidly deployable power-generation systems supports continued adoption of open-cycle gas turbines.

Based on Application, The Power Generation segment dominates the Gas Turbine Market in 2025, supported by rising electricity demand and the continued use of natural-gas-fired power plants for reliable and flexible electricity generation. In the United States, natural gas contributes approximately 40% of electricity generation in 2025.The Oil & Gas segment gains demand from expanding exploration, production, and energy-intensive infrastructure. The Marine and Aerospace segments benefit from gas turbines’ compact design, high power-to-weight ratio, and operational flexibility. Process Plants adopt gas turbines for reliable power, mechanical drive, and CHP applications. The Others segment includes distributed, backup, remote, and specialized power applications supported by rapid startup and flexible operation.

Gas Turbine Market Regional Insights:

• North America, dominated by the United States, Mexico, and Canada, is expected to develop at a rapid pace during the forecast period. The shale gas deposit and technical advancements in extraction and mining technologies, which are continually decreasing the operational cost of gas extraction in the region, are driving demand. Furthermore, large-scale gas-based power plant commissioning has occurred in the North American area. Because of technical advances in completion methods like as multistage hydraulic fracturing and drilling techniques such as horizontal wellbores, oil and gas firms have been able to create shale gas on a commercial scale. According to trends, the aforementioned technical developments, as well as commercial shale gas production, are expected to propel the regional market in the near future.

• Europe region, This region is working hard to minimize the emissions of carbon, numerous nations have opted to phase out coal and nuclear power plants from their energy mix. The emphasis is shifting toward gas-powered turbine Types, which run on natural gas and may be utilized as an alternative to coal. Natural gas contributes far less than coal. This is why it will fuel market growth in the European area.

• Asia Pacific region dominated the market in the year 2025 with 41% market share and is expected to dominate the market during the forecast period. China, Japan, Indonesia, Thailand, and India are the countries that are expected to grow at the fastest rate. Emerging economies such as India and China, as well as labor and low-cost raw materials, are tempting international corporations to extend their operations in this region. Rapid industrialization and urbanization increased the consumption of energy, as well as the desire for sustainable energy solutions like renewable energy, and hence the demand for the industrial gas turbine market. This region's governments have taken many initiatives to reduce carbon emissions using Gas turbine emissions, which have increased owing to the deployment of these turbines in Japan, China, India, Australia, and South Korea.

• Middle East and Africa: The Middle East and Africa Gas Turbine Market is expanding as countries invest in reliable power generation, industrial infrastructure, and energy-efficient technologies. Saudi Arabia remains a significant end-user of gas turbines, supported by large-scale power-generation and industrial projects. Major OEMs such as Siemens Energy, General Electric, and Mitsubishi Power supply gas turbine systems across the region, strengthening technology adoption. Growing electricity demand, industrialization, and investments in natural-gas-based power generation further support regional market growth

• South America: The South American Gas Turbine Market is supported by rising electricity demand, industrial development, and investments in power-generation infrastructure. Brazil, Argentina, Chile, and Colombia contribute to regional demand through expanding industrial activities and energy projects. Natural-gas-fired turbines provide reliable and flexible electricity generation and support grid stability alongside renewable energy sources such as wind and solar.

Steam Trap Market Competitive Landscape

The global steam trap market remains competitive in 2025, with established manufacturers such as Spirax Sarco, Armstrong International, and TLV Corporation competing through extensive product portfolios, global distribution networks, and strong industrial customer relationships. These companies offer mechanical, thermodynamic, and thermostatic steam traps for applications across manufacturing, chemicals, pharmaceuticals, food processing, and power generation. Market competition increasingly focuses on energy efficiency, steam loss reduction, condensate management, operational reliability, and predictive maintenance. Digital monitoring technologies, wireless sensors, and Industrial Internet of Things (IIoT) solutions support real-time steam trap performance monitoring and early fault detection. Meanwhile, specialized technology providers such as Imperium Technologies and DCO Systems contribute to the development of electronic steam trap monitoring and energy-harvesting wireless sensor solutions. Regional manufacturers also compete by offering application-specific products and cost-effective solutions, while ongoing technological innovation and growing demand for industrial energy optimization shape the competitive landscape.

• Imperium Technologies (Launched in 2021, USA): Imperium Technologies is the maker of the InteliTrap, the first fully electronic steam trap in the industry specifically aimed at the elimination of the mechanical versions that are most of the time failure-prone. Its proprietary technology combines the fitted sensors and automated diagnostics into one unit thus allowing real-time health monitoring and exact condensate removal without losing steam, therefore, providing the industrial operators with the opportunity to move from reactive repairs to data-driven, proactive steam system management.

• DCO Systems (Launched in 2016, UK): DCO Systems is a company that energy-harvesting wireless sensor devices which are easy to use and should be the first choice if one wants to monitor steam traps and other industrial assets are their specialization. Their battery less "Easy STM" monitoring implementations are such that they take the thermal energy from the steam pipes and use it for the transmission of the performance data on a continuous basis thus completely doing away with the problem of battery replacements as well as the providing affordable, scalable visibility into steam trap health for complex manufacturing facilities.

Gas Turbine Market Report Scope:

The Gas Turbine Market research report includes product categorization, product application, development trend, product technology, competitive landscape, industrial chain structure, industry overview, national policy and planning analysis of the industry, and the most recent dynamic analysis, among other things. The study discusses the worldwide market's drivers, opportunities, and limitations. It discusses the influence of various drivers, trends, and constraints on market demand during the forecast period. The research also outlines market potential on a global scale.

The research includes the production time, base distribution, technical characteristics, research and development trends, technology sources, and raw material sources of significant Gas Turbine Market firms in terms of production bases and technologies. The more precise research also contains the key application areas of market and consumption, significant regions and consumption, major producers, distributors, raw material suppliers, equipment providers, and their contact information, as well as an analysis of the industry chain relationship. This report's study also contains product specifications, manufacturing processes, cost structure, and data information organized by area, technology, and application.

The objective of the report is to present a comprehensive analysis of the Gas Turbine Market including all the stakeholders of the Technology. The past and current status of the Technology with forecasted market size and trends are presented in the report with the analysis of complicated data in simple language. The report covers all the aspects of the Technology with a dedicated study of key players that includes market leaders, followers, and new entrants by region. PORTER, SVOR, and PESTEL analysis with the potential impact of micro-economic factors by region on the market have been presented in the report. External as well as internal factors that are supposed to affect the business positively or negatively have been analyzed, which will give a clear futuristic view of the Technology to the decision-makers.

The report also helps in understanding the Gas Turbine Market dynamics, and structure by analyzing the market segments and projecting the Gas Turbine Market size. Clear representation of competitive analysis of key players by type, price, financial position, Type portfolio, growth strategies, and regional presence in the Gas Turbine Market makes the report an investor’s guide.

Gas Turbine Market Recent Industry Developments

Date Company Development Impact on Gas Turbine Market
March 18, 2026 GE Vernova & IHI Successfully demonstrated 100% ammonia combustion using full-scale F-class gas turbine components, targeting commercial deployment by 2030. Accelerates low-carbon gas turbine technology and creates opportunities for ammonia-fueled power generation.
May 26, 2026 GE Vernova HA gas turbine fleet surpassed 4 million commercial operating hours, with 128 units operating across 21 countries and approximately 74 GW of capacity. Strengthens confidence in high-efficiency heavy-duty gas turbines and supports global fleet expansion and aftermarket services.
June 3, 2026 Siemens Energy Proposed gas turbine-based generation in Iowa to address a projected 30–60% increase in electricity demand by 2030, driven partly by data centers. Increases demand for flexible gas turbines capable of supporting data centers, industrial loads, and rapidly growing electricity demand.
June 30, 2026 Siemens Energy Confirms turbine supply for Oman’s planned Misfah and Duqm gas-fired power plants, representing a combined capacity of 2.6 GW. Expands gas-fired generation capacity in the Middle East and supports demand for large-scale combined-cycle power-generation technology.
October 5, 2026 Siemens Energy & Naftogaz Ukraine’s Naftogaz considers purchasing five gas-turbine compressor units from Siemens Energy and discusses the potential deployment of 12 gas turbine units for distributed power generation. Creates opportunities for gas-turbine-based gas infrastructure, distributed generation, and energy-system resilience.

Gas Turbine Market Scope: Inquiry Before Buying

Gas Turbine Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: US$ 23.80 Bn.
Forecast Period 2026 to 2034 CAGR: 4.6% Market Size in 2034: US$ 35.80 Bn.
Segments Covered: by Type Heavy Duty
Industrial
Aeroderivative
Industrial Gas Turbine
Marine Gas Turbine
by Technology Open cycle
Combined cycle
by Power Rating Less Than 40 MW
40 To 120 MW
121 To 300 MW
Above 300 MW
by Application Power generation
Oil & gas
Aerospace
Process plants
by Installation / Lifecycle New Installation
Replacement
Retrofit / Upgrade
Aftermarket & Maintenance

Gas Turbine Market by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Gas Turbine Market Key Players

North America
1. General Electric Vernova
2. Solar Turbines Incorporated
3. Baker Hughes
4. Elliott Group
5. Capstone Green Energy
6. Pratt & Whitney
7. Honeywell Aerospace
8. Howmet Aerospace
9. EthosEnergy
10. Williams International
Europe
11. Siemens Energy AG
12. Rolls-Royce Holdings plc
13. Ansaldo Energia
14. MAN Energy Solutions
15. MTU Aero Engines AG
16. OPRA Turbines
17. Kawasaki Gas Turbine Europe GmbH
18. Centrax Ltd.
19. Harbin Electric Europe
20. Sulzer Ltd. 21. Turboatom
22. Doosan Škoda Power
23. ABB Ltd.
24. Safran S.A.
Asia Pacific
25. Mitsubishi Heavy Industries Ltd.
26. Kawasaki Heavy Industries Ltd.
27. Hitachi Ltd.
28. IHI Corporation
29. Bharat Heavy Electricals Limited (BHEL)
30. Toshiba Energy Systems & Solutions
31. Harbin Electric Corporation
32. Shanghai Electric Group
33. Dongfang Electric Corporation
34. Nanjing Turbine & Electric Machinery Group
35. Hyundai Heavy Industries
36. Doosan Enerbility
37. Fuji Electric Co., Ltd.
38. Bharat Forge Ltd.
39. CSIC Gas Turbine Co., Ltd.
40. TPSC (Taiwan Power Service Corporation)
Middle East & Africa
41. Arabian Industries LLC
42. Saudi Arabian Industrial Investments Company (Dussur)
43. TAQA
44. Desert Technologies
45. Elsewedy Electric
46. Alstom Saudi Arabia
47. Enerflex Middle East
South America
48. WEG S.A. 49. TGM Turbinas
50. Termomecanica São Paulo S.A.
51. IMPSA
52. Tecnogera
Others

Frequently Asked Questions:

1] What segments are covered in the Global Gas Turbine Market report?
Ans. The segments covered in the Gas Turbine Market report are based on Type, Application, Technology, Power Rating, and Region.

2] Which region is expected to hold the highest share of the Global Gas Turbine Market?
Ans. The Asia Pacific region which includes countries such as China, South Korea, Japan are expected to hold the highest share of the Gas Turbine Market.

3] What is the market size of the Global Gas Turbine Market by 2034?
Ans. The market size of the Gas Turbine Market by 2034 is expected to reach USD 35.80 Bn.

4] What is the forecast period for the Global Gas Turbine Market?
Ans. The forecast period for the Gas Turbine Market is 2026-2034.

5] What was the market size of the Global Gas Turbine Market in 2025?
Ans. The market size of the Gas Turbine Market in 2025 was valued USD 23.80 Bn.

Table of Contents

1.SECTION A: GLOBAL GAS TURBINE MARKET INTRODUCTION 1.1. Global Gas Turbine Market size, historical evolution, and long-term industry growth outlook. (Value USD Bn. and Volume 000' units) 1.2. Industry ecosystem across power generation, industrial, marine, and oil & gas applications. 1.3. Comprehensive value chain assessment from component suppliers to end-user industries worldwide. 1.4. Key market participants shaping technological innovation and the global competitive industry landscape. 1.5. Emerging investment trends influencing future gas turbine manufacturing and deployment strategies. 1.6. Strategic market outlook driven by efficiency improvements and global energy transition initiatives. 1.7. Global Gas Turbine Market Dynamics & Strategic Industry Assessment 1.7.1. Market Trends 1.7.2. DROC Analysis 1.7.3. Drivers 1.7.4. Restraints 1.7.5. Opportunities 1.7.6. Challenges 1.7.7. PORTER'S Five Forces Analysis 1.7.8. PESTLE Analysis 1.8. Global Gas Turbine Market Landscape & Demand Assessment 1.8.1. Increasing electricity consumption is strengthening demand for reliable gas-fired power generation systems. 1.8.2. Combined-cycle power plants are improving operational efficiency through advanced gas turbine integration. 1.8.3. Industrialization and urbanization are driving captive power generation across manufacturing industries globally. 1.8.4. Grid modernization initiatives are increasing the deployment of flexible and fast-response gas turbines worldwide. 1.8.5. Growing renewable energy integration is enhancing demand for backup and balancing power solutions. 1.8.6. Expanding energy security initiatives supporting investments in modern gas turbine infrastructure. 1.9. Market Opportunity, Growth Potential & Investment Assessment 1.9.1. Untapped market opportunities emerging across utility-scale, industrial, and distributed energy applications. 1.9.2. Replacement demand for aging coal-fired plants creating significant commercial turbine opportunities globally. 1.9.3. Hydrogen-ready turbines expanding future market potential through low-carbon energy transition initiatives. 1.9.4. Emerging economies offering substantial investment opportunities in modern power generation infrastructure. 1.9.5. Oil & gas industry modernization increasing demand for advanced high-efficiency turbine systems. 1.9.6. Future market potential supported by grid expansion and industrial energy infrastructure development. 1.10. Gas Turbine Applications & Deployment Model Assessment 1.10.1. Combined-cycle gas turbine power plants improving efficiency across large-scale electricity generation projects. 1.10.2. Open-cycle gas turbine installations supporting rapid power generation during peak electricity demand. 1.10.3. Temporary mobile gas turbine solutions ensuring uninterrupted electricity supply during emergencies. 1.10.4. Rental turbine power plants addressing short-term industrial, utility, and disaster recovery requirements. 1.10.5. Utility-scale gas turbine projects supporting grid stability through flexible power generation capabilities. 1.10.6. Growing demand for temporary power solutions driven by infrastructure development and energy security. 1.11. Technology Evolution, Product Development & Innovation Assessment 1.11.1. Advanced turbine blade materials improving efficiency, durability, and operational performance significantly. 1.11.2. Aeroderivative gas turbines providing superior flexibility for distributed and industrial power applications. 1.11.3. Hydrogen combustion technologies reducing carbon emissions while supporting sustainable energy transition goals. 1.11.4. AI-enabled monitoring systems improving predictive maintenance and operational reliability across facilities. 1.11.5. Digital twin technologies enhancing equipment lifecycle management and performance optimization capabilities. 1.11.6. Continuous product innovation strengthening competitive differentiation among leading global manufacturers. 1.12. Global Supply Chain, Manufacturing Ecosystem & Component Availability Assessment 1.12.1. Global manufacturing capacity expansion supporting increasing demand for advanced gas turbine systems. 1.12.2. Critical component sourcing strategies improving production efficiency and operational supply resilience globally. 1.12.3. OEM manufacturing facilities strengthening regional production capabilities and export competitiveness. 1.12.4. Supply chain optimization reducing delivery timelines and improving equipment availability worldwide. 1.12.5. Localization initiatives enhancing domestic manufacturing capabilities across emerging industrial economies. 1.12.6. Strategic supplier partnerships ensuring uninterrupted availability of critical turbine components globally. 1.13. Fuel Compatibility, Combustion Technologies & Performance Assessment 1.13.1. Natural gas remains the dominant fuel for commercial gas turbine power generation. 1.13.2. Hydrogen blending technologies are improving fuel flexibility and reducing greenhouse gas emissions significantly. 1.13.3. Dual-fuel turbines support uninterrupted operations across industrial and utility-scale applications globally. 1.13.4. High-efficiency combustion systems minimizing operational costs and maximizing power generation output. 1.13.5. Fuel diversification strategies strengthening long-term energy security and operational sustainability initiatives. 1.13.6. Advanced combustion technologies improving overall thermal efficiency and environmental performance worldwide. 1.14. Pricing Trends, Capital Expenditure & Lifecycle Economics Assessment (2020–2025) 1.14.1. Raw material costs significantly influencing manufacturing expenses across global turbine production facilities. 1.14.2. Installation and commissioning costs impacting total lifecycle investment and customer purchasing decisions. 1.14.3. Operational efficiency improvements supporting higher profitability through reduced maintenance expenditures globally. 1.14.4. Premium turbine technologies generating higher value through superior efficiency and reliability performance. 1.14.5. Comparative Pricing Analysis of New, Used, Refurbished, and Upgraded Gas Turbines Across Major Capacity Categories. 1.14.6. Refurbishment and Retrofit Cost Structure, Service Provider Margins, and Lifecycle Cost Savings.. 1.15. Application Landscape & End-Use Industry Demand Assessment 1.15.1. Utility-scale power generation remains the largest commercial application for gas turbine systems. 1.15.2. Oil and gas operations utilizing turbines for compression and offshore energy production. 1.15.3. Industrial manufacturing facilities adopting gas turbines for reliable captive power generation solutions. 1.15.4. Marine sector increasingly deploying gas turbines for high-performance propulsion and auxiliary systems. 1.15.5. District heating applications expanding through efficient combined heat and power installations globally. 1.15.6. Aviation support facilities utilizing gas turbine technologies across specialized operational applications. 1.16. Distribution, Service Network & Aftermarket Assessment 1.16.1. Global OEM sales networks strengthening commercial market penetration across developed and emerging regions. 1.16.2. Long-term service agreements supporting stable recurring revenue and customer retention strategies. 1.16.3. Aftermarket services enhancing equipment reliability through predictive maintenance and technical support. 1.16.4. Spare parts availability improving operational continuity across industrial and utility-scale installations globally. 1.16.5. Secondary Gas Turbine Sales Channels, Equipment Brokers, Independent Resellers, and OEM-Certified Refurbishment Networks. 1.16.6. Commercial Relationships Among OEMs, Equipment Owners, Independent Service Providers, Refurbishment Contractors, and Secondary Market Buyers. 1.17. Global Secondary Gas Turbine Market & Refurbished Equipment Assessment 1.17.1. Global Secondary Gas Turbine Market Structure Covering Used, Pre-Owned, Refurbished, Reconditioned, and Recertified Gas Turbine Equipment. 1.17.2. Secondary Market Supply and Demand Assessment Across Power Generation, Oil & Gas, Industrial, and Marine Applications. 1.17.3. Global Installed Base of Gas Turbines, Equipment Age Profiles, Retirement Trends, and Availability of Used Turbines for Resale. 1.17.4. Secondary Gas Turbine Trading Ecosystem Covering Original Equipment Manufacturers (OEMs), Independent Dealers, Equipment Brokers, Refurbishment Companies, and End Users. 1.17.5. Used and Refurbished Gas Turbine Pricing Benchmarking by Equipment Type, Capacity, Age, Operating Hours, Technical Condition, and Remaining Useful Life. 1.17.6. Regional Secondary Market Opportunities, Cross-Border Equipment Trading, Asset Relocation, and Redeployment Across Developed and Emerging Economies. 1.17.7. Commercial Comparison of New, Used, and Refurbished Gas Turbines Based on Acquisition Cost, Lead Time, Operational Reliability, and Total Cost of Ownership. 1.17.8. Secondary Gas Turbine Market Size, Transaction Volumes, Revenue Opportunities, and Growth Outlook (2025–2034). 1.18. Global Gas Turbine Refurbishment, Retrofit & Upgrade Market Assessment (2025–2034) 1.18.1. Global Gas Turbine Refurbishment, Retrofit and Modernization Market Landscape, 2025 1.18.2. Refurbishment and Upgrade Demand by Application, Equipment Age and Operating Condition, 2025–2034 1.18.3. Gas Turbine Refurbishment Processes and Component Restoration Requirements, 2025 1.18.4. Retrofit Opportunities Across Turbine Blades, Combustion, Fuel, Control and Cooling Systems, 2025–2034 1.18.5. Technology Upgrades Covering Advanced Materials, Digital Controls, Condition Monitoring and Predictive Maintenance, 2025–2034 1.18.6. Performance Improvement Assessment Covering Efficiency, Power Output, Fuel Consumption, Emissions and Equipment Life Extension, 2025–2034 1.18.7. Refurbishment and Retrofit Cost Comparison with New Equipment Replacement, 2025–2034 1.18.8. Project Economics Based on Investment, Downtime, Maintenance Costs and Total Cost of Ownership, 2025–2034 1.18.9. Global Gas Turbine Refurbishment, Retrofit and Upgrade Market Size, Revenue and Growth Forecast, 2025–2034 1.18.10. Refurbishment vs. Retrofit vs. Upgrade vs. Replacement Decision Analysis, 2025–2034 1.19. Power Generation Applications & Operating Profile Assessment 1.19.1. Independent power producers and merchant power plants driving utility-scale turbine procurement decisions. 1.19.2. Peaking and grid-balancing power stations leveraging fast-start turbines to offset renewable intermittency. 1.19.3. Captive industrial cogeneration facilities adopting turbines for reliable, cost-efficient on-site electricity. 1.19.4. Government-led rural electrification and grid-extension programs expanding gas turbine power generation deployments. 1.19.5. Power purchase agreement structures and tariff frameworks shaping utility-scale turbine investment decisions. 1.20. Aviation Gas Turbine Deployment & Performance Analysis 1.20.1. Auxiliary power units and ground power systems utilizing small-scale aeroderivative turbines at airports. 1.20.2. Airport and aviation infrastructure facilities adopting turbines for uninterrupted backup power reliability. 1.20.3. Military and defense aviation programs driving demand for high-performance turbine propulsion systems. 1.20.4. Engine maintenance, repair and overhaul ecosystem supporting aviation-grade turbine component demand. 1.21. Marine Gas Turbine Technology & Vessel Application Analysis 1.21.1. Marine Gas Turbine Adoption for Naval Propulsion Systems 1.21.2. Gas Turbine Propulsion Deployment in Frigates, Destroyers, Corvettes, and Other Naval Vessels 1.21.3. Marine Gas Turbine Use in High-Speed Commercial and Passenger Vessels 1.21.4. Gas Turbine Combined-Cycle and Combined Gas-and-Gas (COGAG) Propulsion Configurations 1.21.5. Gas Turbine Combined Diesel-and-Gas (CODAG) and Combined Diesel-Electric-and-Gas (CODLAG) Systems 1.21.6. Marine Gas Turbine Fuel Flexibility and Low-Emission Combustion Requirements 1.22. Regulatory, Environmental & Safety Assessment 1.22.1. Global emission regulations encouraging development of cleaner and more efficient gas turbines. 1.22.2. Energy efficiency standards driving technological improvements across commercial turbine manufacturing worldwide. 1.22.3. Industrial safety regulations ensuring reliable operation of high-capacity gas turbine installations globally. 1.22.4. Environmental compliance frameworks influencing future product development and commercialization strategies significantly. 1.22.5. Hydrogen safety standards supporting secure deployment of next-generation gas turbine technologies worldwide. 1.22.6. Government energy policies encouraging investments in sustainable gas turbine infrastructure development. 1.23. Regional Demand & Production Assessment 1.23.1. North America leading investments in flexible gas-fired power generation infrastructure modernization initiatives. 1.23.2. Europe accelerating hydrogen-ready turbine deployment through ambitious decarbonization and energy transition policies. 1.23.3. Military and defense aviation programs driving demand for high-performance turbine propulsion systems. 1.23.4. Engine maintenance, repair, and overhaul ecosystem supporting aviation-grade turbine component demand. 1.24. Marine Gas Turbine Technology & Vessel Application Analysis 1.24.1. Aviation-support facilities utilizing gas turbines for auxiliary power units and specialized ground-support applications. 1.24.2. Marine gas turbine adoption across naval propulsion systems and selected high-speed commercial vessels. 1.24.3. Gas turbine propulsion deployment in frigates, destroyers, corvettes, and other naval vessels. 1.24.4. Marine propulsion configurations covering combined gas and gas (COGAG), combined diesel and gas (CODAG), and combined diesel-electric and gas (CODLAG) systems. 1.24.5. Marine turbine fuel flexibility, compact power density, and emissions requirements influencing vessel-level deployment decisions. 1.24.6. Specialized turbine applications assessed according to performance requirements, operating environment, reliability, and maintenance needs. 1.25. Competitive Technology & Innovation Assessment 1.25.1. Research and development investments accelerating commercialization of advanced gas turbine technologies globally. 1.25.2. Patent activity strengthening competitive differentiation through innovative combustion and efficiency improvements. 1.25.3. AI-driven optimization enhancing operational performance across commercial gas turbine installations worldwide. 1.25.4. Advanced materials improving equipment durability and reducing long-term maintenance requirements significantly. 1.25.5. Collaborative innovation partnerships accelerating next-generation turbine technology commercialization across global markets. 1.25.6. Continuous innovation supporting sustainable competitive advantages among leading turbine manufacturers globally. 1.26. Trade, Export–Import & Assessment (2025) 1.26.1. International trade supporting balanced global supply and commercial turbine market expansion worldwide. 1.26.2. Export-oriented manufacturing hubs strengthening regional competitiveness across global turbine production markets. 1.26.3. Import dependency influencing procurement strategies and commercial project development across regions. 1.26.4. Trade policies impacting international equipment movement and global manufacturing competitiveness significantly. 1.26.5. Logistics optimization improving timely delivery of high-value gas turbine equipment globally. 1.26.6. Regional supply chain integration supporting long-term commercial market growth and stability. 1.27. Investment, Capacity Expansion & Strategic Development Assessment 1.27.1. Manufacturing investments supporting increased production capacity for advanced gas turbine technologies globally. 1.27.2. Strategic mergers and acquisitions strengthening technological capabilities and regional market presence significantly. 1.27.3. Capacity expansion projects supporting increasing commercial demand across global power generation markets. 1.27.4. Joint ventures accelerating innovation and international technology transfer across turbine manufacturing companies. 1.27.5. Government infrastructure investments encouraging modernization of commercial energy generation facilities globally. 1.27.6. Capital expenditure initiatives enhancing operational efficiency and future manufacturing competitiveness worldwide. 1.28. Future Market Outlook & Growth Opportunity Assessment 1.28.1. Distributed energy systems creating significant long-term commercial growth opportunities for gas turbines. 1.28.2. Hydrogen economy expansion supporting next-generation turbine technology adoption across global markets. 1.28.3. Combined-cycle power plants expected to remain the dominant commercial application throughout the forecast period. 1.28.4. Emerging economies presenting attractive investment opportunities through expanding energy infrastructure development. 1.28.5. Artificial intelligence accelerating operational efficiency and predictive maintenance across turbine installations worldwide. 1.28.6. Future market growth driven by innovation, sustainability, and global energy transition initiatives. 1.29. Global Gas Turbine Market: Market Size and Forecast by Segmentation (by Value USD Billion and Volume in 000’ Units) (2025-2034) 1.29.1. Global Gas Turbine Market Size and Forecast, By Type 1.29.1.1. Heavy Duty 1.29.1.2. Industrial 1.29.1.3. Aeroderivative 1.29.1.4. Industrial Gas Turbine 1.29.1.5. Marine Gas Turbine 1.29.2. Global Gas Turbine Market Size and Forecast, By Technology 1.29.2.1. Open cycle 1.29.2.2. Combined cycle 1.29.3. Global Gas Turbine Market Size and Forecast, By Rating Capacity 1.29.3.1. Less Than 40 MW 1.29.3.2. 40 To 120 MW 1.29.3.3. 121 To 300 MW 1.29.3.4. Above 300 MW 1.29.4. Global Gas Turbine Market Size and Forecast, by Installation / Lifecycle 1.29.4.1. New Installation 1.29.4.2. Replacement 1.29.4.3. Retrofit / Upgrade 1.29.4.4. Aftermarket & Maintenance 1.29.5. Global Gas Turbine Market Size and Forecast, by Application 1.29.5.1. Power Generation 1.29.5.2. Aviation 1.29.5.3. Marine 1.29.5.4. Oil and Gas 1.29.5.5. Other End-User Industries. 1.29.6. Global Gas Turbine Market Size and Forecast, By Regions 1.29.6.1. North America 1.29.6.2. Europe, 1.29.6.3. Asia Pacific 1.29.6.4. Middle East & Africa 1.29.6.5. South America 2. SECTION B – COMPETITIVE INTELLIGENCE & GLOBAL GAS TURBINE ECOSYSTEM 2.1. Competitive Landscape 2.1.1. MMR Competitive Matrix 2.1.2. Company Positioning Matrix 2.1.3. Key Company Benchmarking 2.1.4. Parameters 2.1.5. Company Overview 2.1.6. Headquarters 2.1.7. Year of Establishment 2.1.8. Employee Strength 2.1.9. Business Portfolio 2.1.10. Manufacturing Facilities 2.1.11. Production Capacity 2.1.12. Geographic Presence 2.1.13. Revenue Analysis 2.1.14. R&D Capabilities 2.1.15. Patent Portfolio 2.1.16. Sustainability Initiatives 2.1.17. Strategic Developments 2.1.18. Future Growth Strategies 2.1.19. Total Company Revenue (2025) 2.1.20. Product Revenue (2025), 2.1.21. Certifications and Quality Standards 2.1.22. Geographic Presence 2.1.23. Market Structure 2.1.24. Market Leaders 2.1.25. Market Followers 2.1.26. Emerging and Specialized Component Suppliers 2.1.27. Company Revenue Growth / YoY Growth (%) 2.1.28. Operating Profit Margin (%), Where Available 2.1.29. R&D Expenditure and R&D Intensity (%) 2.1.30. Revenue vs. Net Earnings – Financial Health Benchmarking (2025) 2.1.31. Revenue Performance and Financial Analysis (2025) 2.1.32. Mergers, Acquisitions and Strategic Investments 2.1.33. Recent Key Developments 2.2. Competitive Market Structure & Strategic Positioning Assessment 2.2.1. Global competitive landscape across gas turbine OEMs and power equipment manufacturers. 2.2.2. Market positioning based on technology leadership, efficiency, and product diversification strategies. 2.2.3. Competitive differentiation across utility-scale, industrial, marine, and oil & gas applications. 2.2.4. Regional competitiveness supported by manufacturing footprint and global service capabilities. 2.2.5. Strategic collaborations accelerating hydrogen-ready turbine technology commercialization globally. 2.3. Revenue & Market Share Assessment 2.3.1. Revenue comparison among leading global gas turbine manufacturers. 2.3.2. Regional market share across utility and industrial turbine installations worldwide. 2.3.3. Product-wise revenue contribution by heavy-duty and aeroderivative gas turbines. 2.3.4. End-use revenue distribution across power generation, oil & gas, marine, and industrial sectors. 2.3.5. Sales growth comparison among major global turbine manufacturers. 2.3.6. Market concentration analysis of leading gas turbine OEMs. 2.4. Product Portfolio & Technology Benchmarking Assessment 2.4.1. Heavy-duty and aeroderivative turbine portfolio comparison across leading manufacturers. 2.4.2. Hydrogen-ready turbine technology benchmarking among global industry participants. 2.4.3. Combined-cycle efficiency comparison across commercial turbine platforms. 2.4.4. Digital monitoring and predictive maintenance capability benchmarking. 2.4.5. Power output range comparison across utility-scale and industrial gas turbines. 2.4.6. Product innovation assessment supporting future competitive differentiation. 2.5. Manufacturing Footprint & Supply Chain Assessment 2.5.1. Global manufacturing facility comparison among leading gas turbine manufacturers. 2.5.2. Production capacity benchmarking across major OEM manufacturing locations. 2.5.3. Critical component sourcing and supplier ecosystem assessment. 2.5.4. Supply chain resilience supporting uninterrupted commercial turbine production. 2.5.5. Localization strategies improving regional manufacturing competitiveness. 2.5.6. Capacity expansion supporting increasing global turbine demand. 2.6. Distribution, Service Network & Aftermarket Benchmarking 2.6.1. Competitive Benchmarking of Leading Gas Turbine OEMs, Independent Service Providers, Equipment Dealers, and Refurbishment Specialists. 2.6.2. OEM versus Third-Party Refurbishment and Upgrade Service Capabilities Across Heavy-Duty, Industrial, and Aeroderivative Gas Turbines. 2.6.3. Comparison of Secondary Equipment Sales Networks, Used Turbine Inventory Availability, Equipment Sourcing Capabilities, and Geographic Market Coverage. 2.6.4. Refurbishment and Upgrade Service Benchmarking Based on Technical Capabilities, Component Repair Expertise, Turnaround Time, Warranty Coverage, and Pricing Competitiveness. 2.6.5. Strategic Relationships and Partnerships Between Gas Turbine Manufacturers, Independent Repair Companies, Equipment Resellers, and End-User Industries. 2.7. Strategic Developments & Business Expansion Assessment 2.7.1. Strategic mergers and acquisitions strengthening global market leadership. 2.7.2. Manufacturing capacity expansion supporting future turbine demand. 2.7.3. Product launches focused on hydrogen-ready and high-efficiency turbine platforms. 2.7.4. Strategic partnerships accelerating clean energy technology development. 2.7.5. Investments in digitalization, AI, and predictive maintenance solutions. 2.7.6. Regional expansion initiatives strengthening commercial market presence. 2.8. Company Profiles 2.8.1. Company Overview 2.8.2. Financial Overview 2.8.3. Business Segments 2.8.4. Turbine Technology 2.8.5. Manufacturing Facilities 2.8.6. Production Capacity 2.8.7. Geographic Presence 2.8.8. Recent Developments 2.8.9. SWOT Analysis 2.8.10. Key Players 2.8.10.1 North America 2.8.10.1. General Electric Vernova 2.8.10.2. Solar Turbines Incorporated 2.8.10.3. Baker Hughes 2.8.10.4. Elliott Group 2.8.10.5. Capstone Green Energy 2.8.10.6. Pratt & Whitney 2.8.10.7. Honeywell Aerospace 2.8.10.8. Howmet Aerospace 2.8.10.9. EthosEnergy 2.8.10.10. Williams International 2.8.10.10.1 Europe 2.8.10.11. Siemens Energy AG 2.8.10.12. Rolls-Royce Holdings plc 2.8.10.13. Ansaldo Energia 2.8.10.14. MAN Energy Solutions 2.8.10.15. MTU Aero Engines AG 2.8.10.16. OPRA Turbines 2.8.10.17. Kawasaki Gas Turbine Europe GmbH 2.8.10.18. Centrax Ltd. 2.8.10.19. Harbin Electric Europe 2.8.10.20. Sulzer Ltd. 2.8.10.21. Turboatom 2.8.10.22. Doosan Škoda Power 2.8.10.23. ABB Ltd. 2.8.10.24. Safran S.A. 2.8.10.24.1 Asia Pacific 2.8.10.25. Mitsubishi Heavy Industries Ltd. 2.8.10.26. Kawasaki Heavy Industries Ltd. 2.8.10.27. Hitachi Ltd. 2.8.10.28. IHI Corporation 2.8.10.29. Bharat Heavy Electricals Limited (BHEL) 2.8.10.30. Toshiba Energy Systems & Solutions 2.8.10.31. Harbin Electric Corporation 2.8.10.32. Shanghai Electric Group 2.8.10.33. Dongfang Electric Corporation 2.8.10.34. Nanjing Turbine & Electric Machinery Group 2.8.10.35. Hyundai Heavy Industries 2.8.10.36. Doosan Enerbility 2.8.10.37. Fuji Electric Co., Ltd. 2.8.10.38. Bharat Forge Ltd. 2.8.10.39. CSIC Gas Turbine Co., Ltd. 2.8.10.40. TPSC (Taiwan Power Service Corporation) 2.8.10.40.1 Middle East & Africa 2.8.10.41. Arabian Industries LLC 2.8.10.42. Saudi Arabian Industrial Investments Company (Dussur) 2.8.10.43. TAQA 2.8.10.44. Desert Technologies 2.8.10.45. Elsewedy Electric 2.8.10.46. Alstom Saudi Arabia 2.8.10.47. Enerflex Middle East 2.8.10.47.1 South America 2.8.10.48. WEG S.A. 2.8.10.49. TGM Turbinas 2.8.10.50. Termomecanica São Paulo S.A. 2.8.10.51. IMPSA 2.8.10.52. Tecnogera 2.8.10.52.1 Others 3.SECTION C - KEY INSIGHTS, STRATEGIC OUTLOOK & METHODOLOGICAL FRAMEWORK 3.1. Key Findings 3.2. Strategic Moves & Industry Outlook 3.3. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements