Veterinary Drugs Market - Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning / Landscape Review & Global Market Size Forecast to 2034

6.44%
CAGR (2026-2034)
30.54 USD Bn.
Forecast Market Size
329
Report Pages
123
Market Tables

Overview

The Veterinary Drugs Market size was valued at USD 30.54 Billion in 2025 and the total revenue is expected to grow at a CAGR of 6.44% from 2026 to 2034, reaching USD 53.05 Billion by 2034.

Veterinary Drugs Market Overview

Veterinary drugs are medicines designed to keep animals healthy, prevent diseases, and treat health conditions in both companion animals and livestock. The market includes anti-infective drugs, anti-inflammatory drugs, parasiticides, pain-management medicines, dermatology treatments, gastrointestinal medicines, cardiovascular drugs, hormonal treatments, and other veterinary pharmaceuticals. These products are available in different forms such as oral medicines, injections, tablets, liquids, and topical treatments, depending on the animal and the disease being treated. Regulatory agencies are also playing an important role in bringing safer and more effective medicines to the market. For example, the U.S. FDA Center for Veterinary Medicine maintains the Green Book, which provides information on approved and conditionally approved animal drugs and is updated regularly. This continued approval activity supports the introduction of new treatments and creates opportunities for pharmaceutical companies to expand their veterinary product portfolios.

The Veterinary Drugs Market is expanding as animal owners, farmers, and veterinary professionals place greater importance on early treatment, disease prevention, and better animal health. Growing pet ownership is increasing demand for medicines for dogs and cats, while livestock producers are looking for effective treatments that help maintain animal health and farm productivity. This demand is encouraging major animal-health companies to expand their product portfolios, enter new markets, and invest in new therapies. Zoetis, for example, generated USD 9.47 billion in revenue in 2025, operated in more than 100 countries, and maintained around 300 product lines across major animal-health categories. The wider disease-control need is also significant: the World Organisation for Animal Health (WOAH) reported that 47% of animal diseases with available information had zoonotic potential, highlighting the importance of disease monitoring and treatment. As disease prevention, responsible antimicrobial use, companion-animal healthcare, and livestock health become increasingly important, pharmaceutical companies are expanding their presence across these high-demand areas.

Veterinary Drugs Market Share and Growth Analysis
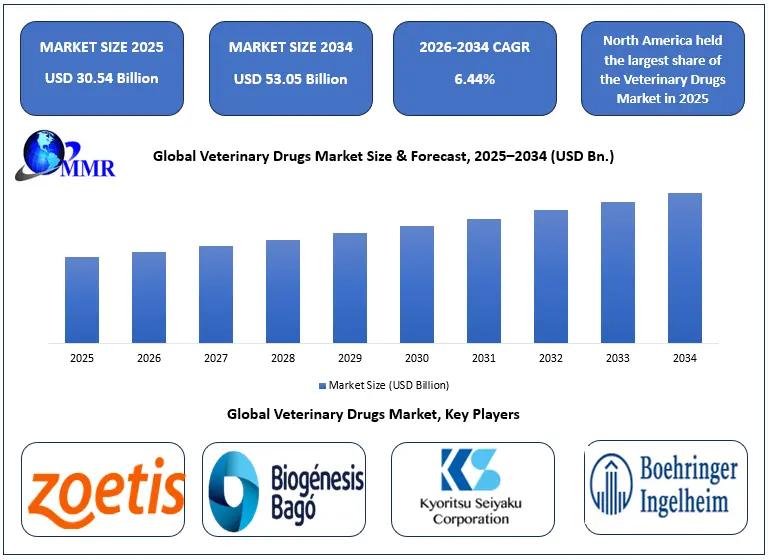
Veterinary Drugs Market Growth

To know about the Research Methodology :- Request Free Sample Report

The MMR Veterinary Drugs Market Report will help clients understand not only how the market is expanding, but also where companies are expanding and what is driving that expansion. The report will provide detailed analysis by drug type, animal type, route of administration, distribution channel, application, and region, along with market dynamics covering drivers, restraints, opportunities, challenges, emerging therapies, regulatory changes, disease trends, product launches, partnerships, acquisitions, and competitive strategies. It will also examine leading companies, their product portfolios, geographic expansion, investments, and strategic developments to show how competition is changing across the industry. Data and insights from organizations such as the U.S. FDA and WOAH will add regulatory and animal-health context to the analysis. By connecting market demand with company expansion, product innovation, regulatory developments, and regional opportunities, the report will give clients a clearer view of where future business opportunities are emerging in the global veterinary drugs industry.

Veterinary Drugs Market Dynamics

Rising Disease Risks and Greater Focus on Animal Health Are Driving Demand for Veterinary Drugs

The increasing occurrence of infectious and zoonotic animal diseases is encouraging farmers, pet owners, and veterinarians to focus more strongly on early treatment, disease prevention, and animal healthcare. According to the World Organisation for Animal Health (WOAH), 47% of reported animal diseases with available information had zoonotic potential, while outbreaks of bird flu in mammals more than doubled in 2024 compared with 2023. These developments are increasing the need for anti-infectives, parasiticides, anti-inflammatory drugs, and other veterinary treatments, encouraging pharmaceutical companies to expand their animal-health portfolios.

Strict Drug Approval Requirements and Regulatory Compliance Are Restraining the Expansion of Veterinary Drug Manufacturers

Veterinary pharmaceutical companies must meet detailed requirements related to drug safety, efficacy, manufacturing quality, labeling, and animal and food safety before products can be commercialized. In the U.S., the FDA categorizes animal drug applications into NADAs, ANADAs, and CNADAs, covering new, generic, and conditionally approved products. The FDA also updates its Green Book every month, creating an ongoing regulatory and compliance requirement for manufacturers. These processes can increase development timelines and costs, particularly for smaller companies entering the veterinary pharmaceutical industry.

Preventive Healthcare and New Treatment Approaches Are Creating Expansion Opportunities for Veterinary Pharmaceutical Companies

The shift toward preventive healthcare, targeted treatment, long-acting formulations, combination therapies, and species-specific medicines is creating opportunities for companies to develop differentiated products. FDA approval activity demonstrates this continued product development: its recent approvals include treatments for dogs, cats, cattle, horses, chickens, and other animal groups, covering conditions ranging from pain and inflammation to parasitic and infectious diseases. For example, the FDA approved BRAVECTO QUANTUM, an extended-release injectable treatment providing flea and tick control for dogs for periods extending up to 12 months for certain infestations. Such product innovation gives companies opportunities to improve treatment convenience while expanding their presence in specific therapeutic and animal segments.

Antimicrobial Resistance and Responsible Drug Use Are Creating Major Challenges for Veterinary Drug Companies

Growing attention to antimicrobial resistance (AMR) is changing how antibiotics and other antimicrobial medicines are used in animal healthcare. WOAH's latest data, covering 71% of the world's animal biomass, showed that antimicrobial use in animals declined by 5% between 2020 and 2022, from 102 mg to 97 mg per kg of animal biomass. The reduction was even greater in Europe, where antimicrobial use fell by 23% during the same period. This trend is creating pressure on pharmaceutical companies to support responsible antimicrobial use while developing new antibiotics, alternative therapies, vaccines, diagnostics, and preventive healthcare solutions that can reduce dependence on conventional antimicrobial treatments.

Key Market Trends in the Veterinary Drugs Market

Key Trend Market Development
Preventive Animal Healthcare Longer-acting and preventive treatments are gaining demand, reducing dosing frequency and improving treatment convenience.
Expansion into Minor Species Drug development is expanding toward sheep, goats, fish, exotic animals, and less-common diseases under the FDA’s 2026–2028 MUMS Blueprint.
Multi-Purpose Treatments Combination products addressing multiple health risks are gaining attention, such as Zoetis’ Simparica Trio.
Focus on Antimicrobial Resistance Stricter approaches to antimicrobial use are influencing veterinary drug development and approval requirements.
Growth of Specialty Therapies Monoclonal antibodies and targeted treatments are expanding, particularly for companion-animal conditions.
Response to Emerging Diseases New disease threats are encouraging companies to develop and adapt treatments for faster animal-health response.

Veterinary Drugs Market Segment Analysis

By Product
The veterinary drugs market is segmented into Anti-infectives, Anti-inflammatory, Parasiticides, and Others. Anti-infectives are widely used to manage bacterial and other infectious diseases in animals, while anti-inflammatory drugs support the treatment of pain, swelling, and inflammatory conditions. Parasiticides are increasingly important for controlling fleas, ticks, worms, and other parasites, particularly in companion animals and livestock. The Others category includes products such as hormonal, cardiovascular, gastrointestinal, and dermatological medicines. Growing preventive animal healthcare and the need for faster disease management are encouraging pharmaceutical companies to expand their veterinary drug portfolios across these product categories.

By Animal
The market is segmented into Companion, Livestock, and Others based on the type of animal treated. Companion animals, particularly dogs and cats, are generating increasing demand for preventive medicines, parasite control products, pain management, and specialty therapies. Livestock remains an important segment because veterinary drugs are essential for maintaining animal health, controlling disease outbreaks, and supporting productivity in cattle, poultry, swine, and other farm animals. The Others segment includes animals such as horses, fish, and exotic species. Companies are expanding their product portfolios across both companion and livestock applications as spending on animal health and disease prevention increases.

Veterinary Drugs Market Segment Insights
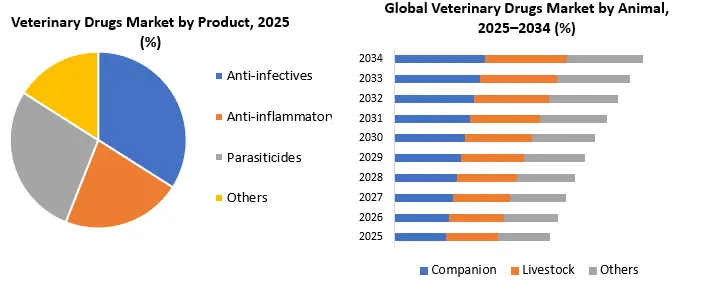
Veterinary Drugs Market Segment Analysis

Global Veterinary Drugs Market Regional Analysis

North America
North America holds a significant position in the global veterinary drugs market, supported by high spending on companion-animal healthcare, advanced veterinary infrastructure, large-scale livestock production, and strong pharmaceutical research. The United States is the leading country in the region, with strong demand for anti-infectives, parasiticides, anti-inflammatory drugs, and specialty therapies for dogs and cats. Canada benefits from established veterinary services and livestock healthcare demand, while Mexico is supported by growing cattle, poultry, and swine production. The region also benefits from a well-established regulatory framework through the U.S. FDA, which supports the development and approval of animal medicines.

Europe
Europe represents a mature veterinary drugs market, driven by preventive animal healthcare, well-developed veterinary services, and strict animal-health regulations. Germany, the United Kingdom, France, Italy, and Spain are major countries contributing to regional demand. Companion-animal healthcare is expanding alongside continued demand for livestock medicines. The region is also placing greater emphasis on responsible antimicrobial use and innovative treatment development. In 2025, the European Medicines Agency recommended 30 veterinary medicines for marketing authorisation, highlighting continued activity in veterinary drug development and product approvals.

Asia Pacific
Asia Pacific is experiencing strong growth in veterinary drug demand due to its large livestock population, rising pet ownership, expanding aquaculture sector, and improving veterinary healthcare infrastructure. China and India are major markets, supported by large cattle, poultry, swine, and other livestock populations. Japan and South Korea have established companion-animal healthcare markets, while Australia has significant demand for livestock medicines due to its large agricultural and animal-production sector. As animal-health awareness improves and producers focus more on disease prevention and productivity, pharmaceutical companies are expanding their veterinary product portfolios and distribution networks across countries in the region.

Middle East & Africa
The Middle East & Africa market is supported by growing investment in livestock healthcare, poultry and dairy production, food-security programs, and veterinary infrastructure. Saudi Arabia, the UAE, South Africa, Egypt, and Israel are important markets within the region. The expansion of commercial dairy and poultry farms in Gulf countries is increasing demand for anti-infectives, parasiticides, and preventive medicines. In Africa, veterinary drug demand is closely linked to livestock disease control, improving access to veterinary services, and efforts to reduce productivity losses caused by animal diseases.

South America
South America has strong demand for veterinary drugs because of its extensive cattle, poultry, and swine industries. Brazil is the leading market in the region, supported by large-scale beef and poultry production and its position as a major agricultural exporter. Argentina also has substantial livestock production, while Chile, Colombia, and Peru contribute to demand through livestock, poultry, aquaculture, and companion-animal healthcare. Increasing focus on herd health, disease prevention, food safety, and compliance with export requirements is encouraging producers to adopt veterinary medicines and structured animal-health programs.

Global Veterinary Drugs Market Competitive Landscape

The Global Veterinary Drugs Market is highly competitive, with companies focusing on product innovation, new drug approvals, companion-animal healthcare, livestock medicines, parasiticides, anti-infectives, and geographic expansion. Key players include Zoetis Services LLC, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco Animal Health Inc., Dechra Pharmaceuticals PLC, Ceva Santé Animale, Phibro Animal Health Corporation, Virbac S.A., Bimeda, Biogénesis Bagó, Vetoquinol S.A., Bayer AG, Norbrook Laboratories, HIPRA, Huvepharma, Kyoritsu Seiyaku Corporation, and other regional veterinary pharmaceutical companies. Competition varies across animal species, product categories, and geographic markets, with companies differentiating themselves through new product development, clinical research, regulatory approvals, product quality, veterinary support, and distribution networks.

Zoetis Services LLC maintains a broad portfolio covering companion animals and livestock, with products spanning parasiticides, vaccines, anti-infectives, pain management, and other animal-health applications. Elanco Animal Health Inc. competes across pet health and farm animal healthcare, while Merck & Co., Inc. and Boehringer Ingelheim International GmbH maintain extensive portfolios across vaccines, parasiticides, anti-infectives, and livestock health solutions. Companies such as Dechra Pharmaceuticals PLC, Virbac S.A., Vetoquinol S.A., Ceva Santé Animale, and Norbrook Laboratories strengthen competition through specialized veterinary medicines and species-specific treatment solutions.

The competitive environment is also shaped by new product launches, regulatory approvals, strategic partnerships, acquisitions, biotechnology development, generic medicines, and expansion into emerging veterinary applications. Companies are increasingly investing in targeted therapies, preventive healthcare, long-acting formulations, and treatments for emerging animal diseases. As demand for veterinary drugs increases across companion animals and livestock, manufacturers are expanding their product portfolios, strengthening distribution networks, and entering new geographic markets to capture emerging opportunities.
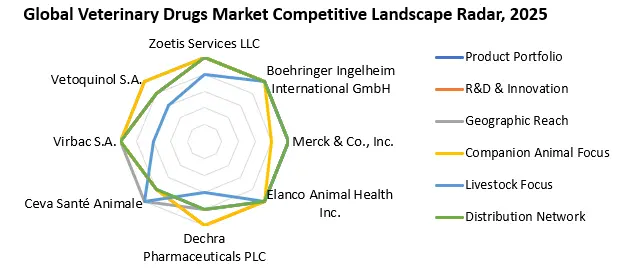
Veterinary Drugs Market Competitive Landscape

Recent Developments in the Global Veterinary Drugs Market

Date Company / Organization Recent Development Market Significance
August 2026 Zoetis Received FDA Emergency Use Authorization for Simparica Trio to treat New World screwworm infestations in dogs and puppies. Expands the use of an established veterinary drug against an emerging animal-health threat.
August 2026 FDA Finalized Guidance for Industry #152 for evaluating the antimicrobial-resistance risks of new animal drugs. Shapes future antimicrobial drug development and regulatory strategies.
June 2026 FDA Released the 2026–2028 MUMS Blueprint to improve development and availability of drugs for minor species and uncommon diseases. Creates new opportunities for veterinary drug development in underserved animal-health segments.
May 2026 Elanco Animal Health Launched Befrena (tirnovetmab), an anti-IL-31 monoclonal antibody for canine allergic and atopic dermatitis, with a 6–8 week dosing interval. Strengthens specialty veterinary therapies and long-acting companion-animal treatments.
May 2026 FDA Authorized Dectomax/Dectomax-CA1 for use against New World screwworm in multiple animal species. Demonstrates rapid regulatory response to emerging livestock and animal disease threats.
September 2026 FDA Authorized Capstar and revised the authorization for generic nitenpyram tablets for prevention and treatment of New World screwworm in dogs and cats. Expands preventive treatment options and addresses an emerging unmet need in companion-animal health.

Veterinary Drugs Market Scope: Inquire before buying

Global Veterinary Drugs Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 30.54 Bn.
Forecast Period 2026 to 2034 CAGR: 6.44% Market Size in 2034: USD 53.05 Bn.
Segments Covered: by Product Anti-infectives
Anti-inflammatory
Parasiticides
Others
by Animal Companion
Livestock
Others
by Route of Administration Oral
Injectable
Topical
Others
by Distribution Channel Veterinary Clinics and Hospitals
Retail Pharmacies and Veterinary Pharmacies
E-commerce Platforms
Others

Veterinary Drugs Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Veterinary Drugs Market, Key Players

1. Zoetis Services LLC
2. Boehringer Ingelheim International GmbH
3. Merck & Co., Inc.
4. Elanco Animal Health Inc.
5. Dechra Pharmaceuticals PLC
6. Ceva Santé Animale
7. Phibro Animal Health Corporation
8. Virbac S.A.
9. Bimeda
10. Biogénesis Bagó
11. Vetoquinol S.A.
12. Bayer AG
13. Archer Daniels Midland
14. Evonik Industries AG
15. Veterinary Pharmaceutical Solutions
16. Norbrook Laboratories
17. Chanelle Pharma
18. Hipra
19. Nexvet
20. Kyoritsu Seiyaku Corporation
21. Huvepharma
22. Troy Laboratories
23. Jurox
24. Vivaldis
25. VetViva Richter GmbH
26. Vetiquinol
27. WuXi Biologics.
28. Mediwin Laboratories
29. Vetnation Pharma
30. Vee Remedies

Frequently Asked Questions:

1] What segments are covered in the Veterinary Drugs Market report?
Ans. The segments covered in the Veterinary Drugs Market report are based on Product, Animal, Route of Administration, Distribution Channel, and region

2] Which region is expected to hold the highest share of the Veterinary Drugs Market?
Ans. North America region is expected to hold the highest share of the Veterinary Drugs Market.

3] What is the market size of the Veterinary Drugs Market by 2034?
Ans. The market size of the Veterinary Drugs Market by 2034 is USD 53.05 Bn.

4] What is the growth rate of the Veterinary Drugs Market?
Ans. The Global Veterinary Drugs Market is growing at a CAGR of 6.44% during the forecasting period 2026-2034.

5] What was the market size of the Veterinary Drugs Market in 2025?
Ans. The market size of the Veterinary Drugs Market in 2025 was USD 30.54 Bn.

Table of Contents

1. Veterinary Drugs Market Introduction 1.1. Study Assumption and Market Definition 1.2. Scope of the Study 1.3. Executive Summary 2. Global Veterinary Drugs Market: Competitive Landscape 2.1. MMR Competition Matrix 2.2. Competitive Landscape 2.3. Key Players Benchmarking 2.3.1. Company Name 2.3.2. Business Segment 2.3.3. End-user Segment 2.3.4. Revenue (2025) 2.3.5. Company Locations 2.4. Leading Veterinary Drugs Market Companies, by market capitalization 2.5. Market Structure 2.5.1. Market Leaders 2.5.2. Market Followers 2.5.3. Emerging Players 2.6. Mergers and Acquisitions Details 3. Veterinary Drugs Market: Dynamics 3.1. Veterinary Drugs Market Trends by Region 3.1.1. North America Veterinary Drugs Market Trends 3.1.2. Europe Veterinary Drugs Market Trends 3.1.3. Asia Pacific Veterinary Drugs Market Trends 3.1.4. Middle East and Africa Veterinary Drugs Market Trends 3.1.5. South America Veterinary Drugs Market Trends 3.2. Veterinary Drugs Market Dynamics by Region 3.2.1. North America 3.2.1.1. North America Veterinary Drugs Market Drivers 3.2.1.2. North America Veterinary Drugs Market Restraints 3.2.1.3. North America Veterinary Drugs Market Opportunities 3.2.1.4. North America Veterinary Drugs Market Challenges 3.2.2. Europe 3.2.2.1. Europe Veterinary Drugs Market Drivers 3.2.2.2. Europe Veterinary Drugs Market Restraints 3.2.2.3. Europe Veterinary Drugs Market Opportunities 3.2.2.4. Europe Veterinary Drugs Market Challenges 3.2.3. Asia Pacific 3.2.3.1. Asia Pacific Veterinary Drugs Market Drivers 3.2.3.2. Asia Pacific Veterinary Drugs Market Restraints 3.2.3.3. Asia Pacific Veterinary Drugs Market Opportunities 3.2.3.4. Asia Pacific Veterinary Drugs Market Challenges 3.2.4. Middle East and Africa 3.2.4.1. Middle East and Africa Veterinary Drugs Market Drivers 3.2.4.2. Middle East and Africa Veterinary Drugs Market Restraints 3.2.4.3. Middle East and Africa Veterinary Drugs Market Opportunities 3.2.4.4. Middle East and Africa Veterinary Drugs Market Challenges 3.2.5. South America 3.2.5.1. South America Veterinary Drugs Market Drivers 3.2.5.2. South America Veterinary Drugs Market Restraints 3.2.5.3. South America Veterinary Drugs Market Opportunities 3.2.5.4. South America Veterinary Drugs Market Challenges 3.3. PORTER's Five Forces Analysis 3.4. PESTLE Analysis 3.5. Technology Roadmap 3.6. Regulatory Landscape by Region 3.6.1. North America 3.6.2. Europe 3.6.3. Asia Pacific 3.6.4. Middle East and Africa 3.6.5. South America 3.7. Key Opinion Leader Analysis For Veterinary Drugs Industry 3.8. Analysis of Government Schemes and Initiatives For Veterinary Drugs Industry 3.9. Veterinary Drugs Market Trade Analysis 3.10. The Global Pandemic Impact on Veterinary Drugs Market 4. Veterinary Drugs Market: Global Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 4.1. Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 4.1.1. Anti-infectives 4.1.2. Anti-inflammatory 4.1.3. Parasiticides 4.1.4. Others 4.2. Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 4.2.1. Companion 4.2.2. Livestock 4.2.3. Others 4.3. Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 4.3.1. Oral 4.3.2. Injectable 4.3.3. Topical 4.3.4. Others 4.4. Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 4.4.1. Veterinary Clinics and Hospitals 4.4.2. Retail Pharmacies and Veterinary Pharmacies 4.4.3. E-commerce Platforms 4.4.4. Others 4.5. Veterinary Drugs Market Size and Forecast, by Region (2025-2034) 4.5.1. North America 4.5.2. Europe 4.5.3. Asia Pacific 4.5.4. Middle East and Africa 4.5.5. South America 5. North America Veterinary Drugs Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 5.1. North America Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 5.1.1. Anti-infectives 5.1.2. Anti-inflammatory 5.1.3. Parasiticides 5.1.4. Others 5.2. North America Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 5.2.1. Companion 5.2.2. Livestock 5.2.3. Others 5.3. North America Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 5.3.1. Oral 5.3.2. Injectable 5.3.3. Topical 5.3.4. Others 5.4. North America Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 5.4.1. Veterinary Clinics and Hospitals 5.4.2. Retail Pharmacies and Veterinary Pharmacies 5.4.3. E-commerce Platforms 5.4.4. Others 5.5. North America Veterinary Drugs Market Size and Forecast, by Country (2025-2034) 5.5.1. United States 5.5.1.1. United States Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 5.5.1.1.1. Anti-infectives 5.5.1.1.2. Anti-inflammatory 5.5.1.1.3. Parasiticides 5.5.1.1.4. Others 5.5.1.2. United States Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 5.5.1.2.1. Companion 5.5.1.2.2. Livestock 5.5.1.2.3. Others 5.5.1.3. United States Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 5.5.1.3.1. Oral 5.5.1.3.2. Injectable 5.5.1.3.3. Topical 5.5.1.3.4. Others 5.5.1.4. United States Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 5.5.1.4.1. Veterinary Clinics and Hospitals 5.5.1.4.2. Retail Pharmacies and Veterinary Pharmacies 5.5.1.4.3. E-commerce Platforms 5.5.1.4.4. Others 5.5.2. Canada 5.5.2.1. Canada Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 5.5.2.1.1. Anti-infectives 5.5.2.1.2. Anti-inflammatory 5.5.2.1.3. Parasiticides 5.5.2.1.4. Others 5.5.2.2. Canada Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 5.5.2.2.1. Companion 5.5.2.2.2. Livestock 5.5.2.2.3. Others 5.5.2.3. Canada Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 5.5.2.3.1. Oral 5.5.2.3.2. Injectable 5.5.2.3.3. Topical 5.5.2.3.4. Others 5.5.2.4. Canada Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 5.5.2.4.1. Veterinary Clinics and Hospitals 5.5.2.4.2. Retail Pharmacies and Veterinary Pharmacies 5.5.2.4.3. E-commerce Platforms 5.5.2.4.4. Others 5.5.3. Mexico 5.5.3.1. Mexico Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 5.5.3.1.1. Anti-infectives 5.5.3.1.2. Anti-inflammatory 5.5.3.1.3. Parasiticides 5.5.3.1.4. Others 5.5.3.2. Mexico Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 5.5.3.2.1. Companion 5.5.3.2.2. Livestock 5.5.3.2.3. Others 5.5.3.3. Mexico Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 5.5.3.3.1. Oral 5.5.3.3.2. Injectable 5.5.3.3.3. Topical 5.5.3.3.4. Others 5.5.3.4. Mexico Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 5.5.3.4.1. Veterinary Clinics and Hospitals 5.5.3.4.2. Retail Pharmacies and Veterinary Pharmacies 5.5.3.4.3. E-commerce Platforms 5.5.3.4.4. Others 6. Europe Veterinary Drugs Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 6.1. Europe Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.2. Europe Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.3. Europe Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.4. Europe Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5. Europe Veterinary Drugs Market Size and Forecast, by Country (2025-2034) 6.5.1. United Kingdom 6.5.1.1. United Kingdom Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.1.2. United Kingdom Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.1.3. United Kingdom Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.1.4. United Kingdom Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.2. France 6.5.2.1. France Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.2.2. France Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.2.3. France Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.2.4. France Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.3. Germany 6.5.3.1. Germany Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.3.2. Germany Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.3.3. Germany Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.3.4. Germany Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.4. Italy 6.5.4.1. Italy Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.4.2. Italy Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.4.3. Italy Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.4.4. Italy Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.5. Spain 6.5.5.1. Spain Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.5.2. Spain Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.5.3. Spain Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.5.4. Spain Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.6. Sweden 6.5.6.1. Sweden Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.6.2. Sweden Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.6.3. Sweden Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.6.4. Sweden Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.7. Austria 6.5.7.1. Austria Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.7.2. Austria Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.7.3. Austria Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.7.4. Austria Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 6.5.8. Rest of Europe 6.5.8.1. Rest of Europe Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 6.5.8.2. Rest of Europe Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 6.5.8.3. Rest of Europe Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 6.5.8.4. Rest of Europe Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7. Asia Pacific Veterinary Drugs Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 7.1. Asia Pacific Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.2. Asia Pacific Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.3. Asia Pacific Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.4. Asia Pacific Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5. Asia Pacific Veterinary Drugs Market Size and Forecast, by Country (2025-2034) 7.5.1. China 7.5.1.1. China Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.1.2. China Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.1.3. China Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.1.4. China Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.2. S Korea 7.5.2.1. S Korea Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.2.2. S Korea Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.2.3. S Korea Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.2.4. S Korea Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.3. Japan 7.5.3.1. Japan Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.3.2. Japan Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.3.3. Japan Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.3.4. Japan Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.4. India 7.5.4.1. India Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.4.2. India Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.4.3. India Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.4.4. India Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.5. Australia 7.5.5.1. Australia Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.5.2. Australia Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.5.3. Australia Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.5.4. Australia Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.6. Indonesia 7.5.6.1. Indonesia Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.6.2. Indonesia Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.6.3. Indonesia Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.6.4. Indonesia Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.7. Malaysia 7.5.7.1. Malaysia Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.7.2. Malaysia Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.7.3. Malaysia Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.7.4. Malaysia Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.8. Vietnam 7.5.8.1. Vietnam Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.8.2. Vietnam Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.8.3. Vietnam Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.8.4. Vietnam Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.9. Taiwan 7.5.9.1. Taiwan Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.9.2. Taiwan Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.9.3. Taiwan Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.9.4. Taiwan Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 7.5.10. Rest of Asia Pacific 7.5.10.1. Rest of Asia Pacific Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 7.5.10.2. Rest of Asia Pacific Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 7.5.10.3. Rest of Asia Pacific Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 7.5.10.4. Rest of Asia Pacific Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 8. Middle East and Africa Veterinary Drugs Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 8.1. Middle East and Africa Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 8.2. Middle East and Africa Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 8.3. Middle East and Africa Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 8.4. Middle East and Africa Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 8.5. Middle East and Africa Veterinary Drugs Market Size and Forecast, by Country (2025-2034) 8.5.1. South Africa 8.5.1.1. South Africa Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 8.5.1.2. South Africa Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 8.5.1.3. South Africa Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 8.5.1.4. South Africa Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 8.5.2. GCC 8.5.2.1. GCC Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 8.5.2.2. GCC Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 8.5.2.3. GCC Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 8.5.2.4. GCC Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 8.5.3. Nigeria 8.5.3.1. Nigeria Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 8.5.3.2. Nigeria Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 8.5.3.3. Nigeria Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 8.5.3.4. Nigeria Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 8.5.4. Rest of ME&A 8.5.4.1. Rest of ME&A Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 8.5.4.2. Rest of ME&A Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 8.5.4.3. Rest of ME&A Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 8.5.4.4. Rest of ME&A Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 9. South America Veterinary Drugs Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 9.1. South America Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 9.2. South America Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 9.3. South America Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 9.4. South America Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 9.5. South America Veterinary Drugs Market Size and Forecast, by Country (2025-2034) 9.5.1. Brazil 9.5.1.1. Brazil Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 9.5.1.2. Brazil Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 9.5.1.3. Brazil Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 9.5.1.4. Brazil Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 9.5.2. Argentina 9.5.2.1. Argentina Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 9.5.2.2. Argentina Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 9.5.2.3. Argentina Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 9.5.2.4. Argentina Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 9.5.3. Rest Of South America 9.5.3.1. Rest Of South America Veterinary Drugs Market Size and Forecast, by Product (2025-2034) 9.5.3.2. Rest Of South America Veterinary Drugs Market Size and Forecast, by Animal (2025-2034) 9.5.3.3. Rest Of South America Veterinary Drugs Market Size and Forecast, by Route of Administration (2025-2034) 9.5.3.4. Rest Of South America Veterinary Drugs Market Size and Forecast, by Distribution Channel (2025-2034) 10. Company Profile: Key Players 10.1. Zoetis Services LLC 10.1.1. Company Overview 10.1.2. Business Portfolio 10.1.3. Financial Overview 10.1.4. SWOT Analysis 10.1.5. Strategic Analysis 10.1.6. Scale of Operation (small, medium, and large) 10.1.7. Details on Partnership 10.1.8. Regulatory Accreditations and Certifications Received by Them 10.1.9. Awards Received by the Firm 10.1.10. Recent Developments 10.2. Boehringer Ingelheim International GmbH 10.3. Merck & Co., Inc. 10.4. Elanco Animal Health Inc. 10.5. Dechra Pharmaceuticals PLC 10.6. Ceva Santé Animale 10.7. Phibro Animal Health Corporation 10.8. Virbac S.A. 10.9. Bimeda 10.10. Biogénesis Bagó 10.11. Vetoquinol S.A. 10.12. Bayer AG 10.13. Archer Daniels Midland 10.14. Evonik Industries AG 10.15. Veterinary Pharmaceutical Solutions 10.16. Norbrook Laboratories 10.17. Chanelle Pharma 10.18. Hipra 10.19. Nexvet 10.20. Kyoritsu Seiyaku Corporation 10.21. Huvepharma 10.22. Troy Laboratories 10.23. Jurox 10.24. Vivaldis 10.25. VetViva Richter GmbH 10.26. Vetiquinol 10.27. WuXi Biologics. 10.28. Mediwin Laboratories 10.29. Vetnation Pharma 10.30. Vee Remedies 11. Key Findings 12. Industry Recommendations 13. Veterinary Drugs Market: Research Methodology 14. Terms and Glossary

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements