
Global Transmission Fluid Market Size by Type, by Base Oil, by Application, by Sales Channel, by End-User Industry, by Region and Forecast 2034
Overview
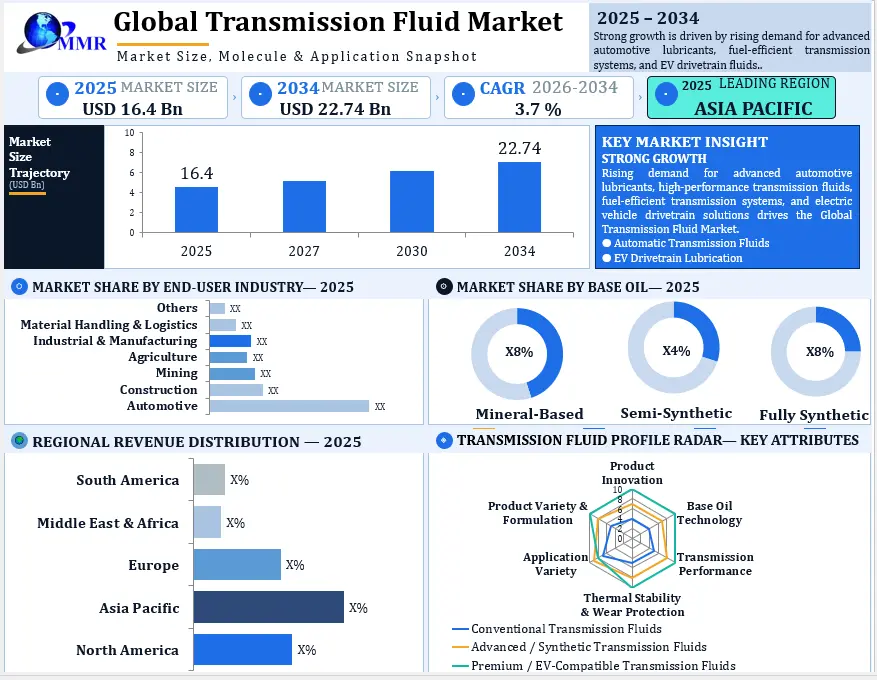
Global Transmission Fluid Market size was valued at USD 16.4 Bn. in 2025 and the total Transmission Fluid revenue is expected to grow by 3.7 % from 2026 to 2034, surged to USD 22.74 Bn.
Global Transmission Fluid Market Overview
The transmission Fluid Market is stated as one of the fluids utilized in vehicles for manual and automatic transmissions during the movement of the engine. Transmission Fluid Market is usually obtainable in red or green color. It is dyed in turn to differentiate it from other fluids and motor oils utilized in vehicles.
The rise in the demand for technologically advanced vehicles with unique drivetrains that deliver comfort of driving is rising the growth of the Transmission Fluid Market. Major factors that increase the growth of the Transmission Fluid Market in the forecast period are the rise in the automotive industry. Also, the technological development in the passenger vehicles sector is further forcing the growth of the market. Transmission Fluid Market provides details of new recent developments, trade regulations, import-export analysis, production analysis, value chain optimization, market share, the impact of domestic and localized market players, analyses opportunities in terms of developing revenue pockets, changes in market regulations, strategic market growth analysis, market size, category market growths, application places and dominance, product approvals, product launches, geographical expansions, technological innovations in the market.
Global Transmission Fluid Market Size, Growth and Share Analysis
To know about the Research Methodology:- Request Free Sample Report
Key Market Highlights – Global Transmission Fluid Market
• The Global Transmission Fluid Market reaches USD 16.4 billion in 2025 and is projected to grow at a CAGR of 3.7% from 2026 to 2034, reaching USD 22.74 billion by 2034.
• Automatic Transmission Fluids hold a leading position in the market, supported by the increasing adoption of automatic transmissions, rising vehicle production, and demand for smooth gear shifting and enhanced transmission protection.
• Synthetic Oil-Based Transmission Fluids gain traction due to their superior thermal stability, oxidation resistance, wear protection, and extended service life compared with conventional mineral oil-based formulations.
• Asia Pacific leads the global market, driven by strong automotive manufacturing, increasing vehicle ownership, expanding commercial vehicle fleets, and growing demand for advanced transmission technologies across China, India, Japan, and South Korea.
• Electric and Hybrid Vehicle Transmission Fluids create new growth opportunities as manufacturers develop specialized formulations that support thermal management, lubrication efficiency, electrical compatibility, and the performance requirements of electrified drivetrains.
Global Transmission Fluid Market Dynamics
Global Transmission Fluid Market Opportunities
Expansion of Electric and Hybrid Vehicle Transmission Fluids: The growing adoption of electric and hybrid vehicles creates opportunities for specialized fluids designed for electric drive units and hybrid transmissions. These formulations address requirements such as thermal management, electrical compatibility, material protection, and lubrication efficiency. Manufacturers develop dedicated fluids to meet the operating requirements of electrified drivetrains, creating opportunities for product innovation and portfolio expansion.
Growth of the Automotive Aftermarket: The large global vehicle population supports demand for transmission fluid replacement, maintenance, and servicing. Vehicles with automatic transmissions require compatible fluids to maintain lubrication, control friction, and protect transmission components throughout their service life. Manufacturers strengthen their aftermarket presence through wider distribution networks, vehicle-specific formulations, and products designed for commercial fleets, independent workshops, and automotive service centers.
Global Transmission Fluid Market Challenges
Increasing Complexity of Modern Transmission Systems: Advanced automatic, dual-clutch, and continuously variable transmissions require fluids with specific viscosity, friction, thermal stability, and material compatibility characteristics. Manufacturers must develop formulations that meet individual automaker specifications while maintaining consistent performance across different temperatures and driving conditions. These requirements increase product development, testing, and validation demands and make formulation consistency an important competitive factor.
Transition Toward Electrified Drivetrains: The expansion of battery-electric vehicles creates challenges for conventional transmission fluid manufacturers because electric drive units require specialized lubrication and thermal management solutions. Conventional formulations do not automatically satisfy the electrical, thermal, and material compatibility requirements of these systems. Manufacturers therefore invest in research, testing, and product development to address evolving drivetrain designs while adapting their portfolios to changing automotive technology.
Global Transmission Fluid Market Segment Analysis
Based on Tansmission Fluid Type, The Global Transmission Fluid Market is segmented by transmission fluid type into Automatic Transmission Fluid (ATF), Manual Transmission Fluid (MTF), Dual-Clutch Transmission Fluid (DCTF), Continuously Variable Transmission Fluid (CVTF), E-Transmission/E-Drive Fluid, and Others. Rising demand for automatic transmission vehicles, fuel-efficient automotive technologies, and advanced automotive lubricants drives market growth. ATF benefits from the increasing adoption of automatic transmissions, while MTF supports lubrication and gear protection in manual vehicles. DCTF and CVTF demand increases with the adoption of dual-clutch and continuously variable transmission systems. Meanwhile, E-Transmission and E-Drive Fluids gain importance with the expansion of electric and hybrid vehicles, creating opportunities for specialized drivetrain lubrication and thermal management solutions.
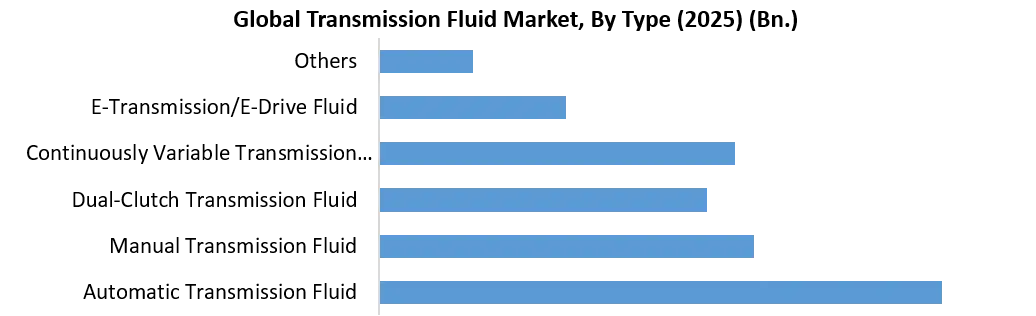
Based on the base oil, The Global Transmission Fluid Market is segmented by base oil into mineral-based, semi-synthetic, and fully synthetic transmission fluids. Mineral-based transmission fluids maintain demand due to their cost-effectiveness and widespread use in conventional vehicles. Semi-synthetic transmission fluids offer a balance between affordability, oxidation resistance, and lubrication performance. Fully synthetic transmission fluids gain traction due to their superior thermal stability, wear protection, and extended service life under demanding operating conditions. Increasing demand for high-performance automotive lubricants, fuel-efficient vehicles, automatic transmission systems, and advanced drivetrain technologies supports segment growth. The expansion of hybrid and electric vehicles also creates opportunities for specialized synthetic transmission and e-drive fluids.
Based on the end-use industry, the off-road vehicles segment dominates the Transmission Fluid Market in the year 2025 and the same during the forecast. The transmission fluids market is segmented into automotive and off-road vehicles. Automotive is further sub-segmented into passenger vehicles and commercial vehicles. The purpose of the fluids used in off-road vehicles, such as construction vehicles and agricultural machinery, is to deliver optimal on-road force by providing wear protection for transmission machinery for longer vehicle life. Asia Pacific is one of the largest regional markets in off-road vehicles application paid to the growth of the construction industry. Additionally, with the increase in infrastructural development across the globe, the demand for these oils in various vehicles is also significantly increasing. Growth of the construction industry in emerging markets of China, India, Brazil, and Mexico remains a key factor driving the demand for off-road vehicles application globally.
Global Transmission Fluid Market Regional Insights
Asia Pacific: Asia Pacific holds the leading position in the global transmission fluid market, supported by extensive automotive manufacturing, rising vehicle ownership, and expanding commercial vehicle fleets. China, India, Japan, and South Korea contribute significantly through passenger vehicle production, automotive component manufacturing, and increasing demand for automatic transmission systems. Strong original equipment manufacturer (OEM) demand and aftermarket maintenance requirements reinforce the region’s market position. Growing adoption of automatic, continuously variable, and hybrid transmission technologies further strengthens demand for advanced transmission fluids.
North America: North America maintains a significant position in the global transmission fluid market, driven by a large vehicle population, widespread automatic transmission adoption, and established automotive maintenance networks. The United States and Canada support demand through passenger vehicles, pickup trucks, commercial fleets, and off-highway equipment. Regular transmission servicing and the preference for high-performance synthetic formulations support aftermarket sales. Increasing demand for fluids that meet specific automaker requirements also encourages product innovation and portfolio expansion.
Europe: Europe represents an important market for transmission fluids, supported by established automotive manufacturing, advanced transmission engineering, and stringent vehicle performance requirements. Germany, France, the United Kingdom, and Italy contribute through passenger vehicle production, commercial transportation, and automotive component manufacturing. Demand for high-quality lubricants with improved thermal stability, oxidation resistance, and extended service life supports the adoption of advanced formulations. The expansion of hybrid vehicles and electrified drivetrains also creates opportunities for specialized transmission and electric-drive fluids.
South America: South America experiences growing demand for transmission fluids as vehicle ownership, commercial transportation, agricultural activities, and industrial operations support lubricant consumption. Brazil and Argentina contribute through automotive manufacturing, agricultural machinery, logistics, and vehicle maintenance. Demand for automatic transmission fluids and replacement lubricants benefits from an expanding vehicle fleet and established aftermarket channels. Greater awareness of preventive maintenance and the availability of vehicle-compatible formulations further support regional market development.
Middle East and Africa: The Middle East and Africa market benefits from demand across commercial transportation, construction, mining, agriculture, and oil and gas operations. Saudi Arabia, the United Arab Emirates, and South Africa contribute through vehicle sales, industrial activity, and equipment maintenance. High operating temperatures and demanding driving conditions increase the importance of thermal stability, oxidation resistance, and wear protection in transmission fluids. Expanding infrastructure projects, growing vehicle populations, and improving lubricant distribution networks support regional market development.
Global Transmission Fluid Market – Competitive Landscape
The Global Transmission Fluid Market features strong competition among integrated energy companies, specialized lubricant manufacturers, and automotive fluid suppliers. Market participants compete through advanced lubricant formulations, original equipment manufacturer (OEM) approvals, product performance, distribution networks, and long-term relationships with automotive manufacturers. Leading companies such as Shell plc, Exxon Mobil Corporation, BP p.l.c., Chevron Corporation, and Total Energies SE leverage established lubricant portfolios and global supply capabilities to serve automotive and industrial customers.
Product innovation remains a key competitive differentiator, particularly as modern transmissions require fluids with precise viscosity, friction control, oxidation resistance, and thermal stability. Manufacturers expand synthetic automatic transmission fluids, continuously variable transmission fluids, and dual-clutch transmission fluids to address different drivetrain requirements. The growing electrification of vehicles also encourages lubricant suppliers to develop specialized fluids for electric drive units and hybrid transmissions, creating opportunities to differentiate through thermal management and electrical compatibility.
OEM approvals and technical compatibility strengthen competitive positioning. Transmission fluid manufacturers formulate products to meet specific automaker performance standards and transmission design requirements. These approvals help suppliers establish long-term OEM relationships, support factory-fill contracts, and improve product credibility in the aftermarket. Companies also compete by expanding multi-vehicle-compatible formulations while maintaining compliance with manufacturer specifications.
Distribution reach and aftermarket availability influence purchasing decisions. Established lubricant brands benefit from relationships with distributors, workshops, retailers, fleet operators, and automotive service centers. Manufacturers strengthen their market presence through wider product availability, vehicle-specific recommendations, and premium formulations for passenger vehicles and commercial fleets. Consistent product quality and technical support further contribute to customer retention.
The shift toward specialized and premium transmission fluids creates opportunities for technology-led competition. Companies invest in synthetic base oils, advanced additive packages, and application-specific formulations to address demanding operating conditions and evolving transmission technologies. Suppliers that combine formulation expertise, reliable raw material sourcing, OEM approvals, and broad distribution capabilities are well positioned to strengthen their competitive presence in the global transmission fluid market.
Key Competitive Factors
| Competitive Factor | Strategic Importance |
|---|---|
| Product Innovation | Develops advanced formulations for automatic, CVT, DCT, hybrid, and electric drivetrains. |
| OEM Approvals | Supports factory-fill contracts and builds trust with vehicle manufacturers. |
| Synthetic Fluid Technology | Improves thermal stability, oxidation resistance, and lubrication performance. |
| Distribution Network | Expands product availability across aftermarket and commercial channels. |
| Product Compatibility | Meets the technical requirements of different transmission systems. |
| Supply Chain Strength | Supports consistent raw material sourcing and reliable product delivery. |
| Brand Reputation | Influences customer confidence and repeat purchases. |
| Electrification Readiness | Creates opportunities in specialized hybrid and electric drivetrain fluids. |
Overall, competition centers on technical performance, OEM qualification, synthetic formulation capabilities, and market reach. Suppliers that align product development with advanced transmission systems and electrified drivetrains can strengthen their market position while serving both OEM and aftermarket customers.
Global Transmission Fluid Market – Recent Developments
| Date | Company | Development | Impact |
|---|---|---|---|
| January 19, 2026 | Eaton | Introduces Eaton Ever Tough fully synthetic transmission fluid for manual and automated manual transmissions, targeting aging commercial vehicle fleets and aftermarket applications. |
Expands aftermarket product offerings and provides additional lubrication options for fleets seeking durability and cost-effective maintenance. |
| February 19, 2026 | ZF | Expands its transmission oil change kit portfolio across combustion-engine, electric, and hybrid vehicle applications, including vehicle-specific maintenance solutions. |
Strengthens aftermarket servicing capabilities and supports transmission maintenance across a wider range of drivetrain technologies. |
| April 2, 2026 | Hot Shot’s Secret | Launches Green Diamond ULV automatic transmission fluid for Ford and GM 10-speed transmissions and other applications requiring ultra-low-viscosity formulations. |
Expands specialized fluid availability for modern transmissions and supports thermal stability, wear protection, and efficient fluid flow. |
| May 17, 2026 | FUCHS | Introduces TITAN DCTF FLEX, a premium multi-vehicle dual-clutch transmission fluid incorporating Advanced Circular Technology. |
Strengthens the specialized dual-clutch fluid portfolio and introduces a circular-technology approach to transmission lubricant development. |
| July 1, 2026 | FUCHS | Introduces BluEV DHTF 3932, a dedicated hybrid transmission fluid developed for modern hybrid platforms from FAW and SGMW. |
Expands application-specific fluid solutions for hybrid dual-clutch transmissions and supports changing drivetrain lubrication requirements. |
| July 24, 2026 | Great Wall Lubricants | Launches three passenger vehicle transmission fluids: ATF X+ for premium automatic transmissions, ATF S for mainstream automatic transmissions, and ETF X+ for new-energy vehicle gearboxes. |
Broadens its transmission fluid portfolio across conventional and electrified vehicles and strengthens its presence in China's automotive aftermarket. |
| August 3, 2026 | FUCHS | Introduces BluEV DHTF 5105, a premium dedicated hybrid transmission fluid designed for modern hybrid platforms, including applications in CHERY vehicles. |
Strengthens specialized hybrid transmission fluid offerings and addresses requirements for thermal stability, controlled friction, and material compatibility. |
Global Transmission Fluid Market Scope: Inquire before buying
| Transmission Fluids Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 16.4 Billion |
| Forecast Period 2026-2034 CAGR: | 3.7% | Market Size in 2034: | USD 22.74 Billion |
| Segments Covered: | by Transmission Fluid Type | Automatic Transmission Fluid (ATF) Manual Transmission Fluid (MTF) Dual-Clutch Transmission Fluid (DCTF) Continuously Variable Transmission Fluid (CVTF) E-Transmission/E-Drive Fluid Others |
|
| by Base Oil | Mineral-Based Semi-Synthetic Fully Synthetic |
||
| by Fill Type | Factory Fill/OEM Service Fill/Aftermarket |
||
| by Vehicle/Equipment Type | On-Highway Vehicles Passenger Cars Light Commercial Vehicles Medium & Heavy Commercial Vehicles Others Off-Highway Equipment Construction Equipment Mining Equipment Agricultural Equipment Material Handling Equipment Others Industrial Equipment |
||
| by End-User Industry | Automotive Construction Mining Agriculture Industrial & Manufacturing Material Handling & Logistics Others |
||
Global Transmission Fluid Market by Region
North America (United States, Canada, and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, and the Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria, and the Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Key Players/Competitors Profiles Covered in the Transmission Fluid Market Report in a Strategic Perspective
North America
1. Exxon Mobil Corporation
2. Chevron Corporation
3. Valvoline Inc.
4. Phillips 66
5. Petro-Canada Lubricants Inc.
6. Amalie Oil Co.
7. CRP Industries Inc.
8. Warren Distribution Inc.
9. Lucas Oil Products, Inc.
10. AMSOIL Inc.
Others
Europe
1. Shell plc
2. BP p.l.c.
3. TotalEnergies SE
4. FUCHS SE
5. Motul
6. Eni S.p.A
7. Repsol S.A.
8. OMV Group
9. LIQUI MOLY GmbH
10. Klüber Lubrication
11. LUKOIL
12. Gazpromneft-SM LLC
Others
Asia-Pacific
1. ENEOS Holdings, Inc.
2. Idemitsu Kosan Co., Ltd.
3. Cosmo Oil Lubricants Co., Ltd.
4. JX Nippon Oil & Energy
5. SK Lubricants
6. GS Caltex (Kixx)
7. Petroliam Nasional Berhad (PETRONAS)
8. Sinopec Lubricant Company
9. PetroChina (CNPC)
10. Indian Oil Corporation Limited
11. Hindustan Petroleum Corp. Ltd. (HPCL)
12. Bharat Petroleum Corp. Ltd. (BPCL)
13. Gulf Oil Lubricants India Ltd.
14. Savita Oil Technologies Ltd.
15. Balmer Lawrie & Co. Ltd.
Others
Middle East & Africa
1. ADNOC Distribution
2. Kemipex
3. Petrolube (Mobil JV)
4. Sasol Limited
5. ryx Energies
6. Total South Africa
7. Bahri Lubricants
8. ENOC Company
Others
South America
1. Petróleo Brasileiro S.A. (Petrobras)
2. YPF S.A.
3. Ipiranga Produtos de Petróleo
4. Raízen
5. Puma Energy
6. Terpel
Others
Frequently Asked Questions:
1] What segments are covered in the Transmission Fluid Market report?
Ans. The segments covered in the market report are based on Type, Base Oil, Sales Channel, Application, End-user Industry, and Region.
2] Which region is expected to hold the highest share in the Transmission Fluid Market?
Ans. The Asia Pacific region is expected to hold the highest share of the market over the forecast period.
3] What is the market size of the market by 2034?
Ans. The market size of the market by 2034 is expected to reach US$ 22.74 Bn.
4] What was the market size of the Transmission Fluid Market in 2025?
Ans. The market size of the market in 2025 was valued at US$ 16.4 Bn.