Polyurethane Market– Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

4.57%
CAGR (2026-2034)
82.17 USD Bn.
Forecast Market Size
324
Report Pages
161
Market Tables

Overview

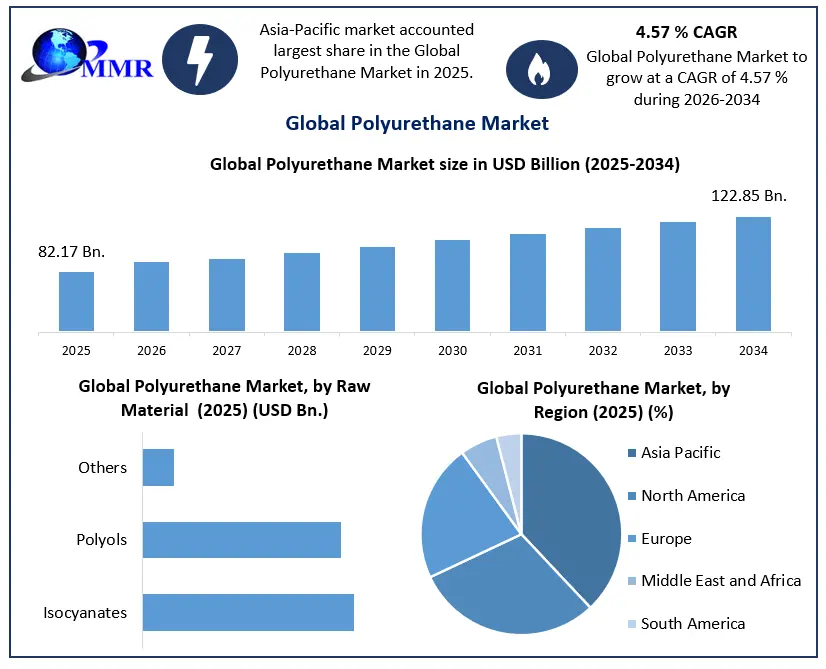
The Polyurethane Market size was valued at USD 82.17 Billion in 2025 and the total Polyurethane revenue is expected to grow at a CAGR of 4.57% from 2026 to 2034, reaching USD 122.85 Billion.

Polyurethane Market Overview:

Polyurethanes are a class of materials valued by consumers for their high performance and durability. Polyurethane foam used in furniture, insulation, and bedding is the most easily recognizable product. Polyurethane materials are also found in paints and coatings, adhesives, sealants, elastomer fibers, and rubberized products, such as conveyor belt rollers. In the construction industry, polyurethane is widely used for insulation purposes, contributing to energy efficiency in buildings. The demand for polyurethane-based components in vehicle manufacturing is rapidly increasing. Due to utilization in the manufacturing of various components including seats, dashboards, and bumpers, owing to its lightweight and impact-resistant nature. Especially as the market shifts towards New Energy Vehicles (NEVs).
Polyurethane Market Growth Outlook

To know about the Research Methodology :- Request Free Sample Report

Also, the increasing demand for eco-friendly materials. This means more products are made from renewable sources like soybeans, reducing reliance on fossil fuels. Also, new recycling methods are emerging to reuse polyurethane waste, reflecting a growing focus on sustainability in manufacturing these factors is significantly responsible for the growth of the Polyurethane Market.

Polyurethane Market Dynamics:

Driver

Rising Building and Construction drives the Polyurethane Market

The surge in construction activities is increasing the demand for energy-efficient buildings, thus boosting the utilization of polyurethane insulation materials This Factor Significantly drives the growth Polyurethane Market. This trend reflects a growing awareness among builders, developers, and consumers regarding the importance of energy conservation in structures. Polyurethane insulation materials enhance energy efficiency by reducing heat transfer, hence lowering the need for constant heating and cooling. Also, the escalating need for durable sealants and adhesives in construction applications is driving the adoption of polyurethane-based solutions, thanks to their strong bonding and sealing properties. Urbanization further intensifies construction endeavors, particularly in densely populated urban areas, where polyurethane finds extensive application due to its efficiency and effectiveness.

The United States leads in polyurethane consumption for construction purposes, with building and construction accounting for a substantial share of this usage. Rigid polyurethane foam stands out as a favored choice for wall and roof insulation, insulated panels, and gap fillers, offering numerous benefits including energy efficiency, high performance, and environmental friendliness. Its exceptional insulating properties allow for thinner walls and lower-profile roofs, maximizing space utilization and reducing operating costs. Also, polyurethane-based coatings, adhesives, and sealants are used to enhance structural integrity, weatherproofing, and overall longevity in diverse construction applications. This symbiotic relationship between rising construction activities and the Polyurethane Market underscores its significance in shaping the modern built environment.

Growing demand for environmentally friendly products boosts Polyurethane Market Growth

Creating bio-based polyurethane and environmentally friendly formulations corresponds to customer expectations and regulatory changes. Green polyurethane product development increases market share by attracting eco-aware organizations and customers. As environmental awareness continues to rise, consumers become more conscious of the impact of their purchases, which significantly boosts the Polyurethane Market growth. This opportunity is expected to drive an increased demand for green polyurethane products. It increases market size as businesses reach out to a new consumer base who are seeking environmentally friendly and sustainable products. Advancements in technology and material science are expected to result in the development of more efficient and cost-effective processes for producing bio-based polyurethane, making it increasingly attractive for manufacturers. Countries such as Germany, China, Netherlands, and Japan have a strong focus on research and developments in bio-based materials, and growing their emphasis on sustainability and their position as major manufacturing hubs drives the research and development initiatives in bio-based polyurethane technologies.

Restrain

Exposure Risks and Environmental Concerns limit the growth of the Polyurethane Market

The Exposure risks and environmental concerns pose significant challenges to the growth of the polyurethane market. PU production involves potentially hazardous substances such as isocyanates, which adversely affect respiratory health and soil quality. Strict regulations in many countries govern the production of PUs due to their environmental impact, including soil and aquatic contamination. Despite PU's beneficial properties, such as improving strength and erosion resistance, its use raises concerns about pollution, particularly from microplastics. Environmental implications arise from inadequate measures to control contamination during PU application, posing risks to ecosystems.

Also, the transportation of PU sealants in soil, facilitated by moisture, exacerbates environmental exposure. Studies indicate that while PU enhances soil mechanical properties, its usage must be carefully regulated to minimize adverse environmental effects. Therefore, exposure risks and environmental concerns surrounding PU production and application inhibit the Polyurethane market growth. Addressing these challenges requires implementing stricter regulations, developing eco-friendly alternatives, and adopting sustainable practices to mitigate environmental impact while harnessing the benefits of PU technology.

Opportunity

Rising Demand from Automotive Industry Creates Lucrative Growth Opportunities for the Polyurethane Market Growth

The automotive industry sees huge potential in the polyurethane market due to its pursuit of lighter, more efficient, and comfortable vehicles. Polyurethane is widely used in various car components, from seating and interior trim to insulation and structural parts, showcasing its versatility. Flexible polyurethane foams, valued for their lightweight, resilience, and sound absorption, are integral to automobile interiors, including seating, headrests, and HVAC systems. Rigid polyurethane foam serves as insulation in refrigerated trucks and some automotive panels, enhancing energy efficiency and sound absorption. Polyurethane coatings provide durability, scratch resistance, and corrosion protection to vehicle exteriors, while adhesives ensure strong bonds for exterior and interior components. Polyurethane elastomers are used in seals, gaskets, and shock absorbers, offering tire puncture protection and enhancing safety.

Thermoplastic polyurethane materials find application in various automobile parts, including exterior body parts and brake systems. Reaction injection molding (RIM) produces lightweight polyurethane parts for vehicle fenders, bumpers, and spoilers, improving shock absorption without adding bulk. This shift from metal alloys to polyurethane versions reduces susceptibility to damage and corrosion.
Polyurethane's lightweight nature, coupled with its mechanical properties, addresses automakers' need for fuel efficiency without compromising safety. Its design flexibility allows for complex shapes and contours, meeting both aesthetic and functional requirements. Additionally, polyurethane's acoustic and thermal insulation properties contribute to a quieter and more comfortable cabin environment, enhancing the overall driving experience. As the automotive industry explores new technologies like electric and autonomous vehicles, specialized polyurethane solutions continue driving further innovation and Polyurethane Market growth.

Polyurethane Market Segment Analysis

Based On Raw Material : The polyurethane market is primarily divided into isocyanates, polyols, and other raw materials. Isocyanates serve as essential chemical building blocks in polyurethane production, with methylene diphenyl diisocyanate (MDI) and toluene diisocyanate (TDI) representing major commercial categories. MDI is widely used in rigid foams, insulation materials, elastomers, and specialty applications, while TDI plays an important role in flexible foam manufacturing for furniture, mattresses, and automotive seating. Polyols form the other major raw material category and include polyether polyols, polyester polyols, and bio-based polyols. Polyether polyols are commonly used in flexible and rigid foams, while polyester polyols support coatings, adhesives, sealants, and elastomer applications. Bio-based polyols gain attention as manufacturers explore renewable feedstocks and more sustainable polyurethane formulations.

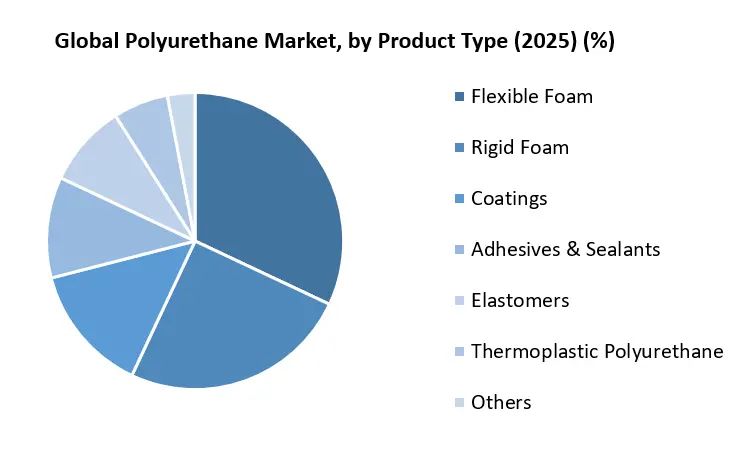
Based On Product: Flexible foam represents a major polyurethane product category due to its extensive use in furniture, mattresses, automotive seating, cushioning, and bedding products. Rigid foam is widely used in building insulation, refrigeration equipment, cold storage, and energy-efficient construction systems. Polyurethane coatings provide surface protection, durability, abrasion resistance, and chemical resistance across automotive, industrial, and construction applications. Adhesives and sealants support bonding and sealing requirements in automotive assembly, footwear, packaging, construction, and furniture manufacturing. Elastomers offer flexibility, strength, impact resistance, and wear performance in industrial components and automotive parts. Thermoplastic polyurethane (TPU) is used in footwear, cables, electronics, automotive components, and consumer products because of its flexibility and processing versatility. Other products include specialty polyurethane materials designed for specific industrial and commercial applications.
Polyurethane Market by Product Type

Polyurethane Market Regional Analysis

Asia Pacific region dominated the Polyurethane Market in the year 2025. With growing construction activities and rapid urbanization in China and India, polyurethane usage is increasing. The region's booming construction industry, particularly in countries like China and India, has been a major driver of polyurethane demand. Polyurethane is extensively used in construction for insulation, sealants, adhesives, and coatings, among other applications. With rapid urbanization and infrastructure development, the demand for polyurethane-based construction materials has been consistently high.With an expected expenditure of nearly USD 13 trillion on buildings by 2032, the demand for polyurethane, a versatile material widely used in construction, is projected to increase.

The region's burgeoning middle-class population, coupled with increasing disposable incomes, has led to a surge in demand for consumer goods. Polyurethane is widely used in the production of furniture, footwear, mattresses, and other consumer products due to its versatility, durability, and comfort properties. The robust furniture markets in countries such as China and India have significantly contributed to the dominance of the Asia-Pacific region in the polyurethane market.

Polyurethane Market Competitive Analysis

The polyurethane market is witnessing intense competition as key players adopt various strategies to maintain and increase their market share. For example, Pearl Polyurethane Systems' expansion into India underscores the importance of geographical expansion to better serve clients in emerging markets. Recital NV/SA's launch of polyurethane insulation boards with bio-circular raw materials reflects a commitment to sustainability, targeting environmentally-conscious consumers. DIC Corporation's introduction of waterborne polyurethane resins highlights a shift towards eco-friendly alternatives, aligning with growing environmental concerns. Covestro AG's inauguration of a new production line and launch of the Desmopan UP thermoplastic polyurethane series signifies a focus on innovation to provide specific industry needs, such as providing paint protection film in the wind and automotive sectors. These moves indicate a dynamic market landscape driven by a combination of technological innovation, sustainability efforts, and strategic expansion initiatives.

Polyurethane market Scope: Inquire before buying

Polyurethane Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 82.17 Billion
Forecast Period 2026-2034 CAGR: 4.57% Market Size in 2034: USD 122.85 Billion
Segments Covered: by Raw Material Isocyanates
Methylene Diphenyl Diisocyanate (MDI)
Toluene Diisocyanate (TDI)
Polyols
Polyether Polyols
Polyester Polyols
Bio-based Polyols
Others
by Product Flexible Foam
Rigid Foam
Coatings
Adhesives & Sealants
Elastomers
Thermoplastic Polyurethane (TPU)
Others
by Processing Method Flexible Foam
Rigid Foam
Coatings
Adhesives & Sealants
Elastomers
Thermoplastic Polyurethane (TPU)
Others
Spray Polyurethane Foam (SPF)
Synthetic Leather
Polyurethane Resins
by Distribution Channel Direct Sales
Distributors
Retailers
by Technology HFC-Blown
Hydrocarbon-Blown
Water-Blown
Bio-Based Polyurethane
Others
by End-use Industry Building & Construction
Insulation Panels
Roofing
Wall Systems
Flooring
Sealants
Furniture & Bedding
Mattresses
Upholstery
Cushions
Office Furniture
Automotive & Transportation
Seating
Interior Components
NVH Components
Exterior Components
EV Battery Insulation
Electronics & Appliances
Refrigerators
Freezers
HVAC
Consumer Electronics
Footwear
Soles
Safety Footwear
Sports Footwear
Packaging
Protective Packaging
Cold Chain Packaging
Consumer Goods
Others

Global Polyurethane Market, by Region

Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
North America (United States, Canada and Mexico)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Key Players / Competitores Proflies Coverd Polyurethane Market Report in Strategic Perspective

North America
1. Dow Inc.
2. Huntsman Corporation
3. The Lubrizol Corporation
4. Carpenter Co.
5. RTP Company
6. Rogers Corporation
7. UFP Technologies, Inc.
8. FXI Holdings, Inc.
9. DuPont de Nemours, Inc.
10. Woodbridge Foam Corporation
11. Others

Europe
1. BASF SE
2. Covestro AG
3. LANXESS AG
4. Recticel NV/SA
5. Trelleborg AB
6. RAMPF Holding GmbH & Co. KG
7. FoamPartner Group
8. Eurofoam Group
9. Zotefoams plc
10. Evonik Industries AG
11. Perstorp Holding AB
12. Sika AG
13. Henkel AG & Co. KGaA
14. COIM Group
15. SAPICI S.p.A.
16. PCC Group
17. Purinova Sp. z o.o.
18. Others

Asia-Pacific
1. Wanhua Chemical Group Co., Ltd.
2. Mitsui Chemicals, Inc.
3. Tosoh Corporation
4. DIC Corporation
5. Sekisui Chemical Co., Ltd.
6. INOAC Corporation
7. Mitsubishi Chemical Group Corporation
8. UBE Corporation
9. Kumho Mitsui Chemicals Inc.
10. Nippon Polyurethane Industry Co., Ltd.
11. Manali Petrochemicals Limited
12. Sheela Foam Limited
13. Others

Rest of World
1. SABIC
2. Sadara Chemical Company
3. Pearl Polyurethane Systems
4. Emirates Chemicals LLC
5. Era Polymers
6. Purcom Química
7. Flexível Indústria e Comércio
8. Tecnofibras
9. Others

Frequently Asked Questions

1. What is the expected CAGR of the global polyurethane market?
Ans: The global polyurethane market is projected to grow at a CAGR of 4.57% during 2026–2034.

2. Which region dominates the global polyurethane market?
Ans: Asia Pacific dominates the global polyurethane market in 2025, supported by rapid urbanization, construction activities, infrastructure development, and expanding furniture and automotive manufacturing in China and India.

3. What are the key applications of polyurethane?
Ans: Polyurethane is widely used in building insulation, furniture, mattresses, automotive seating, vehicle interiors, footwear, electronics, appliances, packaging, coatings, and industrial components.

4. How is the automotive industry creating opportunities for polyurethane manufacturers?
Ans: Growing demand for lightweight, durable, and energy-efficient vehicles increases polyurethane use in seating, interior components, insulation, coatings, adhesives, bumpers, and thermoplastic polyurethane parts.

5. Who are the key players in the global polyurethane market?
Ans: Major companies include BASF SE, Covestro AG, Dow Inc., Huntsman Corporation, Wanhua Chemical Group, Mitsui Chemicals, DIC Corporation, LANXESS AG, Lubrizol Corporation, and Recticel NV/SA.

Table of Contents

1. POLYURETHANE MARKET INTRODUCTION 1.1 Executive Market Landscape and Industry Overview 1.1.1 Polyurethane Market size (Value USD Mn & Volume KT) estimation and growth outlook (2025–2034) 1.1.2 Comprehensive definition of the Polyurethane industry ecosystem 1.1.3 Scope boundaries covering production technologies, infrastructure, and end-use applications 1.1.4 Competitive Landscape Overview: Brands, Participants, Regional Specialists, and New Entrants in the Global Polyurethane Market 1.2 Polyurethane Market Dynamics 1.2.1 Polyurethane Market Trends 1.2.2 Polyurethane Market Drivers 1.2.3 Restraints 1.2.4 Opportunities 1.2.5 Challenges 1.2.6 PORTER’s Five Forces Analysis 1.2.7 Supplier power 1.2.8 Buyer power 1.2.9 Threat of substitutes 1.2.10 Threat of new entrants 1.2.11 Competitive rivalry 1.2.12 PESTLE Analysis 1.3 Polyurethane System House Landscape Assessment 1.3.1 Global & Regional System House Market Structure 1.3.2 Leading Independent and Captive System House Benchmarking 1.3.3 Product Portfolio & Customized Formulation Analysis 1.3.4 Industry-Wise Customer Base Assessment 1.3.5 Raw Material Sourcing & Supplier Network Mapping 1.3.6 Manufacturing Footprint & Production Capacity Analysis 1.3.7 Distribution & Technical Service Network Assessment 1.3.8 Strategic Partnerships, Acquisitions & Expansion Activities 1.3.9 Innovation, Sustainability & Bio-Based Polyurethane Initiatives 1.4 Regulatory Framework and Compliance Requirements Overview 1.4.1 Chemical Registration & Compliance Requirements (REACH, TSCA, UK REACH, etc.) 1.4.2 Isocyanate Handling, Worker Safety & Occupational Exposure Regulations 1.4.3 Environmental, Health & Safety (EHS) Compliance Standards 1.4.4 VOC Emission & Product Stewardship Requirements 1.4.5 Building, Construction & Fire Safety Standards for Polyurethane Products 1.4.6 Automotive, Electronics & Consumer Product Regulatory Requirements 1.4.7 Sustainability, Circular Economy & Extended Producer Responsibility (EPR) Frameworks 1.4.8 Bio-Based, Recycled & Low-Carbon Polyurethane Certification Standards 1.4.9 Future Regulatory Developments & Compliance Impact Assessment 1.5 Supply Chain and Value Chain Analysis Overview 1.5.1 Polyurethane Industry Value Chain Structure 1.5.2 Raw Material Supply Ecosystem (MDI, TDI, Polyols & Additives) 1.5.3 Supplier Landscape and Procurement Network Analysis 1.5.4 Manufacturing Process and Production Flow Assessment 1.5.5 Polyurethane System Houses and Formulation Network Analysis 1.5.6 Distribution Channel and Logistics Network Assessment 1.5.7 End-User Supply Chain Mapping by Industry 1.5.8 Import-Export Flow and Trade Route Analysis 1.5.9 Supply Chain Risks, Bottlenecks and Resilience Assessment 1.5.10 Future Supply Chain Transformation and Strategic Opportunities 1.6 Pricing Analysis and Cost Structure Evaluation (2025) 1.6.1 Global Polyurethane Price Trend Analysis 1.6.2 MDI, TDI & Polyol Price Benchmarking 1.6.3 Raw Material Cost Contribution Analysis 1.6.4 Manufacturing Cost Structure Assessment 1.6.5 Energy, Utility & Labor Cost Impact Analysis 1.6.6 Regional Price Variation and Competitiveness Assessment 1.6.7 Distribution, Logistics & Warehousing Cost Evaluation 1.6.8 Future Pricing Outlook and Cost Optimization Opportunities 1.7 Investment and Funding Trends in Polyurethane Sector 1.7.1 Global Investment Landscape and Capital Flow Analysis 1.7.2 Capacity Expansion and Manufacturing Facility Investments 1.7.3 MDI, TDI & Polyol Production Investment Trends 1.7.4 Private Equity, Venture Capital and Strategic Funding Activities 1.7.5 Mergers, Acquisitions and Joint Venture Analysis 1.7.6 Investments in Specialty Polyurethane and TPU Technologies 1.7.7 Regional Investment Hotspots and Growth Markets 1.7.8 R&D, Innovation and Technology Development Funding Trends 1.7.9 Future Investment Opportunities and Strategic Growth Outlook 1.8 Innovation Trends Shaping Future Polyurethane Development 1.8.1 Bio-Based and Renewable Polyurethane Material Innovations 1.8.2 Recycled and Circular Polyurethane Technology Developments 1.8.3 Advanced TPU and Specialty Polyurethane Product Innovations 1.8.4 Low-Carbon and Sustainable Manufacturing Technologies 1.8.5 Smart, Functional and Lightweight Polyurethane Material Development 1.8.6 Automation, Digitalization and Industry 4.0 Integration in Production 1.9 Sustainability Trends and Environmental Impact Analysis 1.9.1 Carbon Footprint and Greenhouse Gas Emissions Assessment 1.9.2 Bio-Based and Renewable Polyurethane Adoption Trends 1.9.3 Recycled Polyurethane and Circular Economy Initiatives 1.9.4 Low-Carbon Manufacturing and Energy Efficiency Strategies 1.9.5 Waste Management, Recycling and End-of-Life Solutions 1.9.6 Environmental Regulations, ESG and Compliance Requirements 1.9.7 Sustainable Raw Material Sourcing and Supply Chain Practices 1.10 Demand and Consumption Pattern Analysis (2025) 1.10.1 Global Polyurethane Demand Overview and Consumption Trends 1.10.2 End-Use Industry Demand Assessment 1.10.3 Regional Consumption Pattern and Market Share Analysis 1.10.4 Customer Purchasing Behavior and Procurement Trends 1.10.5 Application-Wise Consumption Benchmarking 1.10.6 Demand-Supply Balance and Consumption Gap Analysis 1.10.7 Key Demand Drivers and Emerging Consumption Trends 1.11 Import Export Trade Flow Analysis (2025) 1.11.1 Global Polyurethane Import-Export Overview 1.11.2 Key Exporting and Importing Regions 1.11.3 Regional Trade Dependency and Supply Gap Assessment 1.11.4 Major Trade Routes and Logistics Corridor Mapping 1.11.5 Tariff, Duties and Trade Regulation Impact Analysis 1.11.6 Import Price Benchmarking and Export Price Trends 1.11.7 Supplier-Customer Trade Relationship Mapping 1.11.8 Trade Risk Assessment and Future Trade Outlook 1.12 Risk Assessment and Market Challenges Overview 1.12.1 Raw Material Price Volatility and Supply Risk Assessment 1.12.2 MDI, TDI and Polyol Supply Chain Disruption Analysis 1.12.3 Regulatory, Environmental and Compliance Risk Evaluation 1.12.4 Geopolitical and Trade Policy Impact Assessment 1.12.5 Demand Fluctuation and End-User Industry Dependency Analysis 1.12.6 Competitive Intensity and Market Consolidation Challenges 1.12.7 Sustainability Transition and Decarbonization Risks 1.12.8 Operational, Logistics and Distribution Network Challenges 1.13 Private Label and Brand Positioning Analysis 1.13.1 Global Private Label vs Branded Polyurethane Market Assessment 1.13.2 Private Label Product Portfolio and Offering Analysis 1.13.3 Brand Positioning Strategies of Leading Polyurethane Manufacturers 1.13.4 Customer Perception and Brand Preference Evaluation 1.13.5 Pricing Strategy Comparison: Private Label vs Branded Products 1.13.6 Distribution Channel and Market Reach Analysis 1.13.7 Competitive Benchmarking of Key Brands and Private Label Suppliers 1.13.8 Market Opportunities for Private Label Expansion 1.13.9 Future Brand Differentiation and Positioning Outlook 1.14 Polyurethane Raw Material Demand: Market Share and YoY Growth (2025–2034) 1.14.1 Isocyanates in Global Polyurethane Market Share (%) By Region 2025 1.14.2 North America 1.14.3 Europe 1.14.4 Asia Pacific 1.14.5 Middle East and Africa 1.14.6 South America 1.14.7 Polyols Global Polyurethane Market YoY Growth Rate (%) 2025–2034 1.14.8 Region wise Consumption of Polyurethane By Raw Material 1.15 Growth of Polyurethane By End-use Industry (2025–2034) 1.15.1 Global End-Use Industry Growth Overview 1.15.2 Building & Construction Industry Demand Growth Analysis 1.15.3 Furniture & Bedding Industry Consumption Growth Trends 1.15.4 Automotive & Transportation Sector Growth Assessment 1.15.5 Electronics & Appliances Industry Demand Evaluation 1.15.6 Footwear Industry Polyurethane Adoption Trends 1.15.7 Packaging Industry Growth and Consumption Analysis 1.15.8 Consumer Goods & Industrial Applications Growth Outlook 1.16 Adoption & Deployment Trends 1.16.1 Adoption Trends by Product Type (Foams, CASE, TPU and Specialty Polyurethane) 1.16.2 Regional Adoption and Market Penetration Assessment 1.16.3 Technology Adoption Trends in Polyurethane Manufacturing 1.16.4 Sustainable and Bio-Based Polyurethane Deployment Developments 1.16.5 Customer Acceptance and Procurement Trend Analysis 1.16.6 Adoption Drivers, Barriers and Decision-Making Factors 1.16.7 Emerging Application Deployment Opportunities 1.17 Consumer Preference and Buying Behavior Analysis 1.17.1 Polyurethane Buyer Profile and Customer Segmentation 1.17.2 Key Purchasing Criteria and Supplier Selection Factors 1.17.3 Price Sensitivity and Value Perception Analysis 1.17.4 Product Quality, Performance and Brand Preference Assessment 1.17.5 Procurement Models and Purchasing Decision-Making Process 1.17.6 Customer Loyalty and Supplier Switching Trends 1.17.7 Demand for Sustainable and Bio-Based Polyurethane Products 1.17.8 Distribution Channel Preference and Buying Patterns 1.17.9 Industry-Specific Consumer Requirements and Expectations 1.18 Digitalization Impact on Polyurethane Market 1.18.1 Digital Transformation Trends Across the Polyurethane Value Chain 1.18.2 Industry 4.0 Adoption in Polyurethane Manufacturing 1.18.3 AI, Machine Learning and Advanced Analytics Applications 1.18.4 Smart Manufacturing and Process Automation Assessment 1.18.5 Digital Supply Chain and Inventory Management Optimization 1.18.6 IoT-Enabled Monitoring and Predictive Maintenance Solutions 1.18.7 Digital Procurement, E-Commerce and Customer Engagement Trends 1.18.8 Data-Driven Product Development and Formulation Innovation 1.19 Inventory & Warehousing Optimization Analysis 1.19.1 Global Inventory Management Structure Assessment 1.19.2 Raw Material Inventory Analysis (MDI, TDI, Polyols and Additives) 1.19.3 Finished Product Inventory and Stocking Strategy Evaluation 1.19.4 Warehouse Network and Distribution Hub Assessment 1.19.5 Inventory Turnover and Stock Utilization Benchmarking 1.19.6 Demand Forecasting and Inventory Planning Analysis 1.19.7 Storage, Handling and Shelf-Life Management Assessment 1.20 ESG & Sustainability Assessment 1.20.1 ESG Landscape and Sustainability Trends in the Polyurethane Industry 1.20.2 Environmental Impact and Carbon Footprint Assessment 1.20.3 Sustainable Raw Material Sourcing and Procurement Practices 1.20.4 Bio-Based, Recycled and Circular Polyurethane Adoption Analysis 1.20.5 Energy Efficiency and Low-Carbon Manufacturing Initiatives 1.20.6 Waste Management, Recycling and Circular Economy Strategies 1.20.7 ESG Compliance, Reporting Standards and Regulatory Frameworks 1.20.8 Sustainability Benchmarking of Leading Polyurethane Manufacturers 1.21 Polyurethane Product Portfolio Gap Analysis 1.21.1 Current Product Portfolio Structure Assessment 1.21.2 Market Demand vs Existing Product Offering Gap Analysis 1.21.3 High-Growth Product Segment Opportunity Assessment 1.21.4 Specialty Polyurethane and TPU Portfolio Evaluation 1.21.5 Bio-Based and Sustainable Product Gap Identification 1.21.6 Application-Specific Product Requirement Analysis 1.21.7 Competitive Product Portfolio Benchmarking 1.22 Comparative Analysis: Product Type in Global Polyurethane Market 1.22.1 Demand and Consumption Analysis by Product Category 1.22.2 Revenue Contribution and Market Share Benchmarking 1.22.3 Pricing Trends and Profitability Analysis 1.22.4 Technology and Innovation Comparison 1.22.5 Sustainability and Regulatory Compliance Benchmarking 1.22.6 Competitive Landscape and Product Positioning Analysis 1.22.7 Future Growth Potential and Opportunity Assessment 1.23 Future Technology Roadmap and Innovation Assessment 1.23.1 Polyurethane Technology Evolution and Future Roadmap 1.23.2 Bio-Based and Renewable Polyurethane Technology Developments 1.23.3 Recycled and Circular Polyurethane Innovation Pathways 1.23.4 Advanced TPU and Specialty Polyurethane Technology Trends 1.23.5 Low-VOC, Low-Carbon and Sustainable Formulation Innovations 1.23.6 Next-Generation MDI, TDI, Polyol and Additive Technologies 1.23.7 Automation, Digitalization and AI-Driven Formulation Development 1.24 Qualification, Certification and Time-to-Market Impact 1.24.1 Polyurethane Product Qualification and Approval Framework 1.24.2 Industry-Specific Certification Requirements Assessment 1.24.3 Raw Material Qualification Process (MDI, TDI, Polyols and Additives) 1.24.4 Product Testing, Validation and Performance Benchmarking Requirements 1.24.5 Regulatory Compliance and Certification Timeline Analysis 1.24.6 Customer Approval and Vendor Qualification Process Evaluation 1.24.7 Impact of Certifications on Market Access and Commercial Adoption 1.25 Long-Term Market Evolution and Structural Shifts 1.25.1 Future Evolution of the Global Polyurethane Industry 1.25.2 Shift from Conventional to Sustainable Polyurethane Systems 1.25.3 Structural Changes in Raw Material Supply and Feedstock Dynamics 1.25.4 Transformation of End-Use Industry Demand Patterns 1.25.5 Regional Production and Consumption Shift Analysis 1.25.6 Impact of Circular Economy and Recycling Initiatives 1.25.7 Technology Disruption and Next-Generation Polyurethane Development 1.25.8 Supply Chain Restructuring and Localization Trends 1.26 Polyurethane Market : Market size and Forecast by Segmentation (by Value USD Billion and Volume in Kiloton) (2025-2034) 1.26.1 Polyurethane Market Size and Forecast, By Raw Material 1.26.2 Isocyanates 1.26.3 Methylene Diphenyl Diisocyanate (MDI) 1.26.4 Toluene Diisocyanate (TDI) 1.26.5 Polyols 1.26.6 Polyether Polyols 1.26.7 Polyester Polyols 1.26.8 Bio-based Polyols 1.26.9 Others 1.26.10 Chain Extenders 1.26.11 Catalysts 1.26.12 Additives & Surfactants 1.26.13 Polyurethane Market Size and Forecast, By Product Type 1.26.14 Flexible Foam 1.26.15 Rigid Foam 1.26.16 Coatings 1.26.17 Adhesives & Sealants 1.26.18 Elastomers 1.26.19 Thermoplastic Polyurethane (TPU) 1.26.20 Others 1.26.21 Polyurethane Market Size and Forecast, By Processing Method 1.26.22 Injection Molding 1.26.23 Reaction Injection Molding (RIM) 1.26.24 Extrusion 1.26.25 Casting 1.26.26 Spray Application 1.26.27 Others 1.26.28 Polyurethane Market Size and Forecast, By Distribution Channel 1.26.29 Direct Sales 1.26.30 Distributors 1.26.31 Retailers 1.26.32 Polyurethane Market Size and Forecast, By Technology 1.26.33 HFC-Blown 1.26.34 Hydrocarbon-Blown 1.26.35 Water-Blown 1.26.36 Bio-Based Polyurethane 1.26.37 Others 1.26.38 Polyurethane Market Size and Forecast, By End-use Industry 1.26.39 Building & Construction 1.26.40 Insulation Panels 1.26.41 Roofing 1.26.42 Wall Systems 1.26.43 Flooring 1.26.44 Sealants 1.26.45 Furniture & Bedding 1.26.46 Mattresses 1.26.47 Upholstery 1.26.48 Cushions 1.26.49 Office Furniture 1.26.50 Automotive & Transportation 1.26.51 Seating 1.26.52 Interior Components 1.26.53 NVH Components 1.26.54 Exterior Components 1.26.55 EV Battery Insulation 1.26.56 Electronics & Appliances 1.26.57 Refrigerators 1.26.58 Freezers 1.26.59 HVAC 1.26.60 Consumer Electronics 1.26.61 Footwear 1.26.62 Soles 1.26.63 Safety Footwear 1.26.64 Sports Footwear 1.26.65 Packaging 1.26.66 Protective Packaging 1.26.67 Cold Chain Packaging 1.26.68 Consumer Goods 1.26.69 Others 1.26.70 Polyurethane Market Size and Forecast, By Region 1.26.71 North America 1.26.72 United States 1.26.73 Canada 1.26.74 Mexico 1.26.75 Europe 1.26.76 United Kingdom 1.26.77 France 1.26.78 Germany 1.26.79 Italy 1.26.80 Spain 1.26.81 Sweden 1.26.82 Russia 1.26.83 Rest of Europe 1.26.84 Asia Pacific 1.26.85 China 1.26.86 S. Korea 1.26.87 India 1.26.88 Japan 1.26.89 Australia 1.26.90 Indonesia 1.26.91 Philippines 1.26.92 Malaysia 1.26.93 Vietnam 1.26.94 Thailand 1.26.95 Rest of Asia Pacific 1.26.96 Middle East and Africa 1.26.97 South Africa 1.26.98 Bahrain 1.26.99 Kuwait 1.26.100 Oman 1.26.101 Qatar 1.26.102 Saudi Arabia 1.26.103 United Arab Emirates (UAE) 1.26.104 Turkey 1.26.105 Egypt 1.26.106 Nigeria 1.26.107 Rest of ME&A 1.26.108 South America 1.26.109 Brazil 1.26.110 Argentina 1.26.111 Chile 1.26.112 Colombia 1.26.113 Rest Of South America 1.26.114 (Note: Segment-wise market size figures for all regions will follow the same structure in the final report.) 2. COMPETITIVE INTELLIGENCE & INDUSTRIAL ECOSYSTEM 2.1 Company Profiles: Key Players 2.1.1 Overview 2.1.2 Business Portfolio 2.1.3 Financial Overview 2.1.4 SWOT Analysis 2.1.5 Strategic Analysis 2.1.6 Recent Developments 2.1.7 Dow Inc. 2.1.8 Huntsman Corporation 2.1.9 The Lubrizol Corporation 2.1.10 Carpenter Co. 2.1.11 RTP Company 2.1.12 Rogers Corporation 2.1.13 UFP Technologies, Inc. 2.1.14 FXI Holdings, Inc. 2.1.15 DuPont de Nemours, Inc. 2.1.16 Woodbridge Foam Corporation 2.1.17 BASF SE 2.1.18 Covestro AG 2.1.19 LANXESS AG 2.1.20 Recticel NV/SA 2.1.21 Trelleborg AB 2.1.22 RAMPF Holding GmbH & Co. KG 2.1.23 FoamPartner Group 2.1.24 Eurofoam Group 2.1.25 Zotefoams plc 2.1.26 Evonik Industries AG 2.1.27 Perstorp Holding AB 2.1.28 Sika AG 2.1.29 Henkel AG & Co. KGaA 2.1.30 COIM Group 2.1.31 SAPICI S.p.A. 2.1.32 PCC Group 2.1.33 Purinova Sp. z o.o. 2.1.34 Wanhua Chemical Group Co., Ltd. 2.1.35 Mitsui Chemicals, Inc. 2.1.36 Tosoh Corporation 2.1.37 DIC Corporation 2.1.38 Sekisui Chemical Co., Ltd. 2.1.39 INOAC Corporation 2.1.40 Mitsubishi Chemical Group Corporation 2.1.41 UBE Corporation 2.1.42 Kumho Mitsui Chemicals Inc. 2.1.43 Nippon Polyurethane Industry Co., Ltd. 2.1.44 Manali Petrochemicals Limited 2.1.45 Sheela Foam Limited 2.1.46 SABIC 2.1.47 Sadara Chemical Company 2.1.48 Pearl Polyurethane Systems 2.1.49 Emirates Chemicals LLC 2.1.50 Era Polymers 2.1.51 Purcom Química 2.1.52 Flexível Indústria e Comércio 2.1.53 Tecnofibras 2.1.54 Others 2.2 Competitive Landscape Overview of Key Market Participants 2.2.1 Global Polyurethane Market Structure and Competitive Dynamics 2.2.2 Market Share Analysis of Leading Polyurethane Manufacturers 2.2.3 Competitive Positioning and Benchmarking of Key Players 2.2.4 Product Portfolio and Technology Capability Assessment 2.2.5 Production Capacity and Manufacturing Footprint Analysis 2.3 Company Business Strategy and Expansion Approaches 2.3.1 Corporate Strategy and Long-Term Growth Vision 2.3.2 Product Portfolio Expansion and Diversification Strategies 2.3.3 Capacity Expansion and Manufacturing Investment Initiatives 2.3.4 Geographic Expansion and Market Penetration Approaches 2.3.5 Distribution Network and Channel Development Strategies 2.4 Product Portfolio Analysis of Leading Market Players 2.4.1 Product Portfolio Structure of Leading Polyurethane Companies 2.4.2 Raw Material Portfolio Analysis: MDI, TDI, Polyols and Additives 2.4.3 Product Type Coverage: Foams, CASE, TPU and Specialty Polyurethane 2.4.4 Application-Specific Product Offering Assessment 2.4.5 High-Performance and Specialty Grade Portfolio Benchmarking 2.5 Revenue Performance and Financial Analysis Overview 2.5.1 Revenue Performance and Growth Trend Analysis 2.5.2 Business Segment Revenue Contribution Assessment 2.5.3 Product Portfolio Revenue Breakdown Analysis 2.5.4 Regional Revenue Distribution and Market Presence Evaluation 2.5.5 Profitability and Margin Performance Assessment 2.5.6 Capital Expenditure and Investment Trend Analysis 2.5.7 R&D Spending and Innovation Investment Evaluation 2.6 Future Strategic Outlook of Leading Market Players 2.6.1 Long-Term Growth Strategies and Strategic Priorities 2.6.2 Capacity Expansion and Production Scale-Up Plans 2.6.3 Geographic Expansion and Market Penetration Initiatives 2.6.4 Product Portfolio Diversification and Specialty Polyurethane Focus 2.6.5 Sustainability, Circular Economy and ESG Roadmap 2.6.6 Investment in Advanced Technologies and Innovation Programs 2.6.7 Strategic Partnerships, Joint Ventures and Collaboration Plans 3. STRATEGIC RECOMMENDATION 3.1 Key Findings 3.2 Analyst Recommendation 3.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements