
Marine HVAC Market - Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning / Landscape Review & Global Market Size Forecast to 2034
Overview
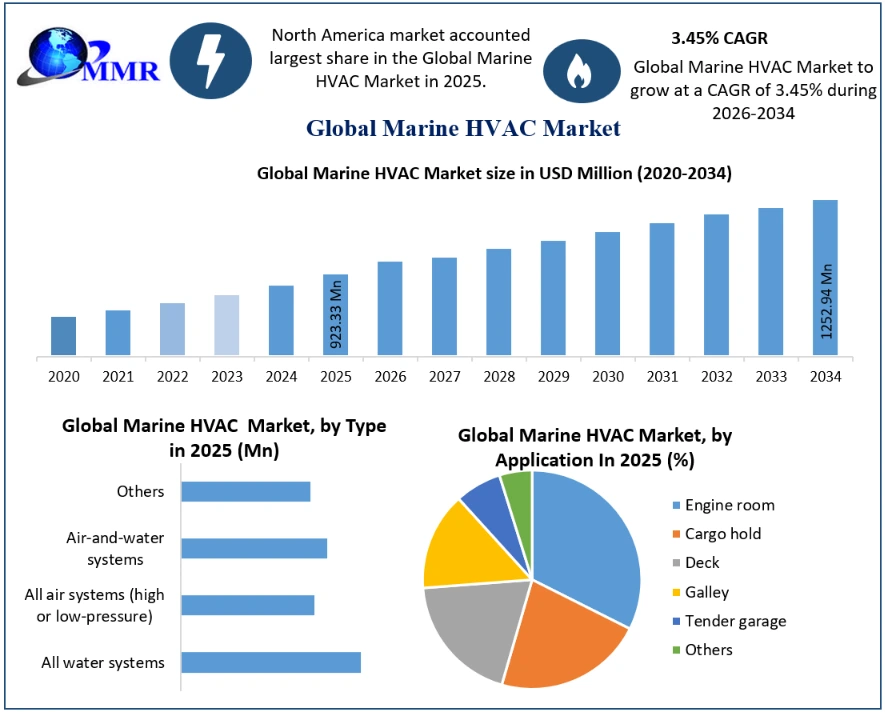
The Marine HVAC Market size was valued at USD 923.33 Million in 2025 and the total Marine HVAC revenue is expected to grow at a CAGR of 3.45% from 2026 to 2034, reaching nearly USD 1252.94 Million by 2034.
Global Marine HVAC Market Overview
The Marine HVAC Market covers critical onboard technologies designed to regulate temperature, humidity, and air quality in marine environments, ensuring comfort for crew and passengers while protecting equipment and cargo from harsh climatic conditions. These systems serve a wide range of vessel types, including commercial ships, naval vessels, offshore platforms, and luxury yachts, addressing challenges such as high humidity, saltwater corrosion, and extreme temperature variations. Advanced marine HVAC solutions integrate high-efficiency chillers, variable air volume controls, and energy recovery systems to deliver optimal thermal comfort while minimizing operational costs. Beyond human comfort, they play a vital role in safeguarding sensitive electronic and mechanical systems in key areas such as engine rooms, cargo holds, and control centers.
The Marine HVAC Market is experiencing growth driven by increasing global maritime trade, expansion of naval fleets in major economies, and rising demand for energy-efficient HVAC solutions that meet stringent marine emission regulations. In 2025, global seaborne trade volumes exceeded 12 billion metric tons, with North America ports seeing significant expansion alongside stable operations in Europe and Asia Pacific. Naval modernization programs in countries such as the U.S., China, and India are accelerating the adoption of advanced HVAC systems featuring improved thermal management, low global warming potential refrigerants, and integrated automation controls. Additionally, offshore energy activities in oil, gas, and emerging offshore wind sectors are fueling demand for heavy-duty, high-capacity marine HVAC installations.
Innovation is also reshaping the Marine HVAC Market, with advancements such as computational fluid dynamics (CFD) for airflow optimization and modular, space-saving unit designs reducing installation complexity while improving performance. Digital monitoring and predictive maintenance technologies are extending equipment lifecycles and minimizing downtime, further enhancing system reliability. As vessel operators increasingly prioritize sustainability and operational efficiency, marine HVAC systems are becoming central to ship design, retrofits, and refitspositioning the market for steady and sustained growth through 2034.
Marine HVAC Market Growth and Share Analysis
To know about the Research Methodology :- Request Free Sample Report
Global Marine HVAC Market Dynamics
Growing Shipping Industry and Stringent Environmental Regulations to Drive the Marine HVAC Market Growth
The marine HVAC market in the United States had undergone substantial growth, predominantly driven by the extensive global shipping industry and the incessant rise in global trade. The US played a pivotal role in propelling this growth, and the market exhibited potential regions for development not only within the US but also in neighbouring countries such as Canada and Mexico. This development was further influenced by the imposition of severe environmental protocols within the sector, prompting a shift towards the adoption of energy-efficient and environmentally friendly HVAC solutions to ensure compliance. The competitive landscape underscored the importance of Marine HVAC Market share, especially among major players, including the US, Germany, and France. Also, the US marine HVAC market demonstrated a significant focus on enhancing crew well-being, leading to an increased demand for systems that enhance on board living conditions. Ongoing technological advancements, particularly in smart and connected HVAC systems, positioned the US at the forefront of innovation, presenting the potential to drive further growth in the market. The market exhibited distinct key segments, and competition extended beyond the US to international rivals, notably China.
Rising Demand for Specialized Vessels and Increase in Retrofitting Projects are bolstering to Create opportunities in Marine HVAC Market
In terms of opportunities, retrofitting projects emerged as a substantial avenue for manufacturers and service providers in the US marine HVAC market. This involved upgrading and modernizing existing vessels, aligning with the growing demand for specialized vessels such as offshore support vessels and cruise ships. The global expansion of offshore wind farms presented another notable opportunity, requiring HVAC systems tailored to the unique environmental conditions associated with offshore installations, both within the US and globally. The industry's heightened focus on sustainability created additional prospects for marine HVAC systems prioritizing energy efficiency and utilizing environmentally friendly refrigerants, aligning with the growing trends in the US
Cost Constraints with Technical Challenges to Restrain the Marine HVAC Market Growth
Conversely, the US marine HVAC market faced specific challenges. Cost constraints within the cost-sensitive maritime industry posed hurdles, as the initial and operational costs associated with advanced HVAC systems acted as a restraint for some US ship operators. Technical challenges, particularly in designing HVAC systems capable of withstanding the harsh marine environment, presented obstacles that could impact the market's growth rate in the US the COVID-19 pandemic had a notable impact on the US shipping industry, leading to delays in new builds and retrofits, potentially affecting the demand for marine HVAC systems. Additionally, regulatory uncertainties or changes in environmental regulations posed challenges for US manufacturers, necessitating compliance efforts and adaptation to evolving standards.
Marine HVAC Market Segment Analysis
Based on Type, all water systems Segment dominated the Marine HVAC Market in 2025. This type dominates the US market, positioning the country as a significant player in this segment. The potential for expansion extends beyond US borders, presenting opportunities in neighbouring regions such as Canada and Mexico. The growth of all air systems, whether high or low-pressure, has been notable in the US Marine HVAC market. This segment operates within a competitive landscape, marked by market penetration strategies within the US and intense competition, particularly between the US and China. The integration of air-and-water systems stands out as a distinctive segment in the Marine HVAC market, with the US holding a substantial market share. Competition dynamics transcend national borders, involving major players from the US, Germany, and France. The others category introduces diverse HVAC solutions, showcasing innovations within the US Marine HVAC market. This segment offers an opportunity for targeted market analysis, exploring consumer demographics and specific trends in product segmentation.
Based on Capacity, the less than 10 Refrigeration Tons (RT) Segment dominated the Marine HVAC Market in 2025, demonstrating significant growth potential in the US market. Sub-segments within this category warrant detailed product segmentation analysis to align with consumer preferences and market demands. The 11-100 RT segment presents growth opportunities in the US, striking a balance between efficiency and adaptability. Geographic market segmentation within the US can further refine strategies to target specific regions and meet diverse consumer needs. HVAC systems exceeding 100 RT capacity cater to larger vessels, holding promise for substantial growth in the European market. Market segmentation should consider dominant sectors and geographic nuances to ensure effective penetration.
Based on Application, In 2025, the engine room dominated the Marine HVAC Market due to its critical role in maintaining safe operating conditions for ship machinery and ensuring compliance with stringent maritime regulations. Engine rooms generate intense and continuous heat from engines, generators, and auxiliary equipment, making robust HVAC systems essential to prevent overheating, protect sensitive machinery, and avoid operational downtime. This segment also demands high-capacity, energy-efficient cooling and ventilation solutions to meet International Maritime Organization (IMO) safety standards, while integrating modern features such as energy recovery, low-GWP refrigerants, and automated controls. Given its direct impact on vessel safety, operational reliability, and cost efficiency, the engine room remains the largest application segment in the market.
Marine HVAC Market Regional Insights
The Marine HVAC market in North America is undergoing remarkable growth, particularly in the US, where it plays a vital role in the dominant sector of the industry. The US exhibits continuous market growth, showcasing potential regions for expansion not only within its borders but also in Canada and Mexico. Market penetration in the US is characterized by a focus on advanced HVAC solutions, including all water and air systems, to align with stringent environmental regulations. The competitive landscape in the US involves notable market share dynamics among major players, emphasizing the region's significance in driving overall market growth. In Europe, the Marine HVAC market boasts a robust presence, driven by the well-established shipping industry and maritime infrastructure. Key players such as Germany and France significantly contribute to the market's development. The region prioritizes the adoption of innovative HVAC technologies, with a notable emphasis on air-and-water systems, reflecting a commitment to environmental sustainability. The competitive landscape in Europe places a strong focus on market share, with continuous efforts directed at technological advancements.
The European market presents opportunities for growth through retrofitting projects and the customization of HVAC solutions for specialized vessels. The Asia Pacific region emerges as a dynamic hub for the Marine HVAC market, experiencing exponential growth fueled by the thriving shipping and offshore industries. Remarkably, China plays a substantial role in the region's market expansion, fostering intense competition, particularly with the US Market penetration in Asia Pacific is marked by a focus on high-capacity HVAC systems catering to large vessels navigating these waters. Technological advancements in marine ventilation and air conditioning systems align with the region's emphasis on innovation. The Asia Pacific market offers lucrative opportunities, especially in the global expansion of offshore wind farms, driving demand for specialized HVAC solutions.
The Marine HVAC market in the Middle East and Africa is witnessing growth influenced by the region's strategic maritime positioning and the presence of vital shipping routes. The demand for efficient HVAC systems is driven by the extreme environmental conditions prevalent in these areas. The Middle East, in particular, stands out as a dominant sector, presenting opportunities in retrofitting projects and addressing specific HVAC needs for vessels navigating through challenging climates. The regional competitive landscape places emphasis on marine refrigeration systems, vital for preserving perishable goods during transit. Market segmentation in the Middle East and Africa considers unique applications, including deck-based systems and those tailored for cargo holds. South America's Marine HVAC market showcases significant potential, driven by the region's growing maritime activities and expanding fleet.
The market experiences notable growth in South America, with Brazil emerging as a dominant sector contributing significantly to the overall market share. Opportunities for growth exist in retrofitting projects and the strategic deployment of HVAC systems in specialized vessels navigating South American waters. The competitive landscape involves focused market penetration efforts, considering diverse applications and environmental conditions specific to the region. The regional outlook underscores the importance of understanding local market entry strategies and tailoring products to meet the unique demands of the South American marine HVAC market.
Marine HVAC Market Competitive Landscape
The competitive landscape of the Marine HVAC market is characterized by robust competition, technological innovation, and strategic acquisitions, reflecting the industry's dynamic nature. Key players engage in competitor benchmarking, strategic reviews, and continuous adaptation to maintain and enhance their market positions. Johnson Controls is set to expand its OpenBlue digital buildings capabilities through the acquisition of workplace management software leader FM:Systems. This strategic move enhances Johnson Controls' leading OpenBlue digital buildings software portfolio by incorporating complementary cloud-based software as a service (SaaS) digital workplace management capabilities. The acquisition anticipates double-digit revenue growth and accretive gross and operating margins for Johnson Controls. The synergy between the two entities is expected to provide increased capabilities and offerings, benefiting Johnson Controls customers.
As the global leader in smart, healthy, and sustainable buildings, Johnson Controls solidifies its position by acquiring FM:Systems, a prominent provider of digital workplace management and Internet of Things (IoT) solutions for facilities and real estate professionals. The transaction involves a base purchase price of USD 455 million, with additional payments contingent on the achievement of post-closing earn-out milestones. In another strategic move, Johnson Controls acquires M&M Carnot to enhance its sustainable Industrial Refrigeration portfolio. This acquisition is a response to the growing demand for ultra-low global warming potential refrigerant technologies. The incorporation of unique CO2 technology broadens Johnson Controls' portfolio of sustainable solutions, aligning with the objective of helping customers achieve net-zero emissions. The acquisition of M&M Carnot positions Johnson Controls as a leader in providing natural refrigeration solutions with ultra-low global warming potential.
Carrier Commercial Refrigeration, in collaboration with METRO AG, receives recognition as a Top Project of the Year in the Environment and Energy Leader Awards 2023. This acknowledgment is based on Carrier Commercial Refrigeration's multi-year collaboration with METRO AG, deploying new natural refrigerant equipment across METRO stores in Europe. The collaboration supports METRO's F-Gas Exit Program, aiming to convert over 760 stores to natural refrigerant systems and reduce carbon dioxide (CO2) footprint by 60% by 2030. Carrier Commercial Refrigeration's installation of high-efficiency remote cabinets and cold-room equipment, including the CO2OLtec Evo system, contributes to average energy savings of up to 30% compared to traditional hydro fluorocarbon products.
The use of climate-neutral CO2 refrigerant aligns with Carrier's commitment to sustainability, with a Global Warming Potential (GWP) of just one. Additionally, Carrier Commercial Refrigeration introduces Refrigeration-as-a-Service (RaaS) for the food retail industry in collaboration with Relayr, Inc. This innovative offering eliminates the need for food retailers to make upfront investments in refrigeration equipment and infrastructure. Instead, they pay a monthly fee based on the performance of the equipment in use.
The RaaS solution aims to empower food retailers by enhancing efficiency, reliability, cost performance, and overall business resilience. Carrier Commercial Refrigeration's expertise in designing, manufacturing, installing, and servicing refrigeration solutions combines with Relayr's IoT technology, equipment financing, and operational asset management, providing a comprehensive and forward-thinking solution for the food retail industry. The Marine HVAC market's competitive landscape is witness further consolidation through strategic acquisitions and collaborations. Key players will continue to invest in research and development, aiming to stay ahead in technological innovation and address the evolving demands of the maritime industry.
Global Marine HVAC Market Trends
| Category | Trend | Example | Market Impact |
| Technology Advancement | Smart & IoT-Enabled HVAC Systems | Johnson Controls Launching shipboard automation and smart HVAC controls | Improves operational efficiency, reduces downtime, enables predictive maintenance, and enhances passenger comfort |
| Sustainability & Compliance | Energy Efficiency & Eco-Friendly Refrigerants | Daikin Industries Promoting R-32 and low-GWP refrigerant marine systems | Helps ship operators meet IMO and environmental regulations while lowering energy consumption and operating costs |
| Design & Customization | Modular & Customized HVAC Solutions | Carrier Corporation Providing modular marine HVAC units for diverse vessel types | Enhances installation flexibility, supports retrofitting, and expands OEM and aftermarket opportunities |
Global Marine HVAC Market Recent Development
| Date | Company | Development | Impact |
|---|---|---|---|
| 15 January 2026 | FläktGroup | FläktGroup confirmed the completion of several major naval defense projects within its marine business unit for international clients, including defense forces in India and the United States. | The successful deployments enhance the company's presence in critical naval environmental control systems designed for extreme maritime operational conditions. |
| 05 February 2026 | Carrier Global Corporation | Carrier reported a 50% surge in commercial orders for late 2025 and launched its 2026 Aftermarket Playbook focused on lifecycle optimization across marine and commercial HVAC systems. | The strategic framework accelerates system longevity, energy efficiency, and lifecycle aftermarket services for global maritime fleet operators. |
| 18 March 2026 | Heinen & Hopman | Heinen & Hopman launched a new range of corrosion-resistant modular HVAC units engineered specifically for offshore renewable energy substations. | The modular engineering reduces vessel installation time by 20% while providing durable climate-control systems for harsh marine environments. |
| 14 April 2026 | Modutec | Modutec completed the strategic acquisition of EOS Europe to expand its turnkey marine engineering and offshore living quarters capabilities. | The transaction strengthens Modutec's global capacity to deliver integrated HVAC, piping, and electrical systems for marine and energy sector vessels. |
| 26 August 2026 | Daikin Industries | Daikin unveiled its new direct current (DC)-powered marine chiller concept at SMM 2026 to integrate with hybrid and fully electric vessel power architectures. | The DC architecture minimizes power conversion losses to significantly improve total onboard energy efficiency and lower equipment footprint. |
Marine HVAC Market Scope :Inquire Before Buying
| Marine HVAC Market: | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2032 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 923.33 USD Million |
| Forecast Period 2026-2032 CAGR: | 3.45% | Market Size in 2032: | 1252.94 USD Million |
| Segments Covered: | by Type | All water systems All air systems (high or low-pressure) Air-and-water systems Others |
|
| by Vessel Type | Passenger Type Cruise Ships and Ferries Yachts and Leisure Vessels Cargo Carriers Fishing Vessels Offshore Platform Vessels Others |
||
| by Installation Type | Newbuild installations Retrofit installations |
||
| by System Type | Centralized Systems Decentralized Systems Hybrid Systems Integrated HVAC Systems |
||
| by Capacity | Less than 10 RT 11- 100 RT More than 100 RT |
||
| by Technology | Marine ventilation systems Marine air conditioning Marine heating systems Marine refrigeration systems |
||
| by Application | Engine room Cargo hold Deck Galley Tender garage Others |
||
| by End User Ownership | Commercial fleet operators Naval & defense fleets Offshore energy operators Luxury vessel owners |
||
Global Marine HVAC Market, by Region
North America (United States, Canada, and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, and the Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, ASEAN, Indonesia, Philippines, Malaysia, Vietnam, Thailand, ASEAN, Rest of Asia Pacific)
Middle East & Africa (South Africa, GCC, Nigeria, Rest of ME&A)
South America (Brazil, Argentina, Rest of South America)
Global Marine HVAC Market, Key Players
North America
1. Carrier Corporation (Carrier Global Corporation)
2. Johnson Controls International plc
3. Bronswerk Marine Inc.
4. Leonardo DRS, Inc. (Leonardo S.p.A. — majority shareholder)
5. Cruisair (Dometic Group AB)
6. Marine Air Systems (Dometic Group AB)
7. Technicold Climate Control
8. Emerson Electric Co.
Europe
9. Dometic Group AB
10. Heinen & Hopman Engineering B.V.
11. Drews Marine GmbH
12. Novenco Marine & Offshore A/S
13. Frigomar S.r.l.
14. Kongsberg Maritime AS
15. Webasto SE
16. Horn International AS
17. AF Group ASA
18. GEA Group AG
19. Condaria
20. Zanotti S.p.A.
Asia Pacific
21. Daikin Industries, Ltd.
22. Mitsubishi Heavy Industries, Ltd.
23. NADI Airtechnics Pvt. Ltd.
24. Toyo Kanetsu K.K.
25. HD Hyundai Heavy Industries Co., Ltd.
26. JOSUN Air Conditioner Co., Ltd.
27. Firsquare Energy (Shanghai) Co., Ltd.
28. Mermaid Marine Air Conditioning
Others
1.Which region has the largest share in Global Marine HVAC Market?
Ans: North America region held the highest share in 2025.
2.What is the growth rate of Global Marine HVAC Market?
Ans: The Global Marine HVAC Market is growing at a CAGR of 3.45% during forecasting period 2026-2034.
3.What is scope of the Global Marine HVAC Market report?
Ans: Global Marine HVAC Market report helps with the PESTEL, PORTER, COVID-19 Impact analysis, Recommendations for Investors & Leaders, and market estimation of the forecast period.
4.Who are the key players in Global Marine HVAC Market?
Ans: The important key players in the Global Marine HVAC Market are – Denso Corporation, Hanon Systems, Sanden Holding Corporation, Mitsubishi Heavy Industries Ltd, MAHLE GmbH, Valeo SA, Keihin Corporation, Calsonic Kansei Corporation, Samvardhana Motherson Group, Subros Limited, SMAC Auto Air, TransAir Manufacturing, Eberspacher Group, Marelli Corporation.
5.What is the study period of this Market?
Ans: The Global Marine HVAC Market is studied from 2020 to 2034.