Linear Polymer Market by Manufacturing Process, Type, Application, End-Use Industry, and Region - Global Market Size Estimation, Industry-Wide Analysis, Competitive Landscape Assessment & Long-Term Forecast to 2034

4.7%
CAGR (2026-2034)
318.04 USD Bn.
Forecast Market Size
325
Report Pages
155
Market Tables

Overview

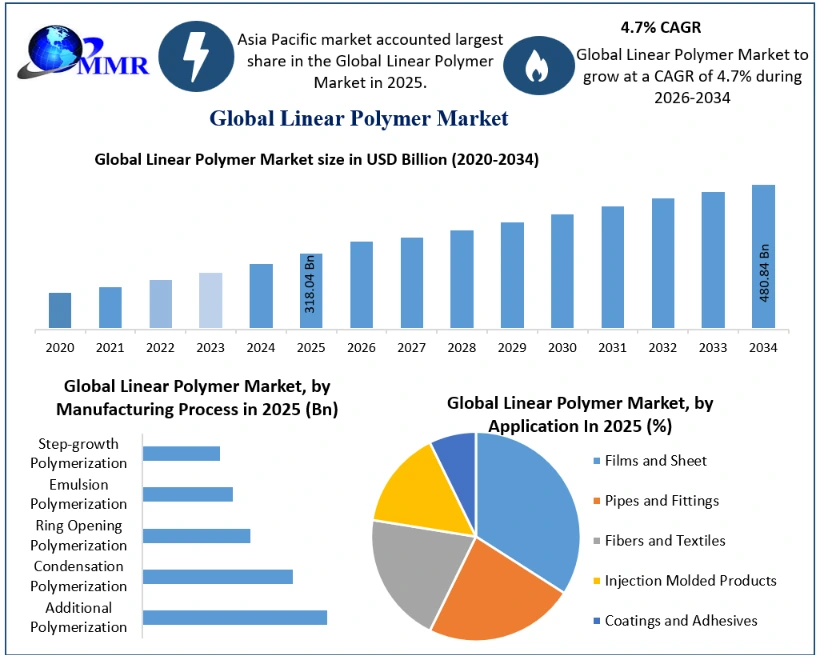
Linear Polymer Market was valued at USD 318.04 Bn in 2025, and Global Linear Polymer Market is expected to reach USD 480.84 Bn by 2034, growing at a CAGR of 4.7% during the forecast period.

Linear Polymer Market Overview:

Linear polymers are one type of polymer, which is characterized by their linear or straight-chain structure. These polymers consist of long and straight chains. They are composed of repeating units, including monomers, which are linked together linearly without any branching or cross-linking.

A major driver is the packaging industry, which requires lightweight, cost-effective, and environmentally friendly products with high barrier properties of the convenience food and e-commerce. At the same time, the growth of the automotive industry, especially in emerging markets, has been driving growth in demand of linear polymers such as polypropylene and polyethylene to substitute heavier metal parts of cars, thereby improving fuel economy and lowering emissions. Asia Pacific dominated the Linear Polymer Market, due to robust industrial growth, development, rising disposable incomes, and many more.

This report provides a straightforward, futuristic perspective of Global Linear Polymer Market.It gives a thorough evaluation in the form of such tools as PORTER, SVOR, and PESTEL to determine the factors that influence the business. This report divides the market and estimates its size and it is a guide to investors since it explains the strategies, portfolio and whereabouts of key players.

Linear Polymer Market Growth OutlookLinear Polymer Market Growth
To know about the Research Methodology :- Request Free Sample Report

Linear Polymer Market Dynamics:

High Demand for Linear Polymers from the Packaging Industry to Drive Market Growth

The packaging industry has to demand sustainable and efficient packaging solutions, which is the primary influencing factor for linear polymer market growth. Linear polymers provide excellent barrier properties, cost advantages, lightweight applications and making them ideal materials for packaging applications. The rising popularity of convenience foods, beverages, and e-commerce further fuels the demand for packaging materials, driving market growth. The demand for lightweight materials in industries such as automotive, aerospace, and transportation is driving the growth of linear polymers. Lightweight polymers, including polypropylene (PP) and polyethylene (PE), offer advantages such as fuel efficiency, reduced emissions, and improved performance. With the emphasis on reducing vehicle weight and enhancing energy efficiency, linear polymers are replacing traditional materials in lightweight applications, contributing to market growth.

Expansion of the Automotive Sector to fuel the Linear Polymer Market

Polypropylene and other resins are replacing metal materials in the automotive sector. PP: Polypropylene demand is expected to increase because automobile manufacturers use it in cars’ interiors and exteriors. The automotive lightweight trends, being driven by sustainability, cost, and performance, create an enormous demand for lightweight materials and design concepts. The automotive industry's emphasis on lightweight materials to increase fuel efficiency and reduce emissions is driving the demand for linear polymers. High-density polyethylene (HDPE) and polypropylene (PP) are widely used in automotive components, electrical systems, and under-the-hood applications. The expansion of the automotive sector, particularly in emerging economies, is expected to create lucrative opportunities for the linear polymer industry's growth potential.

Technological Advancements and Innovations in Linear Polymers to Boost the Market

In emerging economies, continuous research and technological advancements in polymer synthesis and modification techniques have to improve the performance and characteristics of linear polymers. These advancements have expanded their potential applications in various industries, including packaging, construction, electronics, and more. Innovations in polymer blends and additive formulations have to fuel the Linear Polymer Market growth and create new opportunities.

Bio-based Polymers and Emerging Application Areas to Create Lucrative Opportunity for Market Growth

Industrialization and infrastructure development in developing economies and growing concern toward eco-friendly products and availability of energy-efficient solutions are expected to drive the demand for lightweight and sustainable materials in the global Linear Polymer Market. Sustainability and eco-friendly practices present significant growth opportunities for sustainable and bio-based linear polymers. These alternatives reduce carbon footprint and offer improved recyclability compared to traditional polymers. As governments and industries prioritize sustainable materials, the demand for bio-based linear polymers is expected to rise, creating opportunities for market players. Adoption of linear polymers through the automotive and aerospace industry to achieve and improve fuel efficiency.

Linear Polymer Market Segment Analysis

Based on type, the Polyethylene (PE) linear polymer segment dominated the largest Linear Polymer Market share in 2025. Polyethylene is one of the most widely used linear polymers, known for its excellent strength, durability, and chemical resistance. It finds extensive applications in packaging, construction, and automotive industries. Also, it is available in various forms including low-density Polyethylene, high-density Polyethylene, and linear low-density Polyethylene, which is used for packaging material. The increase in the application of polyethylene is expected to drive the demand for Polyethylene segment growth in the global market.

Based on End-Use Industry, in 2025, the packaging industry held the largest Linear Polymer Market share and is expected to grow at a significant CAGR during the forecast period. Linear polymers are used in the packaging industry for applications such as flexible packaging films, bottles, containers, and closures. In the automotive industry for interior and exterior components, electrical systems, and under-the-hood applications. Industries such as automotive and aerospace are significantly adopting linear polymers for reducing emissions and fuel efficiency. The construction segment growth is driven by huge investments in infrastructure projects and development in the transportation network. Huge demand for pipes, cables, insulated materials, flooring roofing, waterproofing membrane and other applications are expected to boost the segment growth during the forecast period.

Linear Polymer Market Regional Analysis

Asia Pacific dominated the global Linear Polymer Market share in 2025. Regional growth is influenced by robust industrial growth, urbanization, rising disposable incomes and growth of the middle-class population and the significant demand for linear polymers. The packaging industry in Asia-Pacific is driven by the rising consumption of packaged food, beverages, and personal care products, fuelling the demand for linear polymers. Demand for linear polymers for infrastructure development, residential construction, and building renovation projects, residential construction, and building renovation projects are expected to create lucrative opportunities for market growth.

Linear Polymer Market Competitive Analysis:

Top Key Players of Linear Polymer Market are Dow Inc. (United States), SABIC (Saudi Arabia), LyondellBasell Industries (United States), ExxonMobil Chemical Company (United States), and BASF SE (Germany). Dow Inc. (United States) has focused on innovation, sustainability, and customer collaboration to meet the diverse demands of industries such as packaging, automotive, construction, and healthcare. SABIC (Saudi Arabia), has been solidifying its position by acquiring full ownership of catalyst leader Scientific Design and a stake in agri-nutrients. LyondellBasell Industries (United States) is actively upgrading its portfolio by acquiring recycled compound manufacturer Mepol Group and the solvent-based recycling company APK, demonstrating a strong commitment to circular economy solutions. BASF SE (Germany) continues its focus on R&D and strategic partnerships to drive innovation in sustainable and high-performance polymers. With a strong emphasis on technological advancements and environmental concerns, these companies drive the market's growth, develop bio-based and recycled polymers, and contribute to a dynamic and competitive landscape.

Linear Polymer Market Key Trends:

• Performance and Advanced Materials
Innovation is focused on enhancing polymer properties. This includes developing high-performance polymers that offer improved strength, durability, thermal stability, and chemical resistance.
• Lightweighting in End-Use Industries
The automotive and aerospace sectors are driving demand for lightweight polymers to improve fuel efficiency and reduce emissions. This trend is pushing manufacturers to develop high-strength, low-density materials.
• Technological Advancements in Manufacturing
Innovations in polymerization techniques, extrusion, and injection molding are enabling the production of polymers with tailored properties and expanding their application possibilities.
• E-commerce and Packaging Demand
The booming e-commerce sector is fuelling demand for packaging materials, which is a major end-use segment for linear polymers. This is driving a need for both efficient and sustainable packaging solutions.

Linear Polymer Market Key Development:

Year Company Name Key Development
Jan 16, 2025 Dow Inc. (United States) Won six BIG Innovation Awards for new technologies, including high-performance HDPE and sustainable coating additives.
Apr 10, 2025 LyondellBasell Industries (United States) Announced that its Dalian Site in China operates fully on 100% renewable electricity.
May 05, 2024 SABIC (Germany) Announced a net loss in Q1 2025 but confirmed plans to invest up to $4 billion in capital expenditure.
Jun 12, 2025 Sumitomo Chemical (Japan) Established mass production technology for a super engineering plastic (LCP) using biomass materials to reduce reliance on fossil fuels.
April 25 2024 Reliance Industries Limited (India) Announced its financial results for FY 2024-25, highlighting a resilient performance in its Oil to Chemicals (O2C) business despite a volatile global environment.

Linear Polymer Market Scope: Inquire before buying

Linear Polymer Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 318.04 USD Billion
Forecast Period 2026-2034 CAGR: 4.7% Market Size in 2034: 480.84 USD Billion
Segments Covered: by Manufacturing Process Additional Polymerization
Condensation Polymerization
Ring Opening Polymerization
Emulsion Polymerization
Step-growth Polymerization
by Type Polyethylene (PE)
High-Density
    Polyethylene (HDPE)
  Low-Density
    Polyethylene (LDPE)
   Linear Low-Density
    Polyethylene (LLDPE)
  Ultra-High Molecular
    Weight Polyethylene
    (UHMWPE)
Polypropylene (PP)
  Homopolymer PP
  Copolymer PP
Polyvinyl Chloride (PVC)
Rigid PVC
  Flexible PVC
Polystyrene (PS)
General Purpose
    Polystyrene (GPPS)
  High Impact
    Polystyrene (HIPS)
  Expanded Polystyrene
   (EPS)
Polyamides (PA / Nylon)
PA 6
  PA 6,6
  Others
Others (PET, Polycarbonate,
ABS, etc.)
by Application Films and Sheet
Pipes and Fittings
Fibers and Textiles
Injection Molded Products
Coatings and Adhesives
by End-User Industry Packaging
Flexible Packaging
   Rigid Packaging
Agriculture
Automotive
Electronics
Oil & Gas
Construction
Healthcare
Consumer and goods

Linear Polymer Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest)
South America (Brazil, Argentina and Rest of South America)

Linear Polymer Market Key Players:

North America

1. Dow Inc. (United States)
2. LyondellBasell Industries (United States)
3. ExxonMobil Chemical Company (United States)
4. Chevron Phillips Chemical Company LLC (United States)
5. DuPont (United States)
6. Westlake Corporation (United States)
7. Celanese (United States)
8. Huntsman Corporation (United States)

Europe

9. BASF SE (Germany)
10. INEOS (United Kingdom)
11. TotalEnergies (France)
12. Covestro AG (Germany)
13. SABIC (Saudi Arabia)
14. Bamberger Polymers (Netherlands)
15. Arkema S.A. (France)
16. Borealis AG (Austria)
17. Versalis S.p.A. (Italy)
18. Solvay (Belgium)

Asia Pacific

19. Sinopec Group (China)
20. LG Chem (South Korea)
21. Formosa Plastics Corporation (Taiwan)
22. Reliance Industries Limited (India)
23. Sumitomo Chemical (Japan)
24. Mitsubishi Chemical Corporation (Japan)
25. Toray Industries (Japan)
26. Lotte Chemical Corporation (South Korea)
27. Polyplex Corporation Ltd. (India)
28. Jindal Poly Films Ltd. (India)
29. Prime Polymer Co., Ltd.
30. Mitsui Chemicals, Inc.
31. Idemitsu Kosan Co., Ltd.
32. Hanwha Solutions Corporation
33. China Petroleum & Chemical Corporation
34. PetroChina Company Limited

Middle East & Africa

35. Borouge (UAE)
36. Equate Petrochemical Company (Kuwait)
37. Sasol Limited (South Africa)

South America

38. Braskem S.A. (Brazil)
39. Petroquímica Cuyo (Argentina)

Table of Contents

1. Global Linear Polymer Market Introduction 1.1. Executive Market Landscape and Industry Overview 1.1.1. Global Linear Polymer Market Size (Value in USD Million & Volume Metric Tons) and Growth Outlook 1.1.2. Historical Market Size Trends Across Global Polymer Industry 1.1.3. Forecast Revenue Projections Through 2034 With Growth Drivers 1.1.4. Global Demand-Supply Balance Across Major Polymer Markets 1.1.5. Macroeconomic Indicators Influencing Linear Polymer Market Expansion 1.1.6. Evolution of Linear Polymers Across Plastics Applications 1.1.7. Oil and Gas Industry Demand Supporting Polymer Consumption 1.1.8. Engineering Material Applications Expanding Linear Polymer Opportunities 1.1.9. Long-Term Market Outlook Highlighting Emerging Growth Opportunities 1.2. Linear Polymer Market Dynamics 1.2.1. Linear Polymer Market Trends 1.2.2. Linear Polymer Market Dynamics 1.2.2.1. Drivers 1.2.2.2. Restraints 1.2.2.3. Opportunities 1.2.2.4. Challenges 1.2.3. PORTER’s Five Forces Analysis 1.2.4. PESTLE Analysis 1.3. Linear Polymer Pricing Structure and Value Chain Profitability 1.3.1. Comprehensive Linear Polymer Cost Structure Across Value Chain 1.3.2. Feedstock Costs Influencing Global Polymer Production Economics 1.3.3. Polymerization Costs Across Major Manufacturing Technology Platforms 1.3.4. Margin Distribution Across Producers, Compounders, and Distributors 1.3.5. Crude Oil Price Impact on Polymer Production Costs 1.3.6. Regional Polymer Pricing Differences Across Global Markets 1.3.7. Pricing Dynamics Across Plastics and Oil Gas Applications 1.3.8. Profitability Trends Across Major Polymer Industry Participants 1.4. Petrochemical Feedstock Procurement and Polymer Supply Dynamics 1.4.1. Key Feedstocks Supporting Global Linear Polymer Production 1.4.2. Ethylene and Propylene Supply Dynamics Across Regions 1.4.3. Natural Gas Influence on Polymer Production Economics 1.4.4. Integrated Refinery and Polymer Manufacturing Operations Analysis 1.4.5. Feedstock Supplier Dependency and Procurement Risk Assessment 1.4.6. Global Feedstock Price Volatility Affecting Polymer Costs 1.4.7. Regional Feedstock Advantages Supporting Polymer Production Competitiveness 1.4.8. Long-Term Feedstock Contracting and Procurement Strategies 1.5. Global Plastics Industry Evolution and Polymer Consumption 1.5.1. Evolution of Global Plastics Manufacturing and Consumption 1.5.2. Linear Polymer Demand Across Major Plastics Applications 1.5.3. Commodity Plastics and Engineering Material Demand Trends 1.5.4. Growth of Polymer-Based Products Across Industrial Applications 1.5.5. Lightweighting Trends Supporting Plastics Material Adoption 1.5.6. Replacement of Conventional Materials With Advanced Polymer Solutions 1.5.7. Expansion of Polymer Processing Industries Across Emerging Economies 1.5.8. Regional Plastics Manufacturing and Consumption Trends 1.6. Oil and Gas Application Dynamics and Industry Demand 1.6.1. Linear Polymer Demand Across Upstream Oil Gas Operations 1.6.2. Polymer Applications Supporting Exploration and Production Activities 1.6.3. Linear Polymer Adoption Across Onshore Oilfield Applications 1.6.4. Polymer Material Demand Across Offshore Oilfield Operations 1.6.5. Polymer Applications Across Midstream Pipeline Transportation Infrastructure 1.6.6. Linear Polymer Usage Across Downstream Refining Operations 1.6.7. Polymer Material Applications Across Oilfield Equipment Components 1.7. Linear Polymer Applications Across Oil and Gas Infrastructure 1.7.1. Polymer Pipes Supporting Oil and Gas Transportation Infrastructure 1.7.2. Flexible Pipe Applications Across Offshore Oilfield Operations 1.7.3. Polymer Liners Supporting Pipeline Protection and Durability 1.7.4. Tank Linings Providing Chemical and Corrosion Resistance 1.7.5. Polymer Seals and Gaskets Supporting Oilfield Equipment 1.7.6. Protective Polymer Coatings Supporting Pipeline Corrosion Prevention 1.7.7. Polymer Composites Supporting Advanced Oilfield Infrastructure Applications 1.8. Engineering Materials Performance and Selection Requirements 1.8.1. Mechanical Strength Requirements Across Industrial Polymer Applications 1.8.2. Chemical Resistance Requirements Across Oilfield Operating Environments 1.8.3. Corrosion Resistance Requirements Across Energy Infrastructure Applications 1.8.4. High-Temperature Performance Across Demanding Industrial Applications 1.8.5. Pressure Resistance Requirements Across Pipeline Polymer Components 1.8.6. Abrasion Resistance Across Oilfield and Industrial Applications 1.8.7. Impact Resistance Requirements Across Engineering Polymer Materials 1.9. Polymer Modification and Specialty Grade Development 1.9.1. Polymer Blending Supporting Enhanced Material Performance Characteristics 1.9.2. Reinforced Polymer Development Across Industrial Material Applications 1.9.3. Glass Fiber Reinforcement Supporting High-Strength Polymer Components 1.9.4. Carbon Fiber Reinforcement Supporting Lightweight Engineering Applications 1.9.5. Impact Modification Improving Polymer Toughness and Durability 1.9.6. Flame-Retardant Formulations Supporting Safety-Critical Industrial Applications 1.9.7. UV and Thermal Stabilization Enhancing Polymer Service Life 1.10. Linear Polymer Manufacturing and Processing Technology Evolution 1.10.1. Advances in Polymerization Technologies Supporting Production Efficiency 1.10.2. Advanced Reactor Technologies Improving Polymer Manufacturing Consistency 1.10.3. Extrusion Technologies Supporting Pipes and Polymer Profiles 1.10.4. Injection Molding Supporting Industrial Polymer Component Manufacturing 1.10.5. Blow Molding Supporting Specialized Polymer Product Applications 1.10.6. Thermoforming Technologies Supporting Advanced Polymer Product Manufacturing 1.10.7. Rotational Molding Supporting Large Polymer Component Production 1.11. Oil and Gas Polymer Processing and Field Performance 1.11.1. Polymer Processing Requirements Across Oilfield Component Manufacturing 1.11.2. Pipe Extrusion Technologies Supporting Oil and Gas Applications 1.11.3. Injection Molding Processes for Oilfield Polymer Components 1.11.4. Polymer Lining Technologies Supporting Pipeline Protection Requirements 1.11.5. Polymer Coating Technologies Supporting Corrosion Protection Applications 1.11.6. Seal and Gasket Manufacturing for Oilfield Equipment 1.12. Global Linear Polymer Trade Analysis and Supply Flows 1.12.1. Global Linear Polymer Trade Flow Trends Analysis 1.12.2. Import-Export Patterns Across Major Polymer-Producing Countries 1.12.3. Regional Trade Dependencies Affecting Polymer Market Stability 1.12.4. Polymer Trade Between Petrochemical and Manufacturing Economies 1.12.5. Tariff Barriers Affecting International Linear Polymer Trade 1.12.6. Geopolitical Factors Influencing Global Polymer Trade Routes 1.13. Linear Polymer Supply Chain and Distribution Dynamics 1.13.1. Global Linear Polymer Supply Chain Structure Analysis 1.13.2. Producer-to-Processor Distribution Models Across Regional Markets 1.13.3. Distribution Networks Supporting Global Plastics Manufacturing Demand 1.13.4. Supply Chains Supporting Oil and Gas Polymer Applications 1.13.5. Distributor and Compounder Networks Supporting Market Accessibility 1.13.6. Bulk Polymer Transportation Across Major Regional Markets 1.14. Sustainability and Circular Economy Development Trends 1.14.1. Sustainable Linear Polymer Development Across Global Markets 1.14.2. Mechanical Recycling Across Industrial Polymer Waste Streams 1.14.3. Chemical Recycling Technologies Supporting Advanced Polymer Circularity 1.14.4. Recycled Polymer Integration Across Plastics Applications 1.14.5. Bio-Based Feedstocks Supporting Sustainable Polymer Material Development 1.14.6. Carbon Footprint Reduction Across Polymer Manufacturing Operations 1.15. Linear Polymer Quality and Certification Standards Analysis 1.15.1. Polymer Grade Quality Classification Across Major Applications 1.15.2. Mechanical Performance Standards Governing Industrial Polymer Materials 1.15.3. Thermal Performance Standards Across High-Temperature Applications 1.15.4. Chemical Resistance Standards Supporting Oilfield Polymer Applications 1.15.5. Pressure Performance Requirements Across Pipeline Polymer Materials 1.15.6. Oil and Gas Material Certification Requirements Across Regions 1.15.7. Industrial Component Standards Governing Polymer Product Applications 1.16. Linear Polymer Regulatory Framework and Compliance Analysis 1.16.1. Global Regulations Governing Linear Polymer Manufacturing Operations 1.16.2. Chemical Registration Requirements Across Major Polymer Markets 1.16.3. Environmental Regulations Influencing Polymer Production Practices 1.16.4. Plastics Waste Regulations Affecting Polymer Product Development 1.16.5. Oil and Gas Material Regulations Across Major Markets 1.16.6. Pipeline Material Standards Influencing Polymer Application Development 1.16.7. Offshore Material Requirements Governing Polymer Component Applications 1.17. Material Substitution and Engineering Competition Across Applications 1.17.1. Metal-to-Polymer Substitution Across Industrial Applications 1.17.2. Composite-to-Polymer Substitution Across Engineering Material Applications 1.17.3. Polymer-to-Polymer Substitution Across Competitive Material Categories 1.17.4. Cost-Performance Comparison Across Major Material Alternatives 1.17.5. Weight Reduction Advantages Supporting Polymer Material Adoption 1.17.6. Corrosion Resistance Advantages Supporting Oilfield Polymer Applications 1.17.7. Lifecycle Cost Benefits Supporting Long-Term Polymer Adoption 1.18. Emerging Polymer Technologies and Future Material Opportunities 1.18.1. High-Temperature Polymer Technologies Supporting Energy Applications 1.18.2. High-Pressure Polymer Materials Supporting Oilfield Infrastructure 1.18.3. Chemical-Resistant Polymer Technologies Supporting Industrial Applications 1.18.4. Corrosion-Resistant Polymer Materials Supporting Pipeline Infrastructure 1.18.5. Wear-Resistant Polymer Technologies Improving Component Service Life 1.18.6. Self-Lubricating Polymer Materials Supporting Industrial Equipment Applications 1.18.7. Advanced Reinforced Polymer Technologies Supporting Engineering Applications 1.18.8. Smart Polymer Materials Supporting Advanced Industrial Applications 1.19. Regional Polymer Production Consumption and O&G Landscape 1.19.1. North American Polymer and Oil Gas Ecosystem 1.19.2. European Polymer and Engineering Material Industry Landscape 1.19.3. Asia Pacific Plastics Manufacturing and Polymer Demand Dynamics 1.19.4. Middle East Petrochemical Integration and Polymer Production 1.19.5. Middle East Oil Gas Polymer Application Landscape 1.19.6. Latin American Oil Gas and Polymer Demand 1.20. Linear Polymer Market: Market Size and Forecast by Segmentation (by Value USD Million & Volume in Metric Tons) (2025–2034) 1.20.1. Linear Polymer Market Size and Forecast, By Type 1.20.1.1. Polyethylene (PE) 1.20.1.1.1. High-Density Polyethylene (HDPE) 1.20.1.1.2. Low-Density Polyethylene (LDPE) 1.20.1.1.3. Linear Low-Density Polyethylene (LLDPE) 1.20.1.1.4. Ultra-High Molecular Weight Polyethylene (UHMWPE) 1.20.1.2. Polypropylene (PP) 1.20.1.2.1. Homopolymer PP 1.20.1.2.2. Copolymer PP 1.20.1.3. Polyvinyl Chloride (PVC) 1.20.1.3.1. Rigid PVC 1.20.1.3.2. Flexible PVC 1.20.1.4. Polystyrene (PS) 1.20.1.4.1. General Purpose Polystyrene (GPPS) 1.20.1.4.2. High Impact Polystyrene (HIPS) 1.20.1.4.3. Expanded Polystyrene (EPS) 1.20.1.5. Polyamides (PA / Nylon) 1.20.1.5.1. PA 6 1.20.1.5.2. PA 6,6 1.20.1.5.3. Others 1.20.1.6. Others (PET, Polycarbonate, ABS, etc.) 1.20.2. Linear Polymer Market Size and Forecast, By Manufacturing Process 1.20.2.1. Additional Polymerization 1.20.2.2. Condensation Polymerization 1.20.2.3. Ring Opening Polymerization 1.20.2.4. Emulsion Polymerization 1.20.2.5. Step-growth Polymerization 1.20.3. Linear Polymer Market Size and Forecast, By Application 1.20.3.1. Films and Sheets 1.20.3.2. Pipes and Fittings 1.20.3.3. Fibers and Textiles 1.20.3.4. Injection Molded Products 1.20.3.5. Coatings and Adhesives 1.20.3.6. Others 1.20.4. Linear Polymer Market Size and Forecast, By End User Industry 1.20.4.1. Packaging 1.20.4.1.1. Flexible Packaging 1.20.4.1.2. Rigid Packaging 1.20.4.2. Agriculture 1.20.4.3. Automotive 1.20.4.4. Electronics 1.20.4.5. Oil & Gas 1.20.4.6. Construction 1.20.4.7. Healthcare 1.20.4.8. Consumer and Goods 1.20.5. Linear Polymer Market Size and Forecast, By Region 1.20.5.1. North America 1.20.5.1.1. United States 1.20.5.1.2. Canada 1.20.5.1.3. Mexico 1.20.5.2. Europe 1.20.5.2.1. United Kingdom 1.20.5.2.2. France 1.20.5.2.3. Germany 1.20.5.2.4. Italy 1.20.5.2.5. Switzerland 1.20.5.2.6. Spain 1.20.5.2.7. Sweden 1.20.5.2.8. Russia 1.20.5.2.9. Rest of Europe 1.20.5.3. Asia Pacific 1.20.5.3.1. China 1.20.5.3.2. South Korea 1.20.5.3.3. Japan 1.20.5.3.4. India 1.20.5.3.5. Australia 1.20.5.3.6. Indonesia 1.20.5.3.7. Philippines 1.20.5.3.8. Malaysia 1.20.5.3.9. Vietnam 1.20.5.3.10. Thailand 1.20.5.3.11. Rest of Asia Pacific 1.20.5.4. Middle East and Africa 1.20.5.4.1. South Africa 1.20.5.4.2. Turkey 1.20.5.4.3. Saudi Arabia 1.20.5.4.4. UAE 1.20.5.4.5. Qatar 1.20.5.4.6. Egypt 1.20.5.4.7. Nigeria 1.20.5.4.8. Rest of ME&A 1.20.5.5. South America 1.20.5.5.1. Brazil 1.20.5.5.2. Argentina 1.20.5.5.3. Chile 1.20.5.5.4. Colombia 1.20.5.5.5. Rest of South America 2. Competitive Intelligence & Industrial Ecosystem 2.1. Competitive Landscape 2.1.1. MMR Competition Matrix 2.1.2. Competitive Positioning of Leading Key Players [Revenue and Market Share (%)] 2.1.3. Key Players Benchmarking 2.1.3.1. Company Name 2.1.3.2. Headquarter 2.1.3.3. Product Portfolio 2.1.3.4. Product Quality & Reliability 2.1.3.5. Technology Innovation & Differentiation 2.1.3.6. Manufacturing Capacity 2.1.3.7. Raw Material & Feedstock Supply Chain Strength 2.1.3.8. Distribution Network 2.1.3.9. End-Use Industry Coverage 2.1.3.10. Revenue (2025) 2.1.3.11. R&D Investment (%) 2.1.3.12. Profit Margin (%) 2.1.3.13. Growth Rate (Y-o-Y %) 2.1.3.14. Geographic Presence 2.1.4. Market Structure 2.1.4.1. Market Leaders 2.1.4.2. Market Followers 2.1.4.3. Emerging Players 2.1.5. Growth Rate/Y-o-Y (%) of Companies 2.1.6. Profit Margin (%) of Companies 2.1.7. R&D Investments (%) of Companies 2.1.8. Mergers and Acquisitions Details 2.1.9. Recent Key Developments 2.2. Linear Polymer Competitive Landscape and Industry Structure 2.2.1. Market Concentration Across Global Linear Polymer Industry 2.2.2. Competitive Intensity Among Leading Polymer Manufacturers 2.2.3. Integrated Petrochemical-to-Polymer Competitive Advantages Analysis 2.2.4. Competitive Positioning Strategies Across Major Producers 2.2.5. Entry Barriers Facing New Polymer Industry Participants 2.2.6. Oil and Gas Application Expertise Across Competitors 2.3. Linear Polymer Company Market Share and Positioning Analysis 2.3.1. Revenue-Based Market Share Comparison Across Leading Companies 2.3.2. Market Share Distribution Across Major Polymer Types 2.3.3. Plastics Application Positioning Across Key Industry Participants 2.3.4. Oil and Gas Application Positioning Across Leading Companies 2.3.5. Engineering Material Positioning Across Major Polymer Producers 2.3.6. Regional Market Share Comparison Across Leading Manufacturers 2.4. Linear Polymer Strategic Initiatives and Expansion Strategies 2.4.1. Mergers and Acquisitions Shaping Global Competitive Landscape 2.4.2. Polymer Production Capacity Expansion Across Strategic Markets 2.4.3. New Manufacturing Facilities Supporting Regional Market Expansion 2.4.4. Petrochemical Integration Supporting Polymer Production Competitiveness 2.4.5. Geographic Expansion Across Emerging Polymer Consumption Markets 2.4.6. Oil and Gas Application Market Expansion Strategies 2.4.7. Strategic Partnerships Supporting Technology and Market Development 2.5. Linear Polymer Product Portfolio and Application Benchmarking 2.5.1. Comparative Linear Polymer Product Portfolio Across Manufacturers 2.5.2. Commodity Plastic Product Portfolio Comparison Across Companies 2.5.3. Engineering Plastic Product Portfolio Benchmarking Across Competitors 2.5.4. Oil and Gas Material Portfolio Comparison 2.5.5. Pipeline and Flowline Material Portfolio Assessment 2.5.6. Coating and Lining Material Portfolio Benchmarking 2.5.7. High-Performance Polymer Grade Portfolio Comparison 2.6. Oil and Gas Application Capability Benchmarking Analysis 2.6.1. Upstream Oil and Gas Application Portfolio Comparison 2.6.2. Midstream Pipeline Material Solutions Across Leading Companies 2.6.3. Downstream Refinery Polymer Application Portfolio Comparison 2.6.4. Offshore and Subsea Material Solutions Benchmarking 2.6.5. Pipe and Flowline Material Capability Across Manufacturers 2.6.6. Polymer Coating and Lining Technology Comparison 2.6.7. Sealing and Gasket Material Portfolio Benchmarking 2.7. Linear Polymer Technology Leadership and R&D Investment 2.7.1. Research and Development Investment Trends Across Companies 2.7.2. Patent Portfolio and Polymer Technology Development Analysis 2.7.3. Polymerization Technology Leadership Across Major Manufacturers 2.7.4. Engineering Material Innovation Across Leading Polymer Producers 2.7.5. Oil and Gas Material Innovation Across Industry Participants 2.7.6. Advanced Compounding Technology Development Across Leading Companies 2.8. Company Profile: 30+ Key Players 2.8.1. Overview 2.8.2. Business Portfolio 2.8.3. Financial Overview 2.8.4. SWOT Analysis 2.8.5. Strategic Analysis 2.8.6. Recent Developments 2.8.7. North America 2.8.7.1. Dow Inc. 2.8.7.2. ExxonMobil Chemical Company 2.8.7.3. LyondellBasell Industries N.V. 2.8.7.4. Chevron Phillips Chemical Company LLC 2.8.7.5. DuPont de Nemours, Inc. 2.8.7.6. Westlake Chemical Corporation 2.8.7.7. Celanese Corporation 2.8.7.8. Others 2.8.8. Europe 2.8.8.1. BASF SE 2.8.8.2. INEOS Group Holdings S.A. 2.8.8.3. Evonik Industries AG 2.8.8.4. Covestro AG 2.8.8.5. Arkema S.A. 2.8.8.6. Solvay S.A. 2.8.8.7. Borealis AG 2.8.8.8. TotalEnergies SE 2.8.8.9. Repsol S.A. 2.8.8.10. Versalis S.p.A. 2.8.8.11. Others 2.8.9. Asia Pacific 2.8.9.1. LG Chem Ltd 2.8.9.2. Formosa Plastics Corporation 2.8.9.3. Prime Polymer Co., Ltd. 2.8.9.4. Mitsui Chemicals, Inc. 2.8.9.5. Idemitsu Kosan Co., Ltd. 2.8.9.6. Mitsubishi Chemical Group Corporation 2.8.9.7. Lotte Chemical Corporation 2.8.9.8. Hanwha Solutions Corporation 2.8.9.9. Reliance Industries Limited 2.8.9.10. China Petroleum & Chemical Corporation 2.8.9.11. PetroChina Company Limited 2.8.9.12. Indorama Ventures Public Company Limited 2.8.9.13. Petronas Chemicals Group Berhad 2.8.9.14. Others 2.8.10. South America 2.8.10.1. Braskem S.A. 2.8.10.2. Others 2.8.11. Middle East & Africa 2.8.11.1. SABIC — Saudi Aramco holds majority stake 2.8.11.2. Sasol Limited 2.8.11.3. Qatar Petrochemical Company 2.8.11.4. Borouge plc 2.8.11.5. Others 3. Key Insights, Strategic Outlook & Methodological Framework 3.1. Key Findings 3.2. Strategic Moves & Industry Outlook 3.3. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements