Lignin Market By Product Type, By Feedstock Source, By Form, By Grade, By Application and Regional Insights 2034

2.37%
CAGR (2026-2034)
1072.51 USD Mn.
Forecast Market Size
312
Report Pages
144
Market Tables

Overview

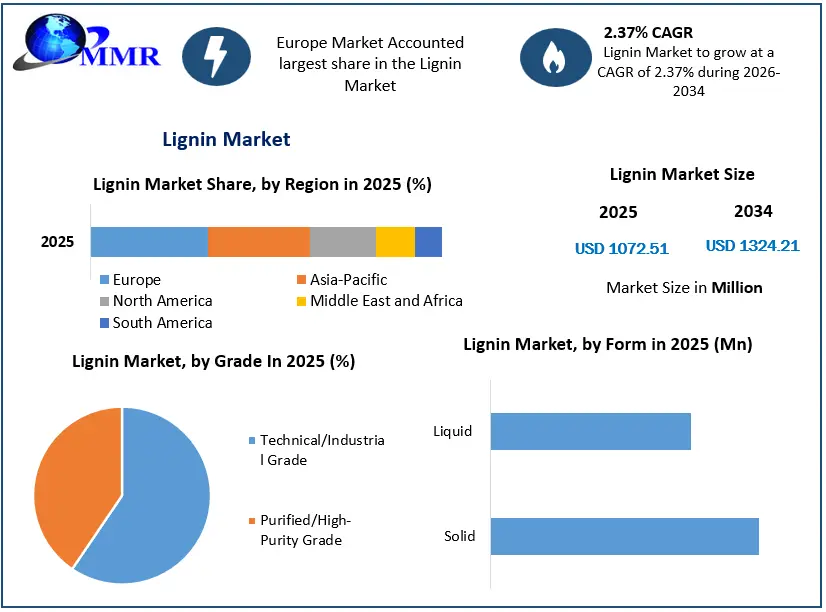
The Lignin Market size was valued at USD 1072.51 Million in 2025 and the total Lignin revenue is expected to grow at a CAGR of 2.37% from 2026 to 2034, reaching nearly USD 1324.21 Million.

Lignin is the second most abundant component in typical biomass, which has the unusual property of being one of the few sources of aromatic compounds that are not petroleum. Lignin is a key renewable resource for the chemical industry and the main byproduct of lignocellosic bio-refineries. Plant lignin has a lot of potentials to be converted into value-added products that can greatly boost bio-profitability. Over the forecast period of 2026 to 2034, an increase in the demand for lignin as an organic additive is expected to propel market growth.

The lignin market is being driven by continuing research and development efforts. Thanks to the soaring demand from numerous end-use industries, the lignin market is growing favorably. In developing economies, market growth is accelerated for many reasons, including rapid urbanisation, ongoing infrastructural development, industrial growth, and technical improvement. However, it is expected that a lack of awareness and technological constraints will impede industry growth.

Lignin Market Report Scope:

The report provides a comprehensive analysis of the global Lignin Market. The report estimates the Lignin Market, in terms of USD value from 2026 to 2034, base year is 2025. The report includes the major factors that are driving and hampering the growth of the lignin market across the globe. The report includes a thorough segmental analysis based on product type and application. An in-depth understanding of the potential of the lignin market may be gained from a regional examination of the supply chain, corporate operations, and market value. In addition, there is a separate section on the market structure. The section offers a thorough analysis of the major industry participants and their plans for growth in the world lignin market.

Lignin Market Growth and Share Analysis
Lignin Market Growth

To know about the Research Methodology:-Request Free Sample Report

Lignin Market Key Dynamics:

The increased use of fossil fuels for many purposes, including the production of chemicals and transportation fuels, has accelerated their rapid depletion. Currently, fossil fuels account for around 80% of the production of chemicals. There is an urgent need for an alternative source to create energy and chemicals because these resources are scarce. The most promising renewable carbon source today is lignocellulosic biomass, which can provide energy in the form of biofuel and value-added chemicals.

More than 70 million tons of lignin per year are produced industrially, and only a tiny portion (1–2%) is used. Because it is polyaromatic, lignin is a proven source of many value-added chemicals. As result, the adoption of lignin from several industries is expected to boost the lignin market growth across the globe.

Diverse Applications of Lignin

The usage of lignin and its byproducts as concrete additives in the form of dyes, dust suppressants, etc. is very common. Glass wool building insulation is bound with lignin. It enhances the effectiveness of asphalt dye. During the forecast period, growth and advancement in industries including agriculture, animal feed, and concrete are expected to boost the market growth. The profitable availability of a wide variety of animal feed is thus increasing demand for lignin. In addition, growing uses for industrial cleansers, industrial dyes, batteries, and water treatment are some of the elements influencing lignin's increased sales across the globe.

Growing Adoption of Lignin across the Globe

Thanks to the increase in chicken meat consumption across the globe, lignin will become more and more in demand for animal feed applications. For instance, according to the U.S. Department of Agriculture (USDOA) world is expected to produce 100.8 million tonnes of chicken meat by the end of 2025. This shows that suitable feed elements like lignin are widely used in animal feed, with advantages like a high energy source.

Governments and corporate investors are increasing their investments to create a public infrastructure that is environmentally friendly. This covers both industrialised and developing economies' railways, roads, and other transportation modalities. For instance, as stated in its Union Budget for 2020–21, the Government of India planned to invest more than USD 6.5 billion in the building of roads and bridges. Such activities would encourage the use of lignin, which is employed in the building industry as a water-reducing additive and an efficient cement substitute.

Growing Adoption of Lignin in the Pharmaceutical Industry

The pharmaceutical Industry is one of the key industry drivers boosting the compound demand. A robust pace of growth is being experienced in the medical industry as a result of the rising global burden of chronic diseases. Due to its low cost and use in a variety of medicinal requirements, including goods for skin disinfection and itch relief, it has raised the demand for phenol-based products from the pharmaceutical industry.

The growing use of Lignin in Concrete Additives

During the forecast period, it is expected that increased demand for lignin in building and construction applications will propel the market. Lignin is being employed more frequently in the building and construction sector. During the forecast period, the demand for lignin as a dispersant in concrete additives will be driven by the construction of infrastructure in both developed and emerging nations. Lignin is more widely used as architects and construction designers incorporate them into their plans. In addition, the lignin market is anticipated to grow during the forecast period due to manufacturers' increased focus on creating, selling, and developing lignin for a number of uses in the building & construction sector.

Lack of Awareness and Research

The growth of the lignin market is expected to be hampered by industrial and commercial end-users lack of knowledge about the benefits and uses of lignin. Lignin is used in a wide range of industries, from chemicals to food and beverage. However, a dearth of studies into the potential uses for this substance could somewhat restrain demand in the years to come. Despite these issues, a steady increase in infrastructure spending and a high demand for animal feed will present prospects for lignin suppliers across the globe.

Lignin Market Key Insights

It is expected that the growing trend of burning lignin for usage in dispersants, binders, and adhesives will accelerate market growth through the forecast period. The demand for lignin is expected to be supported on a macro level by elements like rising construction spending and increasing demand for autos, electronics, and equipment manufacture.

Many market participants offer full service for lignin and its uses. For instance, Nippon Paper manufactures paper and pulp and obtains lignin from the pulping procedure. The business also runs industrial plantations and cultivates forests.

Lignin Market Segment Overview:

By Product, the Lignin Market is segmented into Kraft Lignin, Lignosulphonates, Low Purity Lignin, and Others. The Lignosulphonates segment held the largest market share accounting for 71.23% in 2025. Lignisulfonates are used in the oil and gas sector to regulate the viscosity of drilling mud for deep oil wells. Lignisulfonates are also employed in the creation of ceramics' smooth clay slips. As a result, over the forecast period, there will be an increase in demand for lignosulfonates lignin due to the aforementioned considerations.

The Kraft Lignin segment is expected to grow at a significant CAGR of xx% through the forecast period. As a foam in fire extinguishers and printing inks for high-speed rotary presses, kraft lignin is extensively used. High-grade activated charcoal is also produced using kraft lignin. The demand for lignin is expected to increase over the forecast period as a result of its inventive uses in so many different sectors of the economy.

The low-purity lignin segment is expected to grow more than 5% CAGR through the forecast period. The demand for renewable feedstocks, such as biomass is growing at a significant pace as customers are increasing their preference for eco-friendly fuels. According to the U.K. government’s statistics, in 2020, the total volume of locally sourced biofuels used in the region reached 293 million liters/kilogram, a 5% increase from the 2019 figures. Low-purity lignin is used as a biofuel owing to its ability to generate more energy while burning, as compared to cellulose.

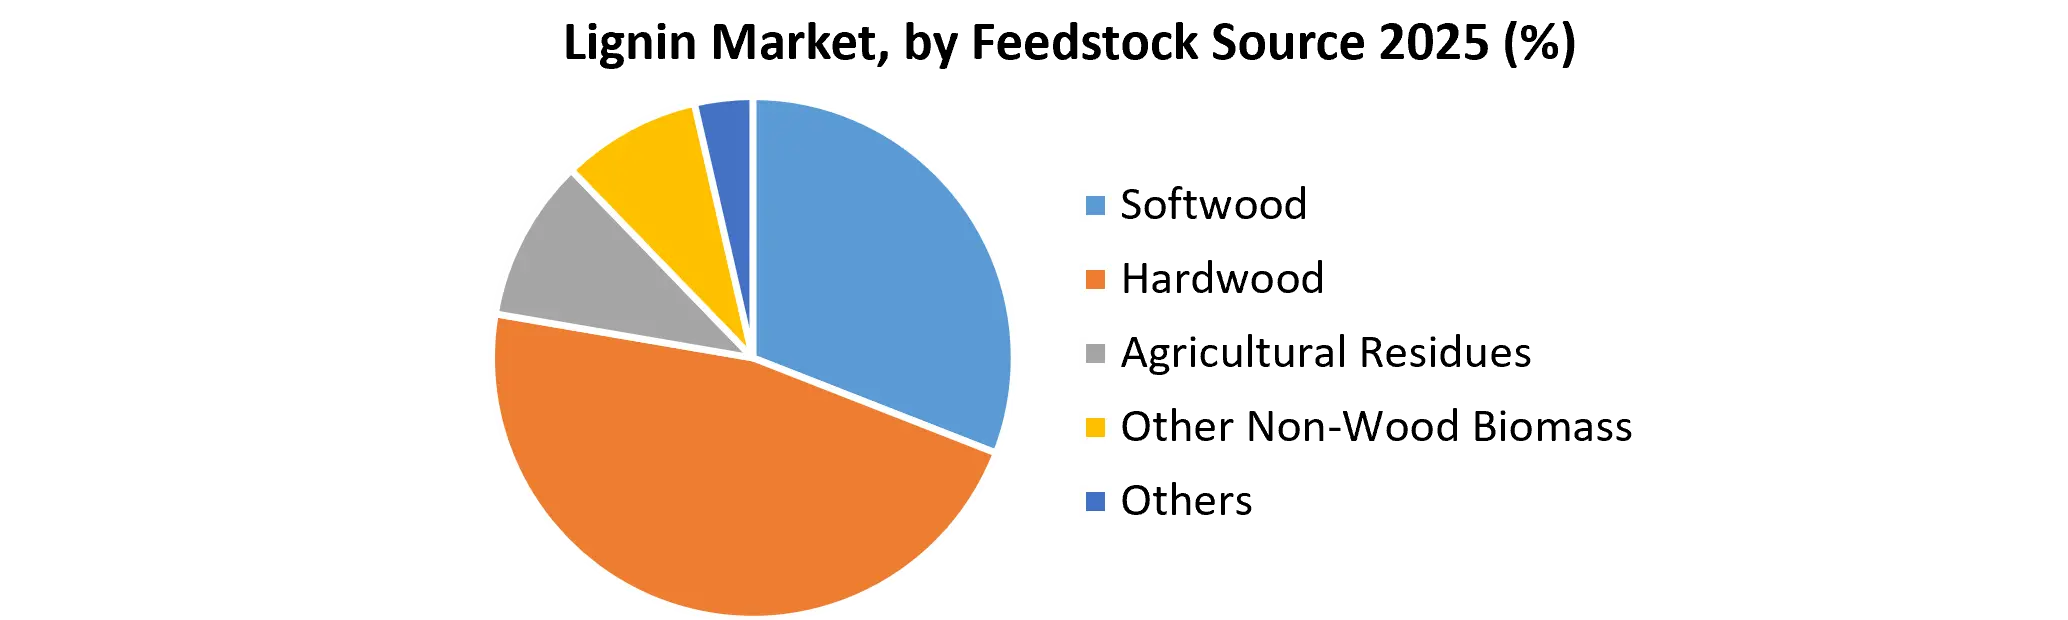
By Feedstock Source, the Lignin Market is segmented into Hardwood, Softwood, Agricultural Residues, Other Non-Wood Biomass. The Hardwood segment held the largest market share in 2025. Hardwood lignin is used to make a variety of adhesives since it has a high concentration of S-lignin units and a low molecular weight. Given that this kind of lignin is produced from leftover plant materials that remain after harvesting, it can serve as a useful substitute for adhesives that are based on petrochemicals. By effectively using biowaste, it harms the environment as little as possible.
Lignin Market, by Feedstock Source

By Application, the Lignin Market is segmented into Aromatics and Macromolecules. The Macromolecules segment dominated the market share accounting for 58.63% in 2025. It is expected that the importance of macromolecules will expand as carbon fibers become more widely used as lightweight materials in the construction and automobile industries. The macromolecules are further processed to create carbon fibers, carbon, biofuels, bitumen, catalysts for bio-refineries, and activated carbon. Carbon fibers are becoming more and more common as the aerospace and automobile production industries require lighter materials. In addition, rising demand for lightweight vehicles is anticipated due to their improved durability and performance.

Companies that produce polymers have been forced to boost their efforts in the research and development of organically derived raw materials due to strict laws designed to enhance awareness of the benefits of earning carbon credits and decreasing greenhouse gas emissions. The production of phenol, phenolic resins, vanillin, and BTX is thus expected to employ lignin as an intermediary. Growing public concern over GHG emissions has increased demand for items made of bio-based polymers. During the forecast period, lignin is expected to experience increased demand for the manufacturing of aromatics. The chemical industry is expected to continue to advance, which will further boost the market.

Lignin Market Regional Insights:

In 2025, Europe dominated the market with the largest market share, followed by North America. It is expected that Europe’s dominance will continue both in terms of volume and value during the forecast period. Europe has stringent laws governing the emission of greenhouse gases, which may open up new markets for the production of bio-based polymers. Growth in these regional lignin markets is being positively impacted by rising demand for lightweight automotive materials and bio-based materials in nations like Germany, France, and the Netherlands.

Asia Pacific is expected to grow at a rapid rate through the forecast period. The region’s growth is attributed to an increase in demand for lignin in a number of applications, including dyes, animal feed, and concrete additives. The region's market is being driven by the sharp increase in demand for lignin in the building and construction and steel industries. China is expected to rule the lignin market in the Asia Pacific region. Value-grab possibilities are being created by the profitable presence of manufacturers operating in the Asia-Pacific region.

Lignin Market Recent Industry Developments

Exact Date Company Development Impact
11 February 2026 UFZ (Helmholtz Centre) The organization presented a lignin-to-adipic acid conversion process at the BIC Matchmaking Event to produce bio-based nylon from industrial residues. This development accelerates the commercialization of lignin-containing residues as a viable alternative to petroleum-based monomers in the textile and plastics markets.
05 January 2026 Ingevity Corporation The company completed the sale of its North Charleston refinery assets while retaining its lignin-based dispersant and pavement technologies product lines. The restructuring allows the company to sharpen its focus on higher-margin specialty lignin applications and sustainable infrastructure materials.
22 January 2026 Stora Enso Research findings were published detailing the integration of lignin-derived hard carbon into lithium-ion batteries to achieve over 1000 stable cycles. The milestone establishes a scalable, low-carbon pathway for energy storage, reducing dependency on synthetic graphite and mined minerals.
01 November 2025 UPM Biochemicals The company successfully ramped up its wood-to-lignin biorefinery in Leuna, Germany, completing the first commercial deliveries of bio-based industrial sugars. This operational success ensures the full-scale production of lignin-based functional fillers for the automotive and rubber industries starting in 2026.
14 May 2025 UPM Biochemicals The company introduced UPM Circular Renewable Black™, a carbon-negative pigment derived from renewable lignin that is fully NIR-detectable for recycling. The product provides a sustainable alternative to carbon black, enabling brands to improve packaging circularity and reduce their carbon footprint.
04 February 2026 Borregaard The company reported record performance in its bio-based niche segments, confirming an expansion investment strategy for advanced lignin derivatives. Strong financial results support increased R&D spending to penetrate high-value markets like pharmaceuticals and agrochemicals.

Lignin Market Scope: Inquire before buying

Lignin Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 1072.51 USD Million
Forecast Period 2026-2034 CAGR: 2.37% Market Size in 2034: 1324.21 USD Million
Segments Covered: by Product Type Lignosulfonates
Kraft Lignin
Organosolv Lignin
Hydrolysis Lignin
Soda Lignin
Others
by Feedstock Source Softwood
Hardwood
Agricultural Residues
Other Non-Wood Biomass
Others
by Form Solid
Liquid
by Grade Technical/Industrial Grade
Purified/High-Purity Grade
Specialty/Functionalized Grade
by Application Concrete Additives & Construction Chemicals
Dispersants & Surfactants
Resins, Adhesives & Binders
Polymers & Bioplastics
    Polyurethane Products
    Thermoplastics & Composites
    Others
Carbon Fiber & Bio-Based Carbon Materials
Bio-Asphalt & Bitumen Modification
Fuels & Energy
Vanillin & Aromatic Chemicals
Animal Feed & Feed Additives
Others

Lignin Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Lignin Market Key Players:

North America

1. Ingevity Corporation
2. Domtar Corporation
3. Rayonier Advanced Materials
4. WestRock Company
5. The Dallas Group of America
6. Liquid Lignin Company
7. Sweetwater Energy
8. Weyerhaeuser Company
9. West Fraser
10. Resolute Forest Products

Europe

11. Borregaard
12. Stora Enso
13. UPM-Kymmene Corporation
14. Sappi
15. Domsjö Fabriker
16. Metsä Group
17. Burgo Group
18. Lignin Industries
19. MetGen
20. Lignolix
21. Vertoro
22. Valmet
23. RISE Research Institutes of Sweden
24. Boreal Bioproducts
25. SunCoal Industries

Asia Pacific

26. Nippon Paper Industries
27. Oji Holdings
28. Shandong Sun Paper Industry
29. Green Agrochem
30. Aditya Birla Group
31. JK Paper
32. ITC
33. Tamil Nadu Newsprint and Papers
34. West Coast Paper Mills
35. Andhra Pradesh Paper Mills
36. Nine Dragons Paper
37. Lee & Man Paper Manufacturing

South America

38. Suzano
39. Klabin
40. Arauco
41. CMPC
42. Eldorado Brasil Celulose
43. Bracell

Middle East & Africa

44. Mondi Group
45. Sappi
46. Nampak
47. Mufindi Paper Mills
48. Neopak
49. Mpact
Others

Frequently Asked Questions:

1. Which region has the largest share in Global Lignin Market?
Ans: Europe region held the highest share in 2025.

2. What is the growth rate of Global Lignin Market?
Ans: The Global Lignin Market is growing at a CAGR of 2.37 % during forecasting period 2026-2034.

3. What is scope of the Global Lignin Market report?
Ans: Global Lignin Market report helps with the PESTEL, PORTER, COVID-19 Impact analysis, Recommendations for Investors & Leaders, and market estimation of the forecast period.

4. What is the study period of this Market?
Ans: The Global Lignin Market is studied from 2020 to 2034.

Table of Contents

1. Executive Market Landscape and Industry Overview 1.1. Global Lignin Market Size (Value USD Million & Volume in Metric Tons), 2025–2034 1.2. Historical Development of Commercial Lignin Production Across Major Wood Markets 1.3. Hardwood and Softwood Lignin Production Trends and Market Development 1.4. Lignin Demand Growth Across Pulp, Paper, and Wood Processing 1.5. Emerging Lignin Applications Across Chemicals, Materials, and Industrial Processing 1.6. Global Lignin Market Forecast and Structural Growth Opportunities Through 2034 2. Lignin Market Dynamics 2.1. Lignin Market Trends 2.2. Lignin Market Dynamics 2.3. Drivers 2.4. Restraints 2.5. Opportunities 2.6. Challenges 2.7. PORTER’s Five Forces Analysis 2.8. PESTLE Analysis 3. Lignin Pricing Structure and Value Chain Profitability Assessment 3.1. Global Lignin Production Cost Structure Across Wood Processing Facilities 3.2. Raw Material Costs Influencing Commercial Lignin Production and Pricing 3.3. Chemical, Energy, and Processing Costs Affecting Lignin Economics 3.4. Purification and Functionalization Costs Influencing Specialty Lignin Product Margins 3.5. Premium Pricing Based on Lignin Purity, Reactivity, and Functionality 3.6. Value Chain Profitability Across Lignin Producers and Industrial Consumers 4. Lignin Raw Materials, Suppliers, and Production Ecosystem 4.1. Wood Feedstock Supply Supporting Global Commercial Lignin Production 4.2. Hardwood and Softwood Raw Material Characteristics Influencing Lignin Chemistry 4.3. Pulp Mill Supply Systems Supporting Continuous Lignin Recovery Operations 4.4. Chemical Suppliers Supporting Lignin Extraction, Purification, and Modification 4.5. Wood Biorefinery Integration Supporting Sustainable Lignin Production Development 4.6. Raw Material Security and Supplier Diversification Across Lignin Markets 5. Lignin Production, Sales, and Demand Development 5.1. Global Lignin Production Across Major Commercial Lignin Product Categories 5.2. Kraft Lignin Production, Sales, and Industrial Demand Development 5.3. Lignosulfonate Production and Demand Across Paper and Industrial Applications 5.4. Specialty Lignin Demand Across High-Value Chemical and Material Applications 5.5. Industrial Lignin Purchasing Preferences Based on Quality and Performance 5.6. Regional Lignin Supply and Demand Development Across Major Markets 6. Lignin Chemistry and Wood Chemistry Evolution 6.1. Chemical Composition of Wood and Structural Characteristics of Lignin 6.2. Cellulose, Hemicellulose, and Lignin Distribution Within Wood Cell Walls 6.3. Guaiacyl, Syringyl, and p-Hydroxyphenyl Units Within Wood Lignin 6.4. Hardwood and Softwood Lignin Structure, Composition, and Reactivity Differences 6.5. Lignin Functional Groups, Chemical Bonds, and Molecular Characteristics 6.6. Advances in Wood Chemistry Supporting Lignin Characterization and Applications 7. Lignin Extraction and Separation Technology Development 7.1. Kraft Pulping Processes Supporting Commercial Lignin Extraction and Recovery 7.2. Sulfite Pulping Processes Supporting Lignosulfonate Production and Recovery 7.3. Soda Pulping Technologies for Lignin Extraction From Wood Feedstocks 7.4. Organosolv Fractionation Technologies Producing High-Purity Wood-Derived Lignin 7.5. Emerging Biorefinery Technologies Supporting Selective Lignin Fractionation Processes 7.6. Green Extraction Technologies Improving Lignin Recovery and Product Quality 8. Lignin Modification and Functionalization Market Development 8.1. Chemical Modification Technologies Improving Lignin Reactivity and Functional Performance 8.2. Oxidation, Reduction, and Depolymerization Processes for Lignin Valorization 8.3. Lignin Functionalization for Resins, Adhesives, Coatings, and Polymers 8.4. Enzymatic and Biological Modification of Wood-Derived Lignin Components 8.5. Functionalized Lignin Development for Specialty Chemical and Material Applications 8.6. Advanced Lignin Modification Technologies Supporting Higher-Value Product Development 9. Lignin-Based Chemicals and Material Development 9.1. Lignin-Derived Aromatic Chemicals and High-Value Product Development 9.2. Phenolic Chemical Production Through Controlled Lignin Depolymerization Processes 9.3. Lignin-Based Resins, Polyurethanes, and Polymer Material Development 9.4. Lignin-Based Adhesives and Coating Materials for Paper Applications 9.5. Carbon Materials and Fibers Produced From Lignin Precursors 9.6. Emerging Lignin-Derived Chemicals Supporting Advanced Wood-Based Material Applications 10. Lignin Applications and End-Use Development 10.1. Global Lignin Applications Across Chemical, Paper, and Wood Industries 10.2. Lignosulfonates in Paper Processing, Concrete, and Industrial Formulations 10.3. Lignin-Based Binders, Adhesives, Resins, and Coating Applications 10.4. Lignin Applications in Agriculture, Fertilizers, and Soil Conditioning 10.5. Lignin-Based Carbon Materials for Energy and Advanced Applications 10.6. Emerging Lignin Applications Across Specialty Chemicals and Functional Materials 11. Lignin Integration Within Pulp and Paper Industries 11.1. Pulp Mills as Major Sources of Commercially Recoverable Lignin 11.2. Kraft Lignin Recovery From Black Liquor Processing Systems 11.3. Sulfite Pulping Integration With Commercial Lignosulfonate Production 11.4. Lignin Separation Technologies Supporting Pulp Mill Resource Efficiency 11.5. Lignin Recovery Economics Versus Internal Energy Recovery Requirements 11.6. Lignin Utilization Opportunities Across Paper, Board, and Coating Applications 12. Lignin Biorefinery and Biomass Valorization Development 12.1. Global Wood Biorefinery Development and Commercialization Trends 12.2. Fractionation of Wood Biomass Into Cellulose, Hemicellulose, and Lignin 12.3. Integrated Biorefinery Processes Maximizing Wood Component Value Recovery 12.4. Lignin Valorization Within Circular Wood Biomass Processing Systems 12.5. Biorefinery Economics Supporting Commercial Lignin Product Development 12.6. Future Integrated Wood Biorefinery Opportunities Across Emerging Markets 13. Lignin Aftermarket, Recovery, and Secondary Processing Demand 13.1. Global Demand for Purified and Upgraded Lignin Products 13.2. Lignin Reprocessing and Purification Requirements for Industrial Applications 13.3. Specialty-Grade Lignin Recovery for High-Performance Material Applications 13.4. Secondary Lignin Processing for Improved Purity and Functional Performance 13.5. Product Standardization Supporting Consistent Downstream Lignin Application Development 13.6. Revenue Opportunities From Higher-Value Upgraded Lignin Products 14. Lignin Investment Trends and Capital Allocation Analysis 14.1. Investment Trends Across Global Lignin Producers and Biorefineries 14.2. Capital Expenditure for Commercial Lignin Recovery and Processing Facilities 14.3. Investment in Lignin Purification, Modification, and Fractionation Technologies 14.4. Strategic Investment in Lignin-Based Chemicals, Coatings, and Materials 14.5. Research Investment Supporting Advanced Wood Chemistry and Lignin Applications 14.6. Future Investment Opportunities Across Lignin Valorization and Biorefinery Technologies 15. Lignin Research, Innovation, and Technology Development 15.1. Global Lignin Research Across Universities, Laboratories, and Industrial Organizations 15.2. Advanced Analytical Techniques for Wood Lignin Structural Characterization 15.3. Research on Lignin Depolymerization and Aromatic Chemical Production 15.4. Innovation in Lignin-Based Polymers, Resins, Adhesives, and Coatings 15.5. Biotechnology Applications Supporting Lignin Conversion and Wood Component Valorization 15.6. Future Research Directions in Wood Chemistry and Lignin Science 16. Hardwood and Softwood Lignin Chemistry Development 16.1. Hardwood Lignin Composition Across Commercially Important Wood Species 16.2. Softwood Lignin Composition Across Commercially Important Wood Species 16.3. Syringyl-to-Guaiacyl Ratios Influencing Hardwood Lignin Reactivity and Processing 16.4. Guaiacyl-Dominant Structures Influencing Softwood Lignin Chemical Behavior 16.5. Species Differences Affecting Lignin Extraction, Modification, and Applications 16.6. Wood Species Selection for Targeted Lignin Chemistry and Performance 17. Lignin Analytical Characterization and Quality Assessment 17.1. Global Lignin Characterization Methods and Quality Assessment Practices 17.2. Molecular Weight Distribution and Structural Property Analysis of Lignin 17.3. Functional Group Analysis Supporting Lignin Processing and Application Development 17.4. Spectroscopic Techniques for Detailed Wood Lignin Structural Characterization 17.5. Thermal and Chemical Stability Assessment of Commercial Lignin 17.6. Quality Parameters Influencing Lignin Processing, Performance, and Application Consistency 18. Lignin Environmental, Sustainability, and Circular Economy Development 18.1. Lignin Contribution to Sustainable Wood-Based Chemical Production 18.2. Carbon Reduction Opportunities Through Lignin-Based Material Substitution 18.3. Lignin Recovery Supporting Circular Economy Development Within Pulp Mills 18.4. Bio-Based Chemical Production From Renewable Wood-Derived Lignin Feedstocks 18.5. Waste Reduction Through Lignin Valorization and Wood Resource Recovery 18.6. Circular Economy Opportunities Across Global Wood Processing Industries 19. Lignin Sustainability and Green Chemistry Development 19.1. Green Chemistry Principles Supporting Sustainable Lignin Processing Development 19.2. Low-Chemical and Low-Energy Technologies for Lignin Extraction 19.3. Renewable Wood Feedstocks Supporting Sustainable Lignin Production 19.4. Lignin-Based Alternatives to Fossil-Derived Aromatic Chemical Feedstocks 19.5. Life-Cycle Assessment of Lignin Recovery and Valorization Processes 19.6. Sustainable Chemistry Opportunities Across Lignin-Based Chemical and Material Industries 20. Lignin Digitalization and Advanced Process Technologies 20.1. Digital Process Monitoring Across Commercial Lignin Production Facilities 20.2. Artificial Intelligence Supporting Lignin Process Optimization and Quality Control 20.3. Advanced Sensors for Real-Time Lignin Composition and Quality Monitoring 20.4. Digital Modeling of Lignin Extraction and Fractionation Processes 20.5. Automation Technologies Improving Lignin Recovery and Processing Efficiency 20.6. Data-Driven Optimization of Lignin Product Development and Manufacturing 21. Lignin Regulatory Framework and Government Support 21.1. Global Regulatory Frameworks Governing Commercial Lignin Production and Applications 21.2. Chemical Safety Requirements for Industrial Lignin Products 21.3. Environmental Regulations Affecting Wood Processing and Lignin Recovery Facilities 21.4. Standards Governing Lignin Quality, Composition, and Industrial Applications 21.5. Government Incentives Supporting Bio-Based Chemical and Wood Material Development 21.6. Regulatory Comparison Across Major Global Lignin-Producing Markets 22. Lignin Distribution, Marketing, and Commercial Development 22.1. Global Lignin Distribution Networks Across Major Industrial Markets 22.2. Direct Producer-to-Industrial Buyer Lignin Sales Development 22.3. Specialty Chemical Distribution Channels Supporting Lignin Market Expansion 22.4. Distribution Channels Serving Paper, Board, Coating, and Chemical Industries 22.5. Distributor Partnerships Supporting Regional Lignin Market Development 22.6. Future Commercial Models for Global Lignin Product Distribution 23. Global Lignin Market: Market Size and Forecast by Segmentation (By Value in USD Million & Volume in Metric Tons), 2025–2034 23.1. Global Lignin Market Size and Forecast, By Product Type 23.1.1. Lignosulfonates 23.1.2. Kraft Lignin 23.1.3. Organosolv Lignin 23.1.4. Hydrolysis Lignin 23.1.5. Soda Lignin 23.1.6. Others 23.2. Global Lignin Market Size and Forecast, By Feedstock Source 23.2.1. Softwood 23.2.2. Hardwood 23.2.3. Agricultural Residues 23.2.4. Other Non-Wood Biomass 23.2.5. Others 23.3. Global Lignin Market Size and Forecast, By Form 23.3.1. Solid 23.3.2. Liquid 23.4. Global Lignin Market Size and Forecast, By Grade 23.4.1. Technical/Industrial Grade 23.4.2. Purified/High-Purity Grade 23.4.3. Specialty/Functionalized Grade 23.5. Global Lignin Market Size and Forecast, By Application 23.5.1. Concrete Additives & Construction Chemicals 23.5.2. Dispersants & Surfactants 23.5.3. Resins, Adhesives & Binders 23.5.4. Polymers & Bioplastics 23.5.4.1. Polyurethane Products 23.5.4.2. Thermoplastics & Composites 23.5.4.3. Others 23.5.5. Carbon Fiber & Bio-Based Carbon Materials 23.5.6. Bio-Asphalt & Bitumen Modification 23.5.7. Fuels & Energy 23.5.8. Vanillin & Aromatic Chemicals 23.5.9. Animal Feed & Feed Additives 23.5.10. Others 23.6. Global Lignin Market Size and Forecast, By Region 23.6.1. North America 23.6.2. Europe 23.6.3. Asia Pacific 23.6.4. Middle East and Africa 23.6.5. South America 24. Competitive Landscape 24.1. MMR Competition Matrix 24.2. Competitive Positioning of Leading Lignin Manufacturers [Revenue and Market Share (%)] 24.3. Key Players Benchmarking 24.4. Company Name 24.5. Headquarters 24.6. Lignin Product Portfolio 24.7. Lignin Types and Production Technologies 24.8. Wood and Biomass Feedstock Sources 24.9. Production Capacity (000' Tons) 24.10. Market Share (%) (2025) 24.11. R&D Investment 24.12. Revenue (2025) 24.13. Revenue Growth Rate (Y-O-Y) 24.14. Profit Margin (%) 24.15. Sales Channels 24.16. Geographical Presence 24.17. Production Facilities 24.18. End-Use Industry Coverage 24.19. Product Quality and Purity 24.20. Certifications 24.21. Sustainability and ESG Positioning 24.22. Market Structure 24.23. Market Leaders 24.24. Market Followers 24.25. Emerging Players 24.26. Recent Key Developments 24.27. Sustainability & ESG Positioning 25. Competitive Landscape and Industry Structure Analysis 25.1. Market Concentration Across the Global Lignin Industry 25.2. Competitive Positioning Across Kraft, Lignosulfonate, Soda, and Organosolv Lignin 25.3. Competitive Differentiation Across Hardwood, Softwood, and Non-Wood Lignin Sources 25.4. Lignin Product Portfolio Breadth and Application Coverage Comparison 25.5. Lignin Purity, Molecular Weight, and Chemical Property Comparison 25.6. Extraction Technology and Production Process Differentiation 25.7. Lignin Modification and Functionalization Technology Positioning 25.8. High-Value Lignin Chemical and Material Application Positioning 25.9. Pulp Mill Integration and Raw Material Supply Relationships 25.10. Sustainability, Renewable Feedstock, and Circularity Positioning 26. Company Market Share and Positioning Analysis (2024–2025) 26.1. Revenue-Based Market Share Comparison Across Leading Lignin Companies 26.2. Global Market Positioning Across Major Lignin Manufacturers 26.3. Kraft Lignin Market Positioning 26.4. Lignosulfonate Market Positioning 26.5. Soda and Organosolv Lignin Market Positioning 26.6. Hardwood and Softwood Lignin Market Positioning 26.7. Specialty and High-Purity Lignin Market Positioning 26.8. Lignin-Based Chemical and Material Application Positioning 26.9. Production Capacity and Manufacturing Footprint Positioning 26.10. Geographical Market Presence and Regional Strength Positioning 26.11. Brand Strength and Industrial Customer Recognition Positioning 27. Strategic Initiatives and Expansion Strategy Analysis 27.1. Lignin Production Capacity Expansion Across Global Markets 27.2. Regional Lignin Production and Manufacturing Facility Expansion 27.3. Expansion of Specialty and High-Purity Lignin Product Lines 27.4. Development of Advanced Lignin Extraction and Fractionation Technologies 27.5. Development of Lignin Depolymerization and Valorization Technologies 27.6. Expansion of Lignin-Based Chemical and Material Applications 27.7. Regional Market Expansion and Distribution Network Development 27.8. Mergers, Acquisitions, Joint Ventures, and Strategic Investments 28. Financial Performance and Profitability Benchmarking 28.1. Revenue Growth Trends Across Leading Lignin Companies 28.2. Profit Margin Analysis Across Leading Lignin Manufacturers 28.3. Lignin Revenue Contribution Across Diversified Chemical Companies 28.4. Kraft Lignin Revenue Contribution Analysis 28.5. Lignosulfonate Revenue Development 28.6. Specialty Lignin Revenue Contribution 28.7. Lignin-Based Chemical Revenue Development 28.8. Lignin-Based Material Revenue Contribution 28.9. Impact of Pulp Prices, Energy Costs, and Raw Materials on Financial Performance 29. Innovation Leadership and R&D Investment Analysis 29.1. Research and Development Investment Across Leading Lignin Companies 29.2. Advanced Lignin Extraction and Fractionation Innovation Trends 29.3. High-Purity Lignin Production Technology Development 29.4. Lignin Depolymerization and Aromatic Chemical Development 29.5. Lignin Functionalization and Chemical Modification Innovation 29.6. Lignin-Based Polymer and Resin Technology Development 29.7. Lignin-Based Carbon Fiber and Carbon Material Innovation 29.8. Lignin-Based Adhesive and Coating Technology Development 29.9. Lignin-Based Agricultural Product Innovation 29.10. Biological and Enzymatic Lignin Conversion Technology Development 29.11. Sustainable and Bio-Based Lignin Material Innovation 29.12. Digital Lignin Process Design, Testing, and Characterization Technologies 29.13. Future Product Pipeline and Emerging Lignin Technology Opportunities 30. Lignin Ecosystem, Technology Partnerships, and Strategic Collaboration Analysis 30.1. Lignin Manufacturer and Pulp Mill Partnerships 30.2. Lignin Producer and Biorefinery Relationships 30.3. Wood Processing and Forestry Industry Partnerships 30.4. Chemical and Specialty Material Supplier Relationships 30.5. Catalyst and Processing Technology Supplier Partnerships 30.6. Polymer, Resin, and Adhesive Manufacturer Partnerships 30.7. Construction Material and Concrete Industry Partnerships 30.8. Automotive and Advanced Material Industry Partnerships 30.9. Research Institution and University Collaboration Networks 30.10. Sustainable Material and Biomass Recycling Partnerships 30.11. Technology Partnerships for Lignin Characterization and Process Optimization 30.12. Strategic Collaborations Across Lignin Applications and End-Use Industries 30.13. Future Strategic Collaboration Opportunities Across the Global Lignin Ecosystem 31. Company and Organization Profiles (45+): Regional Analysis 31.1. Company Profiles: North America 31.1.1. Ingevity Corporation 31.1.2. Domtar Corporation 31.1.3. Rayonier Advanced Materials 31.1.4. WestRock Company 31.1.5. The Dallas Group of America 31.1.6. Liquid Lignin Company 31.1.7. Sweetwater Energy 31.1.8. Weyerhaeuser Company 31.1.9. West Fraser 31.1.10. Resolute Forest Products 31.2. Company Profiles: Europe 31.2.1. Borregaard 31.2.2. Stora Enso 31.2.3. UPM-Kymmene Corporation 31.2.4. Sappi 31.2.5. Domsjö Fabriker 31.2.6. Metsä Group 31.2.7. Burgo Group 31.2.8. Lignin Industries 31.2.9. MetGen 31.2.10. Lignolix 31.2.11. Vertoro 31.2.12. Valmet 31.2.13. RISE Research Institutes of Sweden 31.2.14. Boreal Bioproducts 31.2.15. SunCoal Industries 31.3. Company Profiles: Asia Pacific 31.3.1. Nippon Paper Industries 31.3.2. Oji Holdings 31.3.3. Shandong Sun Paper Industry 31.3.4. Green Agrochem 31.3.5. Aditya Birla Group 31.3.6. JK Paper 31.3.7. ITC 31.3.8. Tamil Nadu Newsprint and Papers 31.3.9. West Coast Paper Mills 31.3.10. Andhra Pradesh Paper Mills 31.3.11. Nine Dragons Paper 31.3.12. Lee & Man Paper Manufacturing 31.4. Company Profiles: South America 31.4.1. Suzano 31.4.2. Klabin 31.4.3. Arauco 31.4.4. CMPC 31.4.5. Eldorado Brasil Celulose 31.4.6. Bracell 31.5. Company Profiles: Middle East & Africa 31.5.1. Mondi Group 31.5.2. Sappi 31.5.3. Nampak 31.5.4. Mufindi Paper Mills 31.5.5. Neopak 31.5.6. Mpact 31.6. Other Companies 31.7. Standard Company Profile Assessment Framework 31.7.1. Company Overview 31.7.2. Business Portfolio 31.7.3. Financial Overview 31.7.4. SWOT Analysis 31.7.5. Strategic Analysis 31.7.6. Recent Developments 32. Key Findings 33. Strategic Moves & Industry Outlook 34. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements