India Gold Loan Market Size, Share, Growth Trends and Industry Analysis by Lender Provider Type, Mode of Disbursement, Customer Income, Loan Ticket Size, Loan Tenure, End-User, and Geography – Regional Market Insights, Market Potential, Revenue Analysis, Competitive Landscape, Key Players, Strategic Developments, Investment Opportunities and Forecast to 2034

12.3%
CAGR (2026-2034)
75.69 USD Bn.
Forecast Market Size
204
Report Pages
47
Market Tables

Overview

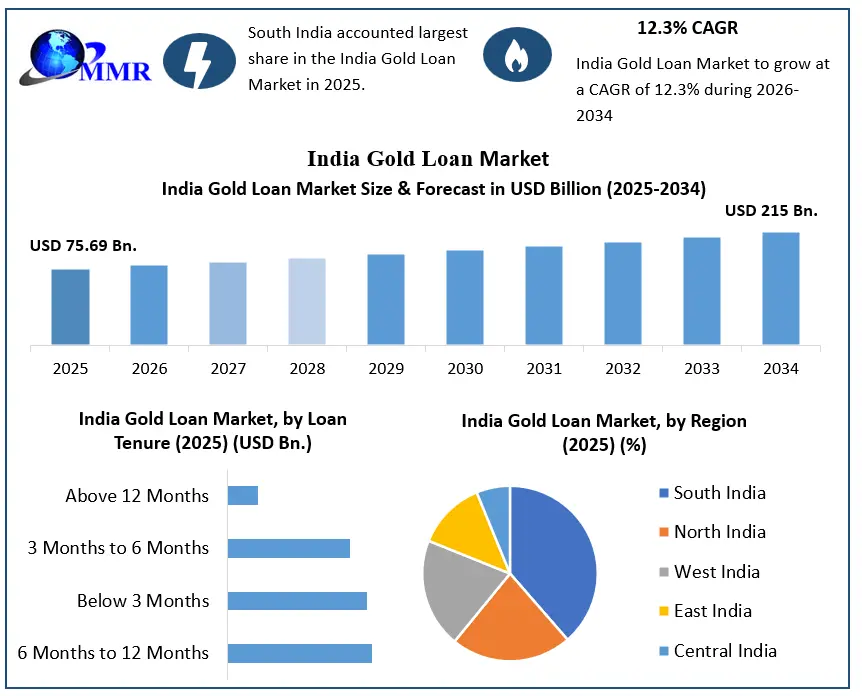
The India Gold Loan Market was valued at USD 75.69 Billion in 2025 and is projected to reach USD 215 Billion by 2034, growing at a CAGR of 12.3% during the forecast period 2026–2034.

India Gold Loan Market Overview:

A gold loan is a secured loan that uses gold jewellery as collateral. The lender holds the gold jewellery during the life of the loan, which typically lasts for 6 months to 1 year. The loan amount is based on the value of the gold jewellery, and the borrower pays interest on the loan amount. In the event of the borrower failing to meet loan payment obligations, the lender has the authority to take possession of the gold jewellery.

India Gold Loan Market Growth Analysis
India Gold Loan Growth Outlook

To know about the Research Methodology :- Request Free Sample Report

India is one of the largest gold markets in the world, with Indian households owning more than 27,000 metric tonnes of gold. This translates into a potential India Gold Loan Market opportunity of INR 65 trillion at current gold prices, compared to the mere INR 6 trillion that is currently tapped by the organized market. This presents a huge opportunity for focused/large gold financiers like MUTH, MGFL, and IIFL. While heightened competition from banks/fintech may continue to impact the growth of gold loan NBFCs in the near term, we believe there is ample space and opportunity for all players, including banks, NBFCs, and fintech, to co-exist and expand over the long term.

Indian households hold a mammoth 14% share of global gold at 27,000 tonnes, only ~20% of which is pledged. The unorganised sector accounts for a whopping 65% of the gold loan market, while organized players like banks and NBFCs only have a 35% share. This shows that there is a huge opportunity for organized players to grow the gold loan market in India. With the right strategies and partnerships, organized players can tap into the vast potential of the Indian gold loan market and grow their businesses significantly.

Demand for Gold in India:

In 2025, the gold demand in India is expected to range between 800 and 850 tonnes, with the total demand likely surpassing the 800-tonne mark. Despite the recent 5 per cent duty increase on gold imposed by the Central government, this measure is not anticipated to exert a significant influence on the demand for the precious yellow metal. It's worth noting that the demand for gold in India in the preceding year, 2021, stood at approximately 797 tonnes, providing context to the projected demand for the upcoming year.

Gold Jewelry Consumer Demand: 2018-2022 Metric Ton Analysis in India

India Gold Loan Market
Gold has a vital place in India, where it is seen as a symbol of financial security, social status, and cultural legacy. Gold has traditionally been a liquid asset and universally accepted commodity that has seen its value appreciate over the decades. This is why India is one of the largest consumers of gold in the world, accounting for an estimated 23% of global gold demand between 2009 and 2018. Gold holdings in India are primarily concentrated in rural areas, with more than two-thirds of India's total demand emerging from rural communities. This is because gold is seen as a safe and secure investment in rural areas, where there is limited access to other financial products. Gold is also used as a form of dowry in rural India, and it is often given as a gift on special occasions.

The demand for gold in India is likely to continue to grow in the coming years, as the country's economy grows and the middle-class increases. Gold is seen as a safe haven asset in times of economic uncertainty, and it is also a popular investment for weddings and other special occasions. As a result, India is likely to remain one of the largest consumers of gold in the world for many years to come.

India Gold Loan Market Dynamics:

Competition among Lenders is Growing: India gold loan market is becoming increasingly competitive, as more and more lenders are entering the market. This competition is leading to lower interest rates and better terms and conditions for borrowers. There are a number of factors that are driving the increasing competition among lenders in the gold loan market. Such as, the demand for gold loans is growing in India, owing to the increasing disposable incomes of Indians, the growing middle class, and the rising cost of living. This growing demand is putting pressure on lenders to offer competitive interest rates and terms and conditions to attract borrowers.

The entry of new players into the India gold loan market is also driving competition. New players, such as online gold loan platforms and non-banking financial companies (NBFCs), are offering competitive products and services, which is putting pressure on traditional lenders to innovate and improve their offerings. Lenders are under pressure to differentiate themselves from their competitors. They are doing this by offering a variety of products and services, such as instant approval, quick disbursal, and flexible repayment terms. They are also using technology to improve the customer experience.

Increasing Online Gold Loan Platforms: Online gold loan platforms are making it easier and more convenient for borrowers to access gold loans. These platforms offer a variety of features, such as instant approval, quick disbursal, and competitive interest rates. As a result, online gold loan platforms are gaining popularity and are expected to continue to grow in the coming years.

Share Of Online Gold Loans By Top Company 2021-22

India Gold Loan Market

Technology Adoption: Technology is playing an increasingly important role in the gold loan market. Lenders are using technology to automate the loan process, improve customer service, and reduce costs. Technology is also making it easier for borrowers to access gold loans, as they can now apply for loans online.

The Gold Loan Market in India Is Facing a Number Of Challenges, including declining gold prices, increased non-performing assets (NPAs), competition from non-banking financial companies (NBFCs), regulatory challenges, the rise of digital lending, the changing needs of borrowers, and the lack of transparency. Declining gold prices are a major challenge for the gold loan market, as the value of the collateral pledged by borrowers determines the amount of loan that they can avail. If gold prices decline, the value of the collateral also declines, which can lead to lenders calling in loans.

Increased NPAs are another major challenge for the gold loan market. This is due to a number of factors, such as borrowers defaulting on their loans due to financial difficulties, and lenders not being able to recover the gold pledged by borrowers. Competition from NBFCs is also a major challenge for the gold loan market. NBFCs are offering gold loans at lower interest rates and with more flexible repayment terms, which is making it difficult for traditional lenders to compete.

Regulatory challenges are also a major challenge for the gold loan market. The Reserve Bank of India (RBI) has imposed a number of regulations on the gold loan market in recent years, which has made it more difficult for lenders to operate. The rise of digital lending is also a challenge for the gold loan market. Digital lending platforms are making it easier for borrowers to access loans, including gold loans. This is posing a challenge to traditional lenders, who are not as well-equipped to compete with digital lenders.

Emerging Trends: India Gold Loan Market

1. Digital lending platforms are making it easier for borrowers to access gold loans. This is posing a challenge to traditional lenders, who are not as well-equipped to compete with digital lenders.
2. Financial inclusion remains a significant trend, with gold loans providing credit access to individuals who are underserved by traditional banking systems, especially in rural areas. Lenders are expanding their reach to serve these untapped markets.
3. Lenders are leveraging data analytics and credit scoring models to enhance risk assessment and manage default rates, leading to improved lending practices.
4. The emergence of gold-backed investment products, such as Gold Loan Exchange Traded Funds (ETFs), allows investors to leverage their gold holdings while retaining ownership. This trend aligns with the growing interest in diversifying investment portfolios.

India Gold Loan Market Segment Analysis:

India Gold Loan Market, by Loan Ticket Size

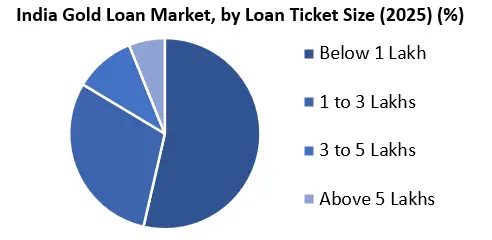
The India Gold Loan Market is segmented by loan ticket size into Below 1 Lakh, 1 to 3 Lakhs, 3 to 5 Lakhs, and Above 5 Lakhs. The Below 1 Lakh segment represents a significant portion of gold loan demand, supported by immediate household liquidity requirements, emergency expenses, and short-term financial needs. The 1 to 3 Lakhs segment serves personal financing, agricultural activities, and small business working capital requirements, while the 3 to 5 Lakhs segment caters to borrowers seeking higher loan amounts against pledged gold. The Above 5 Lakhs segment supports larger business financing and high-value borrowing requirements. Increasing gold prices, expanding NBFC lending networks, flexible repayment options, and growing demand for secured credit influence India Gold Loan Market growth.
India Gold Loan by Ticket Size

India Gold Loan Market, by End User

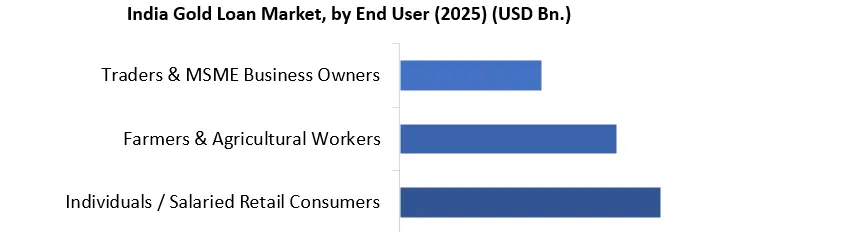
The India Gold Loan Market is segmented by end user into Individuals / Salaried Retail Consumers, Farmers & Agricultural Workers, and Traders & MSME Business Owners. Individuals and Salaried Retail Consumers represent an important segment due to increasing demand for quick personal loans, emergency financing, medical expenses, and household liquidity. Farmers & Agricultural Workers use gold-backed loans for seasonal agricultural activities, crop cultivation, and farming expenses, while Traders & MSME Business Owners rely on gold loans for working capital, inventory purchases, and business expansion. Increasing gold ownership, easy loan accessibility, competitive interest rates, and expanding NBFC lending networks support India Gold Loan Market growth
India Gold Loan by End-User

India Gold Loan Market Regional Insights:

South India dominates the India Gold Loan Market, supported by strong household gold ownership, an established gold-backed lending ecosystem, and the extensive presence of banks and NBFCs. Kerala, Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana contribute significantly to regional market size through demand from retail borrowers, farmers, and small businesses. The regional market gap includes limited access to formal lending in certain rural areas, creating substantial market potential for digital gold loans and branch network expansion. Growing demand for secured credit, flexible repayment options, and technology-driven lending services creates market opportunities. The regional market forecast reflects continued demand for gold-backed financing.

North India maintains a significant position in the India Gold Loan Market, supported by increasing demand for personal financing, agricultural credit, and MSME working capital. Uttar Pradesh, Punjab, Haryana, Delhi, and Rajasthan contribute to regional market size through expanding banking networks and increasing awareness of gold loan products. The market gap between traditional gold ownership and formal gold-backed lending penetration creates market potential for banks, NBFCs, and fintech platforms. Rising demand for quick loan approvals, competitive interest rates, and digital lending solutions generates market opportunities. The regional market forecast indicates opportunities for formal lending expansion across urban and rural markets.

West India represents an important market for gold-backed lending, supported by commercial activity, urbanization, and increasing financing requirements among traders and MSME business owners. Maharashtra and Gujarat contribute to regional market size through established financial institutions, business networks, and demand for short-term secured loans. The regional market gap includes underserved borrowers and limited access to convenient gold loan services in smaller cities. Expanding NBFC networks, digital gold loan platforms, and flexible credit products strengthen market potential and create new market opportunities. The regional market forecast supports continued expansion of retail and business-oriented gold lending services.

East India presents developing opportunities in the India Gold Loan Market, supported by demand for agricultural financing, household liquidity, and small business credit. West Bengal, Bihar, Odisha, and Jharkhand contribute to regional market size through expanding financial services and increasing access to formal credit. The market gap reflects differences in gold loan awareness, lender accessibility, and formal lending penetration across urban and rural locations. Expansion of banking infrastructure, financial inclusion initiatives, and digital loan processing strengthens market potential. The regional market forecast indicates opportunities for financial institutions to expand secured lending services and improve gold loan accessibility.

Central India represents an emerging segment of the India Gold Loan Market, supported by demand for short-term agricultural loans, household financing, and MSME working capital. Madhya Pradesh and Chhattisgarh contribute to regional market size through their agricultural economies and expanding banking infrastructure. The market gap includes limited penetration of specialized gold loan providers and differences in access to organized financial services. Increasing awareness of secured lending, expanding NBFC operations, and digital loan processing create market opportunities for financial institutions. The regional market forecast highlights market potential for expanding gold-backed lending services across smaller cities and rural areas.

Regional Breakdown: Jewelry Market Share Across India in 2023-24

India Gold Loan Market

Gold loans are easily available from a variety of lenders in South India, including banks, NBFCs, and pawnbrokers. This makes it convenient for borrowers to access gold loans quickly and easily. The interest rates on gold loans in South India are relatively competitive, making them a more affordable option than other types of loans, such as personal loans and home loans.

Competitive Analysis of The Gold Loan Market in India:

The gold loan market in India is highly competitive, with a number of players vying for market share. The key players in the market include Muthoot Finance, Manappuram Finance, HDFC Bank, ICICI Bank, and State Bank of India. Muthoot Finance and Manappuram Finance are the leading gold loan providers in India. They have a strong brand presence and wide network of branches. These companies offer a variety of gold loan products, including personal gold loans, business gold loans, and education gold loans. They also offer gold buyback schemes and gold exchange schemes.

HDFC Bank, ICICI Bank, and State Bank of India are also major players in the gold loan market. They offer gold loans as part of their wider range of financial products and services. These banks offer competitive interest rates and repayment terms on their gold loans. They also have a wide network of branches, which makes it convenient for borrowers to apply for and repay their gold loans.

India Gold Loan Market Scope: Inquire Before Buying


India Gold Loan Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 75.69 Billion
Forecast Period 2026 to 2034 CAGR: 12.30 % Market Size in 2034: USD 215 Billion
by Lender Provider Type Specialised Gold NBFCs
Cooperative & Regional Rural Banks (RRBs)
Fintech Platforms
Unorganized Lenders
by Mode of Disbursement Offline
Online
by Customer Income Low Income: Below 3 Lakhs
Lower Middle Income: 3 Lakhs to 5 Lakhs
Middle income: 5 Lakhs to 10 Lakhs
Upper Income: Above 10 Lakhs
by Loan Ticket Size Below 1 Lakhs
1 to 3 Lakhs
3 to 5 Lakhs
Above 5 Lakhs
by Loan Tenure Below 3 Months
3 Months to 6 Months
6 Months to 12 Months
Above 12 Months
by End-User Individuals / Salaried Retail Consumers
Farmers & Agricultural Workers
Traders & MSME Business Owners
by Geography South India
North India
West India
East & Northeast India
Union Territories

India Gold Loan Market, by Region

South India (Kerala, Tamil Nadu, Karnataka, Andhra Pradesh, Telangana)
North India (Uttar Pradesh, Punjab, Haryana, Delhi, Rajasthan, Uttarakhand, Himachal Pradesh, Jammu & Kashmir)
West India (Maharashtra, Gujarat, Goa)
East India (West Bengal, Bihar, Odisha, Jharkhand)
Central India (Madhya Pradesh, Chhattisgarh)

India Gold Loan Market, Key Players are

1. Muthoot Finance Limited
2. State Bank of India (SBI)
3. Canara Bank
4. Manappuram Finance Limited
5. IIFL Finance Limited
6. HDFC Bank Limited
7. ICICI Bank Limited
8. Punjab National Bank (PNB)
9. Bank of Baroda (BoB)
10. CSB Bank Limited
11. Muthoot Pappachan Group (Muthoot Blue)
12. Federal Bank Limited
13. Axis Bank Limited
14. Kotak Mahindra Bank
15. Union Bank of India
16. Bank of India (BoI)
17. Central Bank of India
18. Bajaj Finance Limited
19. Fedbank Financial Services Limited (Fedfina)
20. Capri Global Capital Limited (Capri Loans)
21. Muthoottu Mini Financiers Limited
22. Kosamattam Finance Limited
23. Poonawalla Fincorp Limited
24. Rupeek Fintech Private Limited
25. Indiagold (Flatwhite Capital Private Limited)
26. Oro Money (OroCorp Technologies)
27. IndusInd Bank Limited
28. Bank of Maharashtra
29. Karnataka Bank Limited
30. Indian Overseas Bank (IOB)
31. DBS Bank India Limited
32. Kerala State Co-operative Bank (KeralaBank)

FAQs:

1] What segments are covered in the India Gold Loan Market report?
Ans. The segments covered in the Gold Loan report are based on Market Type, Type of Lenders, Application and others.

2] Which Indian regional expected to hold the highest share in the India Gold Loan Market during the forecast period?
Ans. South India is expected to hold the highest share of the India Gold Loan Market during the forecast period.

3] What is the market size of the India Gold Loan Market by 2034?
Ans. The market size of the Linear Lighting by 2034 is expected to reach USD 215 Billion.

4] What is the forecast period for the India Gold Loan Market?
Ans. The forecast period for the India Gold Loan Market is 2025-2034.

5] What was the market size of the India Gold Loan in 2025?
Ans. The market size of the Linear Lighting in 2025 was valued at USD 75.69 Billion.

Table of Contents

1. Executive Market Landscape and Industry Overview 1.1 India Gold Loan Market Size Valuation Tracking and Projections (Value in USD Bn.), 2026–2034 1.2 Assessment of Current Market Structure, Competitive Landscape, and Industry Maturity 1.3 Assessment of Emerging Growth Opportunities Across Institutional and Informal Lending Sectors 1.4 Key Market Drivers, Industry Challenges, Emerging Growth Opportunities, and Business Outlook 1.5 Strategic Long-Term Investment and Market Development Outlook 2. India Gold Loan Market Dynamics & Strategic Insights 2.1 India Gold Loan Market Trends and Financial Sector Transformations 2.2 India Gold Loan Market DROC Framework Analysis: 2.2.1 Drivers 2.2.2 Restraints 2.2.3 Opportunities 2.2.4 Challenges 2.3 PORTER’S Five Forces Analytical Framework: 2.3.1 Supplier Power 2.3.2 Buyer Power 2.3.3 Threat of New Entrants 2.3.4 Threat of Substitutes 2.3.5 Competitive Rivalry 2.4 PESTLE Macroeconomic Influence Grid Analysis (Political, Economic, Social, Technological, Legal, and Environmental Indicators) 3. Analysis of Demand for Gold Loans in India, 2025 3.1 Historical Trends and Shifts in Borrowing Behavior 3.2 Socio-Economic Triggers Driving Demand 3.3 Role of Informal Lending and Shift to Formal Channels 3.4 Impact of Digital Onboarding and Rise of Doorstep Appraisal Platforms 3.5 Regional Disparities in Credit Sourcing and Penetration Across Non-Southern Hubs 3.6 Micro-Enterprise Capital Requirements and Seasonal Agricultural Credit Trajectories 4. Preference of Gold Loans in Rural, Semi-Urban, and Urban Markets 4.1 Penetration Rate by Region Type, 2025 4.2 Key Borrower Segments and Loan Usage 4.3 Trust in NBFCs vs Banks Across Regions 4.4 Infrastructure and Service Availability 4.5 Impact of Socio-Economic Differences 4.6 Digital vs Physical Access and Preferences 5. Customer Behavior and Trends 5.1 Borrower Sentiment Amid Gold Price and Interest Volatility 5.2 Shift from Informal to Formal Lending Channels 5.3 Digital Onboarding, e-KYC, and UPI-Powered Disbursements 5.4 Preferences for Tenure, Repayment Mode, and LTV Ratios 5.5 Role of Trust, Convenience, and Turnaround Time in Lender Choice 6. Impact of Government Gold Loan Policies 6.1 Key Regulatory Policies by RBI and Ministry of Finance 6.2 Priority Sector Lending Norms 6.3 LTV (Loan-to-Value) Ratio Guidelines and Changes 6.4 Impact of Gold Monetization Scheme 6.5 Government-Backed Agricultural Gold Loans 6.6 Policy Reforms and Digitization Push 7. Gold Loan Operations, Asset Management, and Portfolio Maintenance Review 7.1 Supervision of Preventive, Corrective, Predictive, Risk-Based, and Remote Portfolio Quality Monitoring Services 7.2 Diagnostic of Core Banking Systems, Digital Asset Management Platforms, Artificial Intelligence, and Remote Monitoring Systems 7.3 Gauging of Branch Portfolio Performance Optimization, Net Interest Margin Improvement, and Loan Lifecycle Extension Programs 7.4 Collateral Vault Protection, Field Service Networks, Workforce Development, and Operations Planning 7.5 Contrastive Studies of Commercial Bank Models, Specialized NBFCs, and Long-Term Service Agreements 7.6 Intelligent Asset Management and Digital Operations Outlook 8. Gold Appraisal Technology, Valuer Certification, and Collateral Risk Evaluation 8.1 Examination of Material Density Testing Frameworks, Caratage Scales, Touchstones, and Spectrometer Analyzers 8.2 Dissection of Acid Testing, Laser Testing, Ultrasonic Sound Evaluation, and Emerging Testing Systems 8.3 Quantifying of Appraisal Capacity, Regional Sourcing Strategies, and Valuation Training Infrastructure 8.4 Smart Appraisals, Process Automation, Quality Control, and Valuation Efficiency 8.5 Breakdown of High-, Medium-, and Low-Purity Gold Appraisal Metrics 8.6 Appraisal Systems Development and Collateral Valuation Roadmap 9. India Gold Loan Adoption, Credit Bureau Penetration, and Regional Competitiveness Analysis 9.1 Analysis of State-Level Project Pipeline and Credit Bureau Volume Expansion Plans 9.2 Inspection of Regional Household Gold Stock Availability and Credit Competitiveness 9.3 Evaluation of Government Financial Inclusion Targets and Subsidized Priority Sector Lending Support 9.4 Comparative Analysis of Banking Density, Sourcing Network Readiness, and Portfolio Quality Metrics 9.5 Regional Growth Outlook Through 2034 10. Financial Intermediary Grid, Co-Lending Transmission, and Capital Integration Study 10.1 Assessment of Financial Sourcing Infrastructure Supporting Institutional Gold Loan Portfolios [CRISIL] 10.2 Analysis of Co-Lending Expansion, Digital Sourcing Networks, and Capital Market Monetization Programs 10.3 Evaluation of Liquidity Management, NPA Volatility, and Power Balance System Flexibility 10.4 Smart Sourcing Technologies, Digital Asset Management, and Portfolio Automation 10.5 Study of Risk-Sharing Integrations Supporting Co-Lending Entities 10.6 Intermediary Grid Expansion and Capital Integration Outlook 11. Gold Loan Branch Infrastructure, Strongroom Balance of Plant, and Surveillance Systems Diagnostic 11.1 Inspection of Strongroom Vault Foundations, Counter Layouts, Internal Cash Enclosures, and Civil Infrastructure 11.2 Breakdown of Electronic Cash Collection Systems, Underground Alarm Cabling, Cash-in-Transit Facilities, and Interconnection Facilities 11.3 Monitoring of Electrical Power Backups, Biometric Safes, Time-Lock Switchgear, Protection Systems, and SCADA Integration 11.4 Study of Vault Balance of Plant (BoP) Design, Construction Quality, and Operational Performance Standards 11.5 Examination of Infrastructure Development Across Mature Metropolitan and Emerging Semi-Urban Markets 11.6 Horizon Blueprint for Gold Loan Branch Infrastructure Modernization and Expansion Outlook 12. India Gold Loan Portfolio Distribution and Institution Benchmarking Audit 12.1 Contrastive Mapping of Public Banks, Private Banks, Pure-Play NBFCs, Fintech Co-Lending, and Cooperative Sectors 12.2 Dissection of Branch Gold Loan Portfolios Covering Active, Renewed, Overdue, Restructured, and Auction-Stage Accounts 12.3 Measurement of Portfolio Execution Activities Including Customer KYC, Karatage Appraisal, LTV Allocation, and Loan Closures 12.4 Verification of Legal Frameworks, Loan-to-Value (LTV) Risk Buffers, Key Fact Statements (KFS), and Auction Readiness 12.5 Diagnostic of Outstanding AUM, Operating Costs, Net Interest Margins (NIM), NPAs, and Asset Performance 12.6 Upcoming India Gold Loan Project Pipeline, Capacity Expansion, and Institutional Sizing Outlook 13. Digitalization, Smart Gold Loans, and Emerging Technology Exploration 13.1 Oversight of Artificial Intelligence, Machine Learning, and Predictive Analytics for Risk Scoring Optimization [CRISIL, ICRA] 13.2 Breakdown of Digital Twin Branch Models, SCADA Security Modernization, and Remote Vault Monitoring Systems 13.3 Gauging of Automated Appraisal Verification, Computer Vision Purity Analysis, and Robotics Asset Safekeeping 13.4 Supervision of IoT Branch Connectivity, Edge Computing Infrastructure, and Cybersecurity Frameworks for Financial Transactions 13.5 Cross-Study of Digital Transformation and Sourcing Sizing Performance Across Leading Financial Hubs 13.6 Smart Gold Loan System Development, Instant Loan Approvals, and Digital Innovation Outlook 14. Regulatory Framework, Central Bank Policy, and Financial Compliance Metrics 14.1 Cross-Benchmarking of RBI Lending Policies, Capital Adequacy Rules, and Compliance Targets Across Major Players 14.2 Dissection of Fair Practices Codes, Mandatory Key Fact Statements (KFS), and Land Use or Security Framework Regulations 14.3 Measurement of Anti-Money Laundering (AML) Compliance Standards, KYC Technical Codes, and Branch Audit Requirements 14.4 Inspection of Statutory Liquidity Ratios, Fixed Asset Ownership Limitations, Tier-1 Capital Rules, and Co-Lending Contracts [CRISIL, ICRA] 14.5 Contrastive Mapping of Commercial Banks and Non-Banking Financial Companies (NBFC) Regulatory Competitiveness 14.6 Upcoming Banking Policy Developments Supporting Legal Capital Buffers and Corporate Credit Market Sizing 15. Global Bullion Flow, Sovereign Manufacturing Footprints, and Cross-Border Material Supply Blueprint (2025–2034) 15.1 Inspection of Cross-Border Logistical Networks, Security Sourcing Transits, and Secure Vault Transport Systems 15.2 Monitoring of Import Duty Policies, Sovereign Free Trade Agreements, Local Content Caps, and Supply Corridor Security 15.3 Cross-Study of Domestic Smelting Infrastructure and Bullion Supply Sizing Capabilities Across Core Regional States 15.4 Future International Trade Flow Paths and Sovereign Refinery Asset Expansion Outlook 16. Pricing Structure, Interest Cost Composition, and Loan Lifecycle Economics Blueprint 16.1 Historical Yield Pricing Trends for Bank Schemes, Specialized NBFC Matrices, and Tiered Interest Slab Models 16.2 Cross-Benchmarking of Appraisal Costs, Processing Fees, Valuation Charges, and Auction Logistics Expenses 16.3 Breakdown of Lender Capital Expenditure (CAPEX), Operational Expenditure (OPEX), and Branch Portfolio Cost Composition [CRISIL] 16.4 Gauging of Net Interest Margins (NIM), Cost-to-Income Ratios, Portfolio Return on Investment (ROI), and Account Economics 16.5 Contrastive Mapping of Yield Cost Benchmarking Across Public Sector, Private Sector, and Specialized Non-Banking Credit Lenders 16.6 Upcoming Pricing Adjustments, Competitive Rate Arbitrage, and Loan Cost Competitiveness Outlook 17. India Gold Loan Financial Industry Value Chain Tracking 17.1 Comprehensive Sizing of the Indian Gold Loan Value Chain from Household Asset Pledging to Capital Monetization [CRISIL] 17.2 Upstream Dissection Covering Retail Jewelery Sourcing, Caratage Smelting Standards, Refining Systems, and Custody Safekeeping 17.3 Midstream Tracking Across Commercial Vault Operations, Credit Underwriting, Processing Centers, and Co-Lending Entities 17.4 Downstream Mapping Covering Individual Retail Defaulters, MSME Capital Rollovers, Credit Bureaus, and Auction Liquidation Houses 17.5 Measurement of Value Creation Across Local Customer Sourcing, Branch Processing Networks, Digitized Storage, and Portfolio Trading 17.6 Future Financial Value Chain Disruption, Fintech Platform Integration, and Strategic Capital Aggregation Outlook 18. Gold Loan Liquidity Supply Chain, Sourcing Integration, and Collateral Sourcing Dashboard 18.1 Institutional Liquidity Networks Supporting Branch Funding Operations and Short-Term Capital Draws [CRISIL] 18.2 Breakdown of Tier-1 Bank Lines, Commercial Paper Issuances, Securitization Pools, and Co-Lending Sourcing Ecosystems 18.3 Inspection of Cash Sourcing Strategies Covering Bank Vault Draws, Doorstep Agent Cash Logistics, and Digital Transfers 18.4 Supervision of Collateral Jewelry Velocity, Inventory Vault Risk Management, Cash Transit Security, and Supply Disruptions 18.5 Contrastive Mapping of Sourcing Footprint Optimization, Liability Mix 19. Credit Demand–Supply Outlook and Financial System Balance Grid 19.1 Cross-Benchmarking of Regional Consumer Demand for Short-Term Household and Commercial Retail Credit Lines 19.2 Diagnostic of Financial Capital Reserves Supporting Nationwide Branch Sourcing Operations and Asset Book Growth 19.3 Measurement of Pledged Collateral Pools, Retail Underwriting Pipelines, and Structural Asset-Liability Matching (ALM) Balance 19.4 Cross-Benchmarking of Regional Funding Efficiencies, Systemic Liquidity Trends, and Competitive Sourcing Advantages 19.5 Horizon Charting of Future Credit Demand–Supply Matching Trajectories, Credit Expansion Cycles, and Market Balance Evolution 20. Strategic Capital Investment Opportunities and Commercial Viability Dashboard 20.1 Cross-Study of Regional Investment Attractiveness Across Tier-2, Tier-3, and Unpenetrated Rural Credit Hubs 20.2 Diagnostic of Commercial Viability for High-Tech Digital Doorstep Sourcing Models and Specialized Micro-Branch Rollouts 20.3 Measurement of Capital Deployment Trends Across Vault Infrastructure, Core Banking Digital Frameworks, and Sourcing Automation 20.4 Monitoring of Joint Ventures, Bank-Fintech Co-Lending Alliances, Strategic Platform Sourcing, and Corporate Acquisitions 20.5 Contrastive Mapping of Wholesale Funding Structures, Green Bond Issuances, and Institutional Securitization 20.6 Long-Term Strategic Expansion Horizon Supporting Sustained Capital Allocation and Financial Scale Growth 21. Sustainability, ESG Performance, and Circular Economy Financial Matrix 21.1 Tracking of Carbon Emission Reductions Through Digitized Branch Operations and Reduced Customer Travel Loops 21.2 Breakdown of Circular Economy Financial Practices Including Pledged Asset Recovery, Meltdown Processing, and Refining Cycles 21.3 Inspection of Environmental, Social, and Governance (ESG) Framework Compliance Across Major Public Banks and Listed NBFCs 21.4 Supervision of Consumer Protection Frameworks, Fair Practices Code Adherence, and Rural Community Upliftment Programs 21.5 Diagnostic of Sustainable Capital Sourcing, Social Bonds, and Responsible Financial Inclusion Operations 21.6 Future Sustainability Trajectories, Corporate ESG Benchmarking, and Financial Responsibility Roadmaps 22. Future Market Roadmap, Strategic Recommendations, and Financial Industry Horizon 22.1 Monitoring of Emerging Financial Technology Adoption Across Nationwide Branch Networks and Digital Platforms 22.2 Dissection of Long-Term Financial Stability Policies, Banking Regulation Adjustments, and Credit Expansion Horizons 22.3 Gauging of Disruptive Credit Intermediary Business Models, Alternative Collateral Monetizations, and Structural Shifts 22.4 Prioritizing of Capital Investment Targets Supporting Sustainable Branch Density and Systemic Scale Expansions 22.5 Contrastive Mapping of Underwriting Risk Volatility, Strategic Growth Vectors, and Emerging Credit Arbitrage Opportunities 22.6 National Portfolio Expansion Trajectory, Asset Growth Sizing, and Structural Credit Industry Outlook 23. Gold Loan Financial Ecosystem and Industry Ledger 23.1 Mapping of Commercial Banks, Specialized NBFCs, Fintech Platforms, and Regional Cooperative Lenders Across the India Gold Loan Value Chain 23.2 Breakdown of Public Sector Banks, Private Sector Banks, Co-Lending Partners, and Doorstep Appraisal Services 23.3 Study of Customer Acquisition Channels, Physical Branch Operations, Collateral Evaluation Logistics, and Digital Sourcing Platforms 23.4 Cross-Benchmarking of Regional Portfolio Performance, Loan-to-Value (LTV) Ratios, and Credit Bureau Penetration Across Major Lending Clusters 23.5 Future Gold Loan Financial Ecosystem Development and Commercial Expansion Outlook 24. Gold Loan Lifecycle Management, Risk Analysis, and Compliance Dashboard 24.1 Supervision of End-to-End Gold Loan Lifecycles From Pledged Ornament Appraisal to Loan Closure 24.2 Examination of Collateral Valuation Campaigns, Caratage Purity Audits, and Risk Control Measures 24.3 Gauging of Credit Feasibility, Collection Lifecycles, Non-Performing Asset (NPA) Risks, and Auction Matrix Planning 24.4 Inspection of RBI Regulatory Approvals, Mandatory Key Fact Statements (KFS), KYC Verification, and Branch Security Standards 24.5 Contrastive Mapping of Online Doorstep Disbursals, Traditional In-Branch Pledges, and Overdue Loan Renewals 25. Gold Loan Infrastructure, Branch Construction, Sourcing Network, and Commissioning Audit 25.1 Technical Audit of Physical Branch Engineering Design, Strongroom Vault Infrastructure, and Vault Construction 25.2 Dissection of Operations Execution Models, Cash Inventory Management, Heavy Currency Logistics, and Project Scheduling 25.3 Monitoring of Security Integration, Centralized Alarm Systems, and Real-Time SCADA Surveillance Network 25.4 Verification of Regulatory Compliance Audits, RBI Vaulting Mandates, and Internal Branch Risk Controls 25.5 Cross-Study of Location Sourcing Strategy, Regional Hub Densities, and Cost-Optimized Network Commissioning 26. India Gold Loan Market: Market Size and Forecast by Segmentation (by Value in USD Mn) (2025-2034) 26.1 Sizing and Trend Projections of India Gold Loan Market, By Lender Provider Type (Value Tracking) 26.1.1 Commercial Banks 26.1.2 Specialized Gold NBFCs 26.1.3 Cooperative & Regional Rural Banks (RRBs) 26.1.4 Fintech Platforms 26.1.5 Unorganized Lenders 26.2 Sizing and Trend Projections of India Gold Loan Market, By Mode of Disbursement (Value Tracking) 26.2.1 Online 26.2.2 Offline 26.3 Sizing and Trend Projections of India Gold Loan Market, By Customer Income (Value Tracking) 26.3.1 Low Income: Below 3 Lakhs 26.3.2 Lower Middle Income: 3 Lakhs to 5 Lakhs 26.3.3 Middle income: 5 Lakhs to 10 Lakhs 26.3.4 Upper Income: Above 10 Lakhs 26.4 Sizing and Trend Projections of India Gold Loan Market, By Loan Ticket Size (Value Tracking) 26.4.1 Below 1 Lakhs 26.4.2 1 to 3 Lakhs 26.4.3 3 to 5 Lakhs 26.4.4 Above 5 Lakhs 26.5 Sizing and Trend Projections of India Gold Loan Market, By Geography (Value Tracking) 26.5.1 South India 26.5.2 North India 26.5.3 West India 26.5.4 East India 26.5.5 Union Territories 27. Competitive Landscape 27.1 MMR Competition Matrix 27.2 Competitive Positioning of Leading India Gold Loan Providers 27.3 Key Players Benchmarking 27.3.1 Company Name 27.3.2 Headquarters 27.3.3 Gold Loan Scheme Portfolio 27.3.4 Loan-to-Value (LTV) Risk Framework 27.3.5 Assets Under Management (AUM) 27.3.6 Gold Vault Capacity 27.3.7 Net Interest Margin (NIM) (2025) 27.3.8 Market Share (%) 27.3.9 Digital Doorstep App & Remote Valuer Solutions 27.3.10 Industries Served 27.3.11 Geographic Presence 27.3.12 Strongroom & Branch Security Infrastructure 27.3.13 Co-Lending & Banking Partnership Capabilities 27.4 Market Structure 27.4.1 Market Leaders 27.4.2 Market Followers 27.4.3 Emerging Players 27.5 Mergers and Acquisitions Details 27.6 Recent Key Developments 28. Gold Loan Product Portfolio and Technology Differentiation Blueprint 28.1 Contrastive Mapping of Gold Loan Product Portfolios Across Leading India Gold Loan Companies 28.2 Gauging of Interest Rate Slab Ratings, LTV Ratios, Vault Security Turnaround, and Repayment Scheme Offerings 28.3 Monitoring of Digital Doorstep Gold Solutions Including App Sourcing, Remote Appraisal, and Smart Valuer Technologies 28.4 Measurement of Product Differentiation Through Scheme Flexibility, Interest Rebates, and Customer Lifecycle Performance 29. Risk Management, Underwriting Innovation, and Credit Capability Metrics 29.1 Cross-Benchmarking of Risk Analytics and Credit Assessment Capabilities Across Leading Banks and Gold NBFCs 29.2 Technical Audit of Underwriting Process Investments Supporting Automated Customer Profiling and Portfolio Tracking 29.3 Inspection of Proprietary Risk Scoring Algorithms, Collateral Management IP, and Operational Leadership Across Industry Participants 29.4 Breakdown of Advanced Appraisal Technologies Including Non-Destructive Spectrometer Analysis, Computer Vision, and Predictive NPA Analytics 29.5 Supervision of Industry Collaboration with Credit Bureaus, Fintech Partners, Security Agencies, and Central Bank Regulators Supporting Operational Innovation 29.6 Long-Term Risk Mitigation Roadmap, Co-Lending Analytics Integration, and Underwriting Capability Landscape Outlook 30. Branch Network Scale, Project Execution, and Geographic Presence Dashboard 30.1 Quantifying of Physical Footprints and Vault Sourcing Capabilities Across Major Indian Gold Lenders 30.2 Study of Branch Rollout Capacity, Strongroom Construction, Component Localization, and Sourcing Competitiveness [CRISIL] 30.3 Verification of Customer Acquisition Channels, Physical Branch Distribution Operations, and Valuation Network Expertise Across Major Regional Zones 31. Financial Performance and Market Position Grid 31.1 Tracking of Interest Income Performance, Assets Under Management (AUM) Scale, and Net Revenue Contributions Across Top Lenders [CRISIL] 31.2 Breakdown of Market Position Based on Active Portfolio Growth, Gold Volume Shipments, Co-Lending Pipeline, and Regional Sourcing Footprints 31.3 Diagnostic of Net Interest Margin (NIM), Cost-to-Income Performance, Profitability Trends, and Capital Adequacy Strength 31.4 Supervision of Income Diversification Across Retail Lending, Cross-Selling Insurance, Microfinance, and Fee-Based Sourcing Channels 31.5 Measurement of Technology Investments, Customer Acquisition Costs, and Long-Term Asset Growth Performance 32. Operations, Vault Asset Management, and Customer Service Capability Benchmarking 32.1 Comparative Evaluation of Portfolio Monitoring Service Portfolios Including Collections, Renewals, Overdue Alerts, and Auction Notices 32.2 Analysis of Digital Core Banking Systems, SCADA Vault Security Integration, Artificial Intelligence, and Predictive Default Analytics 32.3 Evaluation of Branch Asset Performance Optimization, Operational Reliability, Personnel Efficiency, and Account Lifespan Enhancements 32.4 Strongroom Cash Logistics, Auditing Networks, Field Force Development, and Auction Planning Timelines 32.5 Comparison of Bank In-House Valuation Models, Specialized NBFC Branches, and Independent Valuation Provider Channels 32.6 Intelligent Vault Operations, Automated Jewelry Assaying, and Customer Lifecycle Service Delivery Outlook 32.7 Intelligent Operations, Autonomous Maintenance, and Service Capability Development Outlook 33. Strategic Co-Lending Partnerships, Banking Alliances, and Business Expansion Outlook 33.1 Comparison of Strategic Cooperations Between Fintech Platforms, Scheduled Commercial Banks, and Wholesale Capital Funders 33.2 Analysis of Co-Lending Credit Lines, Institutional Refinance Auctions, Term Funding Contracts, and Corporate Sourcing Pacts 33.3 Evaluation of Joint Venture Programs, Digital-First Lead Sourcing Partnerships, and National Financial Inclusion Alliance Models 33.4 Study of Inter-Bank Intermediary Hubs, Securitization Pool Channels, and Third-Party API Technology Implementations 33.5 Analysis of Revenue-Sharing Models Supporting Credit Processing, Compliance Routing, and Long-Term Loan Collections 33.6 Review of Fintech-Bank Integration Models, Shared Infrastructure Deployments, and Collaborative Business Expansion Outlook 34. Company Profiles: 30+ Key Players 34.1 Detailed Profile Parameters Considered: 34.1.1 Overview 34.1.2 Business Portfolio 34.1.3 Product Portfolio 34.1.4 Financial Performance (2023–2025) 34.1.5 Vault Infrastructure 34.1.6 Geographic Presence 34.1.7 Recent Developments 34.2 Key Players 34.2.1 Muthoot Finance Limited 34.2.2 State Bank of India (SBI) 34.2.3 Canara Bank 34.2.4 Manappuram Finance Limited 34.2.5 IIFL Finance Limited 34.2.6 HDFC Bank Limited 34.2.7 ICICI Bank Limited 34.2.8 Punjab National Bank (PNB) 34.2.9 Bank of Baroda (BoB) 34.2.10 CSB Bank Limited 34.2.11 Muthoot Pappachan Group (Muthoot Blue) 34.2.12 Federal Bank Limited 34.2.13 Axis Bank Limited 34.2.14 Kotak Mahindra Bank 34.2.15 Union Bank of India 34.2.16 Bank of India (BoI) 34.2.17 Central Bank of India 34.2.18 Bajaj Finance Limited 34.2.19 Fedbank Financial Services Limited (Fedfina) 34.2.20 Capri Global Capital Limited (Capri Loans) 34.2.21 Muthoottu Mini Financiers Limited 34.2.22 Kosamattam Finance Limited 34.2.23 Poonawalla Fincorp Limited 34.2.24 Rupeek Fintech Private Limited 34.2.25 Indiagold (Flatwhite Capital PrivateLimited) 34.2.26 Oro Money (OroCorp Technologies) 34.2.27 IndusInd Bank Limited 34.2.28 Bank of Maharashtra 34.2.29 Karnataka Bank Limited 34.2.30 Indian Overseas Bank (IOB) 34.2.31 DBS Bank India Limited 34.2.32 Kerala State Co-operative Bank (KeralaBank) 35. Untapped Market Identification & Gold Loan Expansion Opportunity Map 35.1 Identifying high-potential markets for gold loan portfolio expansion across India 35.2 State-wise gold ownership potential and existing gold loan penetration analysis 35.3 Identification of underserved rural, semi-urban, and Tier II/Tier III markets with high borrowing potential 35.4 India Gold Loan Market Opportunity Map by State 35.5 High Potential Underserved Regions for Gold Loan Expansion 35.6 Gold Ownership vs Gold Loan Penetration Matrix 35.7 Tier II & Tier III City Expansion Opportunity Analysis 35.8 Regional Gold Loan Market Attractiveness Ranking 35.9 Addressable Market Opportunity vs Current Gold Loan Portfolio Penetration 36. Regional Market Opportunity & Branch Expansion Potential Analysis 36.1 Mapping geographic growth opportunities for gold loan providers 36.2 State-level gold loan demand concentration and market maturity assessment 36.3 Identification of high-growth states based on household gold holdings and financial inclusion indicators 36.4 Urban, semi-urban, and rural branch expansion opportunity analysis 36.5 Tier-wise opportunity assessment covering Metro, Tier I, Tier II, and Tier III cities 36.6 Regional competitive intensity and whitespace opportunity evaluation 36.7 Strategic branch network expansion roadmap for increasing gold loan reach 37. Customer Segment Opportunity & Borrower Acquisition Analysis 37.1 Understanding new customer segments driving future gold loan growth 37.2 Customer segmentation across salaried individuals, farmers, MSMEs, traders, and self-employed borrowers 37.3 Borrower requirement analysis including emergency finance, working capital, agriculture funding, and personal consumption needs 37.4 Customer acquisition potential through digital platforms, doorstep services, and branch networks 37.5 Analysis of repeat borrowers and customer lifecycle value improvement opportunities 37.6 Identification of high-value customer segments based on loan ticket size and repayment behaviour 38. Gold Valuation Challenges & Collateral Assessment Opportunity Analysis 38.1 Evaluating challenges and technology opportunities in gold appraisal mechanisms 38.2 Assessment of traditional gold valuation methods including touchstone testing, acid testing, and manual appraisal 38.3 Challenges associated with purity verification, valuation accuracy, and human dependency 38.4 Adoption potential of digital valuation technologies including XRF testing, AI-based assessment, and automated appraisal systems 38.5 Opportunities to improve valuation accuracy, turnaround time, and customer trust through technology integration 38.6 Assessment of collateral risks including fake jewellery detection, gold substitution, purity mismatch, and overvaluation risks 38.7 Comparative analysis of traditional versus technology-enabled gold appraisal systems and digital valuation adoption trends 38.8 Role of AI, computer vision, and automated appraisal solutions in improving valuation accuracy, risk control, and operational efficiency 39. Gold Loan Collection Mechanism & Portfolio Recovery Analysis 39.1 Understanding collection challenges and improving repayment efficiency 39.2 Gold loan repayment behaviour analysis across customer segments and regions 39.3 Evaluation of collection channels including branch-based collection, digital payments, and doorstep recovery 39.4 Overdue account management and customer engagement strategies assessment 39.5 Analysis of default risks, auction processes, and collateral recovery mechanisms 39.6 Evaluation of portfolio quality indicators including NPA levels, default rates, overdue ageing, and lender-wise risk exposure 39.7 Gold loan auction process assessment covering auction frequency, recovery rates, customer communication, and asset liquidation practices 39.8 Benchmarking of collection efficiency ratios across banks, NBFCs, fintech platforms, and other organized lenders 39.9 Regional risk assessment based on state-wise default trends, repayment behaviour, and customer credit characteristics 40. MTM Monitoring, Margin Call Framework & Gold Price Risk Management Analysis 40.1 Evaluating collateral value fluctuations and risk mitigation strategies for gold loan portfolio stability 40.2 Assessment of gold price volatility impact on collateral value, loan security, and overall gold loan portfolio performance 40.3 Analysis of Mark-to-Market (MTM) valuation mechanisms for continuous monitoring of pledged gold assets 40.4 Evaluation of Loan-to-Value (LTV) ratio management, regulatory limits, and collateral buffer maintenance practices 40.5 Margin call framework analysis covering trigger thresholds, additional collateral requirements, repayment adjustments, and customer response mechanisms 40.6 Assessment of margin call frequency and portfolio exposure during gold price fluctuations and market volatility scenarios 41. Gold Loan Portfolio Growth Strategy & Future Expansion Roadmap 41.1 Identifying strategic initiatives to increase gold loan assets under management 41.2 Assessment of gold loan portfolio expansion opportunities through branch network growth and state-wise market penetration strategies 41.3 Evaluation of digital gold loan adoption, online application growth, e-KYC onboarding, and technology-enabled lending models 41.4 Analysis of doorstep gold loan services, remote appraisal solutions, and customer preference towards convenient lending channels 41.5 Customer acquisition strategy assessment covering borrower acquisition cost, retention rate, repeat borrowing potential, and lifecycle value enhancement 42. Gold Loan Market Opportunity Prioritization & Strategic Investment Assessment 42.1 Evaluating commercial opportunities for sustainable gold loan business expansion 42.2 Market attractiveness assessment based on growth potential, competition intensity, and customer accessibility 42.3 Investment opportunities across branch infrastructure, technology platforms, and valuation systems 42.4 Assessment of digital transformation opportunities for improving operational efficiency 42.5 Evaluation of portfolio diversification strategies across customer segments and geographies 42.6 Identification of strategic priorities for lenders to strengthen gold loan market position 42.7 Future opportunity outlook for organized gold lending ecosystem development 43. Key Findings 44. Strategic Moves & Industry Outlook 45. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements