Immersion Cooling Fluids Market - Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

8.1%
CAGR (2026-2034)
2.11 USD Bn.
Forecast Market Size
315
Report Pages
120
Market Tables

Overview

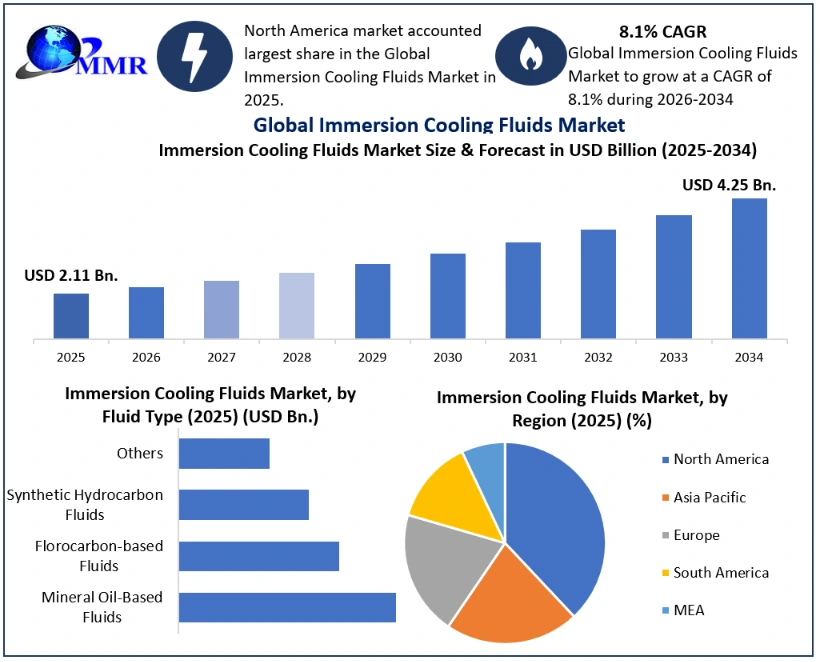
The Immersion Cooling Fluids Market size was valued at USD 2.11 Billion in 2025 and the total Immersion Cooling Fluids revenue is expected to grow at a CAGR of 8.1% from 2026 to 2034, reaching USD 4.25 Billion by 2034.

Immersion cooling is a thermal management approach, commonly used in IT cooling, in which electronic equipment and IT components, including entire servers and storage devices, are immersed in a thermally conductive but electrically insulating dielectric liquid or coolant. Heat is removed from the system by bringing relatively cold liquid into direct contact with hot components, then passing the now-heated liquid through cool heat exchangers. Immersion cooling, particularly for bitcoin mining, has been a popular way of generating useable heat in recent years. A single ASIC miner in a cold environment can generate super high efficiency electric heat conversion sufficient to heat an entire home.

Immersion cooling market is likely to be driven by increasing server rack density and chip density, new use cases such as hazardous edge computing settings, and demand to minimise energy usage during data centre cooling. Several global as well as regional competitors are present in the industry.

In the industry, there are several unique immersion cooling systems available, and several manufacturers retrofit off-the-shelf Information Technology Equipment (ITE) to make it compatible with their technology. Furthermore, manufacturers provide customised solutions to their clients based on their needs. The growing demand for IoT capabilities and cloud computing infrastructure will fuel demand for data centres, particularly hyper-scale data centres. Hyperscale data centres allow digital platforms to efficiently store and move data. When compared to current data centres, hyper-scale facilities can manage high-volume traffic as well as large computational workloads.

Immersion Cooling Fluids Market Growth Outlook
Immersion Cooling Fluids Market Growth

To know about the Research Methodology :- Request Free Sample Report

Immersion Cooling Fluids Market Dynamics

Increasing Need for Sustainable Cooling Solutions

Almost every major sector in the world is undergoing dramatic transformations, and many old business strategies are becoming obsolete as most companies shift their focus from commercial and revenue expansions to sustainable development and the circular economy. As future initiatives are planned within the Environmental, Social, and Governance (ESG) framework, this has had an influence on numerous company models. This is visible in many ESG developments throughout the world. Sustainable data centres have begun to update their facilities in order to drastically cut water use, including data centre cooling advances. New battery improvements enable them to use fewer and longer-lasting batteries. They are also collaborating closely with local power companies to find strategies to increase the use of green energy. This is expected to boost the Immersion Cooling Fluids Market growth.

Increasing Government Initiatives for Carbon Neutral and Energy-Efficient Data Centers

The development of carbon-neutral data centres is expected to be fueled by various government programmes and environmental laws, notably those aimed at lowering carbon emissions. For example, the International Climate Agreement, often known as the Paris Agreement, in which nations discuss activities they will take to reduce greenhouse gas emissions in order to achieve the goal of zero carbon emissions. Government initiatives, as well as data centre and organisation actions and responsibilities, are critical for advancing practical data centre cooling improvements. Governments and data centre operators can collaborate to determine how sustainable investments and activities can best benefit the whole framework while also assisting in fulfilling national energy and environmental standards.

High Investment with Greater Capital Expenditure

The expense of replacing failing servers more often than normal may be less expensive over time for a big organisation than the cost of maintaining a hyperscale facility at lower temperatures. However, with the increasing integration of GPUs in data centres driven by the need for more computational power, major organisations must shift to an effective cooling system.

When comparing the two-phase immersion cooling system to the single-phase immersion, the upfront expenses of the two-phase immersion are much higher owing to the advanced engineering. Because immersion technology is newer than water or air cooling, and cooling technology is continually evolving, the cost is higher than for established methods. Furthermore, the expense of fluorocarbon-based coolants is significant since they must be refilled on a regular basis. These coolants cost hundreds of dollars per gallon, which raises overall running costs and offsets any little increases in power efficiency, not to mention the total cost of ownership (TCO).

Lack of Standardization & Alternative Technologies Existing in the Market

The lack of immersion cooling guidelines and industry standards is a key impediment to the spread of immersion cooling innovation. Standard SOPs and guidelines are chosen for non-homogeneous process settings because goods controlled by standards and regulations are more compatible, consistent, and of higher quality. Because incompatible, non-standardized systems represent a market barrier, it is critical to develop standards and principles to enable worldwide adoption of immersion cooling for data centres, cryptocurrency mining farms, and blockchain applications.

Cooling infrastructure is classified into two types: air-based and water-based. To maintain temperature, air is fed into data centres using air-based cooling. Water-based cooling is further subdivided into immersion cooling and water-cooled racks, where fluid coolants flow across heated parts to maintain temperature. According to research, data centres contribute for 2% to 5% of worldwide greenhouse gas (GHG) emissions. Cooling systems account for over 40% of electricity usage in a data centre. Companies are attempting to address this issue by establishing "green" data centres that use free air-cooling devices rather than traditional air conditioners. The growing trend of establishing green data centres for managing, storing, and exchanging data has assisted many software companies in lowering energy use and total energy costs. This is expected to hamper the Immersion Cooling Fluids Market growth.

Immersion Cooling Fluids Market Segment Analysis

Based on Fluid Type, mineral oil dominated the segment in 2025 and is expected to dominate the Immersion Cooling market during the forecast period. Mineral oil is a by-product of the refining of crude oil to produce gasoline and other petroleum products. These mineral oil kinds are mostly constituted of alkanes and cycloalkanes and are often provided by oil refineries with no further processing, qualifications, or quality control. When compared to traditional air conditioning systems, mineral oil is more efficient, which simplifies facility design and results in cost savings. Mineral oil is used as a single-phase dielectric because of its high boiling point and because it is transparent and oily.

Over the forecast period, demand for fluorocarbon-based fluids is expected to increase at the quickest rate, with the highest CAGR. The most often used fluorocarbon molecules in immersion cooling solutions are perfluorocarbons (PFCs), hydrofluoroethers (HFEs), perfluoropolyethers (PFPEs), and fluorketones (FKs). Strong chemical and thermal stability, high dielectric strength, and relatively high vapour pressure all contribute to the ease of use of such cooling solutions for maintaining IT equipment temperatures.

Based on Product, single-phase immersion cooling type is expected to witness the fastest growth at the highest CAGR and dominate the Immersion Cooling market during the forecast period. Servers or other information technology (IT) components are installed vertically in a coolant bath of a hydrocarbon-based dielectric fluid with qualities comparable to mineral oil in single-phase immersion cooling system technology. Because the coolants do not evaporate when heated, they deteriorate after ten to fifteen years. As a result, the single-phase immersion cooling system is both cost-effective and extremely dependable, and it is expected to grow at a quicker rate in the future. Single-phase immersion cooling will continue to grow in popularity since it is less expensive to install and uses less energy. Demand for single immersion cooling will increase as customers become more aware of the tradeoffs between single-phase and two-phase immersion.

To prevent fluid loss owing to evaporation, the two-phase immersion cooling system is sealed with liquid. As a result, the two-phase immersion cooling system is more complicated and less practical than the single-phase immersion cooling system.

Based on Application, the high-performance computing application is dominating the global immersion cooling market as it requires relatively intensive computing resources such as artificial intelligence (AI) and machine learning (ML). Investment in high-density data centres and high-performance computing applications is expanding. Furthermore, as technology advances, faster microprocessors will become accessible each year, and low-cost HPC systems with a few processors will deliver capability hitherto reserved for pricey vector computers or MPP systems. As a result, high-performance computers are no longer restricted to specific architectures, but instead contribute to the high end of a continuum of fast desktop systems and servers.

Immersion Cooling Fluids Market application

Due to the groundbreaking notion of transactional compliance, start-ups, big and small and medium-sized organisations (SMEs), and many other entrepreneurs are adopting cryptocurrencies. This has led in bitcoin solution suppliers investing, partnerships, and collaborations, which will improve end-to-end solutions. This industry is very competitive because to the tremendous potential for development in nations such as the United States, Japan, India, and Germany. Microsoft has been exploring immersion cooling technology from bitcoin mining for its cloud servers since March 2021. As the most promising technology for future high-density data centres, the business has been focused on immersion cooling technology utilised in bitcoin mining.

Immersion Cooling Fluids Market Regional Insights

North America is a leader in the adoption of emerging technology and is expected to dominate the Immersion Cooling market during the forecast period. The region's linked device penetration has increased dramatically. Investors in data centres are increasingly interested in liquid immersion and direct-to-chip cooling methods. The introduction of 5G networks throughout the world has helped the relevance of edge data centres, and the United States is among the early users of the technology. Many US operators, including EdgePresence, EdgeMicro, and American Towers, have begun to invest in these centres.

Citizens and Companies in the United States are increasingly using the internet. The country is the largest market for data centre operations, and it is continue to grow as end-user data demand increases. The rising popularity of the Internet of Things (IoT) is a crucial driver for the US hyper-scale data centre industry, resulting in the construction of new facilities capable of handling exabytes of data generated by both commercial and consumer users. Furthermore, due to rising need for efficient data centres, initiatives for ecological data centre solutions, and significant expansion in power density across the area, Canada is constantly developing and supplying more data centre infrastructure options.

The data centre business in the Asia Pacific area is expanding rapidly and concentrating more on efficiency and uptime. Larger organisations are aiming to scale out their data centres to assure stability and dependability of data services, as the use of 5G, wearable devices, the internet of things, and artificial intelligence fuels a booming demand for processing capacity. Accelerator processors are finding their way into company data centres as artificial intelligence and comparable loads become regular practise across numerous industrial verticals in China.

Technologies that operate at zero latency process information at astronomical rates with the assistance of accelerating systems, meeting the needs of all latency-sensitive services. Several Taiwanese firms are engaged in considerable development operations in the immersion cooling landscape. With over 150 data centres, the Japanese industry has developed to become one of Asia's major data centre marketplaces. With over 150 data centres, the Japanese industry has developed to become one of Asia's major data centre marketplaces.

Immersion Cooling Fluids Market Recent Developments:

Date Company Development Impact
24 April 2026 Shell plc Shell partnered with Keppel to initiate a 6-month commercial pilot deploying its synthetic Gas-to-Liquids (GTL) immersion cooling fluid in an operational hyperscale data center. The initiative validates single-phase GTL dielectric fluid performance for high-density AI server infrastructure under real-world operating conditions.
05 May 2026 Castrol Limited Castrol announced plans to commercialize its Castrol ON DC 15 and DC 20 single-phase immersion cooling fluids within the Open Compute Project ecosystem. The expansion broadens standardized dielectric liquid choices for data center thermal management and EV fast-charging systems.
14 September 2026 The Lubrizol Corporation Lubrizol launched an expanded commercial rollout of its CompuZol™ single-phase synthetic immersion cooling fluids tailored for high-density AI data centers. The synthetic formulations offer superior material compatibility and thermal stability to optimize uptime in hyperscale computing installations.
12 October 2026 TotalEnergies SE TotalEnergies introduced the Coolant Keep Plate (CKP) technology designed to maintain dielectric liquid coverage during battery cell venting events. The mechanical design prevents thermal runaway propagation in direct immersion-cooled EV battery packs without requiring electronic controls.
23 October 2026 The Chemours Company Chemours scaled commercial output for its Opteon™ low-GWP fluorinated two-phase immersion cooling fluids following memory hardware qualification milestones. The expanded supply offers a PFAS-compliant fluorinated alternative for two-phase immersion cooling architectures in high-performance computing centers.

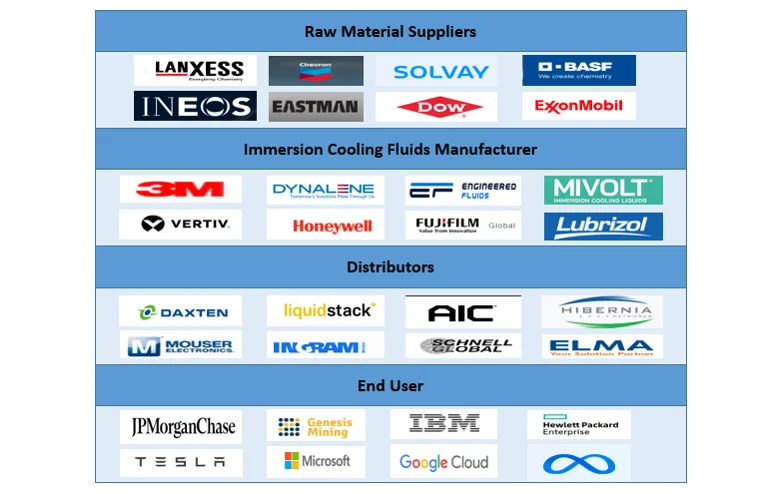
Immersion Cooling Fluids Industry Ecosystem:Immersion Cooling Fluids Industry Ecosystem
Immersion Cooling Fluids Market Scope: Inquire before buying

Immersion Cooling Fluids Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 2.11 Bn.
Forecast Period 2026 to 2034 CAGR: 8.1% Market Size in 2034: USD 4.25 Bn.
Segments Covered: by Cooling Technology Single-Phase Coolant
Two-Phase Coolant
Direct-to-Chip Cooling
Others
by Fluid Type Mineral Oil-Based Fluids
Florocarbon-based Fluids
Synthetic Hydrocarbon Fluids
Others
by Application High-performance Computing
Edge Computing
Cryptocurrency Mining
Artificial Intelligence
Others
by End-Use Industry IT & Data Centers
Semiconductor Manufacturing Facilities
Healthcare & Pharmaceuticals
Food Processing Industry
Energy & Power
Special Laboratories
Telecommunications
Others

Immersion Cooling Fluids Market,by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Immersion Cooling Fluids Market, Key Players are

1.3M Company
2.BASF SE
3.Dow Inc.
4.Shell plc
5.ExxonMobil Corporation
6.Chevron Corporation
7.Cargill, Incorporated
8.Green Revolution Cooling, Inc.
9.TotalEnergies SE
10.Arkema S.A.
11.Lubrizol Corporation
12.FUCHS SE
13.M&i Materials Limited
14.ENEOS Corporation
15.Honeywell International Inc.
16.Engineered Fluids
17.Chemours Company
18.DuPont de Nemours, Inc.
19. Lanxess AG
20. Daikin Industries Ltd.
21. Nynas Ab
22. Valvoline Global Operations
23. Ergon, Speciality Inc.
24. Park Place Technologies
25. SK On Co., Ltd.
26. peasoup.cloud
27. Hydratech
28. ARANER
29. DCX Liquid Cooling Systems, Inc
Others

Frequently Asked Questions:

1] What segments are covered in the Global Immersion Cooling Fluids Market report?
Ans. The segments covered in the Immersion Cooling Fluids Market report are based on Cooling Fluid, Product, Industry, Application.

2] Which region is expected to hold the highest share in the Global Immersion Cooling Fluids Market?
Ans. The North America region is expected to hold the highest share in the Immersion Cooling Fluids Market.

3] What is the market size of the Global Immersion Cooling Fluids Market by 2034?
Ans. The market size of the Immersion Cooling Fluids Market by 2034 is expected to reach USD 4.25 Bn.

4] What is the forecast period for the Global Immersion Cooling Fluids Market?
Ans. The forecast period for the Immersion Cooling Fluids Market is 2026-2034.

5] What was the Global Immersion Cooling Fluids Market size in 2025?
Ans: The Global Immersion Cooling Fluids Market size was USD 2.11 Billion in 2025.

Table of Contents

1.SECTION A – GLOBAL IMMERSION COOLING FLUIDS MARKET INTRODUCTION 1.1 Executive Market Landscape and Industry Overview 1.1.1 Global Immersion Cooling Fluids market overview and application outlook (2025–2034) 1.1.2 Key findings derived from primary and secondary research methodologies 1.1.3 Strategic insights highlighting transformation from air-based to liquid cooling systems 1.1.4 Summary of demand-supply dynamics across major end-use industries 1.1.5 Overview of macroeconomic and regulatory factors influencing cooling technologies 1.1.6 Analysis and recommendations for HVAC engineering firms and stakeholders 1.2 Global Immersion Cooling Fluids Market Dynamics 1.2.1 Immersion Cooling Fluids Market Trends 1.2.2 Immersion Cooling Fluids Market 1.2.3 Drivers 1.2.4 Restraints 1.2.5 Opportunities 1.2.6 Challenges 1.2.7 PORTER’s Five Forces Analysis 1.2.7.1 Supplier power 1.2.7.2 Buyer power 1.2.7.3 Threat of substitutes 1.2.7.4 Threat of new entrants 1.2.7.5 Competitive Rivalry 1.2.8 PESTLE Analysis 1.3 Supply Chain Analysis and Raw Material Procurement Strategies 1.3.1 Overview of global immersion cooling fluid supply chain 1.3.2 Key raw materials including synthetic hydrocarbons, fluorochemicals, silicone oils, mineral oils, and bio-based feedstocks 1.3.3 Role of chemical producers, formulators, distributors, and system integrators 1.3.4 Procurement strategies for data centers, semiconductor fabs, and HVAC&R contractors 1.3.5 Supply chain risks including fluorochemical restrictions, feedstock volatility, and logistics disruptions 1.4 Immersion Cooling Fluids Industry Structure and Ecosystem Overview 1.4.1 Raw material suppliers and specialty chemical producers 1.4.2 Fluid formulators and dielectric fluid manufacturers 1.4.3 Immersion cooling tank and system OEMs 1.4.4 Data center operators, semiconductor companies, laboratories, and HVAC&R engineering firms 1.4.5 Interlinkages across fluid development → system integration → operation → maintenance 1.5 Global Immersion Cooling Fluids Market Statistics 1.5.1 Total volume of immersion cooling fluids deployed globally (Liters) 1.5.2 Installed base of immersion-cooled data centers by region (%) 1.5.3 Average fluid volume per data center rack (Liters per rack) 1.5.4 GPU-enabled immersion-cooled rack penetration rate (%) 1.5.5 Average lifecycle of immersion cooling fluids (Years) 1.5.6 Average thermal load handled per immersion-cooled rack (kW) 1.5.7 Immersion cooling fluid consumption volume by region (Liters) 1.6 Intelligent Analytics (IA) and Smart Liquid Cooling Technology 1.6.1 Integration of Intelligent Analytics (IA) into liquid cooling systems 1.6.2 AI-driven thermal monitoring and real-time cooling optimization 1.6.3 Predictive analytics for temperature, fluid quality, and equipment performance 1.6.4 IoT-enabled sensors and intelligent cooling system controls 1.6.5 Data-driven optimization of cooling energy consumption and thermal efficiency 1.6.6 Integration of IA with data center infrastructure management (DCIM) 1.6.7 Role of machine learning in predictive maintenance and failure detection 1.7 Energy Savings Quantification 1.7.1 Energy savings per MW using immersion cooling (%) 1.7.2 kWh reduction vs air cooling systems 1.7.3 Cooling energy share reduction (%) 1.7.4 Cost savings per data center annually 1.7.5 Efficiency benchmarking across technologies 1.8 Market Penetration and Adoption Rates 1.8.1 % of data centers using immersion cooling 1.8.2 Adoption rate across hyperscale vs enterprise (%) 1.8.3 Penetration by region (%) 1.8.4 Growth in adoption over time (2020–2034) 1.8.5 Conversion rate from air to liquid cooling (%) 1.9 Immersion Cooling Fluids Demand-Supply Gap Analysis (2025–2034) 1.9.1 Global demand vs supply volume gap analysis (liters) 1.9.2 Supply constraints in fluorochemicals and synthetic hydrocarbons 1.9.3 Regional supply-demand imbalance across key markets 1.9.4 Impact of hyperscale data center expansion on supply chain 1.9.5 Inventory trends and stockpiling strategies by OEMs 1.10 Market Evolution Curve and Technology Adoption S-Curve 1.10.1 Historical transition from air → liquid → immersion cooling 1.10.2 Position of immersion cooling on technology adoption lifecycle 1.10.3 Early adopters vs early majority segmentation 1.10.4 Inflection point analysis for mass adoption 1.10.5 Adoption curve forecast by application 1.11 Dielectric Properties and Electrical Performance Analysis 1.11.1 Dielectric strength benchmarking across fluid categories 1.11.2 Electrical insulation performance under high voltage 1.11.3 Impact on short-circuit risk and system safety 1.11.4 Stability of dielectric properties over time 1.11.5 Comparative analysis with traditional cooling mediums 1.12 Trade Flow Analysis Including Imports, Exports, and Tariffs (2025) 1.12.1 Global trade patterns for immersion cooling fluids and specialty chemicals 1.12.2 Import-export analysis across major industrial economies 1.12.3 Tariff structures impacting cost competitiveness of cooling fluids 1.12.4 Regional supply chain dependencies and logistics trends 1.13 Pricing Analysis and Cost Structure of Immersion Cooling Fluids (2025) 1.13.1 Breakdown of raw material, formulation, quality testing, packaging, and logistics cost 1.13.2 Pricing trends across mineral oil, synthetic hydrocarbon, fluorocarbon, silicone, and bio-based fluids 1.13.3 Impact of fluorochemical restrictions and specialty feedstock availability on pricing 1.13.4 Regional pricing variations based on import dependency, logistics, and regulation 1.14 Cost-Benefit Analysis of Immersion Cooling Fluids 1.14.1 Total cost of ownership (TCO) vs air cooling systems 1.14.2 Capex and Opex comparison across cooling technologies 1.14.3 Energy savings and operational cost reduction 1.14.4 Payback period analysis for data centers 1.14.5 Cost sensitivity to raw material price fluctuations 1.15 Retrofit vs Greenfield Deployment Analysis 1.15.1 Adoption in existing data centers (retrofit challenges) 1.15.2 Cost and feasibility of conversion from air cooling 1.15.3 Greenfield data center design advantages 1.15.4 ROI comparison for retrofit vs new builds 1.15.5 Case-based implementation insights 1.16 Rack-Level and Tank-Level Fluid Utilization Analysis 1.16.1 Fluid volume per rack and per MW analysis 1.16.2 Tank design optimization and fluid requirements 1.16.3 Cooling density vs fluid consumption 1.16.4 Modular vs centralized tank configurations 1.16.5 Efficiency benchmarking across configurations 1.17 Comparative Analysis of Liquid Cooling Technologies 1.17.1 Air cooling vs liquid cooling vs immersion cooling 1.17.2 Direct-to-chip liquid cooling vs single-phase immersion cooling 1.17.3 Two-phase immersion cooling vs direct liquid cooling systems 1.17.4 Cold plate, rear-door heat exchanger, and liquid bath cooling comparison 1.17.5 Performance, thermal efficiency, energy consumption, and cost benchmarking 1.17.6 Suitability for AI, HPC, GPU, and high-density data center workloads 1.17.7 Adoption barriers and infrastructure requirements across cooling technologies 1.17.8 Technology transition roadmap from air cooling to advanced liquid cooling 1.18 Data Center Market Overview for Immersion Cooling Fluids 1.18.1 Role of immersion cooling fluids in modern data center infrastructure 1.18.2 Transition from air cooling to liquid immersion systems 1.18.3 Market maturity across hyperscale, colocation, and enterprise data centers 1.18.4 Key drivers: AI workloads, rack density, energy efficiency 1.18.5 Adoption lifecycle across regions 1.19 Global Data Center Statistics 1.19.1 The Global Data Center Capacity in 2025 and Forecast (2026–2034) (MW) 1.19.2 Data center growth statistics (%) 1.19.3 Data center industry trends 1.19.4 Data centers statistics by region, including Africa, Asia, Australia, Europe, North America, and South America 1.19.5 Data centers statistics by country (2025) 1.19.6 Installed Data Center Power Capacity (MW) – Global (2020–2025) 1.19.7 Annual Capacity Additions (MW Added Per Year) (2025) 1.19.8 Hyperscale Data Centers Analysis (2025) 1.19.9 Enterprise Data Centers Analysis (2025) 1.20 Operational & Planned Data Center Expansion Statistics and Regional Market Analysis 1.20.1 Data Center Market Revenue by Region (USD Billion) (2020–2025) 1.20.2 North America 1.20.3 Europe 1.20.4 Middle East & Africa 1.20.5 South America 1.20.6 Installed Data Center Power Capacity (MW) by Region 1.20.7 Data Center Capacity Additions (MW) by Region 1.20.8 Regional CAGR Comparison (%) 1.20.9 Top 10 Countries by Data Center Demand (2025) 1.20.10 Global Data Center Additions by Region (MW, 2025–2034) 1.21 Colocation Data Centers Analysis (2025) 1.21.1 Number of colocation facilities globally in 2025 1.21.2 Total installed colocation power capacity (MW) 1.21.3 Annual MW added (growth rate %) 1.21.4 Share of total data center market (%) 1.21.5 Total IT load installed (MW) 1.21.6 Capacity per MW of facility (%) 1.22 Rack Density and Thermal Load Analysis 1.22.1 Average rack density evolution (kW per rack) 1.22.2 GPU-intensive workloads driving thermal output 1.22.3 Heat dissipation requirements for AI clusters 1.22.4 Comparison with traditional CPU-based loads 1.22.5 Cooling thresholds triggering immersion adoption 1.23 Fluid Consumption per Data Center (Volume Benchmarking) 1.23.1 Fluid volume requirement per MW of IT load 1.23.2 Consumption per rack and per server unit 1.23.3 Variation across single-phase vs two-phase systems 1.23.4 Refill and replacement frequency analysis 1.23.5 Scaling impact for hyperscale deployments 1.24 Single-Phase vs Two-Phase Adoption in Data Centers 1.24.1 Adoption split across data center types 1.24.2 Performance comparison in real-world deployments 1.24.3 Cost and complexity differences 1.24.4 Suitability for AI vs general workloads 1.24.5 Future adoption trends 1.25 Hyperscale Data Center Adoption Analysis 1.25.1 Adoption by major hyperscalers (AWS, Google, Microsoft, Meta) 1.25.2 Deployment scale and fluid requirements 1.25.3 Strategic partnerships with cooling solution providers 1.25.4 Capex investment trends in immersion cooling 1.25.5 Roadmap for large-scale deployment 1.26 Fluid Lifecycle Management in Data Centers 1.26.1 Monitoring of fluid quality and degradation 1.26.2 Filtration and purification processes 1.26.3 Replacement cycles and operational impact 1.26.4 Contamination risks and mitigation 1.26.5 Maintenance protocols 1.27 Data Center Deployment Case Studies 1.27.1 Real-world immersion cooling implementations 1.27.2 Performance outcomes and efficiency gains 1.27.3 Fluid consumption and cost analysis 1.27.4 Lessons learned from early adopters 1.27.5 Best practices for scaling 1.28 AI and GPU Cluster Cooling Requirements 1.28.1 Cooling needs for AI training clusters 1.28.2 GPU thermal output benchmarking 1.28.3 Fluid performance under extreme workloads 1.28.4 Future demand from AI-driven infrastructure 1.28.5 Scaling challenges for next-gen chips 1.29 Future Liquid Cooling, IA, and Data Center Technology Trends (2026–2034) 1.29.1 Growth of AI-native and high-density data center infrastructure 1.29.2 Rising adoption of liquid cooling for AI and GPU clusters 1.29.3 Integration of IA, AI, and machine learning with thermal management 1.29.4 Evolution of direct-to-chip, immersion, and hybrid liquid cooling architectures 1.29.5 Increasing rack densities and thermal loads exceeding 100 kW per rack 1.29.6 Development of autonomous and predictive liquid cooling systems 1.29.7 Integration of liquid cooling with DCIM and smart data center platforms 1.29.8 Emergence of closed-loop, energy-efficient, and sustainable cooling systems 1.29.9 Technology roadmap for next-generation intelligent liquid cooling infrastructure 1.30 Market Entry Barriers and Competitive Challenges 1.30.1 High R&D and formulation complexity 1.30.2 Regulatory barriers for new fluid chemistries 1.30.3 Customer trust and adoption challenges 1.30.4 Capital investment requirements 1.30.5 Competitive pressure from established players 1.31 Market Disruption and Substitution Threat Analysis 1.31.1 Threat from direct-to-chip liquid cooling 1.31.2 Emerging alternatives to immersion cooling 1.31.3 Technology substitution risk timeline 1.31.4 Defensive strategies for fluid manufacturers 1.31.5 Disruption readiness assessment 1.32 Sustainability and Environmental Impact Analysis 1.32.1 Carbon footprint comparison: air cooling vs immersion cooling 1.32.2 Lifecycle analysis of immersion cooling fluids 1.32.3 Biodegradability and recyclability of fluids 1.32.4 Waste management and disposal challenges 1.32.5 Adoption of low-GWP and eco-friendly fluids 1.33 Risk Analysis and Market Uncertainties 1.33.1 Raw material price volatility risks 1.33.2 Regulatory risks (PFAS bans, environmental laws) 1.33.3 Technological risks and adoption barriers 1.33.4 Supply chain disruptions and geopolitical risks 1.33.5 Market entry barriers for new players 1.34 Investment Hotspots and High-Growth Pockets 1.34.1 Top high-growth regions and countries 1.34.2 Fastest-growing applications (AI, HPC, EV) 1.34.3 Emerging fluid technologies attracting investment 1.34.4 Untapped markets with low competition 1.34.5 Short-term vs long-term opportunity zones 1.35 Innovation Pipeline and R&D Investments 1.35.1 R&D spending trends in cooling fluid development 1.35.2 Emerging technologies (nanofluids, hybrid fluids) 1.35.3 Patent landscape analysis 1.35.4 Collaboration between academia and industry 1.35.5 Innovation roadmap (2025–2034) 1.36 Standardization and Industry Protocols 1.36.1 Emerging global standards for immersion cooling fluids 1.36.2 Testing protocols for dielectric fluids 1.36.3 Data center design standards for immersion systems 1.36.4 Certification frameworks and compliance benchmarks 1.36.5 Industry consortiums and standard bodies 1.37 Fluid Testing, Quality Assurance, and Certification 1.37.1 Laboratory testing protocols for fluid performance 1.37.2 Quality control standards during manufacturing 1.37.3 Certification processes for industrial usage 1.37.4 Degradation and contamination testing methods 1.37.5 Third-party validation frameworks 1.38 Regulatory and Compliance Framework for Immersion Cooling Fluids 1.38.1 Overview of global regulatory standards (REACH, EPA, EU directives) 1.38.2 Environmental and safety regulations impacting fluid selection 1.38.3 Compliance requirements for cleanroom and controlled environments (GMP, ISO, HACCP) 1.38.4 Challenges faced by manufacturers and end users in regulatory adherence 1.38.5 Regional variations in regulatory frameworks 1.38.6 Future regulatory trends influencing market adoption 1.39 Global Immersion Cooling Fluids Market: Market size and Forecast by Segmentation (by Value USD Billion and Volume in Liter) (2025–2034) 1.39.1 Global Immersion Cooling Fluids Market Size and Forecast, By Cooling Technology 1.39.1.1 Single-Phase Coolant 1.39.1.2 Two-Phase Coolant 1.39.2 Global Immersion Cooling Fluids Market Size and Forecast, By Fluid Type 1.39.2.1 Mineral Oil-Based Fluids 1.39.2.2 Florocarbon-based Fluids 1.39.2.3 Synthetic Hydrocarbon Fluids 1.39.2.4 Others 1.39.3 Global Immersion Cooling Fluids Market Size and Forecast, By Application 1.39.3.1 Data Centers (Hyperscale & Enterprise) 1.39.3.2 Hyperscale Data Centers 1.39.3.3 Colocation Facilities 1.39.3.4 Enterprise Data Centers 1.39.3.5 Edge/Micro Data Centers 1.39.3.6 High-Performance Computing (HPC) 1.39.3.7 Artificial Intelligence (AI) & Machine Learning Clusters 1.39.3.8 Cryptocurrency Mining 1.39.3.9 Edge Computing Infrastructure 1.39.3.10 Electric Vehicles (EV Batteries, Power Electronics, Motors) 1.39.3.11 Transformers & Power Electronics 1.39.3.12 Others 1.39.4 Global Immersion Cooling Fluids Market Size and Forecast, By End-Use Industry 1.39.4.1 IT & Telecom 1.39.4.2 Automotive & EV Manufacturing 1.39.4.3 Energy & Power (Transformers, grid systems) 1.39.4.4 Electronics & Semiconductor Manufacturing 1.39.4.5 Industrial Manufacturing 1.39.4.6 Healthcare & Research Facilities 1.39.4.7 Others 1.39.5 Global Immersion Cooling Fluids Market Size and Forecast, By Region 1.39.5.1 North America 1.39.5.1.1 United States 1.39.5.1.2 Canada 1.39.5.1.3 Mexico 1.39.5.2 Europe 1.39.5.2.1 United Kingdom 1.39.5.2.2 France 1.39.5.2.3 Germany 1.39.5.2.4 Italy 1.39.5.2.5 Spain 1.39.5.2.6 Sweden 1.39.5.2.7 Russia 1.39.5.2.8 Rest of Europe 1.39.5.3 Asia Pacific 1.39.5.3.1 China 1.39.5.3.2 S. Korea 1.39.5.3.3 India 1.39.5.3.4 Japan 1.39.5.3.5 Australia 1.39.5.3.6 Indonesia 1.39.5.3.7 Philippines 1.39.5.3.8 Malaysia 1.39.5.3.9 Vietnam 1.39.5.3.10 Thailand 1.39.5.3.11 Rest of Asia Pacific 1.39.5.4 Middle East and Africa 1.39.5.4.1 South Africa 1.39.5.4.2 GCC 1.39.5.4.3 Egypt 1.39.5.4.4 Nigeria 1.39.5.4.5 Rest of ME&A 1.39.5.5 South America 1.39.5.5.1 Brazil 1.39.5.5.2 Argentina 1.39.5.5.3 Chile 1.39.5.5.4 Colombia 1.39.5.5.5 Rest Of South America 2.SECTION B – COMPETITIVE INTELLIGENCE & INDUSTRIAL ECOSYSTEM 2.1 Company Profiles: Key Players 2.1.1 Overview 2.1.2 Business Portfolio 2.1.3 Financial Overview 2.1.4 SWOT Analysis 2.1.5 Strategic Analysis 2.1.6 Recent Developments 2.1.7 3M Company 2.1.8 BASF SE 2.1.9 Dow Inc. 2.1.10 Shell plc 2.1.11 ExxonMobil Corporation 2.1.12 Chevron Corporation 2.1.13 Cargill, Incorporated 2.1.14 Green Revolution Cooling, Inc. 2.1.15 TotalEnergies SE 2.1.16 Arkema S.A. 2.1.17 Lubrizol Corporation 2.1.18 FUCHS SE 2.1.19 M&i Materials Limited 2.1.20 ENEOS Corporation 2.1.21 Honeywell International Inc. 2.1.22 Engineered Fluids 2.1.23 Chemours Company 2.1.24 DuPont de Nemours, Inc. 2.1.25 Lanxess AG 2.1.26 Daikin Industries Ltd. 2.1.27 Nynas Ab 2.1.28 Valvoline Global Operations 2.1.29 Ergon, Speciality Inc. 2.1.30 Park Place Technologies 2.1.31 SK On Co., Ltd. 2.1.32 peasoup.cloud 2.1.33 Hydratech 2.1.34 ARANER 2.1.35 DCX Liquid Cooling Systems, Inc 2.1.36 Others 2.2 Global Market Concentration and Herfindahl-Hirschman Index (HHI) Analysis in Immersion Cooling Fluids Market 2.2.1 Global market concentration ratios by fluid type (mineral oil, synthetic hydrocarbons, fluorocarbon-based, bio-based fluids) 2.2.2 Regional Herfindahl-Hirschman Index (HHI) comparison across North America, Europe, and Asia-Pacific 2.2.3 Market fragmentation vs consolidation trends among Tier-1 (global chemical majors) and Tier-2 (specialty fluid manufacturers) 2.2.4 Impact of mergers and acquisitions on market share shifts and competitive positioning 2.2.5 Evaluation of vertical integration strategies (feedstock sourcing → fluid formulation → distribution → end-use deployment) 2.3 Top OEM and Tier-1/Tier-2 Supplier Market Share Analysis 2.3.1 Global and regional revenue share by fluid type and application (data centers, semiconductor, labs) 2.3.2 Top Tier-1 immersion cooling fluid manufacturers’ contribution to global output 2.3.3 Ranking of Tier-2 and Tier-3 specialty chemical and dielectric fluid suppliers 2.3.4 Comparative analysis of OEM-supplier dependency and sourcing diversification 2.3.5 Role of long-term supply agreements and approved vendor lists (AVL) in market share distribution 2.4 Emerging Entrants and Niche Specialists in Immersion Cooling Fluids Market 2.4.1 Analysis of new market participants, specialized formulation companies, and innovation-driven startups 2.4.2 Growth of PFAS-free and environmentally sustainable fluid developers 2.4.3 Emergence of niche specialists in high-performance dielectric fluids and two-phase cooling solutions 2.4.4 Role of small and mid-sized chemical firms in customized fluid development 2.4.5 Strategic acquisitions of niche players by large chemical companies 2.4.6 Entry of startups focusing on smart cooling fluids and monitoring-enabled solutions 2.5 Market Share and Competitive Positioning Analysis (2025) 2.5.1 Evaluation of competitive landscape, leadership positioning, and segment-wise dominance among fluid manufacturers 2.5.2 Market share distribution by fluid type (fluorocarbon, synthetic hydrocarbon, mineral oil, silicone, bio-based) 2.5.3 Leadership in high-performance and semiconductor-grade cooling fluids by key global players 2.6 Detailed Manufacturer Benchmarking and Company Profiling 2.6.1 In-depth comparison of leading immersion cooling fluid manufacturers based on product portfolio, production capabilities, and market positioning 2.6.2 Company profiles and headquarters overview of key players 2.6.3 Product portfolio analysis including dielectric fluids, specialty cooling fluids, and hybrid solutions 2.6.4 Production capacity and formulation technology analysis 2.6.5 Revenue performance and financial positioning 2.6.6 Customer base segmentation including data center operators, semiconductor companies, and system integrators 2.7 Technology and Innovation Comparison Across Key Players 2.7.1 Assessment of technological advancements, formulation innovation, and differentiation strategies among fluid manufacturers 2.7.2 Development of low-viscosity, high thermal conductivity dielectric fluids 2.7.3 Advancements in two-phase immersion cooling fluids and boiling heat transfer technologies 2.7.4 Adoption of PFAS-free and low-GWP fluid alternatives 2.8 Revenue Performance and Financial Analysis (2025) 2.8.1 Comparative financial performance analysis of leading immersion cooling fluid manufacturers across regions and product segments 2.8.2 Revenue comparison across major players in data center and semiconductor cooling markets 2.8.3 Segment-wise revenue contribution (single-phase vs two-phase fluids, application-based segmentation) 2.9 Strategic Positioning and Competitive Outlook in Immersion Cooling Fluids Market 2.9.1 Forward-looking analysis of competitive strategies, market expansion plans, and evolving industry dynamics 2.9.2 Competitive advantages including product performance, sustainability compliance, and supply chain reliability 2.9.3 Differentiation strategies based on innovation, material capabilities, and pricing models 2.10 Strategic Alliances and Partnership Analysis 2.10.1 Joint ventures between chemical companies and data center operators 2.10.2 Partnerships with hyperscalers 2.10.3 Technology collaboration with OEMs 2.10.4 Strategic agreements for supply chain stability 2.10.5 Impact of alliances on market expansion 2.11 Mergers & Acquisitions (M&A) Landscape 2.11.1 Recent M&A transactions in cooling fluids and data center ecosystem 2.11.2 Deal size analysis ($ million/billion) 2.11.3 Strategic rationale behind acquisitions 2.11.4 Consolidation trends in chemical and cooling markets 2.11.5 Future M&A outlook 2.12 Exit Strategy and Valuation Analysis 2.12.1 Exit routes (IPO, acquisition, strategic sale) 2.12.2 Valuation multiples (EV/EBITDA, P/E) 2.12.3 Comparable company analysis 2.12.4 Exit timeline expectations 2.12.5 Investor return scenario 3.SECTION C – KEY INSIGHTS, STRATEGIC OUTLOOK & METHODOLOGICAL FRAMEWORK 3.1 Key Findings 3.2 Strategic Moves & Industry Outlook 3.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements