
Global Reinsurance Market by Type, by Form, by Application, by Distribution Channel, by Region and Forecast 2034
Overview
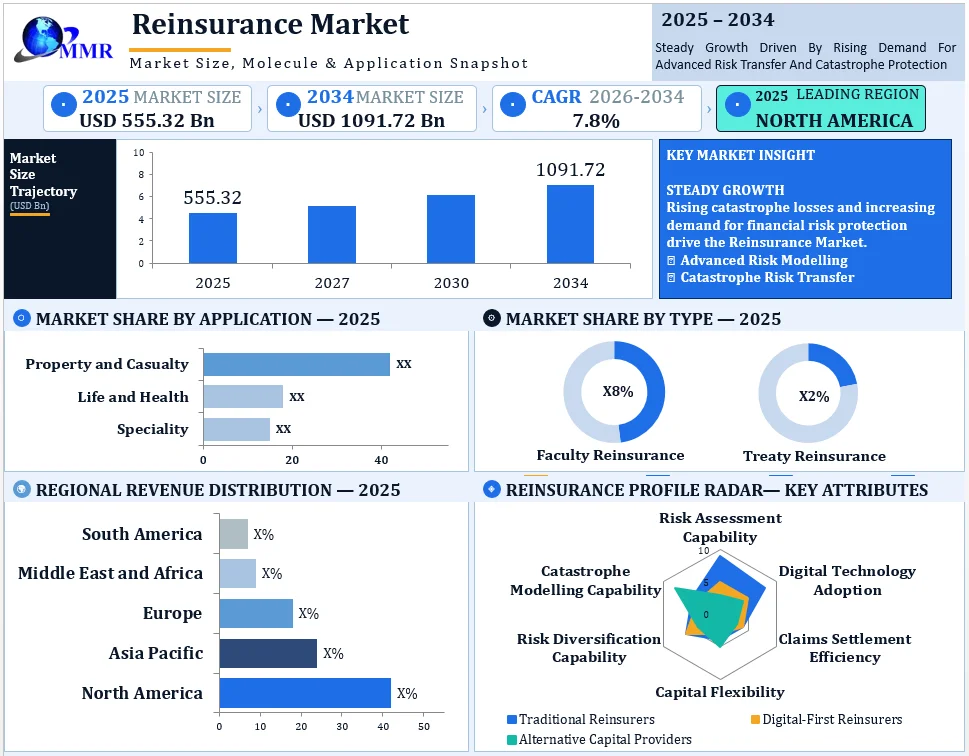
Global Reinsurance Market size was valued at USD 555.32 Billion in 2025 and the total Global Reinsurance Market revenue is expected to grow at a CAGR of 7.8% from 2026 to 2034, reaching USD 1091.72 Billion by 2034.
Global Reinsurance Market Overview:
The Reinsurance Market refers to the financial services industry in which reinsurers provide insurance coverage to primary insurance companies, helping them transfer a portion of their financial risks. Reinsurance strengthens insurer solvency, supports underwriting capacity, and protects against substantial claims arising from natural disasters, health emergencies, property damage, and other unexpected losses.
The Reinsurance Market is evolving as climate-related disasters, rising asset values, cyber threats, and increasingly complex financial risks increase insurers’ need for effective risk transfer and capital management solutions. North America remains a major regional market, while established players such as Swiss Re provide specialized reinsurance solutions, advanced risk modelling, and underwriting expertise. The International Association of Insurance Supervisors highlights the importance of monitoring reinsurance capacity, financial resilience, and emerging risks across international insurance markets. Demand from property and casualty insurers, life and health insurers, and commercial insurance providers is creating opportunities for treaty reinsurance, facultative coverage, catastrophe risk transfer, and alternative reinsurance solutions.
The MMR report provides a comprehensive assessment of the Global Reinsurance Market, including market dynamics, segmentation, regional performance, competitive positioning, and emerging industry trends. Growth opportunities include artificial intelligence-based risk assessment, climate risk protection, cyber reinsurance, insurance-linked securities, and greater insurance penetration in developing economies, helping reinsurers strengthen risk management capabilities and address evolving protection needs.
Reinsurance Market Growth Outlook
To know about the Research Methodology :- Request Free Sample Report
Global Reinsurance Market Key Highlights
| Key Highlight | Analytical Insight | Market Impact |
| Strong Market Growth Outlook | The Reinsurance Market is projected to grow from USD 555.32 billion in 2025 to USD 1091.72 billion by 2034, at a compound annual growth rate of 7.8%. | Creates opportunities for reinsurers to strengthen underwriting capacity, diversify portfolios, and develop specialized risk-transfer solutions. |
| Treaty Reinsurance Maintains Market Leadership | Treaty reinsurance benefits from portfolio-wide coverage, predictable risk transfer, and administrative efficiency for insurers managing recurring exposures. | Supports stable demand from property and casualty, life, and health insurance providers. |
| North America Remains a Major Regional Market | Strong insurance penetration, substantial insured asset values, catastrophe exposure, and established reinsurance infrastructure reinforce the region's competitive position. | Encourages investment in catastrophe modelling, property risk protection, and advanced underwriting capabilities. |
| Alternative Capital Reshapes Risk Transfer | Catastrophe bonds, insurance-linked securities, and collateralized reinsurance give insurers additional ways to transfer large and complex risks beyond traditional reinsurance agreements. | Broadens available risk-bearing capacity and connects reinsurance with institutional investment markets. |
| Artificial Intelligence and Cyber Risk Create New Opportunities | Predictive analytics, automated underwriting, climate risk modelling, and specialized cyber coverage are changing how reinsurers assess emerging and interconnected exposures. | Improves risk selection and creates opportunities for differentiated products, more precise pricing, and specialized coverage. |
Global Reinsurance Market Dynamics:
Rising Catastrophe Losses and Insurer Demand Strengthen Reinsurance Market Growth
The Reinsurance Market is gaining momentum as insurance companies seek stronger financial protection against natural disasters, rising property values, cyber incidents, and increasingly severe claims. According to Swiss Re Institute, insured natural catastrophe losses reached USD 137 billion in 2025, highlighting the growing importance of reinsurance capacity and catastrophe risk management. Primary insurers increasingly use treaty reinsurance to protect entire portfolios and facultative reinsurance to transfer risks associated with individual high-value properties, infrastructure projects, and commercial assets. Growing demand for life and health protection, regulatory capital requirements, and the need to maintain underwriting stability are also strengthening reinsurance purchasing among insurance providers. These factors are supporting demand for property and casualty reinsurance, life reinsurance, and specialized risk transfer solutions.
High Reinsurance Premiums and Coverage Affordability Limit Reinsurance Market Adoption
High reinsurance premiums, stricter underwriting conditions, and increased capital requirements can restrict reinsurance purchasing, particularly among small and medium-sized insurance companies operating with limited financial resources. Reinsurers may also introduce higher deductibles, coverage exclusions, and stricter risk selection to manage potential claims, encouraging primary insurers to retain a greater proportion of their risks. These pressures can reduce demand for comprehensive property catastrophe reinsurance, create affordability concerns in developing insurance markets, and limit access to specialized coverage for high-risk commercial assets.
Artificial Intelligence and Alternative Risk Transfer Create Reinsurance Market Opportunities
The Reinsurance Market presents strong opportunities through artificial intelligence-based underwriting, advanced catastrophe modelling, cyber risk protection, and alternative risk transfer solutions. According to Swiss Re Institute, traditional reinsurance capital stood at approximately USD 500 billion in early 2025, with an additional USD 50 billion available through the catastrophe bond market, illustrating the importance of combining conventional and alternative capital sources. Insurance-linked securities, catastrophe bonds, and collateralized reinsurance can help insurers transfer complex risks while giving institutional investors access to insurance-related returns. Further opportunities arise from low insurance penetration in developing economies, renewable energy infrastructure, healthcare protection, and growing cyber exposures. Reinsurers that combine predictive analytics with customized treaty structures and specialized facultative coverage can improve risk selection and serve emerging protection needs.
Climate Uncertainty and Complex Risk Assessment Pressure Reinsurance Market Performance
The Reinsurance Market faces significant challenges from unpredictable catastrophe losses, climate-related exposure changes, cyber accumulation risks, and increasingly complex claims assessment. The International Association of Insurance Supervisors reported that its analysis of selected non-life insurers found an average capital adequacy impact of 34 percentage points under a severe natural catastrophe scenario equivalent to a one-in-two-hundred-year event, before considering the broader implications for individual companies. Such exposure highlights the difficulty of estimating extreme losses, maintaining sufficient reserves, and setting sustainable premiums across different regions. Reinsurers must also address inconsistent data quality, interconnected cyber threats, regulatory differences, and potential investment volatility. Developing reliable risk models, maintaining adequate capital buffers, and balancing competitive pricing with long-term underwriting profitability remain essential to strengthening market resilience.
Reinsurance Market Key Trends
| Market Trend | Description |
| Artificial Intelligence in Reinsurance Underwriting | Reinsurers are adopting artificial intelligence, predictive analytics, and automated claims assessment to improve risk selection, identify unusual claims patterns, and refine underwriting decisions. These tools are becoming particularly relevant as cyber threats and interconnected risks become more difficult to evaluate. |
| Rising Adoption of Catastrophe Bonds and Alternative Capital | Insurance-linked securities and catastrophe bonds are becoming important sources of reinsurance capacity. Aon reported that outstanding catastrophe bond volume reached a record USD 63.4 billion by June 2026, reflecting growing investor participation in transferring catastrophe risks from insurers to capital markets. |
| Growing Demand for Cyber Reinsurance | Increasing ransomware incidents, cloud service disruptions, and artificial intelligence-related threats are driving demand for specialized cyber reinsurance. Reinsurers are refining policy limits, exclusions, and risk accumulation controls to manage losses arising from a single cyber event affecting multiple insured businesses. |
| Climate Risk Modelling and Portfolio Diversification | Reinsurers are reassessing catastrophe exposure as wildfire, flooding, severe storms, and other weather-related risks affect more locations. Companies are using improved catastrophe models and adjusting portfolio allocations to balance potential losses across regions and insurance categories. |
| Increased Use of Facultative Reinsurance | Insurers are showing greater interest in facultative reinsurance to obtain tailored protection for individual properties, infrastructure projects, and complex commercial risks. A 2026 Willis Towers Watson survey found that 60% of surveyed insurers planned to increase their use of facultative reinsurance, reflecting its role in capital management and specialized risk placement. |
| More Competitive Reinsurance Pricing and Flexible Coverage | Strong capital availability is increasing competition among reinsurers, particularly in property catastrophe coverage. S&P Global Ratings reported rate reductions across many reinsurance lines during the 2026 renewal season, encouraging insurers to compare terms, negotiate coverage structures, and reassess the balance between retained risk and external protection. |
Reinsurance Market Segment Analysis:
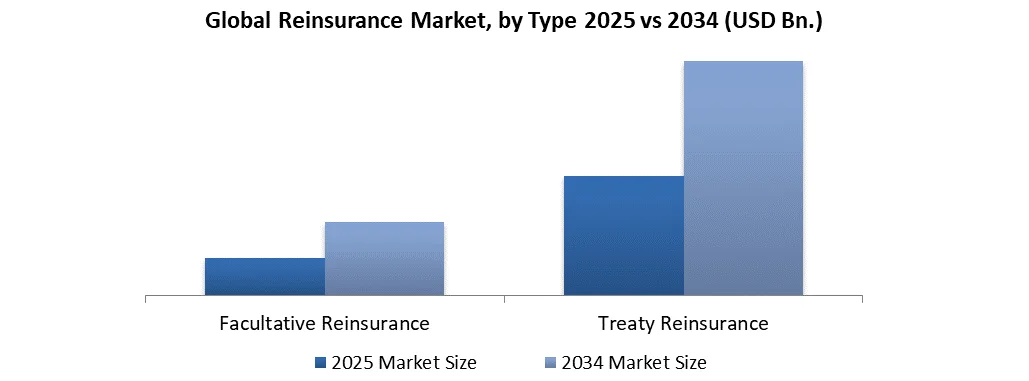
Based on Type the market is segmented into Facultative Reinsurance, Treaty Reinsurance. Treaty reinsurance is dominated the market in 2025 & is expected to hold the largest market share during the forecast period. Due to its structured and long-term agreement nature, where reinsurers cover a portfolio of policies rather than individual risks.
Treaty reinsurance offers insurers greater stability, predictable coverage, and administrative efficiency compared to facultative reinsurance, which requires individual negotiations for each risk. The increasing demand for comprehensive risk management, cost optimization, and capacity enhancement for insurers has further boosted the adoption of treaty reinsurance. It is widely preferred by large insurers for handling high-volume and recurring risks in life, health, and property segments, making it the leading segment.
Based on Form, the market is segmented into Traditional Reinsurance and Alternative Reinsurance (ART). Traditional reinsurance dominated the market in 2025 and is expected to hold the largest market share during the forecast period. This is because traditional reinsurance methods, including treaty and facultative arrangements, have been long-established and widely accepted by insurers for risk transfer and capital management.
They provide reliability, regulatory compliance, and flexibility for covering both life and non-life risks. Alternative reinsurance solutions like catastrophe bonds and insurance-linked securities are gaining traction, their adoption is still limited compared to traditional reinsurance, making the latter the preferred choice in 2025.
Reinsurance Market Regional Analysis:
The study provides a brief overview of the reinsurance market's major regions, including APAC, North America, Europe, South America, and the Middle East, and Africa. North America had the largest market share in 2025, with a global market premium of more than xx %, followed by Europe and Asia. North America, notably the United States, will continue to play an important role that cannot be overlooked. Any changes in the United States could have an impact on the reinsurance industry's growth trajectory.
Due to the losses experienced in 2025, global reinsurance capital, a measure of the capital available for insurers to swap risk with, fell 3% in 2025. Higher interest rates, which pushed unrealized losses in bond portfolios, the strengthening dollar, and the fourth-quarter stock market collapse all contributed to a 5% decline in conventional capital in 2025.
The objective of the report is to present a comprehensive analysis of the global Reinsurance market to the stakeholders in the industry. The past and current status of the industry with the forecasted market size and trends are presented in the report with the analysis of complicated data in simple language. The report covers all the aspects of the industry with a dedicated study of key players that include market leaders, followers, and new entrants.
PORTER, PESTEL analysis with the potential impact of micro-economic factors of the market have been presented in the report. External as well as internal factors that are supposed to affect the business positively or negatively have been analyzed, which will give a clear futuristic view of the industry to the decision-makers.
The report also helps in understanding the global Reinsurance market dynamics, structure by analyzing the market segments and project the global Reinsurance market size. Clear representation of competitive analysis of key players by product, price, financial position, product portfolio, growth strategies, and regional presence in the global Reinsurance market make the report investor’s guide.
Reinsurance Market Competitive Landscape
The Reinsurance Market is characterized by strong competition among established reinsurers that differentiate themselves through financial strength, underwriting expertise, global distribution networks, catastrophe risk modelling, and diversified reinsurance portfolios. According to the 2025 rankings published by S&P Global Ratings, Munich Re, Swiss Re, and Hannover Re ranked among the leading reinsurers based on reported reinsurance premiums and revenue, while Berkshire Hathaway, Lloyd’s, and SCOR maintain important competitive positions across property and casualty, life and health, and specialty reinsurance. Market participants are strengthening their competitive advantage through advanced actuarial analytics, artificial intelligence-based underwriting, customized treaty and facultative reinsurance contracts, and alternative risk transfer solutions. Competition also depends on capital availability, pricing discipline, claims management, and the ability to assess climate-related disasters and emerging cyber exposures. As insurers seek reliable risk protection and improved capital efficiency, reinsurers with diversified portfolios, strong balance sheets, and innovative risk management capabilities are well positioned to capture future Reinsurance Market opportunities.
Reinsurance Market – Key Players by Region and by Country
| REGION | COUNTRY | COMPANY NAME / KEY PLAYER |
|---|---|---|
| North America |
United States |
RGA Reinsurance Company |
| General Reinsurance Corporation (Gen Re) | ||
| National Indemnity Company (Berkshire Hathaway) |
||
| Transatlantic Reinsurance Company (TransRe) |
||
| Odyssey Reinsurance Company | ||
| Everest Reinsurance Company | ||
| Munich Reinsurance America, Inc. | ||
| Swiss Reinsurance America Corporation | ||
| SCOR Reinsurance Company | ||
| Arch Reinsurance Company | ||
| Munich American Reassurance Company | ||
| Canada | SCOR Canada Reinsurance Company | |
| Munich Reinsurance Company of Canada | ||
| Mexico | Reaseguradora Patria, S.A. | |
| Bermuda | Renaissance Reinsurance Ltd. | |
| Everest Reinsurance (Bermuda) Ltd. | ||
| Arch Reinsurance Ltd. | ||
| Partner Reinsurance Company Ltd. (PartnerRe) |
||
| AXA XL Reinsurance Ltd. | ||
| Convex Re Ltd. | ||
| Chubb Tempest Reinsurance Ltd. | ||
| DaVinci Reinsurance Ltd. | ||
| Athene Life Re Ltd. | ||
| Fortitude Reinsurance Company Ltd. | ||
| Hannover Re (Bermuda) Ltd. | ||
| Europe | Germany | Munich Reinsurance Company (Munich Re) |
| Hannover Rück SE (Hannover Re) | ||
| General Reinsurance AG (Gen Re) | ||
| Deutsche Rückversicherung AG | ||
| DEVK Rückversicherungs- und Beteiligungs-AG (DEVK Re) |
||
| E+S Rückversicherung AG | ||
| Switzerland | Swiss Reinsurance Company Ltd. (Swiss Re) | |
| New Reinsurance Company Ltd. (NewRe) | ||
| UNIQA Re AG | ||
| Echo Rückversicherungs-AG | ||
| Renaissance Reinsurance Europe AG | ||
| Deutsche Rückversicherung Schweiz AG | ||
| France | SCOR SE | |
| Caisse Centrale de Réassurance (CCR) | ||
| Arundo Re | ||
| Spain | MAPFRE RE, Compañía de Reaseguros, S.A. | |
| Nacional de Reaseguros, S.A. | ||
| Ireland | RGA International Reinsurance Company dac | |
| Partner Reinsurance Europe SE | ||
| SCOR Global Reinsurance Ireland DAC | ||
| Arch Reinsurance Europe Underwriting DAC | ||
| Hannover Reinsurance (Ireland) DAC | ||
| Luxembourg | Swiss Re Europe S.A. | |
| Czech Republic |
VIG RE zajišťovna, a.s. | |
| Poland | Polskie Towarzystwo Reasekuracji S.A. (Polish Re) |
|
| Slovenia | Sava Reinsurance Company d.d. (Sava Re) | |
| Triglav Re, Reinsurance Company Ltd. | ||
| Bosnia and Herzegovina |
Bosna Reosiguranje d.d. Sarajevo | |
| Türkiye | Milli Reasürans T.A.Ş. | |
| Asia Pacific |
China | China Life Reinsurance Company Ltd. |
| China Property & Casualty Reinsurance Company Ltd. |
||
| PICC Reinsurance Company Ltd. | ||
| Hong Kong | Peak Reinsurance Company Limited (Peak Re) | |
| Taiping Reinsurance Company Limited | ||
| Japan | The Toa Reinsurance Company, Limited | |
| South Korea |
Korean Reinsurance Company (Korean Re) | |
| India | General Insurance Corporation of India (GIC Re) |
|
| Valueattics Reinsurance Limited | ||
| Allianz Jio Reinsurance Limited | ||
| Taiwan | Central Reinsurance Corporation | |
| Malaysia | Malaysian Reinsurance Berhad | |
| Malaysian Life Reinsurance Group Berhad (ML Re) |
||
| Indonesia | PT Reasuransi Indonesia Utama (Indonesia Re) |
|
| PT Reasuransi Nasional Indonesia (Nasional Re) |
||
| Thailand | Thai Reinsurance Public Company Limited | |
| Asian Reinsurance Corporation (Asian Re) | ||
| Pakistan | Pakistan Reinsurance Company Limited | |
| Nepal | Nepal Reinsurance Company Limited | |
| Himalayan Reinsurance Limited | ||
| Singapore | Swiss Re Asia Pte. Ltd. | |
| SCOR Reinsurance Asia-Pacific Pte. Ltd. | ||
| Australia | Hannover Life Re of Australasia Ltd. | |
| Munich Reinsurance Company of Australasia Limited |
||
| RGA Reinsurance Company of Australia Limited |
||
| Swiss Re Life & Health Australia Limited |
||
| SCOR Global Life Australia Pty Limited | ||
| Middle East & Africa |
Saudi Arabia |
Saudi Reinsurance Company (Saudi Re) |
| Kuwait | Kuwait Reinsurance Company K.S.C.P. (Kuwait Re) |
|
| Bahrain | Hannover ReTakaful B.S.C. | |
| Nigeria | African Reinsurance Corporation (Africa Re) |
|
| Continental Reinsurance Plc | ||
| Kenya | Kenya Reinsurance Corporation Limited (Kenya Re) |
|
| ZEP-RE (PTA Reinsurance Company) | ||
| South Africa |
Swiss Re Africa Ltd. | |
| General Reinsurance Africa Ltd. | ||
| Hannover Re South Africa Ltd. | ||
| Ghana | Ghana Reinsurance PLC (Ghana Re) | |
| Morocco | Atlantic Re | |
| Algeria | Compagnie Centrale de Réassurance (CCR Algeria) |
|
| Tunisia | Société Tunisienne de Réassurance (Tunis Re) |
|
| Togo | CICA-RE | |
| Senegal | Société Sénégalaise de Réassurance (SEN-RE) |
|
| Sierra Leone |
WAICA Reinsurance Corporation Plc | |
| Ethiopia | Ethiopian Reinsurance Share Company (Ethiopian Re) |
|
| Tanzania | Tanzania Reinsurance Company Limited (TAN-RE) |
|
| South America |
Brazil | IRB-Brasil Resseguros S.A. (IRB(Re)) |
| Austral Resseguradora S.A. | ||
| Argentina | Nación Reaseguros S.A. | |
| Allianz Re Argentina S.A. | ||
| Berkley Argentina de Reaseguros S.A. |
Reinsurance Market Scope: Inquire before buying
| Global Reinsurance Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 555.32 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 7.8% | Market Size in 2034: | USD 1091.72 Bn. |
| Segments Covered: | by Type | Facultative Reinsurance Treaty Reinsurance |
|
| by Form | Traditional Reinsurance Alternative Reinsurance (ART) |
||
| by Application | Property & Casualty (P&C) Life & Health Specialty |
||
| by Distribution Channel | Direct Writing Broker |
||
Reinsurance Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)
Frequently Asked Questions:
1) What was the market size of Global Reinsurance Market markets in 2025?
Ans - Global Reinsurance Market was worth USD 555.32 Bn in 2025.
2) What is the market segment of the Reinsurance Market?
Ans -The market segments are based on Type, Form, Distribution Channel and Application.
3) What is the forecast period considered for Global Reinsurance Market?
Ans -The forecast period for Global Reinsurance Market is 2026 to 2034.
4) What is the market size of Global Reinsurance Market markets in 2034?
Ans – Global Reinsurance is estimated as worth USD 1091.72 Bn.
5) Which region is dominated in Global Reinsurance Market?
Ans -In 2025, the North America region dominated the Global market.