Polyolefin Foam Market Size – Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

5.3%
CAGR (2026-2034)
9.95 USD Bn.
Forecast Market Size
309
Report Pages
125
Market Tables

Overview

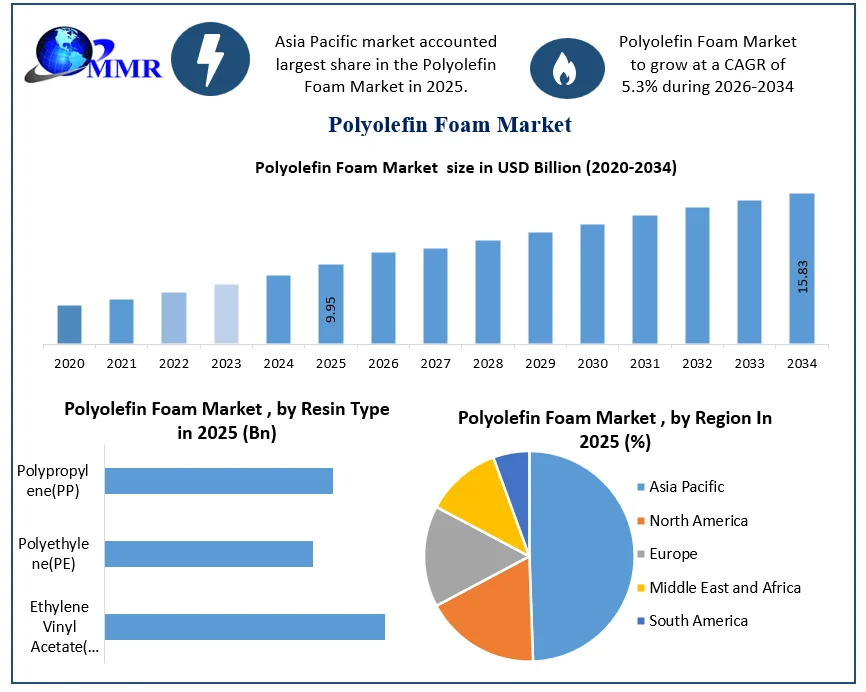
The Polyolefin Foam Market size was valued at USD 9.95 Billion in 2025 and the total Polyolefin Foam revenue is expected to grow at a CAGR of 5.3% from 2026 to 2034, reaching nearly USD 15.83 Billion.

Polyolefins, which include polyethylene (PE), polypropylene (PP), and their derivatives, are the most important polymer family in terms of production and consumption and are thus classified as commodity polymers. Because of their inexpensive cost and a wide variety of characteristics, they have a wide range of uses. They are great polymers for foams because of their superb blend of hardness, flexibility, and resilience to chemicals and abrasion.

the Polyolefin foams are composed of many materials that are combined in a kneading process with an organic blowing agent and a cross-linking agent. Polyolefin resin is created by thermally decomposing it in a closed environment. Polyolefin is a broad term that refers to any compound derived from an olefin monomer.

Polyolefins are classified according to the type of olefin utilized. Polyolefin foams are manufactured using a broad range of processing processes, including extrusion, injection, and compression moulding. Foaming of polyolefins normally happens in three key processes, regardless of technique: nucleation, cell development and stability.

Polyolefin Foam Market  Size, Growth & Share Analysis
Polyolefin Foam Market  Growth

To know about the Research Methodology:- Request Free Sample Report

Polyolefin Foam Market Dynamics

Rise in Deployment of Renewable Energy Across the World to drive Polyolefin Foam Market

Many nations are working on sustainable development and increasing the percentage of renewable energy consumption and generation in overall energy consumption and generation. Because of enormous expenditures to satisfy climate change targets, European countries are at the forefront of the renewable energy market. Germany, Sweden, Spain, and Italy are among the countries.

European governments are helping to boost the renewable energy sector. With the emphasis moving toward the development of renewable energy, the demand for polyolefins has expanded, since these polyolefin-based goods find use in numerous appliances used to manufacture renewable energy infrastructure or equipment.

Advanced Polyolefin Group Facing the Automotive Challenge and Creating Growth Opportunities in Polyolefin Foam Market

Polypropylene, which includes a series of improved reactor thermoplastic olefins (TPOs) and compounded grades, provides novel answers to a variety of difficulties confronting the automotive industry today. Polypropylene's flexibility and low cost enable cost-effective and novel design solutions that improve passenger safety and comfort.

The lower density of PP adds to better fuel economy and cheaper raw material costs. Furthermore, the inherent enhanced noise, vibration, and harshness (NVH) qualities of PP contribute to increased passenger comfort. As a result, PP has become the most significant thermoplastic material in automobiles, accounting for more than 50 kg per car on average.

The amount of polyolefin materials utilized by the automobile sector has steadily increased over the previous two decades. Technological advancements that significantly broaden the property range of polyolefins are driving this development. The primary goal of a bumper system is to limit the damage by absorbing kinetic energy, so reducing the load imparted to the underlying vehicle body. As a result, bumper systems have evolved into intricately designed systems. Automobile manufacturers pioneered the use of polyolefins in a variety of automotive-related applications. Polypropylene-based materials are now utilized to make more than 90% of all bumpers in big corporations. This is expected to drive the Polyolefin Foam Market growth during the forecast period.

Low-Density Polyolefin Packaging Foams to Drive Polyolefin Foam market

Companies are actively forming joint ventures and investing in the development of improved low-density packing foams. In the cushion packaging sector, including computer and anti-static packing applications, case inserts, and automobile material handling, these low-density packaging foams offer price/performance benefits.

As a result of advanced technology developed by companies for the production of ultra-low-density polyolefin foams, the market for polyolefin packaging foams has grown significantly, replacing not only higher-density polyethylene foams but also dissimilar materials such as resilient moulded bead foams and polyurethane foams. Thus, low-density polyolefin packaging foams are expected to drive the growth of Polyolefin Foam Market during the forecast period.

For example, Sentinel Polyolefins, a Pactiv joint venture, and Pactiv Corp. (formerly Tenneco Packaging) have announced the creation of a global marketing and technology development collaboration for innovative low-density packaging foams. SenFlex-H914, the first commercial product, is believed to be the world's first polyolefin packing foam with a density of less than 1.0 pcf. At only 0.9 pcf (14kg/m3), the H914 material outperforms standard polyethylene foams and polyurethane foams that are more than twice as dense. SenFlex is a physically blown foam material made feasible by Dow's Index Interpolymers, a novel thermoplastic polymer family enabled by INSITE Technology.
Polyolefin Foam Market


Meeting New VOC Emission Requirements to Pose a Challenge for Polyolefin Foams Market and Polyolefin Foams Manufacturers

Restrictive rules and growing worries about the environmental impact of tiny plastic beads will slow the polyolefin foam industry's development pace. The rising awareness of the detrimental impacts of plastic on the environment is expected to create significant hurdles for polyolefin foam manufacturers.

For example, with increased health awareness both internationally and in China, various research on how to manage automobile cabin air quality has been conducted in recent years to prevent the principal categories of dangerous volatile organic compounds (VOC) material in the vehicle cabin. The State Environmental Protection Administration of China (SEPA) issued regulation GB/T 27630-2011, a guideline for passenger automobile air quality evaluation, in 2007. This regulation is quite likely to become mandatory and hence influence global regulation.

Lack of Melting Strength Expected to Restraint Polyolefin Foams Industry Growth

Melt strength is defined as the resistance to extensional flow above the polymer's melting point. Melt strength is determined by molecular weight and long-chain branching. Long chain branches are introduced or created to increase melt strength and drawability, with the entanglement of the branched polymer chain giving rise to better melt strength and drawability.

Polyolefins' inability to achieve sufficient melt strength qualities has historically prohibited them from being used effectively in foam applications. PE flexible foams, which employ a blowing agent with or without cross-linking to enhance strength, are mostly used for light-duty cushioning, protective packaging, and limited insulation (sound and roof insulation). Thus, lack of melting strength is expected to restraint Polyolefin Foams Market growth during the forecast period.

Polyolefin Foam Market Segment Analysis

Polyolefin Foam Industry Based on Resin Type, the polyethylene segment dominated the polyolefin foam market in 2025 and is expected to grow at a CAGR of 5.4% during the forecast period. Polyethylene foam is a low-density, chemically cross-linked closed-cell material that may be improved by adding additives and modifiers to get the desired output. Polyethylene-based foams are lightweight, flexible and resistant to thermal insulation. Polyethylene-based polyolefin foams are used in an automobile for interior and exterior body components, bumpers, body panels, trims, dashboards, door claddings, climate control, and many more applications.

The increased production of automobiles will increase demand for the Polyolefin Foam market. According to the International Organization of Motor Vehicle Manufacturers, global vehicle production will grow by 3% in 2025, with automotive production estimated to be around 5,70,54,295 units and commercial vehicle production estimated to be around 2,30,91,693 units. As a result, the rise in vehicle manufacturing has demonstrated that polyethylene is a favoured choice over alternative polyolefin foam resins, propelling its segmental growth.

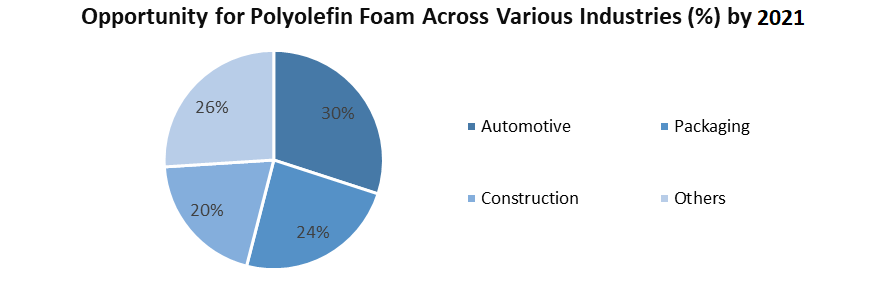
Polyolefin Foam Industry Based on End-Use Industry, the automotive industry held the largest polyolefin foam market share in 2025 and is estimated to grow at a CAGR of 4.9% during the forecast period. Polyolefin foam, which is composed of polypropylene and ethylene vinyl acetate resins, has excellent thermal insulation properties and is widely used in automobile shockproof pads, waterproof door panels, headrests and car door handrails, car sun visors, sealing tape, marine bumpers and buoys, and gaskets.

The increased output of electric cars in the automotive industry is driving the polyolefin foam business. According to the International Energy Agency, electric car sales in Europe will climb by 70% to 2.3 million in 2024, with plug-in hybrids accounting for over half of the total. With the increased manufacturing of electric cars, it is expected that the need for polyolefin foam in the automotive sector would increase in the future years.

Polyolefin Foam Market Regional Insights

Asia-Pacific region dominated the global polyolefin foam market in 2025 with the highest market share. Asia-Pacific region is expected to dominate the polyolefin foam industry during the forecast period. Growing automobile manufacturing demand in countries such as China, Japan, and India is one of the primary reasons driving demand for polyolefin foam in the Asia-Pacific region, which is estimated to increase demand for polyolefin foam in the region.

The building industries of China, India, the United States, and Indonesia are expected to increase significantly in the future years. China will account for 26.1% of world growth on its own. India is estimated to account for 14.1% of global growth, the US for 11.1%, and Indonesia for 7.0%, which will fuel demand for polyolefin foam in the region thanks to the application of polyolefin foams in the building and construction sector.

According to EV Volumes, in 2025, out of a total of 6.75 million EVs across the world, around 3.4 million, or almost 50%, were sold to mainland China. China is still the world's top manufacturer of automobiles. China is concentrating on growing domestic manufacturing and sales of electric cars.

The Chinese car sector was impacted by economic upheavals and the trade war between the United States and China. In India, 4,399,112 automobiles were produced in 2025, a 30% increase over the previous year. Japan is the world's third-largest automaker, manufacturing 7,846,955 automobiles in 2022, a figure that is predicted to rise further in 2025. Because of all of these reasons, the region's polyolefin foam market is expected to increase steadily over the forecast period.

Polyolefin Foam Market  Recent Development

Date Company Development Impact
22 May 2026 SEKISUI Voltek Officially opened Project Endeavor, marking a significant manufacturing facility expansion for its high-performance polyolefin foam solutions. Enhances production output and operational scale to meet growing regional polyolefin foam demand.
02 March 2026 SEKISUI Voltek Successfully implemented the Microsoft Dynamics 365 ERP system to upgrade operational workflows across its polyolefin foam lines. Drives supply chain efficiency and improves customer service capabilities.
01 August 2025 SEKISUI Voltek Transitioned operations toward 100% renewable power, achieving measurable greenhouse gas emissions reductions in foam manufacturing. Advances corporate sustainability goals and lowers the carbon footprint of production.

Polyolefin Foam Market Scope: Inquire before buying

Global Polyolefin Foam Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 9.95 Bn.
Forecast Period 2026 to 2034 CAGR: 5.3% Market Size in 2034: USD 15.83 Bn.
Segments Covered: by Resin Type Ethylene Vinyl Acetate(EVA)
Polyethylene(PE)
Polypropylene(PP)
by End-Use Industry Automotive
Construction
Packaging
Others
by Technology Extrusion Foaming
Injecting Moulding Foaming
Blown Moulding Foaming
Beads Foaming
Others

Polyolefin Foam Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)

Polyolefin Foam Market Key Players are:

1. Armacell (US)
2. Polymer Technologies Inc. (US)
3. Rogers Corporation (US)
4. Dow Inc (US)
5. Sekisui Voltek (US)
6. Pregis LLC (US)
7. Johnson Controls (US)
8. Woodbridge Foam Corporation (Canada)
9. Arkema S.A. (France)
10.Knauf Industries (France)
11.BASF SE (Germany)
12.Covestro AG (Germany)
13.Zotefoams plc (UK)
14.Sekisui Alveo AG (Switzerland)
15.Recticel (Belgium)
16.Borealis AG (Austria)
17.NMC SA (Luxembourg)
18.DAFA A/S (Denmark)
19.Synthos (Poland)
20.JSP Corporation (Japan)
21.Mitsui Chemicals (Japan)
22.Toray Industries (Japan)
23.Cygtefa (CTF) (China)
24.Reliance Industries Limited (India)
25.KK NAG Ltd. (India)
SABIC (Saudi Arebia)

Frequently Asked Questions:

1] Which physical foaming agent (gas) is the best in PP foam production?
Ans. The optimal physical foaming agent is determined by the intended foam. Hydrocarbons such as iso- or n-butane are utilized in the creation of low-density foams, whilst inert gases such as supercritical CO2 or N2 are employed in the manufacturing of foams with densities of more than 200 kg/m3.

2] Can a chemical foaming agent be used with Daploy HMS PP?
Ans. Yes. There are several different masterbatches for chemical foaming that may be employed in PP foaming. In the manufacture of high and medium density foams, chemical foaming agents are more commonly used.

3] What is the minimum and maximum thickness of the foams produced using Daploy HMS PP in extrusion foaming?
Ans. The thinnest foams are 700-800 m thick. Depending on the foam density and cooling capability of the line, the foams can be up to 10 mm thick or even somewhat thicker. The difficulty in producing thick foams is stabilising (cooling down) the foam core to minimise foam collapse.

4] Which die type is recommended: flat die or annular die?
Ans. Flat dies can be used in production of extruded foams with densities down to about 200 kg/m3. Annular dies are recommended if the foam target density is lower.

5] Why are the foam properties different in machine and transverse directions?
Ans. In most circumstances, there will be some cell orientation during foam creation, either in the machine or transfer direction. As a result, the mechanical characteristics of the foam vary in various directions. By optimising foam nucleation and production settings, the situation can be improved.

Table of Contents

1. Polyolefin Foam Market Introduction 1.1. Study Assumption and Market Definition 1.2. Scope of the Study 1.3. Executive Summary 2. Global Polyolefin Foam Market: Competitive Landscape 2.1. MMR Competition Matrix 2.2. Competitive Landscape 2.3. Key Players Benchmarking 2.3.1. Company Name 2.3.2. Business Segment 2.3.3. End-user Segment 2.3.4. Revenue (2025) 2.3.5. Company Locations 2.4. Leading Polyolefin Foam Market Companies, by market capitalization 2.5. Market Structure 2.5.1. Market Leaders 2.5.2. Market Followers 2.5.3. Emerging Players 2.6. Mergers and Acquisitions Details 3. Polyolefin Foam Market: Dynamics 3.1. Polyolefin Foam Market Trends by Region 3.1.1. North America Polyolefin Foam Market Trends 3.1.2. Europe Polyolefin Foam Market Trends 3.1.3. Asia Pacific Polyolefin Foam Market Trends 3.1.4. Middle East and Africa Polyolefin Foam Market Trends 3.1.5. South America Polyolefin Foam Market Trends 3.2. Polyolefin Foam Market Dynamics by Region 3.2.1. North America 3.2.1.1. North America Polyolefin Foam Market Drivers 3.2.1.2. North America Polyolefin Foam Market Restraints 3.2.1.3. North America Polyolefin Foam Market Opportunities 3.2.1.4. North America Polyolefin Foam Market Challenges 3.2.2. Europe 3.2.2.1. Europe Polyolefin Foam Market Drivers 3.2.2.2. Europe Polyolefin Foam Market Restraints 3.2.2.3. Europe Polyolefin Foam Market Opportunities 3.2.2.4. Europe Polyolefin Foam Market Challenges 3.2.3. Asia Pacific 3.2.3.1. Asia Pacific Polyolefin Foam Market Drivers 3.2.3.2. Asia Pacific Polyolefin Foam Market Restraints 3.2.3.3. Asia Pacific Polyolefin Foam Market Opportunities 3.2.3.4. Asia Pacific Polyolefin Foam Market Challenges 3.2.4. Middle East and Africa 3.2.4.1. Middle East and Africa Polyolefin Foam Market Drivers 3.2.4.2. Middle East and Africa Polyolefin Foam Market Restraints 3.2.4.3. Middle East and Africa Polyolefin Foam Market Opportunities 3.2.4.4. Middle East and Africa Polyolefin Foam Market Challenges 3.2.5. South America 3.2.5.1. South America Polyolefin Foam Market Drivers 3.2.5.2. South America Polyolefin Foam Market Restraints 3.2.5.3. South America Polyolefin Foam Market Opportunities 3.2.5.4. South America Polyolefin Foam Market Challenges 3.3. PORTER's Five Forces Analysis 3.4. PESTLE Analysis 3.5. Technology Roadmap 3.6. Regulatory Landscape by Region 3.6.1. North America 3.6.2. Europe 3.6.3. Asia Pacific 3.6.4. Middle East and Africa 3.6.5. South America 3.7. Key Opinion Leader Analysis For Polyolefin Foam Industry 3.8. Analysis of Government Schemes and Initiatives For Polyolefin Foam Industry 3.9. Polyolefin Foam Market Trade Analysis 3.10. The Global Pandemic Impact on Polyolefin Foam Market 4. Polyolefin Foam Market: Global Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 4.1. Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 4.1.1. Ethylene Vinyl Acetate(EVA) 4.1.2. Polyethylene(PE) 4.1.3. Polypropylene(PP) 4.2. Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 4.2.1. Automotive 4.2.2. Construction 4.2.3. Packaging 4.2.4. Others 4.3. Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 4.3.1. Extrusion Foaming 4.3.2. Injecting Moulding Foaming 4.3.3. Blown Moulding Foaming 4.3.4. Beads Foaming 4.3.5. Others 4.4. Polyolefin Foam Market Size and Forecast, by Region (2025-2034) 4.4.1. North America 4.4.2. Europe 4.4.3. Asia Pacific 4.4.4. Middle East and Africa 4.4.5. South America 5. North America Polyolefin Foam Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 5.1. North America Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 5.1.1. Ethylene Vinyl Acetate(EVA) 5.1.2. Polyethylene(PE) 5.1.3. Polypropylene(PP) 5.2. North America Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 5.2.1. Automotive 5.2.2. Construction 5.2.3. Packaging 5.2.4. Others 5.3. North America Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 5.3.1. Extrusion Foaming 5.3.2. Injecting Moulding Foaming 5.3.3. Blown Moulding Foaming 5.3.4. Beads Foaming 5.3.5. Others 5.4. North America Polyolefin Foam Market Size and Forecast, by Country (2025-2034) 5.4.1. United States 5.4.1.1. United States Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 5.4.1.1.1. Ethylene Vinyl Acetate(EVA) 5.4.1.1.2. Polyethylene(PE) 5.4.1.1.3. Polypropylene(PP) 5.4.1.2. United States Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 5.4.1.2.1. Automotive 5.4.1.2.2. Construction 5.4.1.2.3. Packaging 5.4.1.2.4. Others 5.4.1.3. United States Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 5.4.1.3.1. Extrusion Foaming 5.4.1.3.2. Injecting Moulding Foaming 5.4.1.3.3. Blown Moulding Foaming 5.4.1.3.4. Beads Foaming 5.4.1.3.5. Others 5.4.2. Canada 5.4.2.1. Canada Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 5.4.2.1.1. Ethylene Vinyl Acetate(EVA) 5.4.2.1.2. Polyethylene(PE) 5.4.2.1.3. Polypropylene(PP) 5.4.2.2. Canada Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 5.4.2.2.1. Automotive 5.4.2.2.2. Construction 5.4.2.2.3. Packaging 5.4.2.2.4. Others 5.4.2.3. Canada Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 5.4.2.3.1. Extrusion Foaming 5.4.2.3.2. Injecting Moulding Foaming 5.4.2.3.3. Blown Moulding Foaming 5.4.2.3.4. Beads Foaming 5.4.2.3.5. Others 5.4.3. Mexico 5.4.3.1. Mexico Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 5.4.3.1.1. Ethylene Vinyl Acetate(EVA) 5.4.3.1.2. Polyethylene(PE) 5.4.3.1.3. Polypropylene(PP) 5.4.3.2. Mexico Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 5.4.3.2.1. Automotive 5.4.3.2.2. Construction 5.4.3.2.3. Packaging 5.4.3.2.4. Others 5.4.3.3. Mexico Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 5.4.3.3.1. Extrusion Foaming 5.4.3.3.2. Injecting Moulding Foaming 5.4.3.3.3. Blown Moulding Foaming 5.4.3.3.4. Beads Foaming 5.4.3.3.5. Others 6. Europe Polyolefin Foam Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 6.1. Europe Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.2. Europe Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.3. Europe Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4. Europe Polyolefin Foam Market Size and Forecast, by Country (2025-2034) 6.4.1. United Kingdom 6.4.1.1. United Kingdom Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.1.2. United Kingdom Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.1.3. United Kingdom Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.2. France 6.4.2.1. France Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.2.2. France Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.2.3. France Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.3. Germany 6.4.3.1. Germany Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.3.2. Germany Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.3.3. Germany Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.4. Italy 6.4.4.1. Italy Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.4.2. Italy Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.4.3. Italy Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.5. Spain 6.4.5.1. Spain Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.5.2. Spain Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.5.3. Spain Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.6. Sweden 6.4.6.1. Sweden Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.6.2. Sweden Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.6.3. Sweden Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.7. Austria 6.4.7.1. Austria Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.7.2. Austria Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.7.3. Austria Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 6.4.8. Rest of Europe 6.4.8.1. Rest of Europe Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 6.4.8.2. Rest of Europe Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 6.4.8.3. Rest of Europe Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7. Asia Pacific Polyolefin Foam Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 7.1. Asia Pacific Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.2. Asia Pacific Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.3. Asia Pacific Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4. Asia Pacific Polyolefin Foam Market Size and Forecast, by Country (2025-2034) 7.4.1. China 7.4.1.1. China Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.1.2. China Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.1.3. China Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.2. S Korea 7.4.2.1. S Korea Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.2.2. S Korea Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.2.3. S Korea Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.3. Japan 7.4.3.1. Japan Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.3.2. Japan Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.3.3. Japan Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.4. India 7.4.4.1. India Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.4.2. India Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.4.3. India Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.5. Australia 7.4.5.1. Australia Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.5.2. Australia Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.5.3. Australia Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.6. Indonesia 7.4.6.1. Indonesia Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.6.2. Indonesia Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.6.3. Indonesia Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.7. Malaysia 7.4.7.1. Malaysia Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.7.2. Malaysia Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.7.3. Malaysia Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.8. Vietnam 7.4.8.1. Vietnam Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.8.2. Vietnam Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.8.3. Vietnam Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.9. Taiwan 7.4.9.1. Taiwan Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.9.2. Taiwan Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.9.3. Taiwan Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 7.4.10. Rest of Asia Pacific 7.4.10.1. Rest of Asia Pacific Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 7.4.10.2. Rest of Asia Pacific Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 7.4.10.3. Rest of Asia Pacific Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 8. Middle East and Africa Polyolefin Foam Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 8.1. Middle East and Africa Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 8.2. Middle East and Africa Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 8.3. Middle East and Africa Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 8.4. Middle East and Africa Polyolefin Foam Market Size and Forecast, by Country (2025-2034) 8.4.1. South Africa 8.4.1.1. South Africa Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 8.4.1.2. South Africa Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 8.4.1.3. South Africa Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 8.4.2. GCC 8.4.2.1. GCC Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 8.4.2.2. GCC Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 8.4.2.3. GCC Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 8.4.3. Nigeria 8.4.3.1. Nigeria Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 8.4.3.2. Nigeria Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 8.4.3.3. Nigeria Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 8.4.4. Rest of ME&A 8.4.4.1. Rest of ME&A Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 8.4.4.2. Rest of ME&A Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 8.4.4.3. Rest of ME&A Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 9. South America Polyolefin Foam Market Size and Forecast by Segmentation (in USD Billion) 2025-2034 9.1. South America Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 9.2. South America Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 9.3. South America Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 9.4. South America Polyolefin Foam Market Size and Forecast, by Country (2025-2034) 9.4.1. Brazil 9.4.1.1. Brazil Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 9.4.1.2. Brazil Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 9.4.1.3. Brazil Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 9.4.2. Argentina 9.4.2.1. Argentina Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 9.4.2.2. Argentina Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 9.4.2.3. Argentina Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 9.4.3. Rest Of South America 9.4.3.1. Rest Of South America Polyolefin Foam Market Size and Forecast, by Resin Type (2025-2034) 9.4.3.2. Rest Of South America Polyolefin Foam Market Size and Forecast, by End-Use Industry (2025-2034) 9.4.3.3. Rest Of South America Polyolefin Foam Market Size and Forecast, by Technology (2025-2034) 10. Company Profile: Key Players 10.1. Armacell (US) 10.1.1. Company Overview 10.1.2. Business Portfolio 10.1.3. Financial Overview 10.1.4. SWOT Analysis 10.1.5. Strategic Analysis 10.1.6. Scale of Operation (small, medium, and large) 10.1.7. Details on Partnership 10.1.8. Regulatory Accreditations and Certifications Received by Them 10.1.9. Awards Received by the Firm 10.1.10. Recent Developments 10.2. Polymer Technologies Inc. (US) 10.3. Rogers Corporation (US) 10.4. Dow Inc (US) 10.5. Sekisui Voltek (US) 10.6. Pregis LLC (US) 10.7. Johnson Controls (US) 10.8. Woodbridge Foam Corporation (Canada) 10.9. Arkema S.A. (France) 10.10. Knauf Industries (France) 10.11. BASF SE (Germany) 10.12. Covestro AG (Germany) 10.13. Zotefoams plc (UK) 10.14. Sekisui Alveo AG (Switzerland) 10.15. Recticel (Belgium) 10.16. Borealis AG (Austria) 10.17. NMC SA (Luxembourg) 10.18. DAFA A/S (Denmark) 10.19. Synthos (Poland) 10.20. JSP Corporation (Japan) 10.21. Mitsui Chemicals (Japan) 10.22. Toray Industries (Japan) 10.23. Cygtefa (CTF) (China) 10.24. Reliance Industries Limited (India) 10.25. KK NAG Ltd. (India) 10.26. SABIC (Saudi Arebia) 11. Key Findings 12. Industry Recommendations 13. Polyolefin Foam Market: Research Methodology 14. Terms and Glossary

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements