
Military Robots Market by Platform, by Mode of operation, by Mode of Propulsion, by Application, by End-User and Forecast 2034
Overview
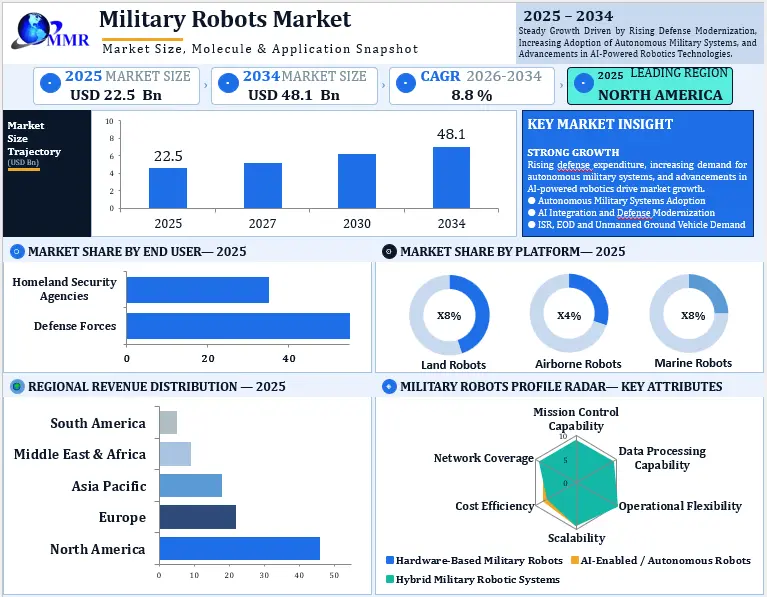
The Global Military Robots Market size was valued at USD 22.5 Bn. in 2025, and the total Global Military Robots Market revenue is expected to grow by 8.8% from 2026 to 2034, reaching USD 48.1 Bn.by 2034
Global Military Robots Market Overview
The military robots market comprises productive robotic systems that serve various defense-related tasks, including reconnaissance, surveillance, logistics, combat support, explosive ordnance disposal (EOD), and search-and-rescue. These automated systems have artificial intelligence (AI), sensor, communication systems, and autonomous navigation capabilities allowing militaries to mitigate the risk to personnel and improve operational effectiveness. They can perform missions in unsafe environments, can eliminate risk and threat to personal experience, and produce real-time data. Therefore, the military robotic systems are irreplaceable in modern warfare. As the market matures, both unmanned ground vehicle (UGV), unmanned aerial vehicle (UAV), and other autonomous naval platforms are becoming more widely adopted.
North America represents a major market for military robots, supported by substantial defense spending, advanced research and development capabilities, and the presence of established defense technology companies. The global military robots market comprises established defense contractors and specialized robotics companies that develop unmanned platforms, autonomous navigation technologies, sensors, and mission-support systems. Competition focuses on platform reliability, mobility, payload integration, secure communications, interoperability, and the ability to meet defense procurement requirements.
The competitive landscape includes established defense contractors and specialized robotics developers investing in platform mobility, sensor integration, autonomy software, interoperability, and modular system design. However, high development costs, technical reliability requirements, cybersecurity risks, and regulatory concerns surrounding autonomous weapon systems continue to influence adoption. These factors shape procurement priorities and create opportunities for manufacturers developing reliable, adaptable, and mission-specific robotic solutions.
Military Robots Market Size, Growth & Share Analysis
To know about the Research Methodology:- Request Free Sample Report
Global Military Robots Market Highlights
1. Market Growth: The global military robots market is estimated at USD 22.5 billion in 2025 and is projected to reach USD 48.1 billion by 2034, at an estimated CAGR of 8.8%.
2. Regional Leadership: North America dominates the military robots market with a 46% share in 2025, driven by defense spending and autonomous military technology.
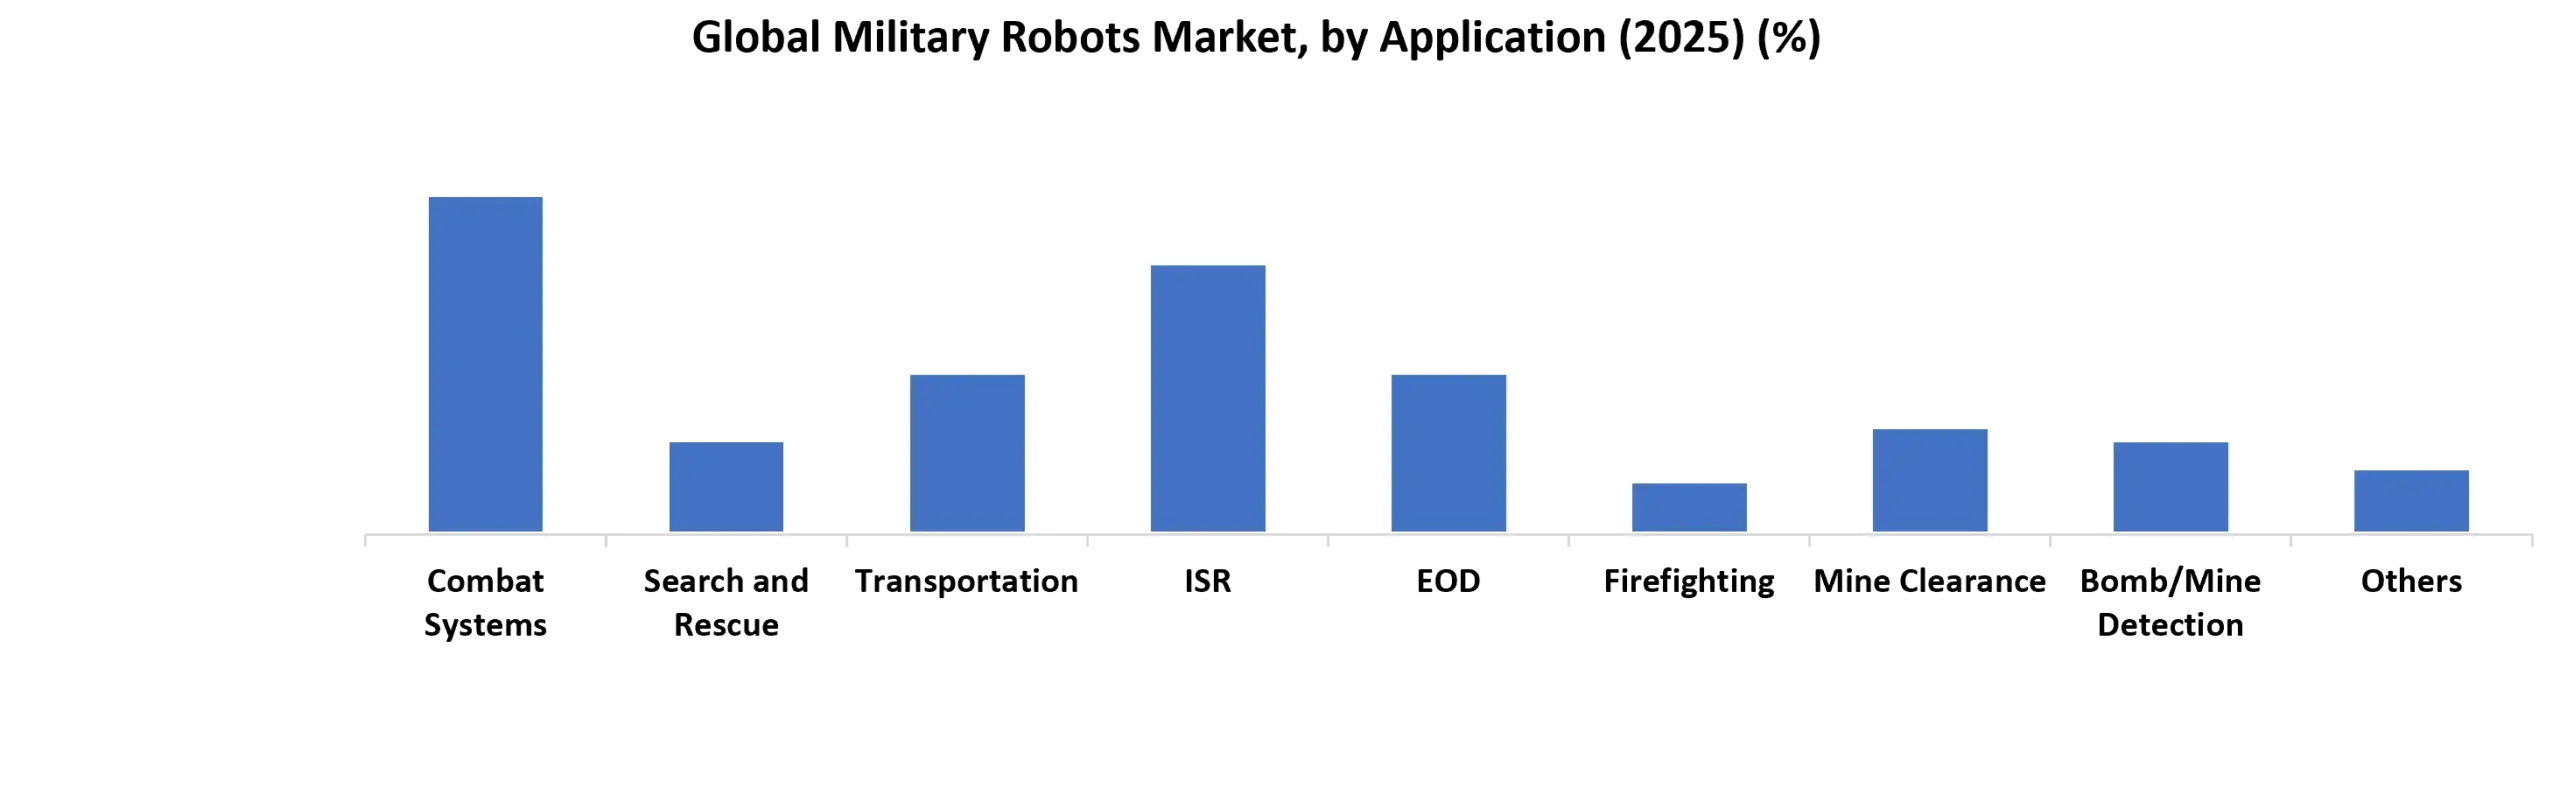
3. Application Dominance: Intelligence, Surveillance and Reconnaissance (ISR) accounts for approximately 48% of market revenue in 2025, supported by growing demand for real-time battlefield intelligence.
4. Platform Leadership: Land robots account for approximately 45% of market volume in 2025, driven by reconnaissance, EOD operations, and military logistics.
5.Emerging Technologies: AI-powered military robots, autonomous navigation, swarm robotics, and multi-robot coordination create growth opportunities across defense robotics and unmanned military systems.
Rising geopolitical tensions, improving defense budgets, and managing/modernizing military capabilities all create demand for military robots. The North American market dominates the global market share on the back of spending by the U.S. Department of Defense and the rapid developments in autonomy in combat systems. The Asia-Pacific region is emerging as the fastest-growing region, as expected growth in defense spending and advancements in innovation and robotics from China, India, South Korea, and Japan will also be drivers of the growth of this market during the forecast period. Despite high development costs, challenges of integrating unmanned systems in military operations, and ethical challenges with autonomous lethal weapons, successful technology provides the foundation for advances in AI, machine learning, swarm robotics, and autonomous navigation are already shaping the future proposition for military robots. There is a strong desire from militaries worldwide to provide faster, safer, and more intelligent solutions. Military robots will likely be key components in evolving next-generation warfare strategy.
Global Military Robots Market Dynamics
Military Robots Market Drivers
• Increasing Adoption of Autonomous Military Systems: The global military robots market expands as defense forces adopt autonomous military systems to improve operational efficiency and reduce personnel exposure to hazardous environments. Unmanned ground vehicles (UGVs), unmanned aerial vehicles (UAVs), and unmanned maritime systems support intelligence, surveillance and reconnaissance (ISR), explosive ordnance disposal (EOD), and military logistics. On June 29, 2026, Defense News reports a USD 20 million U.S. Marine Corps production contract awarded to Overland AI for autonomous ground vehicles. This development highlights increasing demand for military ground robotics and autonomous defense platforms.
• Rising Defense Modernization and Robotic Logistics Investment: Defense modernization programs increasingly prioritize autonomous mobility, robotic convoys, and uncrewed logistics systems. These technologies support military supply operations, reduce risks to personnel, and improve movement across challenging terrain. On July 13, 2026, Rheinmetall announces that it takes responsibility for Germany's InterRoC VII autonomous convoy research project, which focuses on secure cooperation between different vehicle platforms. This development reinforces demand for autonomous military vehicles, robotic logistics, and interoperable defense robotics.
Military Robots Market Restraints
• High Development, Procurement, and Maintenance Cost: High research and development expenditure remains a restraint on the military robots market, particularly for advanced autonomous platforms incorporating artificial intelligence (AI), sensors, secure communications, and cybersecurity systems. Defense organizations also account for testing, operator training, software updates, maintenance, and lifecycle support when procuring military robots. Complex integration with existing defense infrastructure increases deployment costs and can delay procurement decisions. These financial barriers limit adoption among countries with restricted defense budgets and create challenges for manufacturers seeking to scale production economically.
• Ethical Concerns and Regulatory Uncertainty: Ethical concerns, human-control requirements, and international humanitarian law create significant challenges for autonomous military systems, particularly lethal autonomous weapons. On August 25, 2026, the United Nations Secretary-General and the President of the International Committee of the Red Cross renew their call for international rules governing autonomous weapons systems. Their appeal highlights concerns about autonomous targeting, civilian protection, accountability, and human judgment in the use of force. These issues influence military procurement policies and can constrain the deployment of certain AI-enabled combat systems.
Military Robots Market Opportunities
• AI Integration and Multi-Robot Coordination: Artificial intelligence, machine learning, computer vision, and autonomous navigation create opportunities for advanced military robotics. AI-enabled systems support object recognition, battlefield awareness, mission coordination, and data processing across multiple unmanned platforms. On September 9, 2026, Elbit Systems' FUSE introduces AI-driven autonomous combat systems and One2Many capabilities for coordinating aerial and ground robotic formations. This development highlights opportunities in swarm robotics, autonomous control software, and multi-domain defense systems.
• Expansion of Autonomous Military Logistics and Ground Robotics: Growing demand for unmanned logistics, remote operations, and hazardous-environment support creates opportunities for military robot manufacturers. Autonomous ground vehicles help transport supplies, support reconnaissance, and perform selected missions in areas that present risks to military personnel. Rheinmetall's July 2026 InterRoC VII development demonstrates continued investment in interoperable autonomous military convoys. These applications create opportunities for unmanned ground vehicle manufacturers, robotics software developers, sensor suppliers, and defense-system integrators.
Military Robots Market Challenges
• Technical Complexity and Reliability Challenges: Military robots require reliable navigation, advanced sensors, secure communication, and real-time data processing to operate in challenging environments. GPS disruptions, electronic warfare, extreme weather, and communication failures affect robotic performance and limit the reliability of autonomous military systems.
• Cybersecurity Threats and Data Vulnerabilities: The growing integration of artificial intelligence (AI), connected sensors, and autonomous control systems increases exposure to cyberattacks, signal jamming, and unauthorized system access. Defense manufacturers must strengthen cybersecurity, encrypted communications, and electronic-warfare resilience to protect military robots and mission-critical data.
Military Robots Market Trends
• Development of AI-Enabled and Interoperable Unmanned Systems: The military robots market increasingly emphasizes AI-enabled autonomy, secure communications, and interoperability between different unmanned platforms. Defense organizations seek systems that integrate sensor data, coordinate robotic operations, and support faster situational awareness. On October 8, 2026, Reuters reports that Dutch company Intelic develops AI-driven software to coordinate radar, sensors, and image-recognition systems for drone defense in Ukraine. This development highlights the growing importance of autonomous coordination software, multi-system integration, and AI-enabled defense networks.
• Growth of Autonomous Convoys and Collaborative Robotics: Autonomous military convoys, collaborative ground robots, and coordinated aerial-ground platforms represent important trends in next-generation military robotics. Manufacturers increasingly focus on modular platforms, shared control systems, and autonomous mobility to support reconnaissance, logistics, and military operations. Rheinmetall's InterRoC VII project, announced on July 13, 2026, focuses on secure autonomous cooperation between different vehicle platforms under military conditions. This trend supports demand for robotic mobility, autonomous navigation, fleet coordination, and integrated unmanned defense systems.
Global Military Robots Market Segment Analysis
By Platform, the military robots market is segmented as, land robots, marine robots, and airborne robots. In terms of volume, the land robots segment accounted for almost 45% of the market in 2025 and is likely to continue dominating the market over the forecast period. Because of their capacity to maintain a visual on a single target for an extended period, hover, and execute an agile movement, land robots are likely to become more popular for inspection purposes. Airborne robots include military unmanned aerial vehicles used for intelligence gathering, surveillance, reconnaissance, and tactical mission support. Marine robots include unmanned surface vehicles and unmanned underwater vehicles designed for maritime surveillance, underwater inspection, mine countermeasures, and other naval operations.
Based on Application, the military robots market is segmented as, combat system, search and rescue, transportation, ISR, EOD, Firefighting, Mine clearance, Bomb/Mine Detection, and others. In 2025, the ISR segment had the greatest revenue share of around 48%, and this trend is likely to continue during the forecast period. ISR is one of the most common uses for military robots. In ISR applications, UAVs, UGVs, USVs, ROVs, and AUVs are commonly used. Small unmanned ground vehicles are mostly used in the military to deliver battlefield intelligence. Presently, military forces around the world deploy miniature robots instead of human scouts because they can remain nearly undetectable to the enemy.
Based on End-User, the military robots market is segmented as defense and homeland security. In 2025, the defense segment had the greatest market share of over 38%, and this trend is likely to continue during the forecast period because of the surging adoption of military robots for the protection of the country from unknown enemy attacks.Defense forces represent the core user group, adopting military robots for battlefield intelligence, reconnaissance, logistics, explosive-hazard handling, and combat support. Homeland security agencies use relevant robotic systems for border monitoring, surveillance, explosive-threat response, and other security operations. Revenue should be allocated according to the purchasing or deploying end-user organization, with a consistent rule for systems procured jointly or used across multiple agencies.
Global Military Robots Market Regional Insights
In 2025, the North American region dominated the military robots market with 46% of the overall market share. Thanks to technology breakthroughs and increased rates of armed wars against terrorism, the United States has the largest market for military robots in North America. Because of the challenges it faces and its role in the war against terrorism in Syria, Iraq, and Afghanistan, the United States is one of the world's leading manufacturers and end-users of military robots. The acceptance of military robots gives soldiers more assistance and supports them in a variety of military applications.
Europe holds a significant position in the global military robots market, supported by defense modernization, military technology development, and increasing demand for autonomous defense systems. Regional demand focuses on unmanned ground vehicles, military drones, maritime robotics, mine countermeasure systems, and robotic platforms for reconnaissance and logistics. European defense manufacturers, including BAE Systems, Rheinmetall, Milrem Robotics, QinetiQ, Thales, Saab, Leonardo, Airbus Defence and Space, and Exail Technologies, contribute to the development of military robotics, unmanned platforms, sensors, and autonomous mission systems.
Asia Pacific represents the fastest-growing regional market for military robots, supported by defense modernization, rising investment in autonomous military systems, and the expansion of domestic defense manufacturing. China, India, Japan, South Korea, and Australia contribute to regional demand for unmanned ground vehicles, military drones, autonomous maritime systems, and AI-powered military robotics. Companies and defense organizations such as Hanwha Aerospace, Hyundai Rotem, Mitsubishi Heavy Industries, Singapore Technologies Engineering, and India's Defence Research and Development Organisation support regional capabilities. Increasing demand for border surveillance, intelligence, surveillance and reconnaissance (ISR), military logistics, mine detection, and battlefield support strengthens the Asia Pacific military robots market.
The South America military robots market expands through defense modernization, increasing demand for unmanned military systems, and investments in intelligence, surveillance and reconnaissance (ISR), border security, and autonomous defense technologies. Brazil represents a key regional market, supported by its defense industry, military unmanned aerial systems, and growing interest in unmanned ground vehicles and robotic platforms. Argentina, Colombia, Chile, and Peru also contribute to regional demand for military drones, surveillance systems, remotely operated robots, and unmanned maritime technologies. The adoption of military robots supports border monitoring, reconnaissance, military logistics, explosive ordnance disposal (EOD), and operations in remote or hazardous environments. International defense manufacturers and regional defense organizations create opportunities for military robotics procurement, technology transfer, and domestic capability development.
The Middle East and Africa military robots market develops through defense modernization, border security requirements, and growing demand for unmanned surveillance and reconnaissance systems. Saudi Arabia, the United Arab Emirates, Israel, Türkiye, and South Africa contribute to regional defense technology development and procurement. Key companies and technology providers include Elbit Systems, Israel Aerospace Industries, Rafael Advanced Defense Systems, ASELSAN, and other regional defense manufacturers. Demand for military drones, unmanned ground vehicles, explosive ordnance disposal (EOD) robots, mine-countermeasure systems, and autonomous patrol technologies supports market development.
Global Military Robots Market Competitive Landscape
The landscape has a multitude of global and regional defense primes and specialists competing on autonomy software, multi-sensor fusion, rugged reliability, cost, and compatibility with existing C2/ISR and weapons systems. The leading companies (e.g., Lockheed Martin, Northrop Grumman, General Dynamics, BAE Systems, Rheinmetall, Elbit Systems, IAI, Thales, SAAB, AeroVironment, QinetiQ, Hanwha Defense, and Turkish Aerospace) tend to win long-cycle defense contracts leveraging deep R&D pipelines and protected IP, program knowledge, and international supply chains. Each roadmap anticipates UGV/UAV/USV/UUV applications with open architectures (MOSA), SWaP-optimized, trusted AI/autonomy, c-UAS capabilities, and Manned-Unmanned Teaming (MUM-T). Tier-1 primes co-design with defense ministries and OEMs and provide platform+payload solutions (including mission profiles for EOD, ISR, logistics, and strike). Mid-tier and start-up companies are targeting niche roles (EOD robots, loitering munitions, autonomy "kits", CBRN, perimeter security) and producing cost-attractive systems intended for rapid fielding. Services—training, simulation/digital twins, autonomy retrofits, sustainment, and software updates—are an expanding theatre of competition around lifetime value.
| No. | Company | Home country / region | Main military robotics domain | Analytical position in the market |
| 1 | Lockheed Martin | United States — North America | Unmanned aerial and maritime systems; autonomous mission technologies | Major defense prime with broad integration capabilities and access to large defense procurement programs. |
| 2 | Northrop Grumman | United States — North America | Unmanned aircraft, autonomous systems, surveillance platforms | Strong competitor in high-value autonomous platforms and intelligence-related defense systems. |
| 3 | General Dynamics | United States — North America | Ground platforms, military vehicles, unmanned-system integration | Relevant through its ground-defense capabilities and integration of robotic systems with military vehicles. |
| 4 | BAE Systems | United Kingdom — Europe | Land, air and maritime unmanned systems; autonomous defense technologies | Broad multi-domain defense portfolio supports competition across platform and mission categories. |
| 5 | Textron Systems | United States — North America | Unmanned aircraft, ground and maritime systems | Competes across multiple unmanned platform categories, particularly defense and tactical applications. |
| 6 | AeroVironment | United States — North America | Small unmanned aircraft and loitering systems | Specialist competitor in compact aerial systems and tactical unmanned capabilities. |
| 7 | Teledyne FLIR Defense | United States — North America | Ground robots, EOD robotics, thermal imaging and sensing | Strong specialist in remotely operated ground robots and hazardous-environment missions. |
Global Military Robots Market Trends
| Category | Trends | Example | Market Impact |
| Autonomous Systems | Increasing adoption of autonomous and uncrewed systems across air, land, and maritime operations | Lockheed Martin — Indago 4 UAV and multi-domain autonomy capabilities | Improves reconnaissance, mission coordination, operational efficiency, and personnel safety. |
| AI and Machine Learning | Integration of AI, onboard computing, sensor fusion, and automated target recognition into unmanned systems | Lockheed Martin — Indago 4 with onboard computing and AI/ML capabilities | Enhances situational awareness, data processing, navigation support, and decision-making. |
| Lightweight and Modular Design | Development of portable robots and modular unmanned platforms with adaptable payloads | Lockheed Martin — Indago 4, featuring a compact design and multiple payload interfaces | Supports rapid deployment, flexible mission configuration, and use across varied operating environments. |
Global Military Robots Market Recent Development
| Exact Date | Company / Organization | Recent Development | Market Impact |
| January 15, 2026 | Anduril Industries | Receives a USD 23.9 million U.S. Marine Corps contract to deliver more than 600 Bolt-M systems under the Organic Precision Fires-Light program. | Strengthens demand for autonomous defense systems and scalable unmanned capabilities. |
| April 28, 2026 | Textron Systems and Howe & Howe | Unveil the RIPSAW M1 uncrewed ground vehicle technology demonstrator at the Modern Day Marine exposition. | Advances modular ground robotics for reconnaissance, surveillance, and uncrewed military operations. |
| June 14, 2026 | AeroVironment | Introduces the TOM 50 RE backpackable uncrewed ground vehicle for reconnaissance, explosive ordnance disposal, and autonomous mapping. | Expands portable military robotics for hazardous environments and tactical missions. |
| September 9, 2026 | Elbit Systems | Introduces FUSE autonomous combat systems and One2Many capabilities for coordinated aerial and ground robotic formations. | Supports AI-enabled autonomy, multi-domain coordination, and manned-unmanned teaming. |
| October 12, 2026 | Textron Systems | Launches the CoreMotion robotic control package to integrate autonomy software and vehicle hardware across ground-vehicle platforms. | Supports faster autonomy integration, robotic fleet upgrades, and scalable unmanned ground operations. |
Military Robots Market Scope: Inquire before buying
| Military Robots Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 22.5 USD Billion |
| Forecast Period 2026-2034 CAGR: | 8.8% | Market Size in 2034: | 48.1 USD Billion |
| Segments Covered: | by Platform | Land Robots Marine Robots Airborne Robots |
|
| by Mode of operation | Remotely Operated Semi-Autonomous Fully Autonomous |
||
| by Propulsion System | Electric Internal Combustion Engine (ICE) Hybrid |
||
| by Application | Combat Systems Search and Rescue Transportation ISR EOD Firefighting Mine Clearance Bomb/Mine Detection Others |
||
| by End-User | Army Navy Air Force Joint & Special Operations Forces Government & Homeland Security |
||
| by Weight Class | Nano/Micro (<10 kg) Small (10–200 kg) Medium (200–2,000 kg) Heavy (>2,000 kg) |
||
| by Payload Type | EO/IR & Imaging Radar & LiDAR Electronic Warfare & SIGINT Weapon Payloads Detection & CBRN Communication & Relay Other Mission Payloads |
||
Military Robots Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and the Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and the Rest of APAC)
South America (Brazil, Argentina Rest of South America)
Middle East & Africa (South Africa, GCC, Egypt, Nigeria and the Rest of ME&A)
Military Robots Market Key Players
North America:
1. Northrop Grumman Corporation
2. Lockheed Martin Corporation
3. General Dynamics Corporation
4. AeroVironment, Inc.
5. Teledyne Technologies Incorporated / Teledyne FLIR Defense
6. The Boeing Company
7. General Atomics Aeronautical Systems, Inc.
8. L3Harris Technologies, Inc.
9. RTX Corporation
10. Textron Inc. / Textron Systems
11. Kratos Defense & Security Solutions, Inc.
12. Anduril Industries, Inc.
13. Boston Dynamics, Inc.
14. Ghost Robotics Corporation
15. Oshkosh Corporation / Oshkosh Defense
Others
Europe:
16. BAE Systems plc
17. QinetiQ Group plc
18. Rheinmetall AG
19. Thales Group
20. Leonardo S.p.A.
21. Saab AB
22. Kongsberg Gruppen ASA
23. Milrem Robotics
24. Patria Oyj
25. Shark Robotics
26. KNDS
27. Exail Technologies
Others
Asia Pacific:
28. Hanwha Aerospace Co., Ltd.
29. Hyundai Rotem Company
30. Korean Air Aerospace Division
31. Mitsubishi Heavy Industries, Ltd.
32. Kawasaki Heavy Industries, Ltd.
33. ST Engineering
34. China North Industries Group Corporation (NORINCO)
35. Aviation Industry Corporation of China (AVIC)
36. Bharat Electronics Limited (BEL)
37. Tata Advanced Systems Limited (TASL)
Rest of World:
38. Israel Aerospace Industries Ltd. (IAI)
39. Elbit Systems Ltd.
40. EDGE Group PJSC
Others
Frequently Asked Questions
1. What are the major segments of the military robots market?
Ans. The market is segmented by platform (land, marine, and airborne robots), mode of operation, propulsion, application, end user, and region.
2. What are the key trends in the military robotics market?
Ans. Major trends include AI-enabled military robots, autonomous navigation, swarm robotics, modular unmanned ground vehicles (UGVs), advanced sensors, and collaborative unmanned systems.
3. What is the expected CAGR of the military robots market from 2025 to 2034?
Ans. The market is estimated to grow at a CAGR of 8.8%, driven by military modernization, autonomous navigation, and increasing adoption of unmanned systems.
4. What are the key military robots market growth drivers?
Ans. Major growth drivers include rising defense budgets, geopolitical tensions, autonomous military technology, and demand for intelligence, surveillance and reconnaissance (ISR), explosive ordnance disposal (EOD), and robotic logistics.
5. Which region dominates the global military robots market?
Ans. North America dominates the market, accounting for approximately 46% of the market share in 2025, supported by U.S. defense spending and advanced military robotics development.