Industry 4.0 Market Size – Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

20.07%
CAGR (2026-2034)
141.95 USD Bn.
Forecast Market Size
308
Report Pages
151
Market Tables

Overview

The total market value of the Global Industry 4.0 Market stood at USD 141.95 billion in 2025 and is expected to grow up to USD 736.29 billion by 2034, growing at a CAGR of 20.07%. Growth of the market can be attributed to the increasing adoption of AI, IIoT, robotics, digital twins, cloud computing, and smart manufacturing.

Industry 4.0 Market Overview

The adoption of IoT, cloud computing, and AI is changing how manufacturing processes are performed by integrating smart sensors and robotics, forming smart factories that allow data-driven decision-making and insights. This way, manufacturers can gain insights from production data along with ERP and supply chain management systems to create visibility and agility that will result in improved automation, predictive maintenance, and process optimization.

Industry 4.0 market uses big data analytics to monitor assets and perform predictive maintenance to minimize downtime, and AI-powered visual inspections help improve quality control. Available across all manufacturing sectors, including discrete and process manufacturing, oil, gas, and mining, among others, Industry 4.0 brings new levels of excellence to manufacturing.

Industry 4.0 Market Growth Outlook
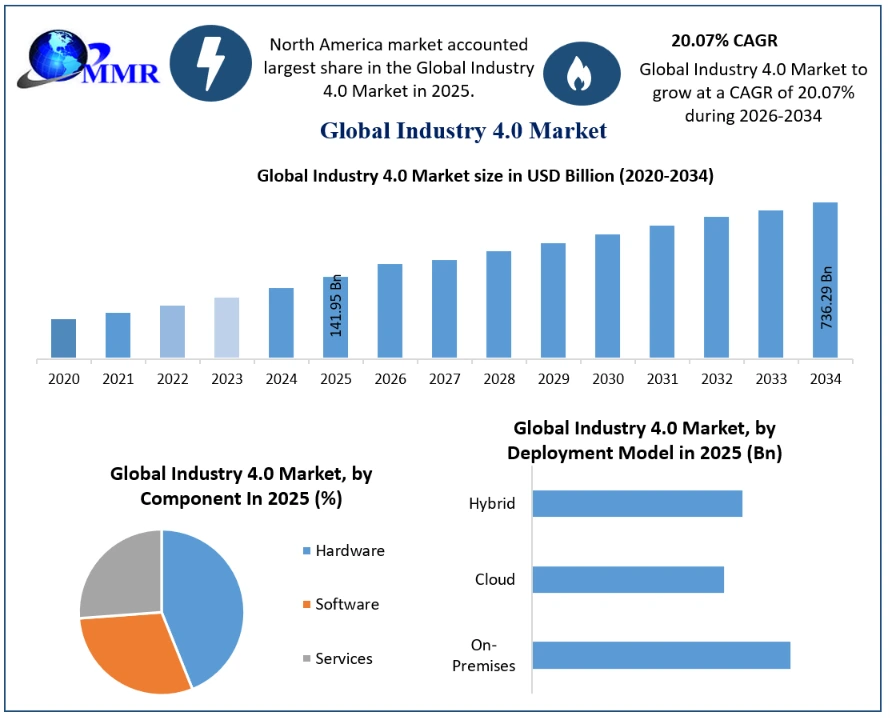
Industry 4.0 Market Growth

To know about the Research Methodology :- Request Free Sample Report

The increasing adoption of advanced technologies such as the Internet of Things (IoT), cloud computing, and artificial intelligence (AI) across manufacturing sectors is driving the expansion of Industry 4.0 initiatives. These technologies enable the creation of interconnected smart factories equipped with sensors and robotics, facilitating real-time data collection and analysis for enhanced decision-making and operational efficiency. The demand for improved productivity, quality, and cost-effectiveness is incentivizing companies to invest in Industry 4.0 solutions to optimize their manufacturing processes. The rise of digital transformation initiatives and the growing availability of data analytics tools are empowering manufacturers to leverage insights from production data to drive continuous improvement and innovation which boost Industry 4.0 Market growth. The increasing integration of Industry 4.0 technologies with existing enterprise systems such as enterprise resource planning (ERP) and supply chain management systems is streamlining operations and enhancing overall business performance. As awareness of the benefits of Industry 4.0 continues to grow and technological advancements accelerate, the adoption and growth of Industry 4.0 initiatives are poised for sustained growth across various industries globally.

Industry 4.0 Market trend

Increasing Convergence of Digital Technologies with Physical Systems, Leading to The Creation of Cyber-Physical Systems (CPS)

CPS seamlessly integrates sensing, computation, control, and networking into physical objects and infrastructure, bridging the gap between the physical and digital realms. These systems allow for the interconnectedness of devices, infrastructure, and the internet, facilitating real-time data exchange and enabling intelligent decision-making processes. CPS plays a crucial role in Industry 4.0 by embedding intelligence and cognitive computing capabilities into the design and simulation processes of physical systems. This integration empowers engineers to create digital twins of physical instruments and processes, facilitating simulation, control and optimization from centralized interfaces which boosts Industry 4.0 Market growth. Industries ranging from healthcare to manufacturing leverage CPS to enhance operational efficiency, precision, and adaptability in dynamic environments.

The applications of CPS are diverse and expansive, spanning industries such as healthcare, manufacturing, automotive, civil engineering, and energy. In healthcare, CPS enables real-time tracking of patient conditions remotely, enhancing monitoring capabilities and facilitating timely interventions. In manufacturing, CPS optimizes processes by simulating changes and controlling operations through digital twins, leading to increased efficiency and precision. CPS finds applications in smart cities and grids, where they streamline infrastructure management and resource allocation through data-driven insights. By leveraging CPS, organizations gain enhanced visibility, control, and predictive capabilities, driving innovation and efficiency across a wide range of industries and driving Industry 4.0 Market growth. As CPS continues to evolve and integrate with existing systems, they promise to revolutionize industrial processes, enabling smarter, more connected and adaptive systems that drive the future of Industry 4.0.
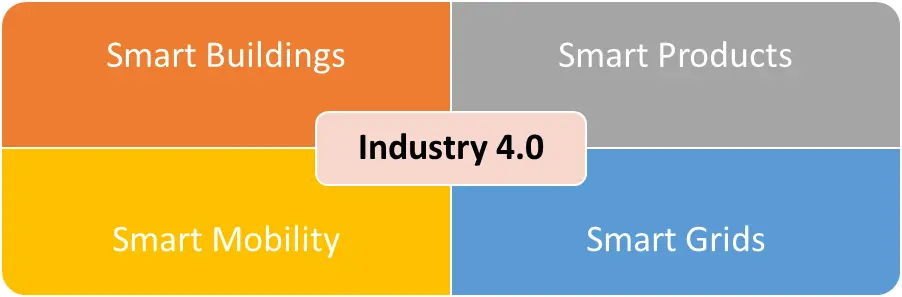
Industry 4.0 Market

Industry 4.0 Market Dynamics

Demand for increased operational efficiency and productivity to Boost Market Growth

In today's fiercely competitive business landscape, companies are compelled to optimize their operations to remain agile, profitable, and sustainable amidst evolving market dynamics and rising customer expectations. This drive for operational excellence is fueled by the imperative to navigate through disruptive challenges such as globalization and digitalization. Industry 4.0 technologies emerge as transformative enablers, offering innovative solutions to streamline processes, minimize resource wastage, and drive efficiencies to unprecedented levels. These technologies, including automation, data analytics, and artificial intelligence, empower businesses to automate routine tasks, improve decision-making processes and adapt quickly to changing market conditions, enabling them to gain a competitive edge and thrive in the fast-paced and ever-evolving business environment.

The increasing demand for operational efficiency is prompted by the need for companies to optimize resource utilization, reduce costs, and enhance sustainability efforts. In today's cost-conscious environment, companies are constantly seeking ways to maximize value while minimizing waste, driving them to adopt Industry 4.0 technologies, which significantly boosts the Industry 4.0 Market growth. By leveraging these technologies, companies optimize production processes, reduce downtime, and minimize waste, leading to significant cost savings and improved profitability. Industry 4.0 technologies facilitate agile responses to rapidly changing market trends and customer preferences, while also supporting sustainability initiatives by enabling more eco-friendly and resource-efficient practices. The increased operational efficiency and productivity emerge as a key driver driving the Industry 4.0 Market growth, as companies strive to remain competitive, profitable, and sustainable in today's dynamic business landscape.

Industry 4.0 Market Restraint

High Initial Investment Required for Implementing Industry 4.0 Technologies

The high initial investment required for implementing Industry 4.0 technologies stands as a significant restraint on the Industry 4.0 market. The adoption of advanced technologies such as the Internet of Things (IoT), artificial intelligence (AI), robotics, and cloud computing necessitates substantial upfront capital expenditure for infrastructure, equipment, software, and skilled personnel. This financial barrier is particularly challenging for small and medium-sized enterprises (SMEs) and organizations operating in cost-sensitive industries, as it deters them from embracing Industry 4.0 solutions.

The concerns about the return on investment (ROI) and uncertainty regarding the long-term benefits of these technologies further exacerbate the reluctance among businesses to commit to Industry 4.0 initiatives. The significant upfront costs associated with implementation lead to delays or hesitations in adopting Industry 4.0 practices, hindering the Industry 4.0 Market growth potential and limiting the transformative impact of these technologies on various industries and sectors.

Industry 4.0 Market Segment Analysis

According to the Component, the global Industry 4.0 market is bifurcated into Hardware, Software, and Services segments. In 2025, the Hardware segment led the market and is anticipated to continue dominating the market throughout the forecast period due to increasing use of industrial robots, IoT sensors, controllers, machine vision systems, edge computing devices, and industrial networking equipment for smart manufacturing. The Software segment aids in digital transformation by leveraging MES, PLM, IIoT platform, AI and Analytics, digital twins, ERP integration, and predictive maintenance solutions.


Based on the Technology Type, the market is segmented into the Internet of Things (IoT), Artificial Intelligence (AI), Big Data and Analytics, Cybersecurity, Additive Manufacturing and Others. Internet of Things (IoT) dominated the Industry 4.0 Market in 2025 and is expected to continue its dominance over the forecast period. The Internet of Things (IoT) has emerged as a transformative force within Industry 4.0, revolutionizing the way manufacturing and industrial processes are managed and optimized. IoT for Industry 4.0 entails the interconnection of physical devices, sensors, and machinery through internet-enabled networks, enabling seamless data exchange and communication. By embedding sensors into machines and equipment, manufacturers gain real-time visibility into their operations, allowing for predictive maintenance, remote monitoring, and enhanced decision-making capabilities.

Based on Industrial Vertical the Industry 4.0 Market segmented into Manufacturing, Healthcare, Energy and Utilities, Transportation and Logistics, Agriculture and Others.

Manufacturing Segment Dominated the market in 2025 and is Expected to hold largest Share during the forecast period. Dominance due to its rapid adoption of smart factory solutions, automation, and real-time data analytics. Manufacturers leveraged Industry 4.0 technologies like IoT, robotics, AI, and digital twins to enhance productivity, reduce downtime, and optimize supply chains. The push for mass customization, predictive maintenance, and operational efficiency further accelerated digital transformation in this sector.
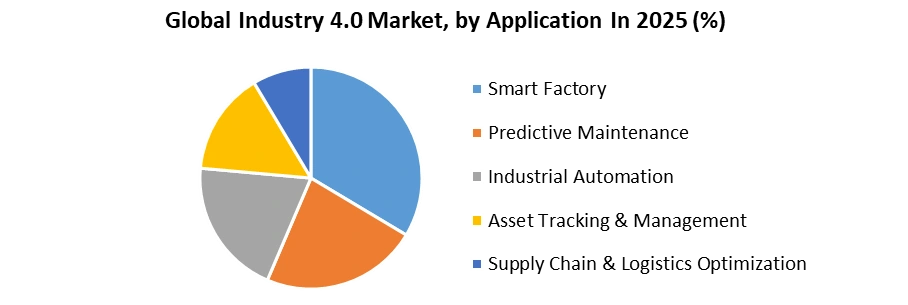
Industry 4.0 Market by Application

With regards to Organization Size, the Industry 4.0 market can be classified into Large Enterprises and Small & Medium-Sized Enterprises (SMEs). Large Enterprises were leading the market in 2025 and will continue doing so till the end of the forecast period owing to higher financial muscle, already in place digital infrastructure, and adoption of advanced technology like Artificial Intelligence (AI), Internet of Things (IoT), Robotics and Digital Twins. On the other hand, Small & Medium-Sized Enterprises (SMEs) are growing steadily driven by cloud-based Industry 4.0 solutions, government initiatives, and necessity to increase efficiency, productivity, and competitiveness.

The Industry 4.0 Market is segmented based on Deployment Mode into On-Premises, Cloud, and Hybrid. The Cloud segment has led the market since 2025 owing to its scalability, cost-effectiveness, remote availability, and capability to handle real-time analytics and AI-based applications in manufacturing. On-Premises deployment remains the choice for those enterprises that need to control their data, meet their regulatory requirements, and require lower latency. Hybrid deployment is rapidly gaining traction as manufacturers leverage on-premises infrastructure for enhanced security combined with the benefits of cloud-based solutions for better scalability.

According to the Application, the Industry 4.0 market can be classified into Smart Factory, Predictive Maintenance, Industrial Automation, Asset Tracking & Management, Supply Chain & Logistics Optimization, and others. The Smart Factory application accounted for the largest market share in 2025 and will continue its leadership position during the forecast period, owing to increasing usage of connected manufacturing, industrial IoT, AI-driven automation, and real-time production monitoring. Predictive maintenance, industrial automation, asset tracking and management, and supply chain & logistics optimization are some of the other applications which are witnessing strong growth.

The market of Industry 4.0 can be categorized based on End Use Industry as Automotive, Electronics & Semiconductor Manufacturing, Industrial Manufacturing, Process Industries, Food & Beverages, Pharmaceuticals & Healthcare Manufacturing, Metals & Mining, Energy & Power, Aerospace & Defense, Packaging, Logistics & Warehousing, Pulp & Paper, and Others. The Automotive industry has emerged as the largest segment of the market in 2025 and will continue to remain so in the coming years due to widespread use of robots, artificial intelligence, industrial Internet of Things, digital twins, and smart factory technologies that help improve production efficiency and quality of products. Other segments such as Electronics & Semiconductor Manufacturing, Industrial Manufacturing, Process Industries, Pharmaceuticals, Energy & Power, and Logistics & Warehousing are also showing substantial adoption of Industry 4.0 technologies.

Competitive Analysis – Global Industrial 4.0 Market

There is intense competition in the global market for Industrial 4.0 because there has been increased transition from automation technologies towards smart and AI-driven factories. There are firms such as Siemens AG, ABB Ltd., Rockwell Automation, Inc., and Schneider Electric SE which have increased competitiveness through the integration of automation, robots, IoT, and digitization technology. Such companies are ensuring that there is connection between machines in the production process while collecting production data for efficient operations within the factories. The current trend is that the competition is moving from the provision of equipment to offering of smart factory ecosystems. Siemens AG has intensified its strategy towards industrial digitalization by partnering further with the company NVIDIA Corporation to offer more AI and digital twin technology.

There is intense competition from tech companies offering AI, cloud computing, and edge computing in the industrial sector. Companies such as Microsoft Corporation, IBM Corporation, Cisco Systems Inc., and Intel Corporation are ensuring that there is enhanced connectivity, cybersecurity, data analysis, and data processing in the manufacturing industries.In the software segment, companies like SAP SE, PTC Inc., AVEVA Group, and Oracle Corporation are supporting manufacturers to connect their enterprise systems with factories using manufacturing software, digital twins, and industrial data platforms.

Robots and Automation is another important segment which is driving competition among manufacturers as they seek intelligent production systems. Some of the leading companies in this segment include FANUC Corporation, KUKA AG, Universal Robots, Mitsubishi Electric Corporation, and DENSO Corporation. These companies are no longer limiting themselves to building robots but are increasingly focusing on providing collaborative robots, AI-based automation, and manufacturing solutions. Similarly, industrial technology companies such as Bosch Rexroth AG, Festo AG & Co. KG, Cognex Corporation, Pepperl+Fuchs SE, and TRUMPF GmbH + Co. KG continue to support the adoption of Industry 4.0.

Organizations have also used partnership, acquisition, and technology growth strategies to improve their positioning in the market for Industrial 4.0. Schneider Electric SE has been improving its digital industrial capability through increasing its concentration in industrial data, automation software, and connectivity. In addition to this, there are players specializing in additive manufacturing, warehouse automation, and intelligent logistics including Stratasys Ltd., Swisslog Holding AG, Addverb Technologies, and Kion Group that have been growing in solutions. In general, the market seems to be moving towards a future where the organizations that are able to combine automation, artificial intelligence, software, connectivity, and industrial know-how would achieve a competitive advantage.

Industry 4.0 Market Regional Insights

The region of North America had the highest share in the Industry 4.0 market globally in 2025 and will dominate the industry for the forecast period. This is because of heavy investments in industrial automation, artificial intelligence (AI), industrial Internet of Things (IIoT), robotics, cloud computing, and advanced manufacturing. This is further aided by government initiatives such as the CHIPS and Science Act in the United States and continued investments in smart manufacturing by the U.S. Department of Energy. Besides, the region enjoys rapid adaptation of digital factory solutions in automotive, aerospace, electronics, health care, and logistics industries. Besides, the region enjoys availability of leading technology vendors, excellent research organizations, advanced digital infrastructure, and high-quality human capital that help in implementing AI-enabled production, predictive maintenance, digital twins, and interconnected supply chain management. The increasing investments in cybersecurity solutions and growth in edge computing have bolstered the region as the leading market for Industry 4.0 solutions.

The Asia-Pacific region is projected to grow at the fastest rate during the forecast period due to industrialization and capacity expansion along with smart manufacturing initiatives by governments in China, Japan, South Korea, and India. Such initiatives like “Made in China 2025,” “Society 5.0” in Japan, “Manufacturing Innovation 3.0” in South Korea, and “Make in India” are promoting the use of industrial IoT, robotics, artificial intelligence, and factory automation on a large scale. The increased investments in the manufacturing of semiconductors, electronics, electric vehicles, and digital infrastructure along with the increased adoption of smart factories by leading manufacturers globally have resulted in rapid growth in the regional market.


The United States has emerged as a leader in the adoption of Industry 4.0 technologies, particularly evident in the manufacturing sector. With a strong emphasis on integrating cutting-edge technologies such as IoT, big data, DevOps, and mobility into their processes, US manufacturers are experiencing significant growth and innovation which drive regional Industry 4.0 Market growth. This trend is powered by heavy investments in research and development, coupled with the flexibility of SMEs and the substantial digitization efforts of large corporations including IBM and General Electric. The US boasts a strong ecosystem for Industry 4.0, with notable advancements in areas such as 3D printing, big data analytics, and robotics, positioning the country as a global leader in the Industry 4.0 landscape.

Recent Developments

Date Company Development Impact
12 January 2026 Siemens AG Siemens completed the strategic acquisition of Canopus AI, a developer of computational and AI-driven metrology solutions. The transaction expands Siemens' semiconductor digital thread by integrating AI-powered inspection capabilities into EDA and smart manufacturing workflows.
04 May 2026 Lattice Semiconductor Lattice Semiconductor entered into a definitive agreement to acquire AMI from THL Partners in a transaction valued at $1.65 billion. The deal combines low-power FPGAs with platform firmware to create an end-to-end secure management platform for Industry 4.0 and AI infrastructure.
04 May 2026 SAP SE SAP SE announced an agreement to acquire Dremio, an open, high-performance data lakehouse platform. The acquisition enables industrial enterprises to unify SAP and non-SAP data to power real-time analytics and agentic AI workloads.
06 August 2026 Emerson Electric Co. Emerson acquired Glue Inc., an innovator in advancing intelligent validation and test via its AI-enabled software product Glue Studio. The deal accelerates Emerson's test and measurement automation capabilities, driving the transition toward autonomous manufacturing environments.
22 October 2026 Rockwell Automation Rockwell Automation launched FactoryTalk Conductor, an AI orchestration platform for industrial automation. The platform connects AI agents, skills, and workflows across engineering and operations, ushering in agentic automation for smart factories.

Industry 4.0 Market Scope: Inquire before buying

Global Industry 4.0 Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 141.95 USD Billion
Forecast Period 2026-2034 CAGR: 20.07% Market Size in 2034: 736.29 USD Billion
Segments Covered: by Technology Artificial Intelligence / Machine Learning
Big Data & Advanced Analytics
Cloud Computing (public/private/hybrid)
Edge Computing
Digital Twin
Industrial Robotics & Cobots
Industrial Automation & Control Systems (NEW)
PLC (Programmable Logic Controllers)
  SCADA
    DCS
    MES
    Industrial Controllers
Additive Manufacturing (3D printing)
AR/VR (augmented & virtual reality)
Blockchain for industrial traceability
5G & Industrial Connectivity
Industrial Ethernet
     Fieldbus
     Wireless Industrial Communication
      IIoT Connectivity
Cybersecurity (OT security, ICS security)
Others
by Component Hardware
Software
Services
by Deployment Model On-Premises
Cloud
Hybrid
by Application Smart Factory
Predictive Maintenance
Industrial Automation
Asset Tracking & Management
Supply Chain & Logistics Optimization
Others
by End-Use Industry Automotive
Electronics & semiconductor manufacturing
Industrial manufacturing / discrete manufacturing
Process industries (chemicals, oil & gas, refining)
Food & beverages
Metals & mining
Others

Industry 4.0 Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Industry 4.0 Key Players

North America
1. Rockwell Automation, Inc.
2. Honeywell International Inc.
3. Microsoft Corporation
4. IBM Corporation
5. General Electric Company
6. Cisco Systems, Inc.
7. Oracle Corporation
8. PTC Inc.
9. NVIDIA Corporation
10. Intel Corporation
11. Cognex Corporation
12. Autodesk, Inc.
13. Amazon Web Services
14. Dell Technologies
15. Hewlett Packard Enterprise
Others
Europe
16. Siemens AG
17. ABB Ltd. Schneider Electric SE
18. Emerson Electric Co.
19. Robert Bosch GmbH
20. SAP SE
21. KUKA AG
22. Dassault Systèmes
23. AVEVA Group plc
24. SICK AG
25. Turck GmbH
26. Beckhoff Automation GmbH
27. Phoenix Contact GmbH & Co. KG
Others
Asia Pacific
28. Mitsubishi Electric Corporation
29. Fanuc Corporation
30. Yokogawa Electric Corporation
31. Omron Corporation
32. Keyence Corporation
33. Advantech Co., Ltd.
34. Moxa Inc.
35. Tata Consultancy Services
36. Infosys Limited
37. Wipro Limited
38. L&T Technology Services Limited
Rest of the World (Latin America, Middle East & Africa)
39. Honeywell International Inc.
40. Schneider Electric SE
41. Siemens AG
42. ABB Ltd.
43. Rockwell Automation, Inc.
44. Emerson Electric Co.
45. Cisco Systems, Inc.
46. Microsoft Corporation
47. IBM Corporation
48. Oracle Corporation
Others

Frequently Asked Questions:

1] What is the growth rate of the Global Industry 4.0 Market?
Ans. The Global Industry 4.0 Market is growing at a significant rate of 20.07% during the forecast period.

2] Which region is expected to dominate the Global Industry 4.0 Market?
Ans. North America is expected to dominated the Industry 4.0 Market during the forecast period.

3] What is the expected Global Industry 4.0 Market size by 2034?
Ans. The Industry 4.0 Market size is expected to reach USD 736.29 Billion by 2034.

4] Which are the top players in the Global Industry 4.0 Market?
Ans. The major top players in the Global Industry 4.0 Market are Siemens AG (Munich, Germany), General Electric (GE) (Boston, Massachusetts, USA), Bosch (Stuttgart, Germany), ABB Ltd (Zurich, Switzerland), Schneider Electric (Rueil-Malmaison, France) and Others.

5] What are the factors driving the Global Industry 4.0 Market growth?
Ans. Technological Advancements and increasing demand for operational efficiency are expected to drive market growth during the forecast period.

Table of Contents

1.SECTION A – GLOBAL INDUSTRY 4.0 MARKET INTRODUCTION 1.1. Executive Market Landscape and Industry Overview 1.1.1. Global Industry 4.0 Market Size (Value USD Million), 2025–2034 1.1.2. Overview of Industry 4.0 Industry 1.1.3. Scope and Market Definition 1.1.4. Key Market Highlights and Strategic Insights 1.1.5. Industry Evolution and Historical Overview 1.1.6. Market Stakeholder Ecosystem Analysis 1.2. Global Industry 4.0 Market Dynamics 1.2.1. Industry 4.0 Market Trends 1.2.2. Industry 4.0 Market Dynamics 1.2.3. Drivers 1.2.4. Restraints 1.2.5. Opportunities 1.2.6. Challenges 1.2.7. PORTER’s Five Forces Analysis 1.2.8. PESTLE Analysis 1.3. Industry 4.0 Industry Landscape & Market Structure 1.3.1. Global Industry 4.0 Ecosystem Structure Across Smart Manufacturing, Industrial Automation, Industrial IoT (IIoT), Robotics, Digital Twin, AI, Analytics, and Connected Factory Solutions 1.3.2. Industry 4.0 Value Chain Covering Technology Development, Industrial Hardware Manufacturing, Software Platforms, Cloud & Edge Infrastructure, System Integration, Industrial Connectivity, Deployment, Training, Maintenance, and Lifecycle Services 1.3.3. Evolution of Industry 4.0 Across Manufacturing Sectors Including Automotive, Electronics & Semiconductors, Aerospace & Defense, Energy & Utilities, Pharmaceuticals, Food & Beverage, Chemicals, and Heavy Industries 1.3.4. Integration of Industry 4.0 Technologies with Artificial Intelligence, Machine Learning, Big Data Analytics, Cloud Computing, Edge Computing, Digital Twins, Industrial Robotics, Additive Manufacturing, AR/VR, and Industrial IoT Platforms 1.3.5. Industry Consolidation, Strategic Partnerships, Mergers & Acquisitions, Technology Alliances, and Expansion of Industrial Automation & Digital Transformation Portfolios 1.4. Industry 4.0 Infrastructure and Smart Factory Assessment 1.4.1. Global Industry 4.0 Infrastructure Assessment Across Manufacturing Plants, Smart Factories, Industrial Facilities, Process Industries, and Critical Infrastructure Sectors 1.4.2. Digital Infrastructure Assessment Including Industrial IoT (IIoT) Platforms, Cloud Computing, Edge Computing, Industrial Networks, Data Centers, and Connected Industrial Assets 1.4.3. Industrial Automation Infrastructure Assessment Including PLCs, SCADA Systems, DCS, MES, Industrial Robots, Sensors, Actuators, and Automated Production Systems 1.4.4. Technology Lifecycle Management Across Deployment, System Integration, Software Updates, Predictive Maintenance, Cybersecurity Management, Data Backup, and Industrial System Upgrades 1.4.5. Operational Efficiency Assessment Across Production Optimization, Asset Monitoring, Quality Control, Supply Chain Visibility, Energy Management, and Workforce Productivity 1.4.6. Regional Industrial Digital Infrastructure Supporting Industry 4.0 Adoption Across North America, Europe, Asia-Pacific, Middle East & Africa, and Latin America 1.4.7. Future Smart Factory Infrastructure Investment Outlook Driven by AI, Industrial Automation, Robotics, 5G Connectivity, Edge Computing, and Autonomous Manufacturing 1.5. Global Industry 4.0 Demand Assessment 1.5.1. Historical Demand Trends Across Cloud-Based, On-Premises, and Hybrid Industry 4.0 Solutions 1.5.2. Regional Demand Assessment Across North America, Europe, Asia-Pacific, Middle East & Africa, and Latin America 1.5.3. Demand Analysis Across AI & Machine Learning, Industrial IoT, Robotics, Digital Twin, Big Data Analytics, Cloud Computing, Edge Computing, Cybersecurity, and Industrial Networks 1.5.4. Large Enterprises Versus Small & Medium Manufacturing Enterprises (SMEs) Industry 4.0 Adoption Comparison 1.5.5. Discrete Manufacturing Versus Process Manufacturing Industry 4.0 Technology Demand Assessment 1.5.6. Demand Outlook Across New Smart Factory Establishments and Existing Factory Digital Transformation Initiatives 1.5.7. Long-Term Demand Outlook Driven by Autonomous Factories, AI-Based Automation, Industrial 5G, Predictive Maintenance, Sustainable Manufacturing, and Connected Supply Chains 1.6. Industry 4.0 Technology Portfolio and Solution Assessment 1.6.1. Comparative Assessment of Industry 4.0 Technology Platforms, Software Solutions, Industrial Connectivity, and Digital Transformation Capabilities 1.6.2. Performance Benchmarking Across Cloud-Based, On-Premises, Hybrid, AI-Enabled, Edge-Based, and Integrated Industry 4.0 Platforms 1.6.3. Industrial Technology Pricing Models, Subscription Models, Licensing Structures, and Total Cost of Ownership (TCO) Assessment 1.6.4. Industrial Standards, Regulatory Compliance, Data Governance, and Interoperability Assessment 1.6.5. Cybersecurity Assessment Covering OT Security, ICS Security, Network Protection, Threat Monitoring, and Data Protection Requirements 1.6.6. Industrial Connectivity Assessment Covering 5G Networks, Industrial Ethernet, Fieldbus, Wireless Communication, and Edge Connectivity 1.6.7. Government Digital Manufacturing Initiatives, Smart Factory Programs, Industry 4.0 Policies, and Incentives Supporting Industrial Digital Transformation 1.7. AI & Digital Transformation Solutions Assessment 1.7.1. AI adoption across smart factories and industrial automation 1.7.2. AI applications: predictive maintenance, machine vision, process optimization, and autonomous operations 1.7.3. Integration of AI with IIoT, Edge Computing, Cloud, Robotics, PLC, SCADA, and MES 1.7.4. Impact on productivity, quality improvement, and operational efficiency 1.7.5. AI governance, industrial data management, and future autonomous manufacturing trends 1.8. Cybersecurity & Industrial Data Management Assessment 1.8.1. OT security and ICS cybersecurity assessment across Industry 4.0 platforms 1.8.2. Industrial cybersecurity solutions: encryption, access control, threat detection, and monitoring 1.8.3. Protection of PLC, SCADA, industrial networks, and connected assets 1.8.4. Cloud, Edge, and industrial data security management 1.8.5. Cybersecurity standards, compliance, and future secure smart factory trends 1.9. Discrete Event Simulation (DES), Advanced Simulation Modeling, and Process Optimization 1.9.1. Event-Based Simulation Modeling Supporting Dynamic Process Analysis 1.9.2. What-If Scenario Simulation Improving Operational Decision-Making 1.9.3. Bottleneck Identification Enhancing Process Efficiency 1.9.4. Resource and Capacity Modeling Optimizing Asset Utilization 1.9.5. Production and Workflow Simulation Improving Throughput Performance 1.9.6. Optimization Algorithms Supporting Cost, Time, and Resource Efficiency 1.10. Process Digital Twin Development, Integration, and Operational Optimization 1.10.1. Real-Time Process Replication Enabling Operational Visibility 1.10.2. Data Integration Architecture Connecting Physical and Digital Systems 1.10.3. Virtual Process Modeling Supporting Performance Analysis 1.10.4. Predictive Process Analytics Improving Operational Outcomes 1.10.5. Digital Twin Synchronization Enhancing Real-Time Decision-Making 1.10.6. Process Optimization Capabilities Driving Continuous Operational Improvement 1.11. Customer Behavior & Procurement Analysis 1.11.1. Industry 4.0 adoption behavior across manufacturers, smart factories, and industrial sectors 1.11.2. Key vendor selection criteria: scalability, integration, cybersecurity, automation capabilities, and cost 1.11.3. Procurement models across licensing, SaaS, cloud, and enterprise agreements 1.11.4. Customer preference for AI-enabled, IIoT, cloud-based, and integrated automation platforms 1.11.5. Purchasing trends across large enterprises and SMEs 1.11.6. Vendor evaluation, implementation, training, and upgrade processes 1.11.7. Future customer expectations for autonomous factories and digital transformation 1.12. Pricing Dynamics & Cost Structure Assessment 1.12.1. Global pricing trends across Industry 4.0 technologies 1.12.2. Cost assessment of AI, IIoT, robotics, digital twins, automation software, and cybersecurity solutions 1.12.3. Cost structure covering software development, hardware, cloud infrastructure, integration, deployment, and support 1.12.4. Cloud-based versus on-premises Industry 4.0 cost comparison 1.12.5. Pricing models including subscription, licensing, usage-based, and enterprise contracts 1.12.6. Total cost of ownership (TCO) analysis for smart factory solutions 1.12.7. Future pricing outlook driven by AI adoption and industrial digitalization 1.13. Research & Development Landscape 1.13.1. Global R&D trends across Industry 4.0, AI, robotics, IIoT, and automation technologies 1.13.2. Development of advanced AI-based manufacturing, predictive maintenance, and autonomous systems 1.13.3. Innovation in industrial robotics, digital twins, edge computing, and industrial networks 1.13.4. Research in cybersecurity, 5G connectivity, and smart factory technologies 1.13.5. Collaboration among technology providers, manufacturers, research institutions, and automation companies 1.13.6. Future R&D roadmap supporting intelligent, connected, and autonomous industrial ecosystems 1.14. Patent & Innovation Trends 1.14.1. Global patent activity across Industry 4.0, AI, robotics, IIoT, automation, and smart manufacturing technologies 1.14.2. Patent landscape covering digital twins, industrial analytics, PLC systems, autonomous robots, and industrial software 1.14.3. Innovation in AI-based manufacturing, predictive maintenance, and connected factory solutions 1.14.4. Emerging technologies supporting automation, edge computing, 5G connectivity, and industrial interoperability 1.14.5. Regional innovation hubs and technology leadership assessment 1.14.6. Future innovation pipeline supporting autonomous factories and intelligent industrial ecosystems 1.15. Technology Advancement Landscape 1.15.1. Emerging Industry 4.0 Technologies and Technology Maturity Assessment 1.15.2. Next-Generation AI, Edge Computing, Digital Twin and Industrial IoT Technologies 1.15.3. Evolution of Autonomous Manufacturing and Intelligent Production Systems 1.15.4. Advanced Machine Vision, Predictive Analytics and Real-Time Monitoring 1.15.5. Industrial Connectivity and Interoperability Advancements 1.15.6. Future technology roadmap for smart factories, autonomous manufacturing, and Industry 4.0 evolution 1.16. Patent & Innovation Trends 1.16.1. Global patent activity across Industry 4.0 equipment, automation systems, AI, robotics, and digital technologies 1.16.2. Patent landscape covering industrial robots, PLC systems, IIoT platforms, digital twins, and smart factory solutions 1.16.3. Innovation in predictive maintenance, industrial analytics, autonomous operations, and energy-efficient manufacturing 1.16.4. Emerging technologies supporting remote monitoring, edge computing, 5G connectivity, and industrial automation 1.16.5. Regional innovation hubs and technology leadership assessment 1.16.6. Future innovation pipeline supporting smart factories and operational excellence 1.17. Technology Advancement Landscape 1.17.1. Digital manufacturing technologies including AI, IoT, Cloud Computing, Edge Computing, and Digital Twins 1.17.2. Robotics, automation, PLC, SCADA, and advanced industrial control technologies 1.17.3. Industrial inspection, machine vision, predictive maintenance, and asset monitoring solutions 1.17.4. Smart factory monitoring and real-time industrial analytics 1.17.5. Integrated digital platforms supporting production management, asset lifecycle management, and operational optimization 1.17.6. Future technologies enabling autonomous manufacturing and connected industrial ecosystems 1.18. Software Architecture & Implementation Assessment 1.18.1. Software architecture across cloud-based, on-premises, and hybrid Industry 4.0 platforms 1.18.2. Integration with PLC, SCADA, MES, IIoT platforms, industrial equipment, and third-party systems 1.18.3. Data migration, software deployment, workforce training, and change management strategies 1.18.4. Cybersecurity, data protection, system reliability, and industrial compliance assessment 1.18.5. Integration of AI, APIs, cloud infrastructure, and interoperability standards 1.18.6. Implementation challenges across large enterprises, SMEs, and multi-site manufacturing facilities 1.18.7. Future software development and deployment practices supporting smart manufacturing transformation 1.19. Comparative Assessment of Industry 4.0 Deployment Models, Technology Architectures and Solution Approaches 1.19.1. Comparative analysis of cloud-based, on-premises, and hybrid Industry 4.0 solutions 1.19.2. AI-enabled versus conventional automation and industrial digital solutions 1.19.3. Standalone versus integrated smart factory platforms 1.19.4. Comparative assessment of robotics, IIoT, digital twin, PLC, SCADA, and analytics technologies 1.19.5. Cost-to-performance benchmarking across major Industry 4.0 technology categories 1.19.6. Technology suitability across manufacturing sectors, SMEs, and large enterprises 1.19.7. Future competitiveness of AI-driven, cloud-based, and autonomous Industry 4.0 solutions 1.20. Trade & Global Market Access Assessment 1.20.1. Global trade flow across Industry 4.0 hardware, software platforms, automation systems, and industrial technologies 1.20.2. Major technology exporting and importing countries 1.20.3. Software localization strategies, industrial standards, and regional compliance requirements 1.20.4. Regional competitiveness in Industry 4.0 adoption and technology development 1.20.5. Supply-demand assessment across global smart manufacturing markets 1.20.6. Impact of geopolitics, cybersecurity regulations, and cross-border data transfer policies 1.20.7. Future international expansion outlook for Industry 4.0 solutions 1.21. Supply Chain & Value Chain Analysis 1.21.1. End-to-end value chain assessment across the Industry 4.0 ecosystem 1.21.2. Supplier ecosystem covering automation providers, software developers, cloud providers, AI companies, robotics manufacturers, and system integrators 1.21.3. Product development, testing, deployment, integration, training, maintenance, and support ecosystem 1.21.4. Supply chain risks, technology dependencies, and implementation challenges 1.21.5. Strategic technology partnerships and vendor qualification assessment 1.21.6. Software licensing, subscription models, and industrial service delivery models 1.21.7. Future supply chain transformation supporting smart factories and connected manufacturing ecosystems 1.22. Regulatory & Compliance Landscape 1.22.1. Global Industry 4.0 regulations, industrial standards, and compliance frameworks 1.22.2. Industrial automation standards including PLC, SCADA, MES, and IIoT interoperability requirements 1.22.3. Data privacy, cybersecurity, OT security, and industrial information protection regulations 1.22.4. AI governance, industrial software compliance, and technology certification standards 1.22.5. Regional regulatory landscape across major Industry 4.0 markets 1.22.6. Quality assurance, system validation, safety standards, and certification requirements 1.22.7. Future regulatory trends impacting smart factories and Industry 4.0 providers 1.23. Channel Ecosystem & Commercial Delivery Models 1.23.1. Direct sales versus system integrator and channel partner distribution models 1.23.2. Strategic partnerships among automation vendors, software providers, cloud companies, robotics manufacturers, and industrial enterprises 1.23.3. Integrated Industry 4.0 platforms versus specialized technology solutions 1.23.4. Regional distribution networks, resellers, implementation partners, and managed service providers 1.23.5. After-sales support, maintenance, upgrades, and lifecycle management services 1.23.6. Digital platforms and cloud-based delivery models for Industry 4.0 solutions 1.23.7. Commercial models supporting long-term industrial digital transformation partnerships 1.24. Sustainability & Digital Transformation Assessment 1.24.1. Green manufacturing and sustainable Industry 4.0 strategies 1.24.2. Energy-efficient smart factories, automation optimization, and resource management 1.24.3. Sustainable cloud infrastructure and energy-efficient data centers 1.24.4. Digital technologies supporting carbon reduction, waste optimization, and operational efficiency 1.24.5. ESG reporting and sustainable industrial operations 1.24.6. Sustainable software development and technology lifecycle management 1.24.7. Future sustainability outlook across the Industry 4.0 ecosystem 1.25. Investment & Market Expansion Assessment 1.25.1. Global investment trends in Industry 4.0, smart manufacturing, automation, and digital transformation 1.25.2. Investments in AI, Industrial IoT, Cloud Computing, Edge Computing, Robotics, Digital Twins, and Cybersecurity 1.25.3. Expansion of smart factories, connected manufacturing facilities, and enterprise Industry 4.0 adoption 1.25.4. Venture capital, private equity, and strategic investment activity in industrial technology companies 1.25.5. Government initiatives, smart manufacturing programs, and public-private investments supporting Industry 4.0 adoption 1.25.6. Mergers, acquisitions, technology partnerships, and ecosystem expansion strategies 1.25.7. Long-term investment outlook and market growth forecast for Industry 4.0 transformation 1.26. Global Industry 4.0 Market: Market size and Forecast by Segmentation (by Value USD Million) (2025-2032) 1.26.1. Global Industry 4.0 Market Size and Forecast, By Technology 1.26.1.1. Artificial Intelligence / Machine Learning 1.26.1.2. Big Data & Advanced Analytics 1.26.1.3. Cloud Computing (public/private/hybrid) 1.26.1.4. Edge Computing 1.26.1.5. Digital Twin 1.26.1.6. Industrial Robotics & Cobots 1.26.1.7. Industrial Automation & Control Systems (NEW) 1.26.1.8. PLC (Programmable Logic Controllers) 1.26.1.9. SCADA 1.26.1.10. DCS 1.26.1.11. MES 1.26.1.12. Industrial Controllers 1.26.1.13. Additive Manufacturing (3D printing) 1.26.1.14. AR/VR (augmented & virtual reality) 1.26.1.15. Blockchain for industrial traceability 1.26.1.16. 5G & Industrial Connectivity 1.26.1.17. Industrial Ethernet 1.26.1.18. Fieldbus 1.26.1.19. Wireless Industrial Communication 1.26.1.20. IIoT Connectivity 1.26.1.21. Cybersecurity (OT security, ICS security) 1.26.1.22. Others 1.26.2. Global Industry 4.0 Market Size and Forecast, By Component 1.26.2.1. Hardware 1.26.2.2. Software 1.26.2.3. Services 1.26.3. Global Industry 4.0 Market Size and Forecast, By Deployment Model 1.26.3.1. On-Premises 1.26.3.2. Cloud 1.26.3.3. Hybrid 1.26.4. Global Industry 4.0 Market Size and Forecast, By Application 1.26.4.1. Smart Factory 1.26.4.2. Predictive Maintenance 1.26.4.3. Industrial Automation 1.26.4.4. Asset Tracking & Management 1.26.4.5. Supply Chain & Logistics Optimization 1.26.4.6. Others 1.26.5. Global Industry 4.0 Market Size and Forecast, By End Use 1.26.5.1. Automotive 1.26.5.2. Electronics & semiconductor manufacturing 1.26.5.3. Industrial manufacturing / discrete manufacturing 1.26.5.4. Process industries (chemicals, oil & gas, refining) 1.26.5.5. Food & beverages 1.26.5.6. Metals & mining 1.26.5.7. Others 1.26.6. Global Industry 4.0 Market Size and Forecast, By Region 1.26.6.1. North America 1.26.6.1.1. United States 1.26.6.1.2. Mexico 1.26.6.1.3. Canada 1.26.6.2. Europe 1.26.6.2.1. United Kingdom 1.26.6.2.2. France 1.26.6.2.3. Germany 1.26.6.2.4. Italy 1.26.6.2.5. Switzerland 1.26.6.2.6. Spain 1.26.6.2.7. Sweden 1.26.6.2.8. Russia 1.26.6.2.9. Rest of Europe 1.26.6.3. Asia Pacific 1.26.6.3.1. China 1.26.6.3.2. South Korea 1.26.6.3.3. Japan 1.26.6.3.4. India 1.26.6.3.5. Australia 1.26.6.3.6. Indonesia 1.26.6.3.7. Philippines 1.26.6.3.8. Malaysia 1.26.6.3.9. Vietnam 1.26.6.3.10. Thailand 1.26.6.3.11. India 1.26.6.3.12. Australia 1.26.6.3.13. Indonesia 1.26.6.3.14. Philippines 1.26.6.3.15. Malaysia 1.26.6.3.16. Vietnam 1.26.6.3.17. Thailand 1.26.6.3.18. Rest of Asia Pacific 1.26.6.4. Middle East and Africa 1.26.6.4.1. South Africa 1.26.6.4.2. Saudi Arabia 1.26.6.4.3. UAE 1.26.6.4.4. Qatar 1.26.6.4.5. Egypt 1.26.6.4.6. Nigeria 1.26.6.4.7. Rest of ME&A 1.26.6.5. South America 1.26.6.5.1. Brazil 1.26.6.5.2. Argentina 1.26.6.5.3. Colombia 1.26.6.5.4. Chile 1.26.6.5.5. Rest Of South America 2.SECTION B – COMPETITIVE INTELLIGENCE & INDUSTRIAL ECOSYSTEM 2.1. Competitive Landscape 2.1.1. MMR Competition Matrix 2.1.2. Competitive Positioning of Leading Key Players [Revenue and Market Share(%)] 2.1.3. Key Players Benchmarking 2.1.4. Company Name 2.1.5. Headquarter 2.1.6. Product Portfolio 2.1.7. Price Competitiveness 2.1.8. Revenue (2025) 2.1.9. R&D Investment 2.1.10. Profit Margin (%) 2.1.11. Growth Rate (Y-o-Y %) 2.1.12. Patent Portfolio 2.1.13. Geographic Presence 2.1.14. Market Structure 2.1.15. Market Leaders 2.1.16. Market Followers 2.1.17. Emerging Players 2.1.18. Mergers and Acquisitions Details 2.1.19. Recent Key Developments 2.1.20. Sustainability & ESG Positioning 2.1.21. Geographic Presence 2.2. Company Profiles: Key Industry 4.0 Providers 2.2.1. Detailed Company Profile Parameters 2.2.2. Corporate Overview and Business Structure 2.2.3. Product Portfolio and Core Software Capabilities 2.2.4. Geographic Presence and Global Customer Footprint 2.2.5. Revenue Analysis and Business Segment Contribution 2.2.6. Employee Strength and R&D Workforce 2.2.7. Software Platforms, Cloud Infrastructure, and Technology Assets 2.2.8. Technology Portfolio, AI Capabilities, Robotics, Automation, PLC and Smart Sensor Solutions 2.2.9. Patent Portfolio and Proprietary Technologies 2.2.10. ESG and Sustainability Strategy 2.2.11. Strategic Initiatives, Partnerships, Acquisitions, and Future Expansion Plans 2.2.12. SWOT Analysis 2.2.13. Recent Developments 2.2.13.1 North America 2.2.14. Rockwell Automation, Inc. 2.2.15. Honeywell International Inc. 2.2.16. Microsoft Corporation 2.2.17. IBM Corporation 2.2.18. General Electric Company 2.2.19. Cisco Systems, Inc. 2.2.20. Oracle Corporation 2.2.21. PTC Inc. 2.2.22. NVIDIA Corporation 2.2.23. Intel Corporation 2.2.24. Cognex Corporation 2.2.25. Autodesk, Inc. 2.2.26. Amazon Web Services 2.2.27. Dell Technologies 2.2.28. Hewlett Packard Enterprise 2.2.28.1 Others 2.2.28.2 Europe 2.2.29. Siemens AG 2.2.30. ABB Ltd. Schneider Electric SE 2.2.31. Emerson Electric Co. 2.2.32. Robert Bosch GmbH 2.2.33. SAP SE 2.2.34. KUKA AG 2.2.35. Dassault Systèmes 2.2.36. AVEVA Group plc 2.2.37. SICK AG 2.2.38. Turck GmbH 2.2.39. Beckhoff Automation GmbH 2.2.40. Phoenix Contact GmbH & Co. KG 2.2.40.1 Others 2.2.40.2 Asia Pacific 2.2.41. Mitsubishi Electric Corporation 2.2.42. Fanuc Corporation 2.2.43. Yokogawa Electric Corporation 2.2.44. Omron Corporation 2.2.45. Keyence Corporation 2.2.46. Advantech Co., Ltd. 2.2.47. Moxa Inc. 2.2.48. Tata Consultancy Services 2.2.49. Infosys Limited 2.2.50. Wipro Limited 2.2.51. L&T Technology Services Limited 2.2.52. Rest of the World (Latin America, Middle East & Africa) 2.2.53. Honeywell International Inc. 2.2.54. Schneider Electric SE 2.2.55. Siemens AG 2.2.56. ABB Ltd. 2.2.57. Rockwell Automation, Inc. 2.2.58. Emerson Electric Co. 2.2.59. Cisco Systems, Inc. 2.2.60. Microsoft Corporation 2.2.61. IBM Corporation 2.2.62. Oracle Corporation 2.2.62.1 Others 2.3. Product Portfolio & Technical Capability Benchmarking 2.3.1. Comparative Assessment of Practice Management, Electronic Dental Records (EDR), Imaging, Treatment Planning, Patient Communication, Billing, and Analytics Software Portfolios 2.3.2. Benchmarking of Integrated Industry 4.0 Suites Versus Standalone Software Solutions 2.3.3. Comparative Analysis of Cloud-Based, On-Premises, AI-Enabled, and Mobile Industry 4.0 Platforms 2.3.4. Evaluation of AI Diagnostics, Digital Imaging, CAD/CAM Integration, Teledentistry, Patient Engagement, and Clinical Decision Support Capabilities 2.3.5. Assessment of System Integration with CBCT, Intraoral Scanners, Digital X-ray Systems, EHR, and Third-Party Applications 2.3.6. Portfolio Gap Analysis and Identification of High-Growth Software Segments 2.4. Operational Infrastructure & Implementation Benchmarking 2.4.1. Comparative Assessment of Global Manufacturing Customer Presence 2.4.2. Regional Technical Support and Service Networks 2.4.3. Robotics and Automation System Integration Capabilities 2.4.4. PLC and Industrial Control System Implementation Capabilities 2.4.5. Smart Sensor Deployment and Industrial Connectivity Capabilities 2.4.6. Technical Support, Training and Maintenance Infrastructure 2.4.7. System Integration and Deployment Methodologies 2.4.8. Software and Hardware Reliability Assessment 2.4.9. Cybersecurity and System Performance Benchmarking 2.4.10. Regional Scalability and Multi-Site Deployment Capabilities 2.5. Technology & Innovation Benchmarking 2.5.1. Comparative Assessment of Robotics Technologies 2.5.2. Industrial Automation Technology Benchmarking 2.5.3. PLC Architecture and Performance Benchmarking 2.5.4. Smart Sensor Technology Benchmarking 2.5.5. AI-Enabled Robotics and Automation Capabilities 2.5.6. Collaborative Robotics and Autonomous Systems 2.5.7. Machine Vision and Intelligent Sensing 2.5.8. Edge Computing and Industrial IoT Integration 2.5.9. PLC–SCADA–MES Integration Capabilities 2.5.10. Industrial Communication and Interoperability 2.5.11. Predictive Maintenance and Real-Time Monitoring 2.5.12. Cybersecurity and Functional Safety Capabilities 2.5.13. Future Technology Leadership Assessment 2.6. Supply Chain, Procurement & Strategic Sourcing Benchmarking 2.6.1. Robotics Component Sourcing Strategies 2.6.2. Industrial Automation Hardware Procurement 2.6.3. PLC Component and Semiconductor Supply Assessment 2.6.4. Smart Sensor Component Sourcing 2.6.5. Supplier Diversification Strategies 2.6.6. Strategic Technology Partnerships 2.6.7. System Integrator and OEM Partnerships 2.6.8. Industrial Hardware and Software Procurement Models 2.6.9. Supply Chain Risk Assessment 2.6.10. Semiconductor and Electronic Component Dependency 2.6.11. Regional Manufacturing and Supplier Networks 2.6.12. Supply Continuity and Resilience Assessment 2.7. Innovation, Patent & Digital Transformation Benchmarking 2.7.1. Comparative R&D Investment Across Leading Industry 4.0 Players 2.7.2. Robotics Patent Benchmarking 2.7.3. Industrial Automation Patent Benchmarking 2.7.4. PLC Technology Patent Benchmarking 2.7.5. Smart Sensor Patent Benchmarking 2.7.6. AI and Machine Learning Innovation 2.7.7. Autonomous Robotics Innovation 2.7.8. Intelligent Automation Innovation 2.7.9. Predictive Maintenance Technologies 2.7.10. Industrial IoT and Edge Computing Innovation 2.7.11. Technology Innovation Pipeline 2.7.12. Future Digital Transformation Leadership 2.8. Geographic Presence & Commercial Delivery Network Analysis — Industry 4.0 Market 2.8.1. Global Manufacturing and R&D Footprint 2.8.2. Regional Robotics and Automation Operations 2.8.3. PLC and Industrial Control System Distribution Networks 2.8.4. Smart Sensor Sales and Distribution Networks 2.8.5. System Integrator and Channel Partner Networks 2.8.6. Regional Technical Support Infrastructure 2.8.7. OEM and Industrial Customer Coverage 2.8.8. Direct Sales vs. Distributor Models 2.8.9. After-Sales Service and Maintenance Networks 2.8.10. Regional Expansion Strategies 2.9. Strategic Initiatives, Industry Alliances & Growth Strategies 2.9.1 Industry 4.0 Market 2.9.1. Mergers and Acquisitions in Robotics and Automation 2.9.2. PLC and Industrial Control Technology Partnerships 2.9.3. Smart Sensor Technology Partnerships 2.9.4. Robotics–AI Collaborations 2.9.5. Automation–IIoT Integration Strategies 2.9.6. Strategic OEM and System Integrator Partnerships 2.9.7. Geographic Expansion Strategies 2.9.8. Product Portfolio Expansion 3.SECTION C – KEY INSIGHTS, STRATEGIC OUTLOOK & METHODOLOGICAL FRAMEWORK 3.1. Key Findings 3.2. Strategic Moves & Industry Outlook 3.3. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements