
Graphite Market by Type, Application, End-User, and Region – Global Market Size Estimation, Industry-Wide Analysis, Competitive Landscape Assessment & Long-Term Forecast to 2034
Overview
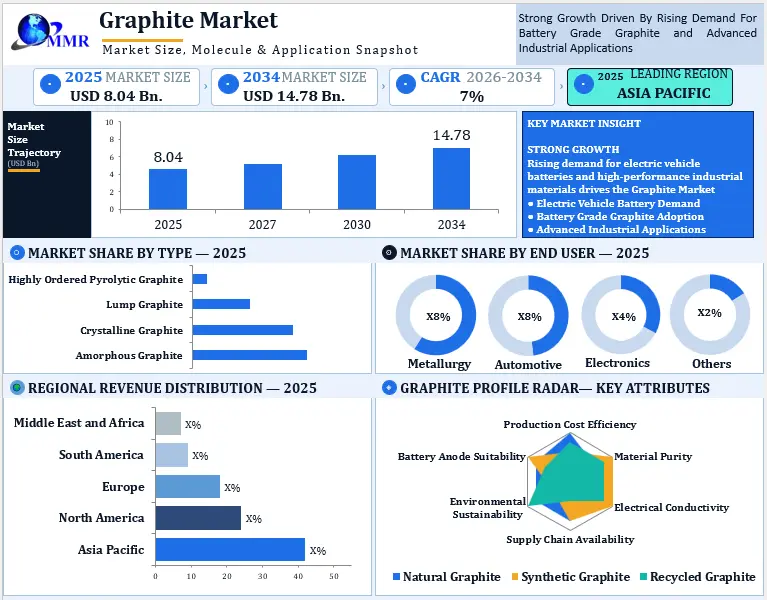
The Graphite Market size was valued at USD 8.04 Billion in 2025 and the total Graphite revenue is expected to grow at a CAGR of 7% from 2026 to 2034, reaching USD 14.78 Billion by 2034.
Graphite Market Overview:
Graphite is a naturally occurring form of carbon that serves as a critical industrial mineral for energy storage, electric vehicle batteries, steelmaking, refractory materials, lubricants, and advanced manufacturing. Its electrical conductivity, thermal stability, and layered structure make graphite an essential raw material for lithium-ion battery anodes and other high-performance industrial applications. Growing demand for battery-grade graphite, synthetic graphite, natural graphite, and high-purity graphite is strengthening its importance across the energy transition and modern industrial supply chains.
The graphite market is growing as electric vehicle production, renewable energy storage, battery manufacturing, and advanced industrial applications increase demand for high-quality graphite materials. Leading manufacturers such as Syrah Resources and BTR New Material Group contribute to the development of graphite mining, processing, purification, and battery anode production. Asia Pacific remains a major hub for graphite processing and battery material manufacturing, supported by its established electric vehicle and lithium-ion battery supply chains. Industry developments tracked by agencies such as the United States Geological Survey help explain natural graphite production, reserves, trade patterns, and supply chain concentration. Increasing electric vehicle adoption, battery energy storage installations, domestic critical mineral strategies, and demand for locally processed battery materials are reshaping graphite market growth, competition, and investment opportunities.
MMR's graphite market research provides an in-depth assessment of market trends, industry drivers, restraints, emerging opportunities, competitive positioning, and regional demand across graphite types, applications, end users, and geographical markets. The analysis helps clients identify growth opportunities in battery-grade graphite, sustainable graphite processing, synthetic graphite innovation, supply chain diversification, and advanced energy storage materials while evaluating market positioning and long-term business potential.
Graphite Market Growth Outlook
To know about the Research Methodology :- Request Free Sample Report
Global Graphite Market Key Highlights
| Key Highlight | Analytical Insights |
| Graphite Market Size, Growth Rate and Revenue Forecast | The graphite market is valued at USD 8.04 billion in 2025 and is projected to reach USD 14.78 billion by 2034, expanding at a CAGR of 7% during 2026–2034, driven by increasing demand for industrial graphite, battery materials, and advanced carbon products. |
| Asia Pacific Graphite Market Leadership | Asia Pacific leads the graphite market through established graphite processing, battery anode manufacturing, electric vehicle production, and steelmaking industries. China remains a major supply chain hub, while India, Japan, and South Korea contribute to regional demand and advanced material development. |
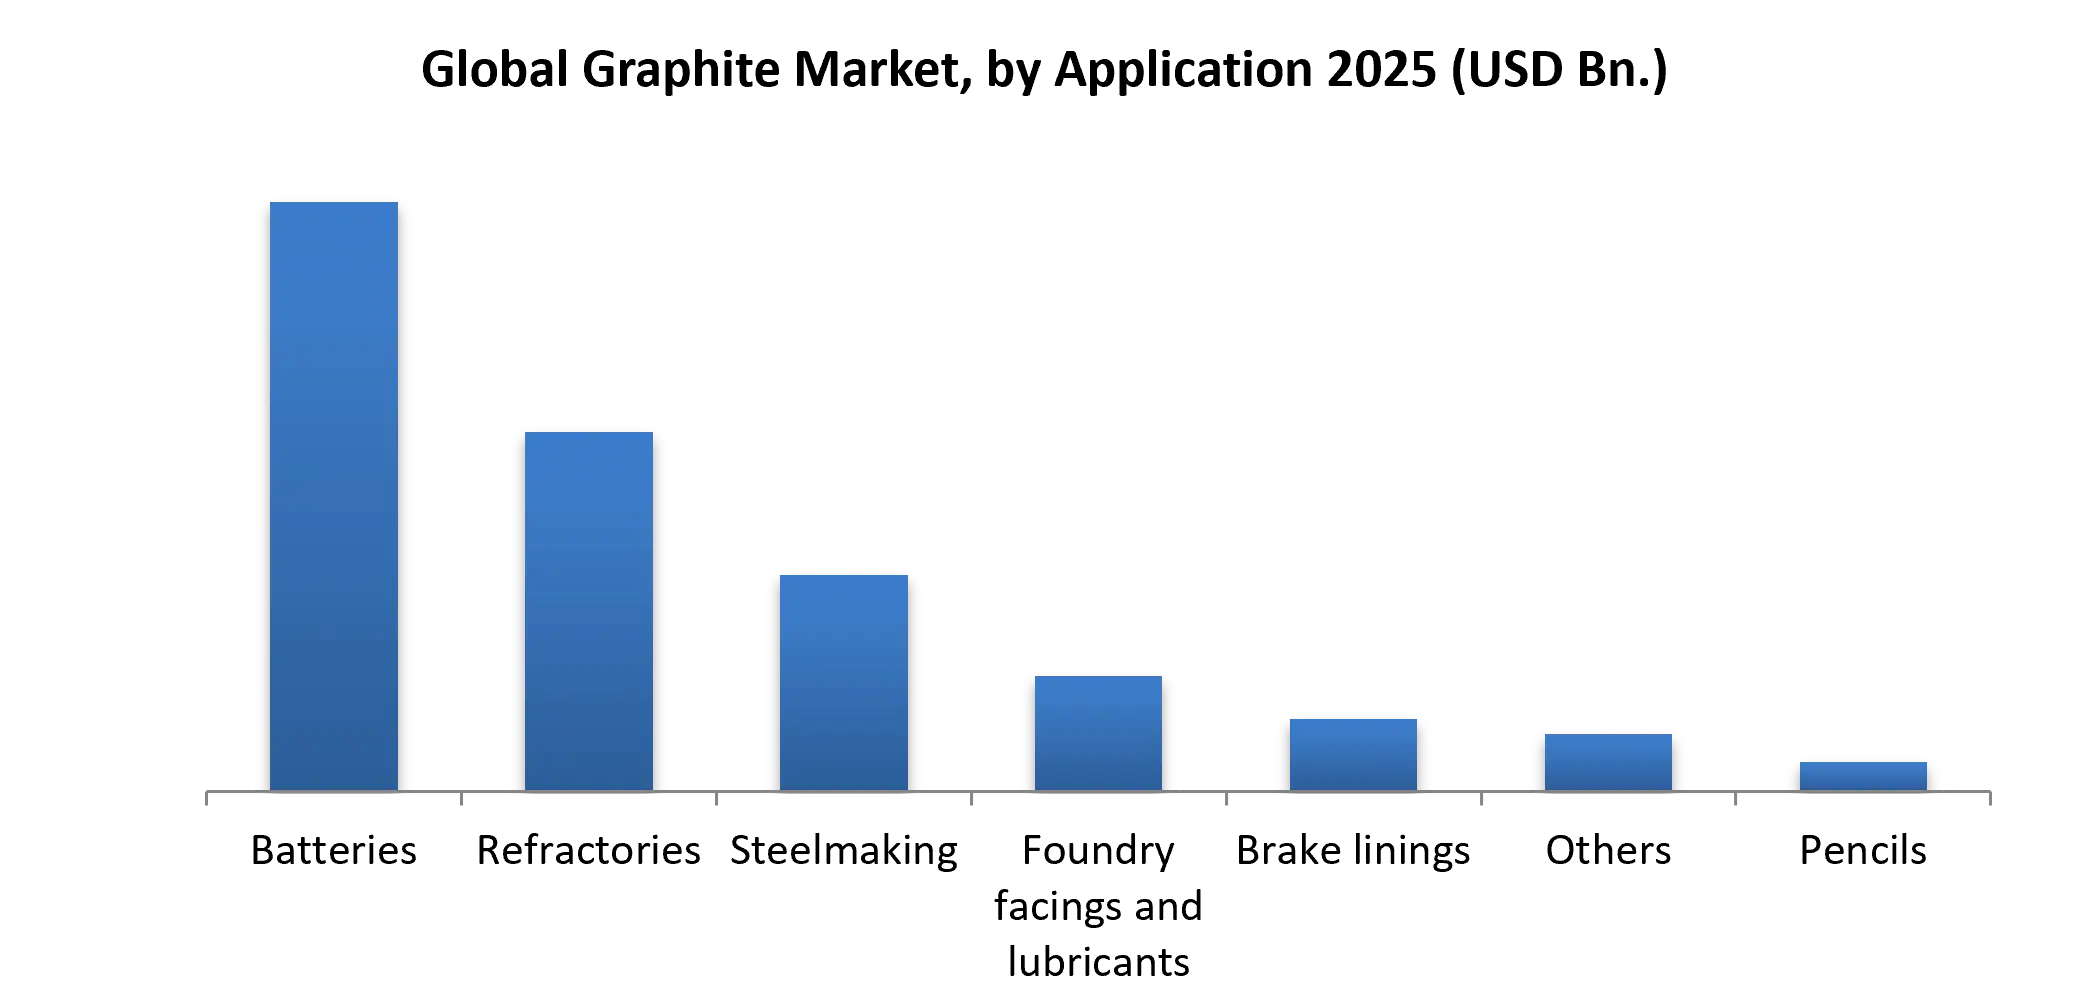
| Refractories Lead Graphite Market Applications | Refractories represent the leading application segment, accounting for more than 50% of market revenue in 2025, according to the provided report. Demand from high-temperature furnaces, steel production, foundries, and other industrial operations supports graphite consumption, while battery-grade graphite gains importance in electric vehicle batteries and energy storage systems. |
| Battery Grade Graphite and Electric Vehicle Demand | Growing electric vehicle production, lithium-ion battery manufacturing, and renewable energy storage create opportunities for natural graphite, synthetic graphite, and high-purity battery anode materials. Graphite recycling, local processing capacity, and supply chain diversification are emerging as important graphite market growth trends. |
| Graphite Market Competition and Strategic Opportunities | Leading graphite companies, including BTR New Material Group, Syrah Resources, SGL Carbon, GrafTech International, Graphite India Limited, and Tokai Carbon, compete through production capacity, material quality, processing technology, and supply chain reliability. Investments in battery anode manufacturing, sustainable graphite processing, and advanced graphite materials are shaping long-term competitive positioning. |
Graphite Market Dynamics:
Revolution in Lithium-Ion Battery to Drive Graphite Market Growth
Batteries are going to be smaller, last longer, and supply more power in the future. Batteries that are lightweight, long-lasting, safe, and can be implanted without needing to be replaced frequently are used in electric cars, power tools, medical equipment, and portable electronic devices.
Lithium-ion and lithium iron phosphate batteries, both of which use graphite as an anode material, are the most advanced battery systems. These batteries account for approximately 25% of the global graphite demand. To power an electric vehicle, a Li-ion battery requires substantially more graphite than lithium, making high-quality battery anode materials scarce. Batteries power smartphones, electric cars, and 3D printers, as well as fuel cells that generate electricity through a chemical process.
Environmental Regulations and Graphite Processing Restrain Graphite Market Growth
The graphite market faces restraints due to the environmental impact of graphite mining, purification, and processing activities. Natural graphite extraction can generate dust, waste materials, and water pollution, while graphite purification and synthetic graphite production may require substantial energy and chemical inputs. Manufacturers must comply with increasingly stringent environmental standards, waste management requirements, and emissions control measures, increasing operational costs and complicating production processes. Furthermore, the availability of high-purity graphite suitable for lithium-ion battery anodes depends on advanced processing technologies and consistent raw material quality. These challenges can delay capacity expansion, limit the entry of smaller manufacturers, and affect the competitiveness of graphite producers. Therefore, environmental compliance costs and complex graphite processing requirements may restrain graphite market growth over the forecast period.
Surging Industrial Applications to Create Graphite Market Opportunity
Markets for traditional graphite are also thriving. Graphite has long been in demand for a variety of applications, including pencils and refractory materials for furnaces, kilns, incinerators, and reactors, as well as flame deflector systems for rocket launch structures. Automobile parts, inks and coatings, paints, polymers and plastics, lubricants and grease, ceramics, drilling fluids, steel pipe and tubing, fire retardants, and oil spill response solutions all contain graphite. Thus, growing industrial applications are likely to drive the market growth over the forecast period.
Surging Prices of Graphite to Create Graphite Market Challenge
The surging prices of graphite are posing a significant challenge to the graphite market by increasing production costs for manufacturers and disrupting supply chains. Graphite, a key material used in batteries, refractories, and lubricants, is witnessing rising demand, particularly driven by the electric vehicle (EV) and renewable energy sectors. However, supply constraints due to limited mining capacity, geopolitical tensions, and stringent environmental regulations in major producing countries like China are tightening availability. As a result, higher raw material costs are putting pressure on downstream industries, potentially slowing the adoption of graphite-based technologies and reducing profit margins for producers. This price volatility creates uncertainty in the market, especially for smaller players with less financial flexibility.
Global Graphite Prices October 2024:
| Graphite Types | New Price | Previous Price | % Change |
| Graphite flake 94% C, +100 mesh, cif Europe, $/tonne | 1,420 | 1,380 | + 2.9 |
| Graphite amorphous 80% C, -200 mesh, fob China, $/tonne | 620-680 | 580-630 | + 8.3 |
| Graphite amorphous 80% C, -200 mesh, FCL, cif Europe, $/tonne | 750-820 | 720-800 | + 4.2 |
As a result of continued environmental inspections and consequent production plant closures, as well as considerable increases in transit costs from China as markets restored after COVID-19, prices for both flake and amorphous graphite climbed through Q4 2023 and Q1 2024. To avoid fines for failing to meet emissions standards, some businesses have voluntarily cut production. Thus, the surging price of graphite globally is expected to be a major barrier to the growth of the market over the forecast period.
Global Graphite Market Key Trends
| Market trend | Description |
| Rising Demand for Battery Grade Graphite | Battery manufacturers are placing greater emphasis on high-purity graphite that delivers consistent performance in lithium-ion battery anodes. Electric vehicles and stationary energy storage systems are strengthening demand for graphite materials with reliable charging performance and long service life. |
| Expansion of Graphite Supply Chains Outside China | Battery producers and industrial buyers are exploring graphite mining, purification, and anode manufacturing capacity outside China to reduce dependence on concentrated supply networks. New projects in North America and Europe are creating opportunities for regional graphite suppliers. |
| Growing Adoption of Synthetic Graphite in Advanced Applications | Synthetic graphite is attracting interest from battery and industrial manufacturers because its purity, particle structure, and performance can be controlled during production. Producers are focusing on process efficiency and consistent material quality to meet the requirements of advanced battery anodes and industrial electrodes. |
| Development of Low Carbon Graphite Manufacturing | Graphite producers are exploring renewable energy, cleaner processing methods, and alternative carbon feedstocks to reduce the environmental footprint of graphite production. Low carbon graphite is becoming an important area of development as battery manufacturers pay closer attention to material sourcing and production emissions. |
| Advancements in Graphite Recycling and Recovery | Battery recyclers and graphite manufacturers are investigating ways to recover, purify, and reuse graphite from spent lithium-ion batteries. Improved regeneration technologies could reduce reliance on newly mined materials and support circular battery material supply chains. |
| Increasing Focus on Natural Graphite Processing Technology | Graphite companies are improving purification, spherical shaping, and coating processes to convert natural flake graphite into battery-ready anode materials. These technologies help manufacturers meet battery quality requirements and create more value from mined graphite. |
Graphite Market Segment Analysis:
Based on Type, the graphite market is segmented into crystalline graphite, amorphous graphite, lump graphite, and highly ordered pyrolytic graphite.
In 2025, the amorphous graphite segment was dominant and held xx% of the overall market share in terms of revenue, as it is widely used in many industrial applications. Amorphous graphite is a mineral found in seams. It is found in a variety of lubrication products, including greases, forging lubricants, and so on. This type of graphite is an excellent alternative for situations where a higher ash content is acceptable or requested.
Based on Application, the graphite market is segmented as refractories, batteries, steel making, brake linings, foundry facings and lubricants, pencils, and others.
In 2025, the refractories segment was dominant and held more than 50% of the overall market share in terms of revenue. The segment’s growth can be related to the booming industrial operations and development, and the increased demand for graphite from industries such as aerospace, construction, automotive, and metal production.
 Graphite Market Regional Insights:
Asia Pacific is the leading region in graphite market, benefits established graphite mining, purification, synthetic graphite production, and battery anode manufacturing capabilities. China plays a central role in graphite processing and supplies materials to lithium-ion battery manufacturers, electric vehicle producers, steelmakers, and electronics companies. India is strengthening its position through domestic graphite resources, industrial development, and growing battery manufacturing demand, while Japan and South Korea contribute through advanced battery technologies and high-performance material processing. Strong demand from refractories, steelmaking, foundry applications, and energy storage continues to support Asia Pacific graphite market growth.
North America is strengthening its graphite market through investments in domestic mining, battery-grade graphite processing, and electric vehicle battery supply chains. The United States is encouraging local critical mineral production and advanced anode material manufacturing to reduce dependence on imported graphite, while Canada contributes through natural graphite resources and mining development. Demand from lithium-ion batteries, automotive manufacturing, steel production, industrial lubricants, and refractory applications supports regional market expansion. Opportunities are emerging for graphite suppliers that can deliver consistent battery-grade materials, improve processing efficiency, and establish reliable supply agreements with battery manufacturers.
Europe is advancing the graphite market through electric vehicle manufacturing, battery production, renewable energy storage, and efforts to strengthen critical raw material supply chains. Germany, France, the United Kingdom, and other industrial economies generate demand for battery-grade graphite, synthetic graphite, refractory materials, and specialty industrial products. Automotive electrification and stricter sustainability requirements are encouraging manufacturers to prioritize traceable raw materials, cleaner graphite processing, and recycling technologies. Investment in local anode production and battery material recovery creates opportunities for graphite suppliers seeking to serve European electric vehicle manufacturers and energy storage companies.
South America is developing its graphite market through mineral exploration, natural graphite production, and growing interest in critical mineral supply chains. Brazil offers opportunities through its mineral resources and established mining industry, while regional industrial development supports demand for graphite used in steelmaking, foundry operations, refractory products, and lubricants. The expansion of electric mobility and energy storage could create additional opportunities for graphite processing and battery material supply. Investment in mining infrastructure, mineral beneficiation, and export capabilities will influence the region's ability to participate more extensively in the graphite value chain.
Middle East and Africa is gaining attention in the graphite market through natural graphite mining projects, mineral resource development, and opportunities to diversify battery material supply. African countries such as Mozambique, Madagascar, and Tanzania contribute to natural graphite production and provide feedstock for industrial and battery applications. In the Middle East, industrial diversification, steel production, and emerging energy storage initiatives may support demand for graphite-based materials. Improvements in mining infrastructure, processing capacity, transportation networks, and investment conditions can create opportunities for regional producers to strengthen their position in graphite supply chains.
Global Graphite Market Competitive Landscape
The graphite market is characterized by strong competition among natural graphite miners, synthetic graphite manufacturers, battery anode material suppliers, and specialty graphite producers. Key companies such as BTR New Material Group, Syrah Resources, SGL Carbon, GrafTech International, Graphite India Limited, and Imerys compete through product quality, production capacity, advanced processing technologies, pricing, and supply chain reliability. Rising demand for electric vehicle batteries, energy storage systems, steelmaking electrodes, and high-performance industrial materials is encouraging manufacturers to strengthen research and development, improve graphite purification and processing, and expand battery-grade graphite production. Companies are also pursuing vertical integration, strategic partnerships, long-term supply agreements, and lower-emission manufacturing to improve their competitive position. Increasing investment in natural graphite mining, synthetic graphite innovation, battery anode technology, and graphite recycling creates new opportunities for established producers and emerging suppliers to strengthen their presence in the graphite market.
| Region | Country | Company | Market relevance and competitive advantage |
| Asia Pacific | China | BTR New Material Group | Major battery anode material supplier, with natural and synthetic graphite products serving lithium-ion battery manufacturers and electric vehicle supply chains. |
| Asia Pacific | China | Ningbo Shanshan | Competes in graphite anode materials and synthetic graphite, with established capabilities serving lithium-ion battery production. |
| Asia Pacific | Japan | Tokai Carbon | Supplies graphite electrodes and specialty carbon products for steelmaking and industrial applications, strengthening its position in high-performance graphite materials. |
| North America | United States | GrafTech International | Specializes in graphite electrodes used in electric arc furnace steelmaking, where product quality and electrode performance influence competitiveness. |
| North America | Canada | Northern Graphite | Develops natural graphite mining and downstream processing opportunities, supporting efforts to diversify graphite supply for industrial and battery applications. |
| Europe | Germany | SGL Carbon | Competes in specialty graphite, carbon-based materials, and engineered graphite solutions for industrial, automotive, and high-temperature applications. |
| Latin America | Brazil | Nacional de Grafite | Focuses on natural graphite mining, processing, and industrial graphite products for applications such as refractories, lubricants, and foundry materials. |
| Middle East and Africa | Mozambique | Syrah Resources | Operates natural graphite mining activities and develops downstream anode material capabilities, connecting African graphite resources with battery supply chains. |
Graphite Market Key Developments:
• Syrah Resources (Australia) started its expanded Balama graphite mine operations in Q1 2025, growing production capacity by 40% to meet the growing need for electric vehicle batteries. The new purification technological advances accomplished an anode-grade material purity of 99.95%.
• GrafTech International (USA) established its EcoGraphiteTM synthetic electrodes in March 2025, with 20% less energy consumption in the manufacturing of steel and 30% faster charging for lithium-ion batteries.
• BTR New Material (China) implemented its future coating technology in Q2 2025, which led to an increase of 15% in the density of spherical graphite anode and a $200/tonne decrease in processing costs.
• Talga Group (Sweden) To supply locally sourced graphite to Northvolt's gigafactories with a 60% lower carbon footprint, the business began commissioning Europe's first integrated anode facility in April 2025.
• SGL Carbon (Germany) Three important European automakers are currently using its RECARBON® recycled graphite line, which was introduced in 2024 and obtained 90% of battery-grade material from production scrap.
Global Graphite Market Recent Development
| Month/ Year | Company | Recent development |
| January 2026 | Graphite India Limited | Graphite India announced plans to invest in synthetic graphite anode materials for lithium ion batteries, marking a strategic move into battery materials manufacturing and diversification beyond its traditional graphite electrode business. |
| March 2026 | POSCO Future M | POSCO Future M announced a long term artificial graphite anode material supply agreement valued at approximately KRW 1 trillion and plans for a new manufacturing facility in Vietnam to expand production capacity and strengthen its battery material supply chain. |
| June 2026 | Graphite One | Graphite One secured an engineering contract for its planned Ohio anode materials facility, advancing development of domestic synthetic graphite production capacity for the North American battery market. |
| August 2026 | EcoGraf | EcoGraf announced that its German offtake partner agreed to increase graphite purchase volumes, strengthening its commercial relationships and supporting future development of its natural graphite supply operations. |
| September 2026 | Fortum and Talga Group | Fortum and Talga signed a memorandum of understanding to explore supplying recovered graphite from battery recycling operations for refining into battery anode materials, supporting recycled graphite integration and more sustainable battery supply chains. |
| October 2026 | SGL Carbon | SGL Carbon announced a capacity expansion at its St Marys site, reflecting continued investment in specialty graphite and carbon material manufacturing capabilities. |
Graphite Market Scope: Inquire before buying
| Graphite Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 8.04 USD Bn |
| Forecast Period 2026-2034 CAGR: | 7% | Market Size in 2034: | 14.78 USD Bn |
| Segments Covered: | by Type | Crystalline Graphite Amorphous Graphite Lump Graphite Highly Ordered Pyrolytic Graphite |
|
| by Form | Powder Graphite Granular Graphite Expandable Graphite Spherical Graphite Graphite Flakes Massive Graphite |
||
| by Product Type | Graphite Electrodes Carbon Fibers Graphene-based Materials Isotropic Graphite Extruded Graphite Molded Graphite |
||
| by Application | Refractories Batteries Steelmaking Brake linings Foundry facings and lubricants Pencils Others |
||
| by End User | Electronics Metallurgy Automotive Other End-user Industries |
||
Graphite Market, by Region
North America (United States, Canada, and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and the Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Colombia and the Rest of South America)
Graphite Market Key Players
1. SGL Carbon SE
2. GrafTech International Ltd.
3. Resonac Holdings Corporation
4. BTR New Material Group Co., Ltd.
5. Graphite India Limited
6. Tokai Carbon Co., Ltd.
7. Imerys S.A.
8. Syrah Resources Limited
9. Toyo Tanso Co., Ltd.
10. Mersen S.A.
11. Nippon Carbon Co., Ltd.
12. Zentek Ltd.
13. HEG Limited
14. Northern Graphite Corporation
15. Asbury Carbons
16. Nacional de Grafite
17. Talga Group
18. EcoGraf Limited
19. NOVONIX Limited
20. Mason Graphite Inc.
21. Triton Minerals Limited
22. Focus Graphite Inc.
23. NextSource Materials Inc.
24. Mitsubishi Chemical Group Corporation
25. Ningbo Shanshan Co., Ltd.
26. POSCO Future M Co., Ltd.
27. Anovion Technologies
28. Superior Graphite
29. Vianode
30. Fangda Carbon New Material Co., Ltd.
31. Graphit Kropfmühl GmbH
32. Epsilon Advanced Materials
33. Graphite One Inc.
34. Eagle Graphite Incorporated
35. China Carbon Graphite Group, Inc.
36. SEC CARBON, LIMITED
37. Jilin Carbon Co., Ltd.
38. Qingdao Epsilon Carbon Co., Ltd.
39. Huangshan Fenghua Graphite Co., Ltd.
40. Yankuang GuoAo Co., Ltd.
41. Shanghai Shanshan Technology Co., Ltd.
42. Shanghai PTL New Energy Technology Co., Ltd.
43. Dongguan Kaijin New Energy Technology Co., Ltd.
44. Hunan Zhongke Shinzoom Technology Co., Ltd.
45. Jiangxi Zichen Technology Co., Ltd. (Putailai)
46. Shijiazhuang Shangtai Technology Co., Ltd.
47. Himadri Speciality Chemical Ltd.
48. Graphinex Pty Ltd.
49. Idemitsu Kosan Co., Ltd.
50. Graphjet Technology Sdn. Bhd.
Frequently Asked Questions:
1. What are the key factors driving graphite market growth?
Answer: The graphite market is driven by rising electric vehicle production, increasing lithium ion battery demand, renewable energy storage, steel manufacturing, and growing demand for high performance industrial materials.
2. Which region dominates the graphite market?
Answer: Asia Pacific leads the graphite market due to its established graphite processing industry, battery anode manufacturing capacity, electric vehicle supply chains, and strong industrial demand.
3. Which application segment dominates the graphite market?
Answer: Refractories are a major graphite application because graphite supports high temperature performance in furnaces and metal processing, while battery applications gain importance with expanding electric vehicle and energy storage production.
4. Who are the key players in the graphite market?
Answer: Major graphite market companies include SGL Carbon, GrafTech International, BTR New Material Group, Graphite India Limited, Tokai Carbon, Imerys, Syrah Resources, HEG Limited, and Toyo Tanso.
5. What factors are restraining graphite market growth?
Answer: High graphite processing costs, environmental regulations, energy intensive purification, raw material price fluctuations, and supply chain concentration can restrict graphite market expansion.