Engineered Fluids Market Size by Application, End-users, Polymer Type, Region, Industry-Wide Analysis, Competitive Landscape Assessment & Long-Term Forecast to 2034

9%
CAGR (2026-2034)
1.54 USD Bn.
Forecast Market Size
324
Report Pages
136
Market Tables

Overview

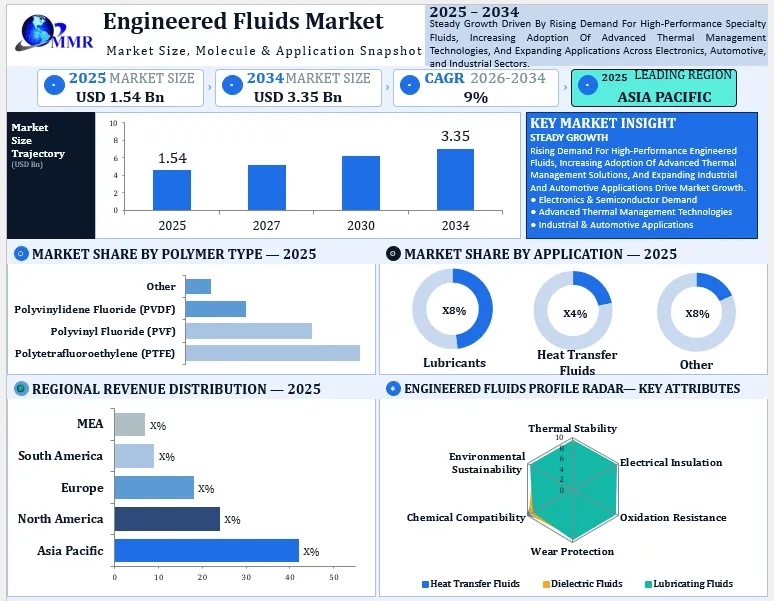
The Engineered Fluids Market size was valued at USD 1.54 Billion in 2025 and the total Engineered Fluids revenue is expected to grow at a CAGR of 9% from 2026 to 2034, reaching USD 3.35 Billion.

Engineered Fluids Market Overview:

Engineered Fluids have been used for a long time in extreme conditions due to their unique properties such as non-flammability, low and high temperature, stability, and non-toxicity. The engineered fluids, also known as fluorinated fluids, are versatile materials used in thermal management applications. Other properties of these fluids include chemical stability, non-toxicity, non-flammability, use at high and low temperatures, and excellent compatibility with a wide range of plastics, metals, and elastomers. Engineered fluids (fluorinated fluids) are specially designed to provide excellent lubricity while maintaining safety and reliability in a variety of advanced applications. This product is primarily used in automotive, electronics and semiconductors, oil and gas, aerospace, and power generation to reduce friction between machine parts. This aspect is expected to drive the growth of the Engineered Fluids Market.

The use of the product in a profitable application such as a heat transfer fluid, where there is a high demand for heat stability, purity, lubricity, and low toxicity, as well as the increasing demand due to the versatility and exceptional properties of these products, are the factors driving the Engineered Fluids Market. A surge in funding for manufacturing these products by governments of third-world economies, as well as increased awareness about environmental impact, is increasing their demand as they are known to be environmentally friendly, accelerating the market growth. The high use of these fluids in various industries such as semiconductor and electronics, chemical processing, aerospace, automotive, power, and energy generation, as well as their low global warming potential, may have an impact on the market. Moreover, the growth of end-use industries, an increase in R&D activities, and growing investment all have a positive impact on the market. Additionally, the high demand for heat exchangers and the replacement of petroleum-based lubricants with fluorinated lubricants create several profitable opportunities for Engineered Fluids Market players during the forecast period. On the other hand, the high cost of technology development and manufacturing of fluorinated fluids hamper the growth of the Engineered Fluids Market.

Engineered materials are versatile materials used in thermal management applications. Chemical stability, non-toxicity, non-flammability, use at high and low temperatures, and excellent compatibility with a wide range of plastics, metals, and elastomers are some of the properties of these fluids. Engineered fluids are used to reduce friction between machine parts in industries such as electronics and semiconductors, automotive, chemical processing, oil and gas, power generation, and aerospace. All the aspects are considered to boost the Engineered Fluids Market growth in the forecast period.

Global Engineered Fluids Market Growth Outlook
Engineered Fluids Market Growth

To know about the Research Methodology :- Request Free Sample Report

Engineered Fluids Market Dynamics:

Increased Aircraft Production Volume

Fluorinating fluids are used in aircraft as heat transfer fluids to reduce engine temperature, and fluorinated solvents are used to clean aircraft components such as valves and gaskets. Increased aircraft production in regions such as Europe and North America has boosted demand for fluorinated fluids. For example, in , Airbus increased the production rate of A320 Family aircraft from 43 in Q3 to 45 in Q4 at its production plants in France, Germany, and Toulouse. In addition, with 224 units produced in , Boeing was the leading manufacturer of wide-body planes, followed by Airbus with 147 units. As a result of such an increase in major aircraft manufacturers' production, the demand for fluorinated fluids and solvents used in them will also rise. This helps the Engineered Fluids Market grow.

Growing Demand for New Automotive Products for Engineered Fluids

Fluorinated fluids, such as polytetrafluoroethylene, have a wide range of applications in the automotive industry because they have low friction and prevent the formation of abrasion particles on parts. It is used as a fluorinated lubricant in automotive bushings, gears, and gaskets, and as a dielectric coolant in engines. The rise in purchasing power, rising living standards, and rapid urbanization have all contributed to an increase in demand for new automobiles. According to the Europe Automobile Manufacturer Association's November report, new passenger car registrations increased by 2.2% in the first ten months of , with increases shown in European Union markets such as Italy (12.7%), Spain (5.6%), and France (3.1%). The increased consumption of automobiles will have a positive impact on the use of fluorinated fluids in the automotive sector, such as dielectric fluid and lubricants. This will have a positive impact on the Engineered Fluids Market growth.

Engineered Fluids Market Restraints

Fluorinated fluids are engineered fluids that are created in specialized high-temperature, high-pressure reactors using a process designed specifically to create high-purity engineered compounds. The high cost of high-temperature reactors makes the entire manufacturing process very expensive, especially during dielectric coolants. The primary reason for preferring mineral oil to engineered fluids. This may have a negative impact on the Engineered Fluids Market growth.

Engineered Fluids Market Opportunity

The factors that aid in the market's growth include the superior and environmentally friendly qualities of engineered fluids. Increased thermal management issues in the electronics & semiconductors, automotive, and aerospace industries are some of the factors driving the market. Because of these characteristics, fluorinated can operate under harsh conditions like high pressure, an oxidation-prone environment, and high operating temperatures. However, this market is constrained by the high cost of technological development and manufactured fluids.

The increasing application of engineered fluids in several end-use industries is one of the factors anticipated to boost the Engineered Fluids Market. It is primarily because of these fluids' exceptional characteristics. Chemical stability, non-toxicity, and excellent compatibility with a wide range of metals, plastics, and elastomers are a few of the prominent characteristics of engineered fluids. Engineered fluids are used in machine parts to reduce friction. Electronics cooling, heating chambers, cleaning, and wafer handling are some of the most common applications for engineered fluids. Engineered fluids' numerous applications will drive the Engineered Fluids Market. Aside from that, engineered fluids help to reduce global warming potential while having no negative environmental impact. This will boost the Engineered Fluids Market shortly.

Engineered Fluids Market Segment Analysis:

Based on Application, The Lubricants segment dominated the Engineered Fluids Market in 2025 and is expected to do so during the forecast period. Engineered fluids are also utilized in a wide range of applications, including vacuum pump fluids, mechanical sealants, metering fluids, and compressor fluids. They are more stable than petroleum-based lubricants because they do not crack, discolor, react, or dissolve, and they can withstand a wide temperature range of roughly -120°C to 300°C. Since they are non-flammable, resistant to harsh chemicals and fuels, and have low volatility, fluoride-based lubricants are frequently chosen for high-vacuum applications. The market for engineered fluids is expected to be driven during the forecast period by the growing demand from a variety of industries, including chemical, electrical, manufacturing, and oil & gas.

Engineered fluids are frequently used as lubricants because of their thermal stability, and their market is expected to grow quickly during the forecast period. Engineered fluids are fluorinated fluids, such as polytetrafluoroethylene, perfluoropropyl ether, perfluoropolyether, etc. They are frequently used as lubricants due to their excellent operational performance, non-reactivity, non-toxic nature, and ability to withstand a wide range of temperatures, from cryogenics to higher ambient temperatures.

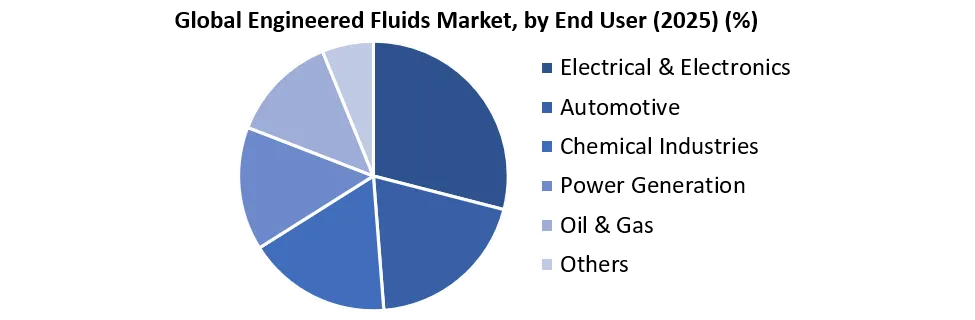
Based on the End-users, The electrical and electronics segment, which has a high temperature and long-lasting lubrication, dominated the engineered fluids market in 2025. The product is primarily used in semiconductors for the benefit of wafer handling and for electronic cooling, heating, testing, process chambers, and connector lubrication. Fluorinated lubricants' ability to carry loads at high temperatures in semiconductors allows them to endure in hostile environments, which is anticipated to fuel the growth of the market during the study period. During the forecast period, the increasing demand for oil and grease for vacuum pumps in semiconductors is expected to drive product demand. During the forecast period, market participants are expected to benefit from innovation and development aimed at lowering the cost of manufacturing technology and replacing traditional lubricants. However, the market's manufacturing technology is more expensive than traditional oil and grease technologies, which is expected to limit market growth during the forecast years.Engineered Fluids Market by Enduser
Engineered Fluids Market Regional Insights:

The Asia-Pacific region dominated the Engineered Fluids Market, thanks to increasing demand from countries like India and China. Engineered fluids are used as heat transfer fluids in a variety of applications, including chemical industries, high-performance machines, power generation, and electrical applications such as semiconductors, electronic devices, and servers. The market is expected to be driven by increased competition in the development of artificial intelligence, supercomputers, and the use of electronics.

India is the world's leading manufacturer of generic drugs, supplying roughly half of the total demand and with an export value of approximately USD 19.14 billion in the fiscal year 2019. Globally, India is the third-largest consumer of crude oil and petroleum products, trailing only China and the United States, and it has Asia's second-largest refinery, trailing only China.

North America: North America holds a significant position in the Engineered Fluids Market, supported by advanced aerospace, automotive, electronics, and industrial manufacturing sectors. The United States is a major contributor, driven by investments in semiconductor production, data center infrastructure, electric vehicles, and high-performance cooling technologies. The region's focus on technological innovation and equipment efficiency also supports demand for specialized engineered fluids.

Europe: Europe represents an important market, driven by its established automotive, chemical processing, aerospace, and industrial manufacturing industries. Germany, France, the United Kingdom, and Italy contribute to regional demand through advanced engineering capabilities and investments in electric mobility, industrial automation, and energy-efficient technologies. Increasing emphasis on environmental standards and sustainable fluid formulations also influences product development.

South America: South America offers growth opportunities as industrial production, automotive manufacturing, mining, and energy-related activities create demand for specialized fluid solutions. Brazil, Argentina, and Chile are important markets, supported by industrial development and demand for lubricating, cooling, and heat-transfer fluids. Improvements in manufacturing infrastructure and investment in industrial technologies may further support market expansion.

Middle East & Africa: The Middle East & Africa region is supported by demand from oil and gas, petrochemicals, energy, mining, and industrial processing sectors. Saudi Arabia, the United Arab Emirates, and South Africa are important markets due to investments in industrial infrastructure and energy projects. Growing data center capacity and increasing demand for efficient thermal management solutions may create additional opportunities for engineered fluid suppliers.

Engineered Fluids Market – Competitive Landscape

The global Engineered Fluids Market is competitive and partially fragmented, with established chemical manufacturers and specialized fluid producers competing through product innovation, performance improvement, application-specific formulations, and global distribution networks. Key players include 3M, Daikin Industries, Solvay, The Chemours Company, AGC Chemicals, Halocarbon, and Engineered Fluids, Inc.

Leading companies focus on developing high-performance fluorinated fluids, specialty lubricants, dielectric fluids, and heat-transfer solutions for electronics, automotive, aerospace, and industrial applications. Technological expertise, product quality, regulatory compliance, and customer-specific solutions are important competitive factors.
Companies are also responding to changing environmental requirements and demand for efficient thermal management, particularly in electronics and data center cooling. Strategic partnerships, research and development, portfolio expansion, and development of alternative fluid formulations are important approaches for strengthening market presence.

Key Companies: 3M Company, Daikin Industries Ltd., Solvay S.A., The Chemours Company, AGC Chemicals Americas, Halocarbon LLC, HaloPolymer, F2 Chemicals Ltd., IKV Tribology Ltd., Lubrilog, Nye Lubricants Inc., and Engineered Fluids Inc.

Engineered Fluids Market Recent Development:

Date Company Development Impact
15 January 2026 Infinium Launched Infinium Edge, featuring custom-engineered dielectric immersion fluids for AI and high-performance computing data centers. The launch strengthens demand for specialized dielectric fluids designed for efficient thermal management in high-density computing environments.
27 January 2026 PFX Group Announced the showcasing of its SOLUTHERM™ heat-transfer fluid portfolio for HVAC systems and data center cooling at the 2026 AHR Expo. The portfolio highlights opportunities for advanced heat-transfer fluids that improve thermal performance, equipment protection, and operational efficiency.
18 May 2026 Dow Inc. and ChemTreat, Inc. ChemTreat joined Dow's Coolant Care Network as a strategic national service provider for AI data center cooling. The collaboration expands coolant testing, fluid optimization, and heat-transfer fluid support for data center cooling infrastructure.
22 June 2026 Standard Fluids Corporation Formalized a strategic partnership with Firetrace International to advance high-performance fire-protection fluids and solutions for critical industries. The partnership creates opportunities for specialty fluorinated fluids across industrial, electrical, clean-energy, and data center applications.

Engineered Fluids Market Scope: Inquire before buying

Engineered Fluids Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 1.54 Bn.
Forecast Period 2026 to 2034 CAGR: 9% Market Size in 2034: USD 3.35 Bn.
Segments Covered: by Application Lubricants
Heat Transfer Fluids
Others
by End-users Electrical & Electronics
Automotive
Chemical Industries
Power Generation
Oil & Gas
Others
by Polymer Type Polytetrafluoroethylene (PTFE)
Polyvinyl Fluoride (PVF)
Polyvinylidene Fluoride (PVDF)
Other

Engineered Fluids Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)

Engineered Fluids Market, Key Players are:

1. ExxonMobil Corporation
2. Shell plc
3. TotalEnergies SE
4. BP plc
5. BASF SE
6. Dow Inc.
7. Honeywell International Inc.
8. Daikin Industries, Ltd.
9. Shin-Etsu Chemical Co., Ltd.
10. Syensqo SA
11. Arkema Group
12. Wacker Chemie AG
13. Huntsman Corporation
14. The Chemours Company
15. The Lubrizol Corporation
16. Kuraray Co., Ltd.
17. Clariant AG
18. Momentive Performance Materials Inc.
19. Croda International Plc
20. Quaker Houghton
21. Halocarbon, LLC
22. Nye Lubricants, Inc.
23. AGC Inc.
24. Interflon BV
25. Engineered Fluids, Inc.
26. F2 Chemicals Ltd.
27. Chemtool Incorporated
28. Perstorp Holding AB
29. Cargill, Incorporated
30. Eastman Chemical Company
31. DuPont de Nemours, Inc.
32. Chevron Corporation
33. FUCHS SE
34. Idemitsu Kosan Co., Ltd.
35. ENEOS Corporation
36. PetroChina Company Limited
37. China Petroleum & Chemical Corporation (Sinopec)
38. PETRONAS Lubricants International
39. M&I Materials Ltd.
40. HaloPolymer OJSC

Frequently Asked Questions:

1] What are fluorinated fluids?
Ans. Fluorinated heat transfer fluids are fluorinated GHGs used in certain types of electronics manufacturing production processes for temperature control, device testing, cleaning substrate surfaces and other parts, and soldering.

2] What is Halocarbon oil used for?
Ans. As a medium viscosity inert oil manufactured within the industry standard viscosity range of 10%, Halocarbon 27 is the ideal fluorinated oil for general-purpose inert lubrication for applications such as bearings, compressors, gearboxes, and pumps.

3] What is fluorinert used for?
Ans. 3MTM FluorinertTM Electronic Liquids are heat transfer and immersion cooling dielectric fluids. Thermal management applications include semiconductor wafer manufacturing, electronics reliability testing, data center server immersion cooling, and a wide range of other high-tech applications.

4] What was the Global Engineered Fluids Market size in 2025?
Ans:
The Global Engineered Fluids Market size was USD 1.54 Billion in 2025.

5] What segments are covered in the Global Engineered Fluids Market report?
Ans. The segments covered in the Engineered Fluids Market report are based on Application and End Users.

Table of Contents

1. Engineered Fluids Market Introduction 1.1. Study Assumption and Market Definition 1.2. Scope of the Study 1.3. Executive Summary 2. Global Engineered Fluids Market: Competitive Landscape 2.1. MMR Competition Matrix 2.2. Competitive Landscape 2.3. Key Players Benchmarking 2.3.1. Company Name 2.3.2. Business Segment 2.3.3. End-user Segment 2.3.4. Revenue (2025) 2.3.5. Company Locations 2.4. Leading Engineered Fluids Market Companies, by market capitalization 2.5. Market Structure 2.5.1. Market Leaders 2.5.2. Market Followers 2.5.3. Emerging Players 2.6. Mergers and Acquisitions Details 3. Engineered Fluids Market: Dynamics 3.1. Engineered Fluids Market Trends by Region 3.1.1. North America Engineered Fluids Market Trends 3.1.2. Europe Engineered Fluids Market Trends 3.1.3. Asia Pacific Engineered Fluids Market Trends 3.1.4. Middle East and Africa Engineered Fluids Market Trends 3.1.5. South America Engineered Fluids Market Trends 3.2. Engineered Fluids Market Dynamics by Region 3.2.1. North America 3.2.1.1. North America Engineered Fluids Market Drivers 3.2.1.2. North America Engineered Fluids Market Restraints 3.2.1.3. North America Engineered Fluids Market Opportunities 3.2.1.4. North America Engineered Fluids Market Challenges 3.2.2. Europe 3.2.2.1. Europe Engineered Fluids Market Drivers 3.2.2.2. Europe Engineered Fluids Market Restraints 3.2.2.3. Europe Engineered Fluids Market Opportunities 3.2.2.4. Europe Engineered Fluids Market Challenges 3.2.3. Asia Pacific 3.2.3.1. Asia Pacific Engineered Fluids Market Drivers 3.2.3.2. Asia Pacific Engineered Fluids Market Restraints 3.2.3.3. Asia Pacific Engineered Fluids Market Opportunities 3.2.3.4. Asia Pacific Engineered Fluids Market Challenges 3.2.4. Middle East and Africa 3.2.4.1. Middle East and Africa Engineered Fluids Market Drivers 3.2.4.2. Middle East and Africa Engineered Fluids Market Restraints 3.2.4.3. Middle East and Africa Engineered Fluids Market Opportunities 3.2.4.4. Middle East and Africa Engineered Fluids Market Challenges 3.2.5. South America 3.2.5.1. South America Engineered Fluids Market Drivers 3.2.5.2. South America Engineered Fluids Market Restraints 3.2.5.3. South America Engineered Fluids Market Opportunities 3.2.5.4. South America Engineered Fluids Market Challenges 3.3. PORTER's Five Forces Analysis 3.4. PESTLE Analysis 3.5. Technology Roadmap 3.6. Regulatory Landscape by Region 3.6.1. North America 3.6.2. Europe 3.6.3. Asia Pacific 3.6.4. Middle East and Africa 3.6.5. South America 3.7. Key Opinion Leader Analysis in the Engineered Fluids Market 3.8. Analysis of Government Schemes and Initiatives For Global Industry 3.9. Engineered Fluids Market Trade Analysis 3.10. The Global Pandemic Impact on Engineered Fluids Market 4. Engineered Fluids Market: Global Market Size and Forecast by Segmentation (in USD Million) 2025-2034 4.1. Engineered Fluids Market Size and Forecast, by Application (2025-2034) 4.1.1. Lubricants 4.1.2. Heat Transfer Fluids 4.1.3. Others 4.2. Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 4.2.1. Electrical & Electronics 4.2.2. Automotive 4.2.3. Chemical Industries 4.2.4. Power Generation 4.2.5. Oil & Gas 4.2.6. Others 4.3. Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 4.3.1. Polytetrafluoroethylene (PTFE) 4.3.2. Polyvinyl Fluoride (PVF) 4.3.3. Polyvinylidene Fluoride (PVDF) 4.3.4. Other 4.4. Engineered Fluids Market Size and Forecast, by Region (2025-2034) 4.4.1. North America 4.4.2. Europe 4.4.3. Asia Pacific 4.4.4. Middle East and Africa 4.4.5. South America 5. North America Engineered Fluids Market Size and Forecast by Segmentation (in USD Million) 2025-2034 5.1. North America Engineered Fluids Market Size and Forecast, by Application (2025-2034) 5.1.1. Lubricants 5.1.2. Heat Transfer Fluids 5.1.3. Others 5.2. North America Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 5.2.1. Electrical & Electronics 5.2.2. Automotive 5.2.3. Chemical Industries 5.2.4. Power Generation 5.2.5. Oil & Gas 5.2.6. Others 5.3. North America Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 5.3.1. Polytetrafluoroethylene (PTFE) 5.3.2. Polyvinyl Fluoride (PVF) 5.3.3. Polyvinylidene Fluoride (PVDF) 5.3.4. Other 5.4. North America Engineered Fluids Market Size and Forecast, by Country (2025-2034) 5.4.1. United States 5.4.1.1. United States Engineered Fluids Market Size and Forecast, by Application (2025-2034) 5.4.1.1.1. Lubricants 5.4.1.1.2. Heat Transfer Fluids 5.4.1.1.3. Others 5.4.1.2. United States Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 5.4.1.2.1. Electrical & Electronics 5.4.1.2.2. Automotive 5.4.1.2.3. Chemical Industries 5.4.1.2.4. Power Generation 5.4.1.2.5. Oil & Gas 5.4.1.2.6. Others 5.4.1.3. United States Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 5.4.1.3.1. Polytetrafluoroethylene (PTFE) 5.4.1.3.2. Polyvinyl Fluoride (PVF) 5.4.1.3.3. Polyvinylidene Fluoride (PVDF) 5.4.1.3.4. Other 5.4.2. Canada 5.4.2.1. Canada Engineered Fluids Market Size and Forecast, by Application (2025-2034) 5.4.2.1.1. Lubricants 5.4.2.1.2. Heat Transfer Fluids 5.4.2.1.3. Others 5.4.2.2. Canada Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 5.4.2.2.1. Electrical & Electronics 5.4.2.2.2. Automotive 5.4.2.2.3. Chemical Industries 5.4.2.2.4. Power Generation 5.4.2.2.5. Oil & Gas 5.4.2.2.6. Others 5.4.2.3. Canada Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 5.4.2.3.1. Polytetrafluoroethylene (PTFE) 5.4.2.3.2. Polyvinyl Fluoride (PVF) 5.4.2.3.3. Polyvinylidene Fluoride (PVDF) 5.4.2.3.4. Other 5.4.3. Mexico 5.4.3.1. Mexico Engineered Fluids Market Size and Forecast, by Application (2025-2034) 5.4.3.1.1. Lubricants 5.4.3.1.2. Heat Transfer Fluids 5.4.3.1.3. Others 5.4.3.2. Mexico Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 5.4.3.2.1. Electrical & Electronics 5.4.3.2.2. Automotive 5.4.3.2.3. Chemical Industries 5.4.3.2.4. Power Generation 5.4.3.2.5. Oil & Gas 5.4.3.2.6. Others 5.4.3.3. Mexico Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 5.4.3.3.1. Polytetrafluoroethylene (PTFE) 5.4.3.3.2. Polyvinyl Fluoride (PVF) 5.4.3.3.3. Polyvinylidene Fluoride (PVDF) 5.4.3.3.4. Other 6. Europe Engineered Fluids Market Size and Forecast by Segmentation (in USD Million) 2025-2034 6.1. Europe Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.1.1. Lubricants 6.1.2. Heat Transfer Fluids 6.1.3. Others 6.2. Europe Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.2.1. Electrical & Electronics 6.2.2. Automotive 6.2.3. Chemical Industries 6.2.4. Power Generation 6.2.5. Oil & Gas 6.2.6. Others 6.3. Europe Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.3.1. Polytetrafluoroethylene (PTFE) 6.3.2. Polyvinyl Fluoride (PVF) 6.3.3. Polyvinylidene Fluoride (PVDF) 6.3.4. Other 6.4. Europe Engineered Fluids Market Size and Forecast, by Country (2025-2034) 6.4.1. United Kingdom 6.4.1.1. United Kingdom Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.1.1.1. Lubricants 6.4.1.1.2. Heat Transfer Fluids 6.4.1.1.3. Others 6.4.1.2. United Kingdom Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.1.2.1. Electrical & Electronics 6.4.1.2.2. Automotive 6.4.1.2.3. Chemical Industries 6.4.1.2.4. Power Generation 6.4.1.2.5. Oil & Gas 6.4.1.2.6. Others 6.4.1.3. United Kingdom Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.1.3.1. Polytetrafluoroethylene (PTFE) 6.4.1.3.2. Polyvinyl Fluoride (PVF) 6.4.1.3.3. Polyvinylidene Fluoride (PVDF) 6.4.1.3.4. Other 6.4.2. France 6.4.2.1. France Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.2.1.1. Lubricants 6.4.2.1.2. Heat Transfer Fluids 6.4.2.1.3. Others 6.4.2.2. France Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.2.2.1. Electrical & Electronics 6.4.2.2.2. Automotive 6.4.2.2.3. Chemical Industries 6.4.2.2.4. Power Generation 6.4.2.2.5. Oil & Gas 6.4.2.2.6. Others 6.4.2.3. France Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.2.3.1. Polytetrafluoroethylene (PTFE) 6.4.2.3.2. Polyvinyl Fluoride (PVF) 6.4.2.3.3. Polyvinylidene Fluoride (PVDF) 6.4.2.3.4. Other 6.4.3. Germany 6.4.3.1. Germany Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.3.1.1. Lubricants 6.4.3.1.2. Heat Transfer Fluids 6.4.3.1.3. Others 6.4.3.2. Germany Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.3.2.1. Electrical & Electronics 6.4.3.2.2. Automotive 6.4.3.2.3. Chemical Industries 6.4.3.2.4. Power Generation 6.4.3.2.5. Oil & Gas 6.4.3.2.6. Others 6.4.3.3. Germany Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.3.3.1. Polytetrafluoroethylene (PTFE) 6.4.3.3.2. Polyvinyl Fluoride (PVF) 6.4.3.3.3. Polyvinylidene Fluoride (PVDF) 6.4.3.3.4. Other 6.4.4. Italy 6.4.4.1. Italy Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.4.1.1. Lubricants 6.4.4.1.2. Heat Transfer Fluids 6.4.4.1.3. Others 6.4.4.2. Italy Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.4.2.1. Electrical & Electronics 6.4.4.2.2. Automotive 6.4.4.2.3. Chemical Industries 6.4.4.2.4. Power Generation 6.4.4.2.5. Oil & Gas 6.4.4.2.6. Others 6.4.4.3. Italy Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.4.3.1. Polytetrafluoroethylene (PTFE) 6.4.4.3.2. Polyvinyl Fluoride (PVF) 6.4.4.3.3. Polyvinylidene Fluoride (PVDF) 6.4.4.3.4. Other 6.4.5. Spain 6.4.5.1. Spain Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.5.1.1. Lubricants 6.4.5.1.2. Heat Transfer Fluids 6.4.5.1.3. Others 6.4.5.2. Spain Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.5.2.1. Electrical & Electronics 6.4.5.2.2. Automotive 6.4.5.2.3. Chemical Industries 6.4.5.2.4. Power Generation 6.4.5.2.5. Oil & Gas 6.4.5.2.6. Others 6.4.5.3. Spain Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.5.3.1. Polytetrafluoroethylene (PTFE) 6.4.5.3.2. Polyvinyl Fluoride (PVF) 6.4.5.3.3. Polyvinylidene Fluoride (PVDF) 6.4.5.3.4. Other 6.4.6. Sweden 6.4.6.1. Sweden Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.6.1.1. Lubricants 6.4.6.1.2. Heat Transfer Fluids 6.4.6.1.3. Others 6.4.6.2. Sweden Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.6.2.1. Electrical & Electronics 6.4.6.2.2. Automotive 6.4.6.2.3. Chemical Industries 6.4.6.2.4. Power Generation 6.4.6.2.5. Oil & Gas 6.4.6.2.6. Others 6.4.6.3. Sweden Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.6.3.1. Polytetrafluoroethylene (PTFE) 6.4.6.3.2. Polyvinyl Fluoride (PVF) 6.4.6.3.3. Polyvinylidene Fluoride (PVDF) 6.4.6.3.4. Other 6.4.7. Austria 6.4.7.1. Austria Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.7.1.1. Lubricants 6.4.7.1.2. Heat Transfer Fluids 6.4.7.1.3. Others 6.4.7.2. Austria Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.7.2.1. Electrical & Electronics 6.4.7.2.2. Automotive 6.4.7.2.3. Chemical Industries 6.4.7.2.4. Power Generation 6.4.7.2.5. Oil & Gas 6.4.7.2.6. Others 6.4.7.3. Austria Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.7.3.1. Polytetrafluoroethylene (PTFE) 6.4.7.3.2. Polyvinyl Fluoride (PVF) 6.4.7.3.3. Polyvinylidene Fluoride (PVDF) 6.4.7.3.4. Other 6.4.8. Rest of Europe 6.4.8.1. Rest of Europe Engineered Fluids Market Size and Forecast, by Application (2025-2034) 6.4.8.1.1. Lubricants 6.4.8.1.2. Heat Transfer Fluids 6.4.8.1.3. Others 6.4.8.2. Rest of Europe Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 6.4.8.2.1. Electrical & Electronics 6.4.8.2.2. Automotive 6.4.8.2.3. Chemical Industries 6.4.8.2.4. Power Generation 6.4.8.2.5. Oil & Gas 6.4.8.2.6. Others 6.4.8.3. Rest of Europe Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 6.4.8.3.1. Polytetrafluoroethylene (PTFE) 6.4.8.3.2. Polyvinyl Fluoride (PVF) 6.4.8.3.3. Polyvinylidene Fluoride (PVDF) 6.4.8.3.4. Other 7. Asia Pacific Engineered Fluids Market Size and Forecast by Segmentation (in USD Million) 2025-2034 7.1. Asia Pacific Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.1.1. Lubricants 7.1.2. Heat Transfer Fluids 7.1.3. Others 7.2. Asia Pacific Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.2.1. Electrical & Electronics 7.2.2. Automotive 7.2.3. Chemical Industries 7.2.4. Power Generation 7.2.5. Oil & Gas 7.2.6. Others 7.3. Asia Pacific Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.3.1. Polytetrafluoroethylene (PTFE) 7.3.2. Polyvinyl Fluoride (PVF) 7.3.3. Polyvinylidene Fluoride (PVDF) 7.3.4. Other 7.4. Asia Pacific Engineered Fluids Market Size and Forecast, by Country (2025-2034) 7.4.1. China 7.4.1.1. China Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.1.1.1. Lubricants 7.4.1.1.2. Heat Transfer Fluids 7.4.1.1.3. Others 7.4.1.2. China Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.1.2.1. Electrical & Electronics 7.4.1.2.2. Automotive 7.4.1.2.3. Chemical Industries 7.4.1.2.4. Power Generation 7.4.1.2.5. Oil & Gas 7.4.1.2.6. Others 7.4.1.3. China Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.1.3.1. Polytetrafluoroethylene (PTFE) 7.4.1.3.2. Polyvinyl Fluoride (PVF) 7.4.1.3.3. Polyvinylidene Fluoride (PVDF) 7.4.1.3.4. Other 7.4.2. S Korea 7.4.2.1. S Korea Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.2.1.1. Lubricants 7.4.2.1.2. Heat Transfer Fluids 7.4.2.1.3. Others 7.4.2.2. S Korea Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.2.2.1. Electrical & Electronics 7.4.2.2.2. Automotive 7.4.2.2.3. Chemical Industries 7.4.2.2.4. Power Generation 7.4.2.2.5. Oil & Gas 7.4.2.2.6. Others 7.4.2.3. S Korea Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.2.3.1. Polytetrafluoroethylene (PTFE) 7.4.2.3.2. Polyvinyl Fluoride (PVF) 7.4.2.3.3. Polyvinylidene Fluoride (PVDF) 7.4.2.3.4. Other 7.4.3. Japan 7.4.3.1. Japan Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.3.1.1. Lubricants 7.4.3.1.2. Heat Transfer Fluids 7.4.3.1.3. Others 7.4.3.2. Japan Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.3.2.1. Electrical & Electronics 7.4.3.2.2. Automotive 7.4.3.2.3. Chemical Industries 7.4.3.2.4. Power Generation 7.4.3.2.5. Oil & Gas 7.4.3.2.6. Others 7.4.3.3. Japan Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.3.3.1. Polytetrafluoroethylene (PTFE) 7.4.3.3.2. Polyvinyl Fluoride (PVF) 7.4.3.3.3. Polyvinylidene Fluoride (PVDF) 7.4.3.3.4. Other 7.4.4. India 7.4.4.1. India Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.4.1.1. Lubricants 7.4.4.1.2. Heat Transfer Fluids 7.4.4.1.3. Others 7.4.4.2. India Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.4.2.1. Electrical & Electronics 7.4.4.2.2. Automotive 7.4.4.2.3. Chemical Industries 7.4.4.2.4. Power Generation 7.4.4.2.5. Oil & Gas 7.4.4.2.6. Others 7.4.4.3. India Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.4.3.1. Polytetrafluoroethylene (PTFE) 7.4.4.3.2. Polyvinyl Fluoride (PVF) 7.4.4.3.3. Polyvinylidene Fluoride (PVDF) 7.4.4.3.4. Other 7.4.5. Australia 7.4.5.1. Australia Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.5.1.1. Lubricants 7.4.5.1.2. Heat Transfer Fluids 7.4.5.1.3. Others 7.4.5.2. Australia Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.5.2.1. Electrical & Electronics 7.4.5.2.2. Automotive 7.4.5.2.3. Chemical Industries 7.4.5.2.4. Power Generation 7.4.5.2.5. Oil & Gas 7.4.5.2.6. Others 7.4.5.3. Australia Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.5.3.1. Polytetrafluoroethylene (PTFE) 7.4.5.3.2. Polyvinyl Fluoride (PVF) 7.4.5.3.3. Polyvinylidene Fluoride (PVDF) 7.4.5.3.4. Other 7.4.6. Indonesia 7.4.6.1. Indonesia Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.6.1.1. Lubricants 7.4.6.1.2. Heat Transfer Fluids 7.4.6.1.3. Others 7.4.6.2. Indonesia Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.6.2.1. Electrical & Electronics 7.4.6.2.2. Automotive 7.4.6.2.3. Chemical Industries 7.4.6.2.4. Power Generation 7.4.6.2.5. Oil & Gas 7.4.6.2.6. Others 7.4.6.3. Indonesia Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.6.3.1. Polytetrafluoroethylene (PTFE) 7.4.6.3.2. Polyvinyl Fluoride (PVF) 7.4.6.3.3. Polyvinylidene Fluoride (PVDF) 7.4.6.3.4. Other 7.4.7. Malaysia 7.4.7.1. Malaysia Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.7.1.1. Lubricants 7.4.7.1.2. Heat Transfer Fluids 7.4.7.1.3. Others 7.4.7.2. Malaysia Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.7.2.1. Electrical & Electronics 7.4.7.2.2. Automotive 7.4.7.2.3. Chemical Industries 7.4.7.2.4. Power Generation 7.4.7.2.5. Oil & Gas 7.4.7.2.6. Others 7.4.7.3. Malaysia Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.7.3.1. Polytetrafluoroethylene (PTFE) 7.4.7.3.2. Polyvinyl Fluoride (PVF) 7.4.7.3.3. Polyvinylidene Fluoride (PVDF) 7.4.7.3.4. Other 7.4.8. Vietnam 7.4.8.1. Vietnam Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.8.1.1. Lubricants 7.4.8.1.2. Heat Transfer Fluids 7.4.8.1.3. Others 7.4.8.2. Vietnam Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.8.2.1. Electrical & Electronics 7.4.8.2.2. Automotive 7.4.8.2.3. Chemical Industries 7.4.8.2.4. Power Generation 7.4.8.2.5. Oil & Gas 7.4.8.2.6. Others 7.4.8.3. Vietnam Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.8.3.1. Polytetrafluoroethylene (PTFE) 7.4.8.3.2. Polyvinyl Fluoride (PVF) 7.4.8.3.3. Polyvinylidene Fluoride (PVDF) 7.4.8.3.4. Other 7.4.9. Taiwan 7.4.9.1. Taiwan Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.9.1.1. Lubricants 7.4.9.1.2. Heat Transfer Fluids 7.4.9.1.3. Others 7.4.9.2. Taiwan Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.9.2.1. Electrical & Electronics 7.4.9.2.2. Automotive 7.4.9.2.3. Chemical Industries 7.4.9.2.4. Power Generation 7.4.9.2.5. Oil & Gas 7.4.9.2.6. Others 7.4.9.3. Taiwan Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.9.3.1. Polytetrafluoroethylene (PTFE) 7.4.9.3.2. Polyvinyl Fluoride (PVF) 7.4.9.3.3. Polyvinylidene Fluoride (PVDF) 7.4.9.3.4. Other 7.4.10. Rest of Asia Pacific 7.4.10.1. Rest of Asia Pacific Engineered Fluids Market Size and Forecast, by Application (2025-2034) 7.4.10.1.1. Lubricants 7.4.10.1.2. Heat Transfer Fluids 7.4.10.1.3. Others 7.4.10.2. Rest of Asia Pacific Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 7.4.10.2.1. Electrical & Electronics 7.4.10.2.2. Automotive 7.4.10.2.3. Chemical Industries 7.4.10.2.4. Power Generation 7.4.10.2.5. Oil & Gas 7.4.10.2.6. Others 7.4.10.3. Rest of Asia Pacific Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 7.4.10.3.1. Polytetrafluoroethylene (PTFE) 7.4.10.3.2. Polyvinyl Fluoride (PVF) 7.4.10.3.3. Polyvinylidene Fluoride (PVDF) 7.4.10.3.4. Other 8. Middle East and Africa Engineered Fluids Market Size and Forecast by Segmentation (in USD Million) 2025-2034 8.1. Middle East and Africa Engineered Fluids Market Size and Forecast, by Application (2025-2034) 8.1.1. Lubricants 8.1.2. Heat Transfer Fluids 8.1.3. Others 8.2. Middle East and Africa Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 8.2.1. Electrical & Electronics 8.2.2. Automotive 8.2.3. Chemical Industries 8.2.4. Power Generation 8.2.5. Oil & Gas 8.2.6. Others 8.3. Middle East and Africa Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 8.3.1. Polytetrafluoroethylene (PTFE) 8.3.2. Polyvinyl Fluoride (PVF) 8.3.3. Polyvinylidene Fluoride (PVDF) 8.3.4. Other 8.4. Middle East and Africa Engineered Fluids Market Size and Forecast, by Country (2025-2034) 8.4.1. South Africa 8.4.1.1. South Africa Engineered Fluids Market Size and Forecast, by Application (2025-2034) 8.4.1.1.1. Lubricants 8.4.1.1.2. Heat Transfer Fluids 8.4.1.1.3. Others 8.4.1.2. South Africa Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 8.4.1.2.1. Electrical & Electronics 8.4.1.2.2. Automotive 8.4.1.2.3. Chemical Industries 8.4.1.2.4. Power Generation 8.4.1.2.5. Oil & Gas 8.4.1.2.6. Others 8.4.1.3. South Africa Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 8.4.1.3.1. Polytetrafluoroethylene (PTFE) 8.4.1.3.2. Polyvinyl Fluoride (PVF) 8.4.1.3.3. Polyvinylidene Fluoride (PVDF) 8.4.1.3.4. Other 8.4.2. GCC 8.4.2.1. GCC Engineered Fluids Market Size and Forecast, by Application (2025-2034) 8.4.2.1.1. Lubricants 8.4.2.1.2. Heat Transfer Fluids 8.4.2.1.3. Others 8.4.2.2. GCC Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 8.4.2.2.1. Electrical & Electronics 8.4.2.2.2. Automotive 8.4.2.2.3. Chemical Industries 8.4.2.2.4. Power Generation 8.4.2.2.5. Oil & Gas 8.4.2.2.6. Others 8.4.2.3. GCC Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 8.4.2.3.1. Polytetrafluoroethylene (PTFE) 8.4.2.3.2. Polyvinyl Fluoride (PVF) 8.4.2.3.3. Polyvinylidene Fluoride (PVDF) 8.4.2.3.4. Other 8.4.3. Nigeria 8.4.3.1. Nigeria Engineered Fluids Market Size and Forecast, by Application (2025-2034) 8.4.3.1.1. Lubricants 8.4.3.1.2. Heat Transfer Fluids 8.4.3.1.3. Others 8.4.3.2. Nigeria Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 8.4.3.2.1. Electrical & Electronics 8.4.3.2.2. Automotive 8.4.3.2.3. Chemical Industries 8.4.3.2.4. Power Generation 8.4.3.2.5. Oil & Gas 8.4.3.2.6. Others 8.4.3.3. Nigeria Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 8.4.3.3.1. Polytetrafluoroethylene (PTFE) 8.4.3.3.2. Polyvinyl Fluoride (PVF) 8.4.3.3.3. Polyvinylidene Fluoride (PVDF) 8.4.3.3.4. Other 8.4.4. Rest of ME&A 8.4.4.1. Rest of ME&A Engineered Fluids Market Size and Forecast, by Application (2025-2034) 8.4.4.1.1. Lubricants 8.4.4.1.2. Heat Transfer Fluids 8.4.4.1.3. Others 8.4.4.2. Rest of ME&A Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 8.4.4.2.1. Electrical & Electronics 8.4.4.2.2. Automotive 8.4.4.2.3. Chemical Industries 8.4.4.2.4. Power Generation 8.4.4.2.5. Oil & Gas 8.4.4.2.6. Others 8.4.4.3. Rest of ME&A Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 8.4.4.3.1. Polytetrafluoroethylene (PTFE) 8.4.4.3.2. Polyvinyl Fluoride (PVF) 8.4.4.3.3. Polyvinylidene Fluoride (PVDF) 8.4.4.3.4. Other 9. South America Engineered Fluids Market Size and Forecast by Segmentation (in USD Million) 2025-2034 9.1. South America Engineered Fluids Market Size and Forecast, by Application (2025-2034) 9.1.1. Lubricants 9.1.2. Heat Transfer Fluids 9.1.3. Others 9.2. South America Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 9.2.1. Electrical & Electronics 9.2.2. Automotive 9.2.3. Chemical Industries 9.2.4. Power Generation 9.2.5. Oil & Gas 9.2.6. Others 9.3. South America Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 9.3.1. Polytetrafluoroethylene (PTFE) 9.3.2. Polyvinyl Fluoride (PVF) 9.3.3. Polyvinylidene Fluoride (PVDF) 9.3.4. Other 9.4. South America Engineered Fluids Market Size and Forecast, by Country (2025-2034) 9.4.1. Brazil 9.4.1.1. Brazil Engineered Fluids Market Size and Forecast, by Application (2025-2034) 9.4.1.1.1. Lubricants 9.4.1.1.2. Heat Transfer Fluids 9.4.1.1.3. Others 9.4.1.2. Brazil Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 9.4.1.2.1. Electrical & Electronics 9.4.1.2.2. Automotive 9.4.1.2.3. Chemical Industries 9.4.1.2.4. Power Generation 9.4.1.2.5. Oil & Gas 9.4.1.2.6. Others 9.4.1.3. Brazil Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 9.4.1.3.1. Polytetrafluoroethylene (PTFE) 9.4.1.3.2. Polyvinyl Fluoride (PVF) 9.4.1.3.3. Polyvinylidene Fluoride (PVDF) 9.4.1.3.4. Other 9.4.2. Argentina 9.4.2.1. Argentina Engineered Fluids Market Size and Forecast, by Application (2025-2034) 9.4.2.1.1. Lubricants 9.4.2.1.2. Heat Transfer Fluids 9.4.2.1.3. Others 9.4.2.2. Argentina Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 9.4.2.2.1. Electrical & Electronics 9.4.2.2.2. Automotive 9.4.2.2.3. Chemical Industries 9.4.2.2.4. Power Generation 9.4.2.2.5. Oil & Gas 9.4.2.2.6. Others 9.4.2.3. Argentina Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 9.4.2.3.1. Polytetrafluoroethylene (PTFE) 9.4.2.3.2. Polyvinyl Fluoride (PVF) 9.4.2.3.3. Polyvinylidene Fluoride (PVDF) 9.4.2.3.4. Other 9.4.3. Rest Of South America 9.4.3.1. Rest Of South America Engineered Fluids Market Size and Forecast, by Application (2025-2034) 9.4.3.1.1. Lubricants 9.4.3.1.2. Heat Transfer Fluids 9.4.3.1.3. Others 9.4.3.2. Rest Of South America Engineered Fluids Market Size and Forecast, by End-users (2025-2034) 9.4.3.2.1. Electrical & Electronics 9.4.3.2.2. Automotive 9.4.3.2.3. Chemical Industries 9.4.3.2.4. Power Generation 9.4.3.2.5. Oil & Gas 9.4.3.2.6. Others 9.4.3.3. Rest Of South America Engineered Fluids Market Size and Forecast, by Polymer Type (2025-2034) 9.4.3.3.1. Polytetrafluoroethylene (PTFE) 9.4.3.3.2. Polyvinyl Fluoride (PVF) 9.4.3.3.3. Polyvinylidene Fluoride (PVDF) 9.4.3.3.4. Other 10. Company Profile: Key Players 10.1. ExxonMobil Corporation 10.1.1. Company Overview 10.1.2. Business Portfolio 10.1.3. Financial Overview 10.1.4. SWOT Analysis 10.1.5. Strategic Analysis 10.1.6. Scale of Operation (small, medium, and large) 10.1.7. Details on Partnership 10.1.8. Regulatory Accreditations and Certifications Received by Them 10.1.9. Awards Received by the Firm 10.1.10. Recent Developments 10.2. Shell plc 10.3. TotalEnergies SE 10.4. BP plc 10.5. BASF SE 10.6. Dow Inc. 10.7. Honeywell International Inc. 10.8. Daikin Industries, Ltd. 10.9. Shin-Etsu Chemical Co., Ltd. 10.10. Syensqo SA 10.11. Arkema Group 10.12. Wacker Chemie AG 10.13. Huntsman Corporation 10.14. The Chemours Company 10.15. The Lubrizol Corporation 10.16. Kuraray Co., Ltd. 10.17. Clariant AG 10.18. Momentive Performance Materials Inc. 10.19. Croda International Plc 10.20. Quaker Houghton 10.21. Halocarbon, LLC 10.22. Nye Lubricants, Inc. 10.23. AGC Inc. 10.24. Interflon BV 10.25. Engineered Fluids, Inc. 10.26. F2 Chemicals Ltd. 10.27. Chemtool Incorporated 10.28. Perstorp Holding AB 10.29. Cargill, Incorporated 10.30. Eastman Chemical Company 10.31. DuPont de Nemours, Inc. 10.32. Chevron Corporation 10.33. FUCHS SE 10.34. Idemitsu Kosan Co., Ltd. 10.35. ENEOS Corporation 10.36. PetroChina Company Limited 10.37. China Petroleum & Chemical Corporation (Sinopec) 10.38. PETRONAS Lubricants International 10.39. M&I Materials Ltd. 10.40. HaloPolymer OJSC 11. Key Findings 12. Industry Recommendations 13. Engineered Fluids Market: Research Methodology 14. Terms and Glossary

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements