
Aircraft Engines Market – Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning / Landscape Review & Global Market Size Forecast to 2034
Overview
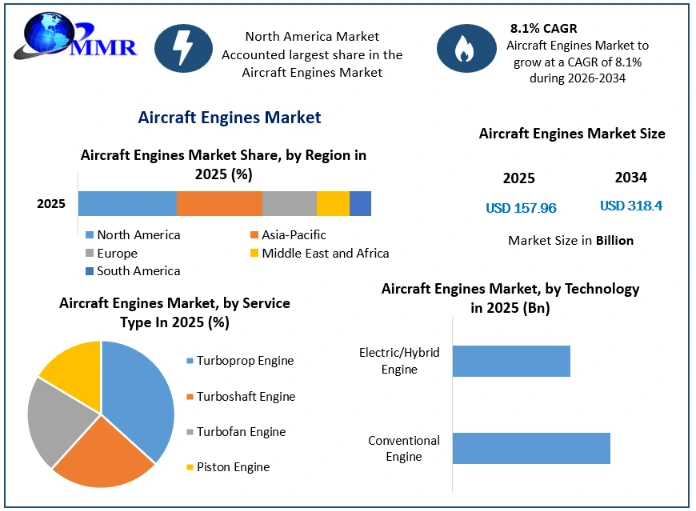
The Aircraft Engines Market was valued at USD 157.96 billion in 2025, and total global Aircraft Engines Market revenue is expected to grow at a CAGR of 8.1% from 2026 to 2034, reaching nearly USD 318.4 billion.
Aircraft Engines Market Overview
Aircraft engines are propulsion systems designed to generate thrust for aircraft movement using various technologies such as turbofan, turboprop, and turboshaft configurations in commercial, military, and general aviation sectors. The Aircraft Engines Market involves the design, manufacturing, maintenance, and supply of engines used across fixed-wing and rotary-wing aircraft. Demand is growing due to their rising global air travel, fleet modernization, and regulatory mandates for fuel efficiency. Availability is influenced by OEM capacities and MRO networks, while supply chains face constraints due to material and component shortages.
Aircraft Engines Market Size, Growth & Share Analysis
To know about the Research Methodology :- Request Free Sample Report
North America dominated the aircraft engines market in 2025, sponsored by strong OEM presence (GE Aerospace, Pratt & Whitney), advanced MRO infrastructure, and large-scale defense and commercial orders driving regional growth. Top players such as GE Aerospace, Pratt & Whitney, Rolls-Royce, and Safran lead the Aircraft Engines Industry by their technological innovation, strategic OEM alliances, and robust global MRO presence. Commercial narrow-body aircraft is the leading end-user segment, accounting for the highest Aircraft Engines Market share in 2025 due to their global airline fleet expansion and demand for fuel-efficient engines.
Aircraft Engines Market Dynamics
Focus on Fuel Efficiency and Lightweight Design to Drive the Aircraft Engines Market
Rising fuel prices have placed intense pressure on airlines and aircraft manufacturers to optimize operational efficiency, making fuel consumption a critical performance factor. Leading OEMs and aircraft manufacturers are increasingly investing in lightweight, high-performance engines to reduce fuel burn and improve the overall economics of aircraft operation. By lowering the total weight of the aircraft, manufacturers can significantly enhance fuel efficiency, reduce operating costs, and improve payload capacity. This shift toward lightweight design is being made possible by the adoption of advanced composite materials, such as carbon fiber-reinforced polymers and high-strength lightweight plastics, which drives the Aircraft Engines Market growth.
These materials not only reduce weight but also maintain structural integrity and durability, enabling aircraft to operate more efficiently over longer periods. advances in turbine blade design, engine core optimization, and integration of next-generation propulsion technologies are further pushing the boundaries of fuel savings. Governments and international aviation bodies are tightening emissions regulations, compelling manufacturers to design engines that not only consume less fuel but also emit fewer greenhouse gases. Technologies such as geared turbofans and open rotor concepts are being explored to meet these requirements without compromising performance.
High Costs and Long Product Life Cycles to Hinder Market Growth
Most engines are designed to operate efficiently for decades, meaning that replacement demand arises primarily from new aircraft production rather than from wear and tear. The aircraft engines are high-value, capital-intensive products. Manufacturing requires specialized facilities, advanced materials, and a highly skilled workforce, all of which contribute to elevated production costs. The same applies to maintenance, repair, and overhaul (MRO) activities, which demand precision engineering and technical expertise. Large backlogs of aircraft orders can slow down OEM productivity and delay engine deliveries. Combined, these factors create financial and operational challenges for both manufacturers and suppliers, acting as a restraint on the Aircraft Engines Market growth.
Aircraft Engines Market Segment Analysis
Based on Technology, the Conventional segment dominated the Aircraft Engines Market in 2025. Conventional aircraft are also known as aero engines. This is the most important power component for an aircraft propulsion system. Increased use of conventional engines in current commercial and military aircraft is driving the demand for the segment. Combustion engines with conventional powertrains offer the best performance in terms of simple layout, well-known and approved technology, and excellent performance in terms of mission range. Increasing investment in research and development of hybrid technology to reduce fuel consumption and carbon dioxide emissions.
Based on Type, the Turbofan dominated the market in 2025 with the largest Aircraft Engines Market share. Turbofan engines, known as fan jets or bypass engines, generate thrust through a combination of high-velocity exhaust from the engine core and bypass air propelled by a large fan. This design delivers superior fuel efficiency, enhanced thrust at cruising altitudes, and lower noise emissions compared to other engine types. The accelerating fan, driven by the turbine core, significantly boosts overall performance while reducing specific fuel consumption. These advantages make turbofans the preferred choice for commercial airliners, long-haul military transport aircraft, and certain business jets. Rising global air travel demand, the push for quieter and greener aviation technologies, and the introduction of next-generation geared turbofan systems are expected to further strengthen this segment’s market position.
Aircraft Engines Market Regional Analysis
The North America region held the largest Aircraft Engines Market share in 2025. Rising manufacturing and the growth of the aerospace industry have led aircraft engine manufacturers to introduce technologically advanced and efficient products to a wide variety of aircraft. The growing demand for aero engines and the presence of key players, such as General Electric Company and Honeywell International Inc., in the region. These players are focusing on research and development to expand their product line and use technologically advanced systems, subsystems, and other components to manufacture aircraft engines. These factors are driving the growth of the aircraft engines industry in the region.
Asia Pacific is expected to grow at the highest CAGR through the forecasted period. Increased defense budgets and air fleets in emerging countries such as India and China are expected to contribute to regional growth. Due to geopolitical tensions in the region, countries are increasing their investment to enhance their flight capabilities by procuring advanced aircraft and replacing older aircraft. These factors are expected to drive the growth of the market in the region through the forecast period.
Aircraft Engines Market Competitive Landscape
The Aircraft Engines Market is dominated by major players due to government support, innovation and sustainability trends. For example, the U.S. Department of Defense allocated $25.7 billion for aircraft propulsion programs in FY2024, boosting R&D. The EU’s Clean Aviation Initiative received €4.1 billion through 2031 to develop zero-emission technologies. These policies push key players like GE and Rolls-Royce to shift toward hybrid-electric engines, SAF integration, and digital MRO, ensuring long-term growth, regulatory compliance and global competitiveness.
Top players in the Aircraft Engines Market include GE Aerospace, Rolls-Royce, Pratt & Whitney, and Safran Aircraft Engines, each commanding global influence by advanced technology, strategic partnerships and government-backed innovation. GE leads with its LEAP engine via CFM International JV and strong U.S. defense contracts. Rolls-Royce dominates the wide-body segment and benefits from the EU’s green aviation funding. Pratt & Whitney led with its fuel-efficient Geared Turbofan (GTF) engines, while Safran, as Airbus’s key partner, is pivotal in Europe's shift toward sustainable aviation.
Aircraft Engines Market Key Trends
| Key Trend | Market Implications |
| Sustainable Aviation Push | Accelerates industry shift toward low-emission engines, forcing competitors to invest in clean-tech R&D or risk obsolescence. |
| Supply Chain Localization | Reduces Western reliance on traditional manufacturing hubs, creating new aerospace clusters in Africa/emerging markets. |
| Military Engine Sovereignty | Nations prioritizing domestic engine programs fragment the historically US/EU-dominated defense engine market. |
| Regional Jet Resurgence | Rising demand for fuel-efficient short-haul fleets benefits engine makers with specialized small turbofans. |
Aircraft Engines Market Recent Industry Development
| Date | Company | Development | Impact |
|---|---|---|---|
| 28 February 2025 | Pratt & Whitney | Pratt & Whitney achieved U.S. FAA type certification for its GTF Advantage engine, designed to power the Airbus A320neo family. | The certified engine delivers up to 8% higher takeoff thrust and reduced carbon emissions, establishing new efficiency standards for single-aisle commercial aircraft. |
| 09 March 2026 | GE Aerospace | GE Aerospace announced a $1 billion investment in U.S. manufacturing sites and supply chains to ramp up production of commercial and defense engines. | The funding expands assembly capacity for CFM LEAP and military propulsion systems while hiring 5,000 workers across 17 states. |
| 15 July 2026 | Pratt & Whitney | Pratt & Whitney completed the acquisition of Amsterdam-based Aiir Innovations to integrate AI-assisted borescope software across its global engine maintenance network. | The technology speeds up engine component inspections, cutting turnaround times and increasing time on wing for commercial and military fleets. |
| 21 July 2026 | GE Aerospace | GE Aerospace secured a major commercial agreement from AerCap to supply GEnx-1B engines for 15 additional Boeing 787 Dreamliners. | The deal reinforces market demand for widebody propulsion systems featuring 99.98% dispatch reliability and improved hot-section durability. |
| 27 August 2026 | Rolls-Royce | Rolls-Royce completed a $1 billion decade-long modernization program at its Indianapolis engine manufacturing, assembly, and testing campus. | The facility expansion cements advanced defense manufacturing capabilities for military aircraft engines supporting global defense platforms. |
Aircraft Engines Market Scope: Inquire before buying
| Global Aircraft Engines Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 157.96 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 8.1% | Market Size in 2034: | USD 318.4 Bn. |
| Segments Covered: | by Type | Turboprop Engine Turboshaft Engine Turbofan Engine Piston Engine |
|
| by Technology | Conventional Engine Electric/Hybrid Engine |
||
| by Component | Compressor Turbine Gear Box Combustion Chamber Fuel System Others |
||
| by Platform | Unmanned Ariel Fixed Wing Rotary Wing |
||
| by End Use | Commercial Narrow Body Wide Body Business Jet General Aviation Helicopters Others Military Fighter Aircraft Military Transport Aircraft Militar Helicopters Others Others |
||
| by Point-of-sale | OEM Aftermarket |
||
Aircraft Engines Market, by Region
North America (United States, Canada, Mexico)
Europe (United Kingdom, France, Germany, Italy, Spain, Sweden, Russia, the Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Philippines, Thailand, Vietnam, Rest of Asia Pacific)
Middle East and Africa (MEA) (South Africa, GCC, Nigeria, Rest of MEA)
South America (Brazil, Argentina, Colombia, Chile, Rest of South America)
Aircraft Engines Market, Key Players
North America
1. GE Aerospace (USA)
2. Pratt & Whitney (USA)
3. Honeywell Aerospace (USA)
4. Williams International (USA)
5. Textron Inc. (USA)
6. Raytheon Technologies (USA)
Europe
7. Rolls-Royce Holdings (UK)
8. Safran Aircraft Engines (France)
9. MTU Aero Engines (Germany)
10. ITP Aero (Spain)
11. Avio Aero (Italy)
12. GKN Aerospace (UK)
Asia Pacific
13. IHI Corporation (Japan)
14. Kawasaki Heavy Industries (Japan)
15. Mitsubishi Heavy Industries (Japan)
16. Hindustan Aeronautics Limited (India)
17. AECC – Aero Engine Corporation of China (China)
18. AVIC Shenyang Liming Aero-Engine (China)
Middle East and Africa
19. Turbomeca Middle East (UAE)
20. SAMI – Saudi Arabian Military Industries (Saudi Arabia)
21. Denel Aerostructures (South Africa)
South America
22. Embraer (Brazil)
23. Akaer Engenharia (Brazil)
Frequently Asked Questions
1] What segments are covered in the Aircraft Engines Market report?
Ans. The segments covered in the Aircraft Engines Market report are based on Type, Technology, Component, Platform, End-Use, and Point of Sale.
2] Which region is expected to hold the highest share in the Aircraft Engines Market?
Ans. The North America Region is expected to hold the highest share in the Aircraft Engines Market.
3] What is the market size of the Aircraft Engines Market by 2034?
Ans. The market size of the Aircraft Engines Market by 2034 is USD 318.4 Bn.
4] Who are the top key players in the Aircraft Engines Market?
Ans. GE Aerospace (USA), Pratt & Whitney (USA), Honeywell Aerospace (USA),Williams International (USA), Textron Inc. (USA) and Raytheon Technologies (USA) and others.
5] What was the market size of the Aircraft Engines Market in 2025?
Ans. The Aircraft Engines Market Size was USD 157.96 Bn. in 2025.