
Biostimulants Market – Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034
Overview
Global Biostimulants Market Overview:
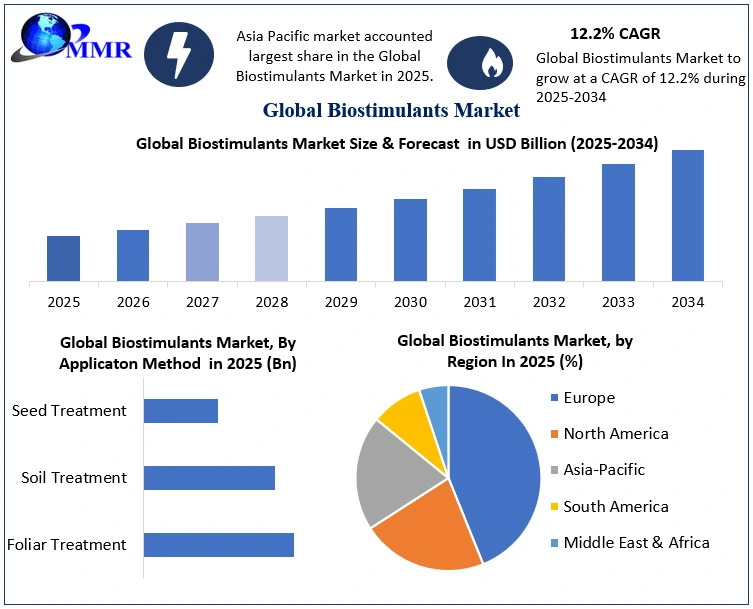
The Global Biostimulants Market was valued at USD 4.90 Billion in 2025 and is projected to reach USD 13.81 Billion by 2034, growing at a CAGR of 12.2% during 2026–2034.
Biostimulants are agricultural products containing substances or microorganisms that enhance plant growth, nutrient-use efficiency, crop quality, and resilience to environmental stresses. They include seaweed extracts, humic and fulvic acids, amino acids, microbial products, and other plant-based or naturally derived formulations. Biostimulants are increasingly used in modern agriculture to support crop productivity while improving the efficiency of agricultural inputs.
The Biostimulants Market is expanding due to the growing adoption of sustainable farming practices, increasing demand for high-quality agricultural produce, and the need to improve crop performance under drought, salinity, temperature fluctuations, and other environmental stresses. Europe is a leading regional market, supported by the adoption of sustainable agricultural practices and regulatory initiatives promoting efficient crop production. Major companies operating in the market include BASF SE, UPL Limited, Biolchim S.p.A., Valagro S.p.A., and Koppert Biological Systems.
The market's development is further supported by the increasing use of biostimulants in cereals and grains, fruits and vegetables, oilseeds and pulses, and other crops. Application methods such as foliar treatment, soil treatment, and seed treatment provide manufacturers and agricultural producers with multiple avenues for market expansion.
The Maximize Market Research (MMR) Biostimulants Market Report provides a comprehensive assessment of the industry, covering market size, growth trends, drivers, restraints, opportunities, competitive landscape, and regional dynamics. The report analyzes key market segments by active ingredient, crop type, application method, and region, while also evaluating the strategies and developments of major companies. It provides quantitative and qualitative insights that can help clients understand market opportunities, competitive developments, regional demand patterns, and future growth prospects.
Global Biostimulants Market Growth Outlook
To know about the Research Methodology :- Request Free Sample Report
Global Biostimulants Market Dynamics
Market Drivers
• Growing Market Value: The global biostimulants market was valued at USD 4.90 Billion in 2025 and is projected to reach USD 13.81 Billion by 2034, reflecting a CAGR of 12.2% during 2026–2034.
• Increasing Demand for Sustainable Agriculture: Growing emphasis on sustainable farming and improved crop productivity is encouraging the adoption of biostimulants as complementary inputs to conventional fertilizers.
• Rising Crop Applications: Increasing use across cereals and grains, fruits and vegetables, oilseeds and pulses, and other crops is creating broader market opportunities.
• Multiple Application Methods: Foliar treatment, soil treatment, and seed treatment allow biostimulant manufacturers to address different crop requirements and farming practices.
Market Restraints
• Limited Awareness Among Farmers: Lack of knowledge regarding the appropriate selection, dosage, and application of biostimulants can restrict adoption in developing agricultural markets.
• Variable Field Performance: The effectiveness of biostimulants can vary according to crop type, soil conditions, climate, formulation, and application method.
• Regulatory Complexity: Differences in regulatory frameworks and product classification across countries can increase the time and cost required for market entry.
Market Opportunities
• Rapid Market Expansion: Growth from USD 4.90 Billion in 2025 to USD 13.81 Billion by 2034 creates substantial opportunities for manufacturers, distributors, and technology providers.
• Product Innovation: Development of advanced formulations combining seaweed extracts, humic substances, amino acids, microorganisms, and other bio-based ingredients can expand product portfolios.
• Expansion Across Crop Segments: Rising adoption in cereals and grains, fruits and vegetables, oilseeds and pulses, and other crops provides opportunities for crop-specific formulations.
Market Challenges
• Product Standardization: Variations in composition and performance can make consistent product quality and efficacy challenging.
• Farmer Adoption Costs: Initial product costs and uncertainty regarding return on investment may influence adoption decisions.
• Competition with Conventional Inputs: Biostimulant producers must demonstrate clear agronomic benefits while operating alongside established fertilizer and crop-input products.
Biostimulants Market Segment Analysis:
Biostimulants Market, by active ingredient
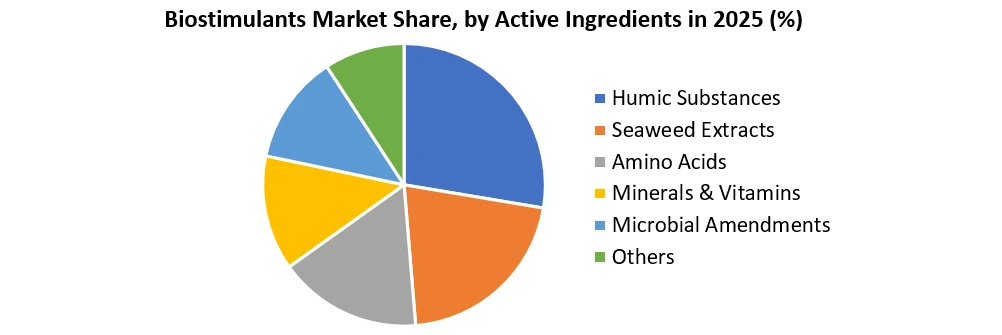
The biostimulants market is segmented into humic substances, seaweed extracts, amino acids, minerals & vitamins, microbial amendments, and others. Seaweed extracts held the leading share in 2025, supported by their strong use in improving root development, nutrient uptake, chlorophyll formation, stress tolerance, and crop quality. Seaweed-based products contain bioactive compounds such as auxins, cytokinins, gibberellins, polysaccharides, and micronutrients, making them widely preferred in fruits, vegetables, cereals, and high-value crops. Humic substances and amino acids also accounted for significant market share due to their role in soil conditioning, nutrient mobility, seed vigor, and abiotic stress management. Seaweed extract biostimulants are also highlighted by secondary sources as a fast-growing product category driven by rising demand for natural, plant-based agricultural inputs.
Biostimulants Market, by crop type
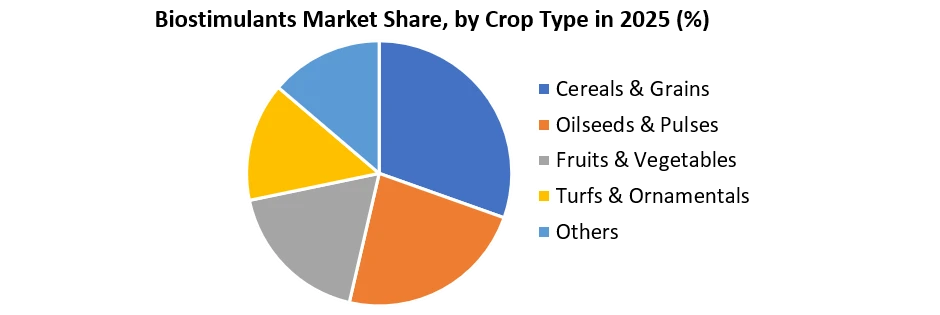
The biostimulants market is segmented into cereals & grains, oilseeds & pulses, fruits & vegetables, turf & ornamentals, and others, including forage and plantation crops. Cereals & grains held the largest share in 2025, supported by large-scale cultivation of corn, wheat, rice, barley, oats, and millets across major agricultural economies. Biostimulants are increasingly used in these crops to improve seed germination, root growth, nutrient uptake, stress resistance, and yield stability. Fruits & vegetables represented the second-largest segment due to strong demand for improved crop size, color, quality, shelf life, and residue-free produce, while oilseeds & pulses continued to gain adoption in soybean, sunflower, lentils, and other protein-rich crops.
Biostimulants Market, by Source
The biostimulants market is divided into natural and microbial sources. Natural-source biostimulants dominated the market in 2025, driven by the widespread use of seaweed extracts, humic acids, fulvic acids, amino acids, and plant-based extracts in sustainable and organic farming systems. These products are strongly preferred because they improve plant metabolism, root activity, soil health, nutrient efficiency, and tolerance to abiotic stress without directly replacing fertilizers or pesticides. Microbial biostimulants are gaining strong momentum as farmers increasingly adopt beneficial bacteria and fungi to improve nutrient availability, rhizosphere activity, soil biology, and crop resilience.
Biostimulants Market, by Farming Practice
The biostimulants market is segmented into conventional farming, organic farming, and greenhouse production. Conventional farming held the largest share in 2025, as biostimulants are increasingly being used alongside fertilizers and crop protection products to improve nutrient-use efficiency, yield quality, and stress tolerance in broad-acre and commercial farming systems. Organic farming represented a fast-growing segment due to rising demand for residue-free food, soil-health restoration, and sustainable agricultural inputs. Greenhouse production also showed steady adoption because protected cultivation requires high crop quality, uniform growth, controlled nutrition, and efficient stress management for vegetables, fruits, flowers, and ornamentals.
Biostimulants Market, by Application Method
The biostimulants market is segmented into foliar treatment, soil treatment, and seed treatment. Foliar treatment held the largest market share in 2025, as it enables quick absorption of biostimulant compounds through leaves and provides faster crop response during stress periods. This method is widely used for seaweed extracts, amino acids, micronutrient blends, and plant-based formulations in cereals, fruits, vegetables, and high-value crops. Soil treatment remained important for improving root growth, soil microbial activity, nutrient mobility, and long-term soil health, while seed treatment gained adoption due to its ability to improve germination, seedling vigor, early root establishment, and crop uniformity. MarketsandMarkets also identifies foliar treatment as the largest application segment in 2025.
Biostimulants Market, by Form
The biostimulants market is categorized into liquid and dry formulations. Liquid biostimulants held the largest market share in 2025, mainly due to their easy mixing ability, fast absorption, compatibility with fertigation and foliar spray systems, and suitability for precision farming. Liquid products are widely preferred by growers because they allow uniform application and quick plant response, especially under stress conditions such as drought, salinity, heat, and nutrient deficiency. Dry biostimulants also maintained a strong position due to better shelf life, lower transport cost, and suitability for seed treatment, soil application, and bulk agricultural use.
Biostimulants Market Regional Insights
Europe dominated the global biostimulants market
Accounting for 43.9% of the market share in 2025, supported by increasing adoption of sustainable agricultural practices, organic farming, and regulations promoting environmentally friendly crop inputs. Countries such as Germany, France, Italy, and Spain are witnessing growing demand for biostimulants, while major companies including BASF SE and Valagro are strengthening their presence through product development and agricultural solutions. The United States represents a major market in North America, supported by increasing awareness of soil health, crop productivity, and sustainable farming practices.
Asia-Pacific is expected to witness significant growth during the forecast period
Driven by rising food demand, expanding agricultural production, and growing awareness of crop quality and productivity. China represents a major market in the region, supported by its large agricultural sector and increasing adoption of advanced agricultural inputs. India and Japan are also contributing to regional market expansion through investments in sustainable farming technologies and improved crop management practices.
South America is experiencing increasing demand for biostimulants
Supported by the expansion of commercial agriculture and the growing adoption of environmentally responsible farming methods. Brazil represents a major market in the region, followed by Argentina, where extensive cultivation of soybeans, corn, and other crops creates opportunities for biostimulant applications. Overall, increasing emphasis on soil health, crop efficiency, and sustainable agricultural production is expected to support market development across emerging regions.
Biostimulant Industry Ecosystem
Competitive Landscape – Biostimulants Market
The global Biostimulants Market is characterized by a mix of multinational agricultural-input companies and specialized biological-input manufacturers. Competition is primarily shaped by product innovation, R&D capabilities, regulatory approvals, manufacturing capacity, geographic reach, strategic partnerships, acquisitions, and expansion of crop-specific biostimulant portfolios. Major companies are increasingly developing solutions focused on abiotic-stress tolerance, nutrient-use efficiency, soil health, crop yield, and sustainable agriculture.
Key players include Syngenta Group, BASF SE, Bayer AG, UPL Limited, Corteva Agriscience, FMC Corporation, Sumitomo Chemical Co., Ltd., Novonesis, Yara International, Koppert Biological Systems, Acadian Plant Health, Biolchim S.p.A., Nufarm Limited, PI Industries Ltd., and SEIPASA S.A.

Recent development:
February 2026 – Acadian Plant Health highlighted its Abiotic Stress Management (ASM) biostimulant portfolio in response to severe winter conditions across EMEA, including flooding, excessive humidity, frost, and extreme temperature events. The portfolio uses biomarkers derived from Ascophyllum nodosum seaweed extracts combined with anti-stress compounds to help crops prime, protect, and recover from abiotic stress. The development reinforces the growing role of seaweed-based biostimulants in improving crop resilience under increasingly unpredictable weather conditions.
February 2026 – Acadian Plant Health expanded its focus on climate-resilient crop production, emphasizing next-generation biostimulants designed to support crop performance during drought, cold, flooding, and other environmental stresses. Its 2026 communications position abiotic-stress management as an important application area for biological crop inputs, particularly as growers seek solutions that maintain crop health and productivity under volatile climatic conditions.
May 2026 – BASF commissioned its BioHub fermentation plant in Ludwigshafen, Germany, backed by a high double-digit million-euro investment. The facility strengthens BASF’s internal production capability for biological and biotechnology-based crop inputs. Although the plant is broader than biostimulants alone, it is strategically relevant because fermentation capacity is central to scaling microbial and biotechnology-based agricultural biologicals.
December 2026 - developments cannot yet be reported as completed recent developments, because December 2026 is still in the future. For a market report published now, it would be more accurate to use the December 2025 Sumitomo Chemical Agro Europe Valent BioSciences portfolio launch rather than label it as a December 2026 development. The companies launched their new EMEA biostimulant portfolio in December 2025 around three technology platforms: MCOM, S-ABA, and MycoApply AMF.
March 2026 – Certis Belchim and Elicit Plant announced a strategic partnership to co-develop an innovative biostimulant for potatoes. The collaboration combines Elicit Plant’s agri-biotechnology and R&D capabilities with Certis Belchim’s crop-solution and potato-market expertise. The planned biological solution is designed to improve potato tolerance to abiotic stress, particularly drought-related stress, helping growers maintain yield and crop quality under increasingly challenging climatic conditions. The development highlights the growing focus on climate-resilient and crop-specific biostimulants in European agriculture.
May 2026 – Verdesian Life Sciences received Certified Biostimulant status from The Fertilizer Institute (TFI) for its Take Off LS liquid biostimulant. The certification followed an independent review of the product's composition, safety, and efficacy. Take Off LS is designed for foliar or in-furrow application in crops including corn and soybeans, with a focus on nitrogen-use efficiency and nutrient uptake. The certification strengthens formal recognition of biostimulant products focused on nutrient efficiency in row-crop agriculture.
March 2026 – Elicit Plant and Certis Belchim formed a strategic partnership to co-develop a potato biostimulant in Europe. The solution is designed to address climate-related production stress, especially drought pressure in potato crops. This development is highly relevant because it shows biostimulants moving from broad crop-enhancement positioning toward crop-specific, stress-specific solutions.
June 2026 – Rovensa Next and Novonesis signed a U.S. distribution agreement under which Rovensa Next will commercialize selected Novonesis agricultural biosolutions from the 2027 growing season. The portfolio includes biostimulants, biofertilizers, bionutrition, biocontrol, and adjuvants. This strengthens the U.S. biological-input channel and expands access to science-backed biosolutions across row crops and specialty crops.
July 2026 – Corteva Agriscience and Arevo partnered on Arginex Soy, an arginine-based seed treatment for soybean crops in Europe. The product is designed to strengthen root systems, increase nodulation, and improve soybean performance by supporting early nutrient-use efficiency. This is relevant to the biostimulants market because seed-applied biostimulants are gaining traction as growers look for early-stage crop establishment and nutrient-efficiency tools.
June 2026 – Certis Belchim and Greenhas Group announced a formal collaboration on biostimulant development and sales, combining Certis Belchim’s expertise in biological-product development, registration, and marketing with Greenhas Group’s specialized capabilities in biostimulant research, production, and product development. The partnership aims to co-develop new biostimulant products and expand portfolio reach across international markets, with a focus on plant health, crop resilience, productivity, and resource efficiency. This development is relevant to the biostimulants market because it strengthens collaboration between established biological-input companies and expands the pipeline of science-based biostimulant solutions.
Biostimulants Market Scope: Inquiry Before Buying
| Global Biostimulants Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 4.90 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 12.2% | Market Size in 2034: | USD 13.81 Bn. |
| Segments Covered: | by Active Ingredients | Humic Substances Seaweed Extracts Amino Acids Minerals & Vitamins Microbial Amendments Others |
|
| by Crop Type | Flowers & Ornamentals Other Crop Types Fruits & Vegetables Oilseeds & Pulses Cereals & Grains |
||
| by Application | Foliar Soil Treatment Seed Treatment |
||
| by Form | Liquid Dry |
||
| by Farming Practice | Conventional Farming Organic Farming Greenhouse Production |
||
Biostimulants Market, by Region:
North America (United States, Canada, and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, and the Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan, and the Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria, and the Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Biostimulants Market, Key Players:
North America
1. BASF SE
2. Corteva Agriscience
3. FMC Corporation
4. Actagro LLC
5. Koppert Biological Systems
6. Acadian Plant Health
7. Valent BioSciences
8. Verdesian Life Sciences
9. Sound Agriculture
10. American Vanguard Corporation
11. BioFert Manufacturing Inc.
Europe
1. Syngenta Group
2. Syngenta Biologicals (formerly Valagro)
3. Bayer AG
4. UPL Limited
5. Biolchim S.p.A.
6. ILSA S.p.A.
7. Hello Nature
8. PI Industries
9. Novonesis
10. Yara International
11. SEIPASA
12. TIMAC AGRO
13. Bioiberica
14. SICIT Group
15. Elicit Plant
Asia Pacific
1. Sumitomo Chemical Co., Ltd.
2. PI Industries Ltd.
3. Coromandel International Ltd.
4. T. Stanes and Company Ltd.
5. Biostadt India Ltd.
6. IPL Biologicals Ltd.
7. Nufarm Limited
8. Nutri-Tech Solutions
9. Qingdao Seawin Biotech Group
10. Leili Group
11. Angel Yeast Co., Ltd.
Middle East & Africa
1. Omnia Group
2. Agri Life Gulf
3. Emirates Biotech Pharmaceutical Factory LLC
4. Bioriginal Africa
South America
1. Rovensa Next
2. Bioceres Crop Solutions
3. Stoller
4. Aminoagro
5. Solum Brasil
Frequently Asked Questions in the Biostimulants market
1. What are the growth drivers for the Biostimulants market?
Ans. The increasing Organic farming and sustainability in agriculture are the major drivers for the biostimulants market.
2. Which sector is expected to grow the Biostimulants Market?
Ans. The Organic farming industries are expected to grow in the Biostimulants Market during the forecast period.
3. Which region is expected to lead the global Biostimulants Market during the forecast period?
Ans. North America is expected to lead the global Biostimulants Market during the forecast period.
4. What is the projected market size and growth rate of the Market?
Ans. The Biostimulants Market size was valued at USD 4.9 Billion in 2025 and the total Biostimulants revenue is expected to grow at a CAGR of 12.2% from 2026 to 2034, reaching nearly USD 13.81 Billion by 2034.
5. What segments are covered in the Market report?
Ans. The Biostimulants Market report covers segmentation by active ingredient, form, crop type, source, farming practice, application method, and region, including key categories such as humic substances, seaweed extracts, amino acids, liquid and dry formulations, cereals & grains, fruits & vegetables, oilseeds & pulses, natural and microbial sources, conventional and organic farming, and foliar, soil, and seed treatment applications.