
Automotive Market in Germany – Industry Structure Evaluation, Demand Drivers Analysis, Geographicall Growth Analysis and Identification, Competitive Positioning Review & Market Size Forecast to 2034
Overview
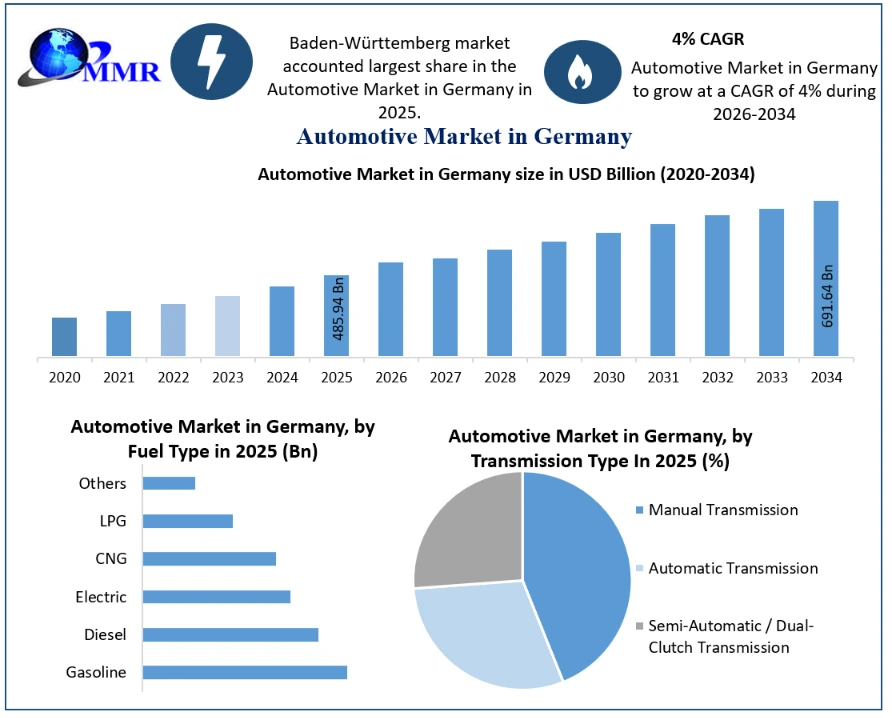
Automotive Market in Germany is expected to grow at a CAGR of 4% throughout the forecast period, to reach US$ 691.64 Bn. by 2034.
Automotive Market in Germany Overview:
The automotive market in Germany is the largest in Europe and the fourth largest in the world, and it is widely regarded as the backbone of the German economy. Germany is not only known for car manufacturing but also for engineering excellence, innovation, and premium quality. It is home to some of the most iconic automotive brands in the world, including Volkswagen, BMW, Mercedes-Benz, Audi, Porsche, and Opel. Every year, Germany produces millions of passenger cars, commercial vehicles, and electric vehicles, a large share of which is exported to markets across Europe, North America, and Asia.
Automotive Market in Germany Growth Outlook
To Know About The Research Methodology :- Request Free Sample Report
The automotive industry contributes significantly to Germany’s GDP, provides direct and indirect employment to millions of people, and is one of the highest investors in research and development globally. In recent years, the market has been undergoing a major transformation from traditional internal combustion engine vehicles towards electric, hybrid, connected, and autonomous vehicles. The German government is actively supporting this transition through investments in EV charging infrastructure, battery gigafactories, and green mobility initiatives. The country also has a world-class supplier ecosystem led by companies such as Bosch, Continental, ZF Friedrichshafen, and Schaeffler, which makes its supply chain extremely strong and innovative. Major production and research hubs are located in Wolfsburg, Munich, Stuttgart, Ingolstadt, Leipzig, and Regensburg. Overall, the Germany automotive market is moving from its traditional strength in premium ICE vehicles towards a future defined by software, electrification, and sustainable mobility, and it is expected to remain one of the most important automotive markets in the world over the next decade.
Automotive Market in Germany Dynamics
The dynamics of the Germany automotive market are shaped by a combination of strong drivers, emerging opportunities, and serious challenges. The biggest driver is electrification, pushed by the strict CO2 emission targets set by the European Union. To meet these targets, all major German OEMs have developed dedicated electric platforms such as Volkswagen’s MEB platform, BMW’s Neue Klasse platform, and Mercedes-Benz’s MMA platform. Another major trend is the rise of software-defined vehicles. A car is no longer just a mechanical product, it has become a connected digital device equipped with ADAS, over-the-air updates, AI-based infotainment, and autonomous driving features. Consumer preferences are also changing rapidly. Many consumers, especially younger buyers, are now shifting from outright ownership towards leasing, subscription, and car-sharing models. Demand for SUVs, premium electric cars, and compact electric vehicles has increased sharply. However, the market also faces significant restraints.
Manufacturing costs, electricity prices, and labour costs in Germany are very high, which makes it difficult to compete on price with Chinese OEMs such as BYD, NIO, and XPeng. Supply chain issues related to semiconductors, lithium, and rare earth materials, along with the withdrawal of EV purchase subsidies, have slowed the growth of EV demand. Strict EU regulations such as Euro 7 norms, the Battery Regulation, and the Data Act have also increased compliance costs. Despite these challenges, there are huge opportunities in battery recycling, solid-state batteries, hydrogen fuel cell vehicles, autonomous driving, and vehicle-to-everything technology. New revenue streams are also emerging in the aftermarket, EV servicing, charging business, and digital services. In total, the German automotive market is currently in a transition phase where companies that can successfully shift from ICE technology to sustainable and digital mobility will survive and grow.
Automotive Market in Germany Segment Analysis
By Vehicle Type: Two-wheeler segment in Germany is relatively small compared to passenger cars, but it has a stable niche market driven by urban commuting, delivery services, and young riders. Motorcycles and scooters are more popular in cities like Munich, Berlin, and Hamburg where parking and traffic are major issues. In recent years, electric two-wheelers and e-scooters have gained popularity due to low running costs and government support for micro-mobility. Three-wheeler segment is almost negligible in Germany because three-wheelers are not a part of German transport culture like in India or Southeast Asia. They are used only in very specific applications such as small cargo delivery in narrow streets and for specially-abled mobility solutions. Passenger cars are by far the largest and most dominant segment in Germany. Within passenger cars, SUVs have become the most preferred body type because German consumers prefer space, safety, high driving position, and premium features.
Sedans still hold a strong position in the premium and executive segment with models like the BMW 3 Series, Mercedes C-Class, and Audi A4, while hatchbacks remain popular for city driving and first-time buyers because they are compact, fuel-efficient, and affordable. Models like the Volkswagen Golf continue to be an icon in this segment. Light Commercial Vehicles including vans and pickup trucks are growing rapidly due to the boom in e-commerce, last-mile delivery, and small business logistics. Vans from Volkswagen, Mercedes-Benz Sprinter, and Ford Transit dominate this category. Heavy Commercial Vehicles including heavy trucks and buses and coaches are a very strong segment because Germany is a logistics hub of Europe. Companies like MAN, Daimler Truck, and Scania have a major presence here. Demand for heavy trucks is driven by freight transport, construction, and cross-border trade, while buses and coaches are driven by public transport modernization and tourism. Off-highway vehicles used in agriculture, construction, and mining form a specialised but profitable segment led by companies like Liebherr, Claas, and John Deere. Overall, passenger cars and commercial vehicles together dominate the market, with SUVs and LCVs showing the highest growth.
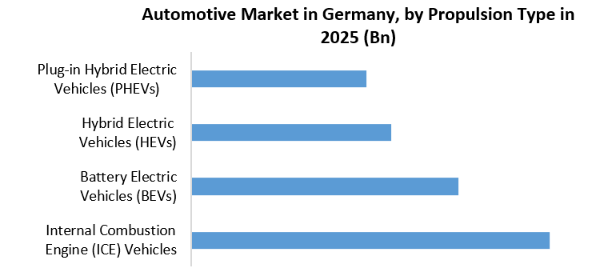
By Propulsion Type: Internal Combustion Engine vehicles still hold a large share of the vehicles on German roads, but their share in new sales is declining every year due to strict EU emission norms and the shift towards electrification. Diesel cars, which were once very popular in Germany, have seen a sharp decline after Dieselgate and rising environmental concerns. Battery Electric Vehicles are the fastest-growing propulsion segment in Germany. Despite the removal of government purchase subsidies, BEV sales are recovering because of new affordable models, improved range, and expanding charging infrastructure. Models like the Tesla Model Y, Volkswagen ID.4, and BMW iX1 are leading this growth. Hybrid Electric Vehicles are also growing because many German consumers still want fuel efficiency without worrying about charging. Toyota, BMW, and Mercedes have strong hybrid portfolios. Plug-in Hybrid Electric Vehicles are very popular in the premium segment because they offer electric driving in the city and petrol or diesel power for long highway drives, and they also benefit from company car taxation benefits. Fuel Cell Electric Vehicles are still in a very early stage in Germany and are mainly used in pilot projects for buses, trucks, and commercial fleets. Germany is investing in hydrogen infrastructure, and FCEVs are expected to grow in the heavy commercial segment in the long term rather than in passenger cars.
By Fuel Type: Gasoline remains the most common fuel type for passenger cars in Germany, especially for small and mid-size cars, because petrol engines are cheaper, quieter, and suitable for city driving. Diesel still holds importance in the commercial vehicle and long-distance segment because diesel engines offer better torque and fuel efficiency for heavy trucks, vans, and large SUVs. However, the overall share of diesel in new passenger car sales has fallen significantly. Electric as a fuel type is growing the fastest, supported by home charging, public fast-charging networks along the Autobahn, and workplace charging. Compressed Natural Gas has a very small share and is mainly used in some municipal fleets and buses, while Liquefied Petroleum Gas is also limited to a niche market of converted vehicles and taxis. Other fuels including hydrogen, biofuels, and synthetic e-fuels are being tested in Germany as future alternatives, especially for aviation, shipping, and heavy transport where electrification is difficult. In the coming years, electric is expected to become the dominant fuel type for new vehicles, while gasoline and diesel will remain important for the existing vehicle fleet.
By Transmission Type: Manual transmission was once the standard in Germany, and German drivers have traditionally preferred manual cars for control and driving pleasure. However, this trend is changing rapidly. Automatic transmission is now becoming the dominant type, especially in premium cars, SUVs, and electric vehicles. Most new BMW, Mercedes, and Audi models are now offered only with automatic gearboxes. Electric vehicles do not need traditional multi-gear transmissions, which has further accelerated the shift to automatic. Semi-automatic and dual-clutch transmission is very popular in the performance and mid-premium segment because it offers the speed of automatic with the sporty feel of manual. Volkswagen’s DSG gearbox is the best example of this technology and is widely used across VW, Audi, and Skoda models. Overall, manual transmission is now limited to entry-level small cars and some commercial vehicles, while automatic and dual-clutch systems dominate the future of the German market.
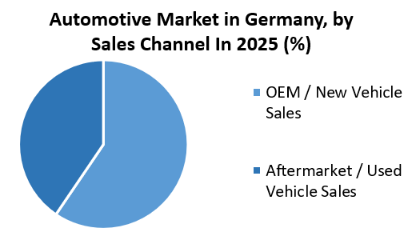
By Sales Channel: OEM and new vehicle sales form the core of the German automotive market. Germany has one of the strongest new car sales networks in Europe, with thousands of dealerships and direct sales channels from Volkswagen, BMW, Mercedes-Benz, and other brands. Company car leasing is a very important part of new vehicle sales in Germany because many employees get cars as part of their job benefits. Aftermarket and used vehicle sales are also extremely large in Germany. Germany has a very well-organised used car market with certified pre-owned programmes from OEMs, online platforms like mobile.de and AutoScout24, and a strong network of independent dealers. Used car demand is high because many consumers prefer a 2 to 3 year old premium car at a lower price instead of a new mass-market car. The aftermarket for spare parts, servicing, tyres, and accessories is also huge and is led by Bosch, Continental, and ZF. In recent years, online sales, digital showrooms, and subscription models are also growing and are changing how Germans buy cars.
By Application: Personal mobility is the largest application segment in Germany because the majority of cars are bought for personal and family use. Germans have a strong car culture, and owning a car is still seen as a symbol of freedom and status, especially in suburban and rural areas where public transport is less frequent. Commercial and logistics is the second largest application, driven by Germany’s position as Europe’s logistics centre. Trucks, vans, and delivery vehicles are essential for e-commerce, manufacturing supply chains, and cross-border trade. Public transport is also a major application, with strong demand for buses, trams, and coaches in cities like Berlin, Munich, and Hamburg. The German government is investing in electric buses and modernising public transport to reduce emissions. Shared mobility and mobility services including car-sharing, ride-hailing, and rental services are growing fast in urban areas. Services like Sixt, Europcar, and SHARE NOW are popular among young urban consumers who do not want to own a car but need one occasionally. This segment is expected to grow further with autonomous and electric shared fleets.
By End User: Individual consumers are the largest end-user group in Germany, accounting for the majority of passenger car purchases. German consumers are known for being brand-loyal, quality-conscious, and willing to pay a premium for safety, performance, and technology. Fleet operators are the second largest end-user group and are very influential in Germany. Large leasing companies, rental companies, logistics firms, and delivery companies buy vehicles in bulk and have a major impact on which models succeed in the market. Government is also an important end-user, buying vehicles for police, fire services, municipal transport, and public administration. The German government is now mandating that its own fleet should shift to electric vehicles to set an example. Corporates and enterprises form the fourth major end-user group, mainly through company car programmes. Many German companies provide cars to their employees as a benefit, and these company cars are usually premium models from BMW, Mercedes, or Audi. This corporate demand plays a huge role in keeping premium car sales high in Germany.
Automotive Market in Germany Regional Analysis
Baden-Württemberg is the most dominant region in the Germany automotive market when it comes to value, premium manufacturing, innovation and supplier strength. This region, centred around Stuttgart, is home to Mercedes-Benz and Porsche, two of the most profitable luxury brands in the world. It is not only about car assembly, the real dominance of Baden-Württemberg comes from its complete ecosystem. Companies like Bosch, Mahle, ZF and hundreds of specialised Tier-1 and Tier-2 suppliers are based here, which means that research, engineering, software, powertrain and component development all happen in this one region. Stuttgart alone accounts for a very large share of Germany's automotive R&D spending and patent filings. Because Mercedes-Benz and Porsche focus on high-margin luxury and performance cars, the revenue generated per vehicle from this region is much higher than any other region in Germany. In simple terms, if Germany earns its reputation from premium engineering, a major part of that reputation is built in Baden-Württemberg.
Bavaria is the second most dominant region and the strongest challenger to Baden-Württemberg. Centred around Munich, Ingolstadt and Regensburg, Bavaria is home to BMW and Audi, two global premium brands. Munich is the headquarters of BMW and also a major hub for software, autonomous driving and electric mobility research. Ingolstadt is the headquarters and main production centre for Audi. Regensburg, Dingolfing and Landshut are also major production and component hubs. Bavaria dominates in terms of premium car production volume, brand value and employment in the premium segment. The state government has also invested heavily in EV charging, hydrogen research and AI for mobility, which has made Bavaria a key region for future mobility. In terms of overall automotive turnover and employment, Bavaria and Baden-Württemberg together control more than half of the German automotive industry, and these two southern states are clearly the dominant powerhouses.
Lower Saxony is the third dominant region and it is the leader in terms of pure production volume. Wolfsburg in Lower Saxony is home to the headquarters of the Volkswagen Group, the largest carmaker in Germany and Europe, and it also hosts the largest car manufacturing plant in Europe. Because Volkswagen sells in the mass-market and volume segment, the number of cars produced in Lower Saxony is higher than in any other state. The Zwickau plant is in Saxony, but the strategic control, design and decision-making for Volkswagen still sits in Wolfsburg. Hanover in Lower Saxony is also important for commercial vehicles, with Volkswagen Commercial Vehicles and Continental having a strong presence. So while Baden-Württemberg and Bavaria dominate in value and premium image, Lower Saxony dominates in scale, volume and mass-market influence. Without Lower Saxony, Germany would not be the volume leader in Europe.
North Rhine-Westphalia is dominant in terms of domestic demand, market size and logistics rather than in manufacturing. It is the most populous state in Germany with large cities like Cologne, Düsseldorf, Dortmund and Essen. Because of this large population, car sales, dealership networks, leasing companies, fleet operators and aftermarket businesses are strongest here. Cologne is also important because Ford has its European EV production plant there, where the new Explorer EV is produced. The region also acts as a logistics gateway for automotive parts moving between Germany, Netherlands and Belgium. While it does not have a German OEM headquartered there like Bavaria or Baden-Württemberg, its power lies in consumption, distribution and commercial vehicle demand.
Saxony has emerged as the fastest-growing automotive region in Germany, especially for electric vehicles. Leipzig is home to BMW’s plant and Porsche’s plant, while Zwickau is home to Volkswagen’s first fully dedicated EV plant in Germany where the ID.3, ID.4 and other MEB-based models are produced. Dresden has become a semiconductor hub with Infineon, GlobalFoundries and Bosch, which is critical for EV, ADAS and connected car technology. Because of lower land and labour costs compared to southern Germany, Saxony is attracting new battery, semiconductor and supplier investments. It is not yet as dominant as the southern states, but it is the region that is shaping Germany’s EV future.Hesse and Eastern Germany play supporting but strategically important roles.
Hesse, with Rüsselsheim, is home to Opel under Stellantis and focuses on affordable mass-market cars and electric models like the Corsa-e. Eastern Germany, especially Brandenburg, has become important after Tesla opened its Gigafactory Berlin-Brandenburg in Grünheide. This plant produces the Model Y for the whole European market and has put Eastern Germany on the global automotive map. Thuringia and Saxony-Anhalt are also attracting battery and supplier plants.
Automotive Market in Germany Competitive Landscape
The competitive landscape in Germany is highly intense, although it is still dominated by German OEMs. The Volkswagen Group is the market leader, with brands such as Volkswagen, Audi, Porsche, Skoda, and Seat, and it holds the largest market share in the country. Volkswagen was one of the earliest to invest heavily in electric vehicles and launched the ID. series to lead the EV transition. The BMW Group is the leader in the premium segment with BMW, MINI, and Rolls-Royce, and it has received a strong response for its electric models such as the iX, i4, and iX1. The Mercedes-Benz Group is the leader in the luxury segment, known for the S-Class and E-Class, and is now focusing on luxury electric vehicles such as the EQE and EQS. Below these leaders, Opel under Stellantis is strong in the mass-market segment with affordable electric models such as the Corsa-e and Astra Electric.
Ford Germany has shifted its focus towards commercial vehicles and the Explorer EV produced in Cologne. Tesla has made a direct entry into the German market with its Gigafactory in Berlin-Brandenburg, and its Model Y has become one of the best-selling EVs in Germany. In recent years, Chinese companies such as BYD, NIO, and XPeng have also entered the German market aggressively, offering feature-rich EVs at lower prices and putting pressure on German brands. To respond to this competition, German companies are investing heavily in new EV platforms, battery technology, software joint ventures such as Cariad and the Rivian JV, charging networks, and autonomous driving. In the coming years, the companies that can offer affordable EVs, strong software, and sustainable production will lead the German automotive market.
Automotive Market in Germany Recent Developments:
| Date | Company | Development | Impact |
|---|---|---|---|
| 25 August 2026 | mobile.de | mobile.de signed a definitive agreement to acquire Carwow Germany from Carwow Group to expand its digital car-buying and leasing platform in Germany. | The transaction strengthens online vehicle marketplace consolidation by integrating new-car configuration, leasing, and dealer stock-sourcing capabilities for German consumers and OEMs. |
| 12 October 2026 | Schaeffler | Schaeffler and Qorix entered into a strategic partnership in Germany to co-develop and market software-based platform solutions for software-defined vehicles (SDVs). | The collaboration accelerates standardized, open-source middleware integration to shorten vehicle development cycles and scale central computing architectures. |
| 05 November 2026 | Continental | Continental received original-equipment approval from Volkswagen to supply EcoContact 7, WinterContact TS 870 P, and AllSeasonContact 2 tires for the all-electric ID. Cross compact SUV. | The factory fitment supports lower aerodynamic drag and reduced rolling noise for electric vehicle efficiency across European markets. |
| 12 November 2026 | Mercedes-Benz | Mercedes-Benz froze all further capital investment in its German manufacturing facilities amid stalled labor-cost negotiations and elevated domestic production expenses. | The investment freeze places cost competitiveness and domestic plant capacity under heightened scrutiny across Germany's automotive production network. |
| 16 November 2026 | Tesla | Tesla announced plans to invest approximately €3 billion to build an additional production hall and expand capacity at its Grünheide plant in Germany for Cybercab manufacturing. | The planned expansion targets up to 1 million Cybercab units annually starting in 2029, boosting autonomous vehicle manufacturing scale in Germany. |
Automotive Market in Germany Scope: Inquire before buying
| Automotive Market in Germany | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | US $ 485.94 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 4% | Market Size in 2034: | US $ 691.64 Bn. |
| Segments Covered: | By Vehicle Type | Two-Wheeler Three-Wheeler Passenger Cars Hatchbacks Sedans SUVs Light Commercial Vehicles (LCVs) Vans Pickup Trucks Heavy Commercial Vehicles (HCVs) Heavy Trucks Buses & Coaches Off-Highway Vehicles Others |
|
| By Propulsion Type | Internal Combustion Engine (ICE) Vehicles Battery Electric Vehicles (BEVs) Hybrid Electric Vehicles (HEVs) Plug-in Hybrid Electric Vehicles (PHEVs) Fuel Cell Electric Vehicles (FCEVs) |
||
| By Fuel Type | Gasoline Diesel Electric Compressed Natural Gas (CNG) Liquefied Petroleum Gas (LPG) Others |
||
| By Transmission Type | Manual Transmission Automatic Transmission Semi-Automatic / Dual-Clutch Transmission |
||
| By Sales Channel | OEM / New Vehicle Sales Aftermarket / Used Vehicle Sales |
||
| By Application | Personal Mobility Commercial & Logistics Public Transport Shared Mobility / Mobility Services |
||
| By End User | Individual Consumers Fleet Operators Government Corporates & Enterprises |
||
Germany Automotive Market Key Players
1. Volkswagen Group
2. Mercedes-Benz Group AG
3. BMW Group
4. Porsche AG
5. Audi AG
6. Opel Automobile GmbH
7. MAN Truck & Bus SE
8. Daimler Truck AG
9. Schmitz Cargobull AG
10. Krone Commercial Vehicle Group
11. Iveco Magirus AG
12. Isuzu
13. Solaris
14. Lucid
15. Ford
16. Toyota
17. Hyundai
18. Kia
19. Renault
20. Nissan
21. Volvo Cars
22. Volvo Trucks
23. Scania
24. DAF Trucks
25. Tesla
26. BYD
27. Temsa
Others
Frequently Asked Questions:
1. Which region has the largest share in Market?
Ans: Baden-Württemberg region held the highest share in 2025.
2. What is the growth rate of Market?
Ans: The Global Automotive Market is growing at a CAGR of 4% during forecasting period 2026-2034.
3. What is scope of the Global Automotive market report?
Ans: Global Automotive Market report helps with the PESTEL, PORTER, COVID-19 Impact analysis, Recommendations for Investors & Leaders, and market estimation of the forecast period.
4. What is the study period of this market?
Ans: The Global Automotive Market is studied from 2020 to 2034.