Agrigenomics Market Size by Sequencer, Objectives, Application, Region – Segment-Level Market Assessment, Growth Opportunity Analysis, Competitive Mapping & Forecast to 2034

9.7%
CAGR (2026-2034)
5.24  USD Bn.
Forecast Market Size
305
Report Pages
138
Market Tables

Overview

Global Agrigenomics Market was valued at USD 5.24 Bn in 2025 and is expected to reach USD 12.05 Bn by 2034, growing at a CAGR of 9.7% during the forecast period.

Agrigenomics Market Overview:

Agrigenomics is the study of how genes influence the genetic makeup of crops and livestock. Agriculture can gain financially from genomics by elevating the sustainability and productivity of livestock and crop production. The Agrigenomics business is growing due to significant advancements in technology that have led to a switch from single-gene sequencing to whole-genome sequencing, as well as an uptick in genome composition and gene function studies. The increased use of genome sequencing in livestock not only allows for the study of parent lineage but also aids in the understanding of infectious organisms like bacteria and viruses that infest or dwell in them.

Agrigenomics Market Growth and Share Analysis
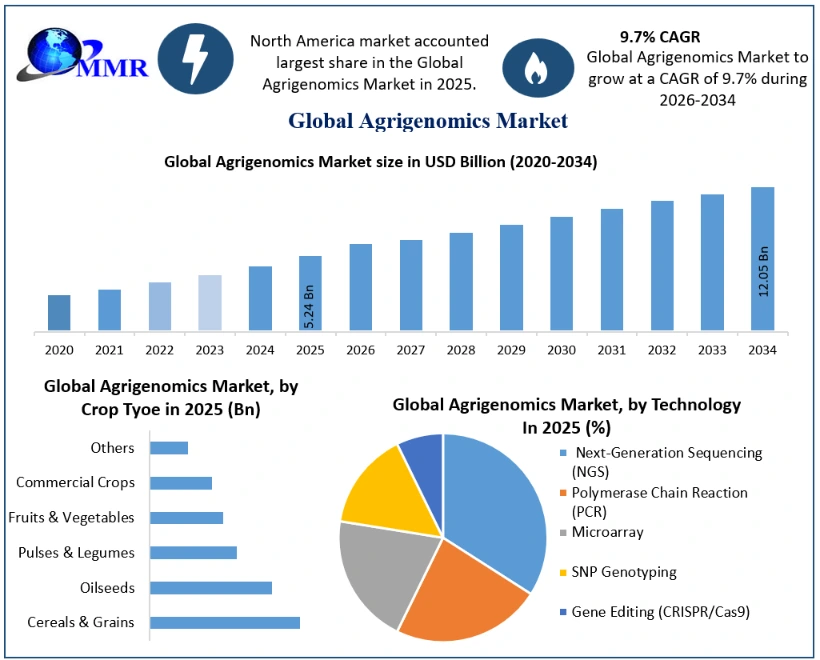
Agrigenomics Market GrowthTo know about the Research Methodology :- Request Free Sample Report

Agrigenomics Market Dynamics:

Tools and techniques for advanced genome analysis are driving the growth of the Agrigenomics market.

Rapid breakthroughs in the functional genomics sector, such as the adoption of massively parallel sequencing technology and the creation of methods to efficiently study cellular behavior at the molecular level, are driving the worldwide Agrigenomics market. In terms of applied genomics in agriculture, molecular marker-assisted crop breeding has outperformed traditional breeding programs in terms of crop selection scope, speed, and efficiency. Advanced genome characterization tools have revealed that crops can have higher quality and yield while using fewer fertilizers, herbicides, and water.

The Agrigenomics market's growth is dependent on expanding the application range beyond food and nutrition security. Genome analysis tools and techniques can also help with food safety issues like spoilage and contamination, adulteration, and economic fraud, as well as traceability across the full supply chain from farm to fork. By providing unparalleled access to genomic information, New Breeding Techniques (NBT) based on applied genetics have transformed breeding techniques for crops and livestock. Genomics has also provided information on the biological status of critical resources like fisheries, crops, and cattle health.

The Agrigenomics sector's technology constraints are thwarting its current full-fledged expansion and compromising its future growth trajectories. Overcoming species and genotype-dependent transformation, particularly in crops, hence widening the scope of targeted agricultural enhancements by genome editing, and obtaining high-efficiency base replacement by changing the focus away from targeted mutagenesis are some of the hurdles. Plants' superior and desirable features are frequently influenced by genetic variants in SNPs (single nucleotide polymorphisms). The primary stumbling block is quickly identifying and integrating all of these features in elite cultivars.

Agrigenomics Market Segment Analysis:

In 2025, the Illumina HiSeq Family segment holds the highest demand in the agrigenomics market due to its high-throughput sequencing capability, accuracy, and cost-effectiveness for large-scale genomic studies. These sequencers are widely used in crop and livestock genome mapping, enabling researchers to analyze genetic variations and accelerate breeding programs. PacBio Sequencers are gaining increasing adoption because of their ability to generate long-read sequences, which are valuable for identifying complex genomic structures and structural variations in plants and animals. Sanger Sequencing continues to be used for validation and smaller research applications due to its high accuracy, while SOLiD Sequencers have relatively limited adoption compared to newer sequencing technologies.

Based on Objectives, DNA / RNA Sequencing represents the most demanded segment in 2025 as it plays a crucial role in understanding genetic variations, identifying desirable traits, and improving crop productivity and livestock quality. Researchers increasingly rely on sequencing technologies to study plant resistance to diseases, environmental adaptability, and productivity enhancement. Genotyping and Marker-Assisted Selection are also widely adopted for accelerating breeding programs and improving genetic traits in agricultural species. Meanwhile, DNA Extraction & Purification forms the foundational step in genomic analysis, supporting all downstream applications. Gene Expression Profiling and GMO / Trait Purity Testing are gaining importance for regulatory compliance, quality control, and advanced agricultural research.

Agrigenomics Market Regional Insights:

Based on Region, North America dominates the global agrigenomics market in 2025 due to strong investments in agricultural biotechnology, advanced research infrastructure, and widespread adoption of genomic technologies in crop and livestock research. The region benefits from the presence of major genomics companies and significant funding for agricultural innovation. Europe follows with strong growth driven by increasing research initiatives focused on sustainable agriculture and genetic improvement programs. Asia Pacific is expected to witness the fastest growth due to rising food demand, expanding agricultural biotechnology research, and increasing adoption of genomic technologies in countries such as China, India, and Japan. Meanwhile, South America, Middle East, and Africa show gradual market expansion driven by increasing interest in improving crop productivity and livestock breeding efficiency through genomic technologies.

The objective of the report is to present a comprehensive analysis of the Agrigenomics Market to the stakeholders in the industry. The past and current status of the industry with the forecasted market size and trends are presented in the report with the analysis of complicated data in simple language. The report covers all the aspects of the industry with a dedicated study of key players that include market leaders, followers, and new entrants.

PORTER, SVOR, PESTEL analysis with the potential impact of micro-economic factors of the market have been presented in the report. External as well as internal factors that are supposed to affect the business positively or negatively have been analyzed, which will give a clear futuristic view of the industry to the decision-makers.

The report also helps in understanding the Agrigenomics Market dynamics, structure by analyzing the market segments and projecting the Agrigenomics Market size. Clear representation of competitive analysis of key players by Grade, price, financial position, Grade portfolio, growth strategies, and regional presence in the Agrigenomics Market make the report investor’s guide.

Agrigenomics Market Recent Developments:

Exact Date Company Development Impact
26 February 2026 Illumina, Inc. Illumina unveiled its NovaSeq X innovation roadmap, specifically highlighting its 2026 focus on multiomic data visualization for large-scale plant and animal sequencing projects. This advancement enables researchers to streamline analysis of complex agricultural genomes, significantly reducing the time required to correlate genetic markers with productive traits.
09 January 2026 Bayer AG Bayer officially announced the commercial launch of Baya Solara, an innovative strawberry variety developed through advanced genomic selection and molecular breeding. This launch demonstrates the successful commercialization of genomic insights to deliver fruits with enhanced shelf-life and disease resistance without traditional genetic modification.
08 January 2026 seqWell The company launched the AgriPrep™ Library Prep Kit, a specialized solution designed for low-coverage whole genome sequencing (WGS) in high-throughput agricultural applications. This product addresses the market need for cost-effective genotyping, allowing breeders to perform large-scale population screening at a fraction of previous costs.
20 October 2025 10x Genomics, Inc. 10x Genomics launched its Next-Generation Flex Assay, featuring automation-compatible, plate-based multiplexing for high-scale functional genomics. The assay enables scalable CRISPR screens in plant cells, empowering agritech firms to accelerate trait discovery by testing thousands of genetic variations simultaneously.
15 May 2025 QIAGEN QIAGEN signed a definitive agreement to acquire Genoox, an AI-driven software provider, to integrate the Franklin cloud-based platform into its digital insights portfolio. The acquisition enhances clinical-grade data interpretation for agrigenomics, allowing for more robust pathogen detection and genetic purity testing in global seed supply chains.
11 February 2025 Roche Roche introduced its proprietary Sequencing by Expansion (SBX) technology, a novel NGS chemistry designed for ultra-rapid, high-throughput sequencing. This technology provides enhanced scalability for diverse agricultural applications, particularly in livestock genomics where rapid turnaround of genetic merit data is critical.

Agrigenomics Market Scope: Inquire before buying

Global Agrigenomics Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 5.24 USD Bn
Forecast Period 2026-2034 CAGR: 9.7% Market Size in 2034: 12.05 USD Bn
Segments Covered: by Breeding Trait Yield Improvement
Disease Resistance
Pest Resistance
Abiotic Stress Tolerance
Herbicide Tolerance
Nutritional & Quality Improvement
Others
by Objectives DNA Extraction & Purification
DNA / RNA Sequencing
Genotyping
Gene Expression Profiling
Marker-Assisted Selection
GMO / Trait Purity Testing
by Crop Type Cereals & Grains
Oilseeds
Pulses & Legumes
Fruits & Vegetables
Commercial Crops
Others
by Technology Next-Generation Sequencing (NGS)
Polymerase Chain Reaction (PCR)
Microarray
SNP Genotyping
Gene Editing (CRISPR/Cas9)
by End User Agricultural Biotechnology Companies
Academic & Research Institutes
Contract Research Organizations (CROs)
Seed Companies
Animal Breeding Companies
Government Research Agencies

Agrigenomics Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)

Key Players /Competitor Profiles Covered in the Global Agrigenomics Market Report from a Strategic Perspective

North America:
1. Thermo Fisher Scientific
2. Illumina
3. Agilent Technologies
4. Pacific Biosciences (PacBio)
5. Bio-Rad Laboratories
6. Revvity
7. Azenta Life Sciences / GENEWIZ
8. Standard BioTools
9. AgriPlex Genomics
10. Zymo Research
11. Corteva Agriscience
12. Inari Agriculture
13. Cibus
14. Benson Hill
15. Daicel Arbor Biosciences
Others

Europe:
16. Eurofins Scientific
17. QIAGEN
18. LGC Biosearch Technologies
19. Oxford Nanopore Technologies
20. KeyGene
21. IGA Technology Services
22. SGS
23. Bayer Crop Science
24. BASF Agricultural Solutions
25. KWS SAAT
26. Limagrain
27. Syngenta Group
Others

Asia-Pacific:
28. BGI Genomics
29. Novogene
30. Celemics
31. AgriGenome Labs
32. SciGenom Labs
33. Genotypic Technology
Others

Rest of World:
34. NRGene Technologies
35. Evogene
Others

Table of Contents

1. SECTION A – AGRIGENOMICS MARKET FOR PLANT BREEDING INTRODUCTION 1.1 Executive Market Landscape and Industry Overview 1.1.1 Agrigenomics Market for Plant breeding size (Value USD Mn. and Volume (Kilotons)) estimation and growth outlook (2025–2034) 1.1.2 Comprehensive definition of the Agrigenomics industry ecosystem 1.1.3 Scope boundaries covering production technologies, infrastructure, and end-use applications 1.1.4 Competitive Landscape Overview: Brands, Participants, Regional Specialists, and New Entrants in the Global Agrigenomics Market for Plant breeding 1.2 Agrigenomics Market for Plant breeding Dynamics 1.2.1 Agrigenomics Market for Plant breeding Trends 1.2.2 Agrigenomics Market for Plant breeding 1.2.3 Drivers 1.2.4 Restraints 1.2.5 Opportunities 1.2.6 Challenges 1.2.7 PORTER’s Five Forces Analysis 1.2.7.1 Supplier power 1.2.7.2 Buyer power 1.2.7.3 Threat of substitutes 1.2.7.4 Threat of new entrants 1.2.7.5 Competitive rivalry 1.2.8 PESTLE Analysis 1.3 Plant Breeding Genomics & Molecular Breeding Landscape 1.3.1 Evolution of Genomics-Enabled Plant Breeding 1.3.2 Role of Molecular Markers in Crop Improvement 1.3.3 Marker-Assisted Selection (MAS) Adoption Landscape 1.3.4 Genomic Selection and Predictive Breeding Approaches 1.3.5 DNA Sequencing and Genotyping Applications in Breeding Programs 1.3.6 Trait Discovery and Genetic Mapping Technologies 1.3.7 Germplasm Characterization and Genetic Diversity Analysis 1.3.8 Molecular Breeding Pipeline and Workflow Assessment 1.3.9 Integration of Bioinformatics in Plant Breeding Decisions 1.4 Regulatory Framework and Compliance Requirements Overview 1.4.1 Global Regulatory Landscape for Agrigenomics Applications 1.4.2 Seed & Crop Genetic Testing Regulations 1.4.3 GMO and Gene Editing Regulatory Framework 1.4.4 NGS and Genotyping Data Compliance Requirements 1.4.5 Plant Variety Protection & Intellectual Property Regulations 1.4.6 Country-wise Approval & Compliance Requirements 1.4.7 Biosafety and Environmental Regulations 1.4.8 Data Management, Genomic Data Privacy & Standards 1.5 Supply Chain Analysis Overview 1.5.1 Agrigenomics Value Chain Mapping 1.5.2 Sample Collection & Transportation Workflow 1.5.3 DNA/RNA Extraction and Sample Preparation 1.5.4 Sequencing & Genotyping Service Supply Chain 1.5.5 Bioinformatics & Data Processing Ecosystem 1.5.6 Technology Provider and Equipment Supplier Network 1.5.7 Seed Company & Breeding Organization Integration 1.5.8 Supply Chain Challenges and Optimization Opportunities 1.6 Pricing Analysis and Cost Structure Evaluation (2025) 1.6.1 Agrigenomics Service Pricing Benchmarking 1.6.2 Sequencing Cost Analysis by Technology 1.6.3 Genotyping & SNP Testing Cost Structure 1.6.4 Sample Preparation and Laboratory Processing Costs 1.6.5 Bioinformatics & Data Analysis Pricing 1.6.6 Cost Comparison: Conventional vs. Genomics-Assisted Breeding 1.6.7 Pricing Differences by Crop Type and Application 1.6.8 Key Factors Influencing Agrigenomics Service Costs 1.7 Investment and Funding Trends in Agrigenomics Sector 1.7.1 Global Investment Landscape in Agricultural Genomics 1.7.2 Venture Capital & Private Equity Activity 1.7.3 Government Funding & Research Grants 1.7.4 Seed Technology and Genomics Startup Investments 1.7.5 Investments in NGS, AI & Bioinformatics Platforms 1.7.6 Gene Editing and Molecular Breeding Funding Trends 1.8 Innovation Trends Shaping Future Agrigenomics Development 1.8.1 AI-Driven Genomic Data Analysis in Plant Breeding 1.8.2 Multi-Omics Integration for Crop Improvement 1.8.3 Digital Breeding Platforms and Predictive Analytics 1.8.4 Long-Read Sequencing Advancements 1.8.5 Climate-Resilient Crop Development Using Genomics 1.8.6 Next-Generation Breeding Platform Innovations 1.9 Genotyping & High-Throughput SNP Analysis 1.9.1 SNP Genotyping Technology Adoption 1.9.2 High-Throughput Genotyping Platforms Overview 1.9.3 Genotyping-by-Sequencing (GBS) Applications 1.9.4 Marker Discovery and Validation 1.9.5 SNP-Based Trait Identification 1.9.6 Population Genotyping & Genetic Diversity Analysis 1.10 Demand and Consumption Pattern Analysis (2025) 1.10.1 Agrigenomics Testing Demand by Application 1.10.2 Crop-wise Genomics Testing Consumption 1.10.3 Demand from Seed Companies and Breeding Organizations 1.10.4 Regional Adoption Patterns 1.10.5 Genotyping vs. Sequencing Demand Comparison 1.10.6 Research vs. Commercial Usage Trends 1.10.7 Sample Processing Volume Analysis 1.11 Genomic Selection & Breeding Value Prediction 1.11.1 Genomic Selection Adoption in Crop Breeding 1.11.2 Genome-Wide Marker-Based Prediction Models 1.11.3 Breeding Value Estimation Approaches 1.11.4 Integration of Phenotypic and Genotypic Data 1.11.5 AI-Based Predictive Breeding Models 1.11.6 Selection Accuracy Improvement 1.12 NGS Applications in Plant Breeding 1.12.1 Whole Genome Sequencing Applications 1.12.2 Transcriptome Sequencing in Crop Research 1.12.3 Targeted Sequencing for Trait Identification 1.12.4 Genomic-Assisted Breeding Programs 1.12.5 Mutation Detection and Variant Discovery 1.12.6 Germplasm Characterization 1.13 Gene Editing & CRISPR/Cas Applications 1.13.1 CRISPR-Based Crop Trait Improvement 1.13.2 Gene Knockout and Gene Modification Applications 1.13.3 Disease and Stress Resistance Development 1.13.4 Yield and Quality Trait Enhancement 1.13.5 Regulatory Landscape for Gene-Edited Crops 1.14 Agrigenomics Technology Demand: Market Share and YoY Growth (2025–2034) 1.14.1 Next-Generation Sequencing in Global Agrigenomics Market for Plant breeding Share (%) By Region 2025 1.14.1.1 North America 1.14.1.2 Europe 1.14.1.3 Asia Pacific 1.14.1.4 Middle East and Africa 1.14.1.5 South America 1.14.2 NGS Adoption Growth Assessment 1.14.3 Genotyping Platform Demand Trends 1.14.4 PCR and Molecular Testing Demand 1.14.5 Gene Editing Technology Growth 1.15 Growth of Agrigenomics By End User (2025–2034) 1.15.1 Seed Company Adoption Growth 1.15.2 Agricultural Biotechnology Company Expansion 1.15.3 Research Institute Genomics Usage 1.15.4 Contract Research Organization Demand 1.15.5 Government Agricultural Research Investment 1.15.6 Commercial Breeding Program Adoption 1.16 Adoption & Deployment Analysis 1.16.1 Global Adoption of Agrigenomics in Plant Breeding 1.16.2 Adoption Rate Across Seed Companies and Research Institutions 1.16.3 Commercial vs. Research Deployment Trends 1.16.4 Regional Deployment Patterns 1.16.5 Technology Adoption by Breeding Programs 1.16.6 Barriers to Agrigenomics Implementation 1.17 Consumer Preference and Buying Behavior Analysis 1.17.1 Seed Company Technology Selection Criteria 1.17.2 Preference for Sequencing vs. Genotyping Solutions 1.17.3 Cost vs. Accuracy Trade-off Analysis 1.17.4 Demand for Faster Breeding Cycles 1.17.5 Preference for Integrated Genomics Platforms 1.18 Crop-wise Agrigenomics Adoption & Testing Volume 1.18.1 Crop-wise Genomics Adoption Level 1.18.2 Sample Testing Volume by Crop Type 1.18.3 Sequencing Demand Across Crop Categories 1.18.4 Genotyping Utilization by Breeding Programs 1.18.5 Crop-specific Trait Analysis Requirements 1.19 Trait Discovery, Mapping & Validation 1.19.1 Genomic Trait Discovery Approaches 1.19.2 Quantitative Trait Loci (QTL) Mapping 1.19.3 Genome-Wide Association Studies (GWAS) 1.19.4 Disease Resistance Trait Identification 1.19.5 Yield and Quality Trait Validation 1.19.6 Stress Tolerance Trait Mapping 1.20 Sequencing & Genotyping Platform Benchmarking 1.20.1 NGS Platform Comparison 1.20.2 Short-read vs. Long-read Sequencing Assessment 1.20.3 Illumina vs. PacBio vs. Oxford Nanopore Benchmarking 1.20.4 SNP Genotyping Platform Comparison 1.20.5 Accuracy, Throughput and Cost Assessment 1.20.6 Platform Adoption by Breeding Application 1.21 Breeding Trait Analysis – Yield, Disease, Pest & Stress Resistance 1.21.1 Yield Improvement Genomics 1.21.2 Disease Resistance Trait Development 1.21.3 Pest Resistance Breeding Programs 1.21.4 Drought Tolerance Genomics 1.21.5 Heat and Cold Stress Resistance 1.21.6 Herbicide Tolerance Development 1.22 Comparative Analysis: Crop Type in Global Agrigenomics Market for Plant breeding 1.22.1 Cereals & Grains Genomics Adoption 1.22.2 Oilseeds Genomics Adoption 1.22.3 Pulses & Legumes Genomics Adoption 1.22.4 Fruits & Vegetables Genomics Adoption 1.22.5 Commercial Crop Genomics Adoption 1.22.6 Crop-wise Technology Utilization 1.22.7 Crop-specific Testing Requirements 1.22.8 Growth Potential Across Crop Segments 1.23 Plant Breeding Sample/Test Volume Analysis 1.23.1 Total Genomic Samples Processed 1.23.2 Testing Volume by Technology Type 1.23.3 Sample Volume by Crop Category 1.23.4 Commercial Breeding Testing Demand 1.23.5 Research Sample Processing Trends 1.23.6 High-throughput Testing Capacity Analysis 1.23.7 Sample Processing Workflow Assessment 1.23.8 Volume Growth Forecast Analysis 1.24 Qualification, Certification and Time-to-Market Impact 1.24.1 Seed Quality Certification Requirements 1.24.2 Regulatory Qualification Processes 1.24.3 Genetic Purity Certification Impact 1.24.4 Breeding Validation Requirements 1.24.5 Time Reduction Through Genomics Adoption 1.24.6 Conventional vs. Genomics-assisted Breeding Timeline 1.25 Long-Term Market Evolution and Structural Shifts 1.25.1 Transition from Conventional Breeding to Genomics-Driven Breeding 1.25.2 Expansion of AI-Enabled Predictive Breeding Platforms 1.25.3 Increasing Adoption of Genomic Selection Technologies 1.25.4 Shift Toward High-Throughput Sequencing and Automation 1.25.5 Integration of Multi-Omics Approaches in Crop Improvement 1.25.6 Growth of CRISPR and Precision Breeding Technologies 1.25.7 Increasing Role of Bioinformatics and Data Analytics 1.26 Agrigenomics Market for Plant breeding: Market Size and Forecast by Segmentation (by Value USD) (2025–2034) 1.26.1 Agrigenomics Market for Plant breeding Size and Forecast, By Technology 1.26.1.1 Next-Generation Sequencing 1.26.1.2 PCR & qPCR 1.26.1.3 Microarray 1.26.1.4 Genotyping Platforms 1.26.1.5 Capillary Electrophoresis 1.26.1.6 Gene Editing 1.26.1.7 Others 1.26.2 Agrigenomics Market for Plant breeding Size and Forecast, By Objective 1.26.2.1 Genotyping & Genetic Characterization 1.26.2.2 Marker-Assisted Selection 1.26.2.3 Genomic Selection 1.26.2.4 Trait Discovery & Mapping 1.26.2.5 Gene Expression Analysis 1.26.2.6 Genetic & Trait Purity Testing 1.26.2.7 Others 1.26.3 Agrigenomics Market for Plant breeding Size and Forecast, By Breeding Trait 1.26.3.1 Yield Improvement 1.26.3.2 Disease Resistance 1.26.3.3 Pest Resistance 1.26.3.4 Abiotic Stress Tolerance 1.26.3.5 Herbicide Tolerance 1.26.3.6 Nutritional & Quality Improvement 1.26.3.7 Others 1.26.4 Agrigenomics Market for Plant breeding Size and Forecast, By Crop Type 1.26.4.1 Cereals & Grains 1.26.4.2 Oilseeds 1.26.4.3 Pulses & Legumes 1.26.4.4 Fruits & Vegetables 1.26.4.5 Commercial Crops 1.26.4.6 Others 1.26.5 Agrigenomics Market for Plant breeding Size and Forecast, By End User 1.26.5.1 Seed & Plant Breeding Companies 1.26.5.2 Agricultural Biotechnology Companies 1.26.5.3 Research & Academic Institutions 1.26.5.4 Contract Research Organizations 1.26.5.5 Government Agricultural Research Agencies 1.26.6 Agrigenomics Market for Plant breeding Size and Forecast, By Region 1.26.6.1 North America 1.26.6.1.1 United States 1.26.6.1.2 Canada 1.26.6.1.3 Mexico 1.26.6.2 Europe 1.26.6.2.1 United Kingdom 1.26.6.2.2 France 1.26.6.2.3 Germany 1.26.6.2.4 Italy 1.26.6.2.5 Spain 1.26.6.2.6 Sweden 1.26.6.2.7 Russia 1.26.6.2.8 Rest of Europe 1.26.6.3 Asia Pacific 1.26.6.3.1 China 1.26.6.3.2 S. Korea 1.26.6.3.3 India 1.26.6.3.4 Japan 1.26.6.3.5 Australia 1.26.6.3.6 Indonesia 1.26.6.3.7 Philippines 1.26.6.3.8 Malaysia 1.26.6.3.9 Vietnam 1.26.6.3.10 Thailand 1.26.6.3.11 Rest of Asia Pacific 1.26.6.4 Middle East and Africa 1.26.6.4.1 South Africa 1.26.6.4.2 Bahrain 1.26.6.4.3 Kuwait 1.26.6.4.4 Oman 1.26.6.4.5 Qatar 1.26.6.4.6 Saudi Arabia 1.26.6.4.7 United Arab Emirates (UAE) 1.26.6.4.8 Rest of MEA 1.26.6.5 South America 1.26.6.5.1 Brazil 1.26.6.5.2 Argentina 1.26.6.5.3 Chile 1.26.6.5.4 Colombia 1.26.6.5.5 Rest Of South America 2. SECTION B – COMPETITIVE INTELLIGENCE & INDUSTRIAL ECOSYSTEM 2.1 Company Profiles: Key Players 2.1.1 Overview 2.1.2 Business Portfolio 2.1.3 Financial Overview 2.1.4 SWOT Analysis 2.1.5 Strategic Analysis 2.1.6 Recent Developments 2.1.7 North America 2.1.7.1 Thermo Fisher Scientific 2.1.7.2 Illumina 2.1.7.3 Agilent Technologies 2.1.7.4 Pacific Biosciences (PacBio) 2.1.7.5 Bio-Rad Laboratories 2.1.7.6 Revvity 2.1.7.7 Azenta Life Sciences / GENEWIZ 2.1.7.8 Standard BioTools 2.1.7.9 AgriPlex Genomics 2.1.7.10 Zymo Research 2.1.7.11 Corteva Agriscience 2.1.7.12 Inari Agriculture 2.1.7.13 Cibus 2.1.7.14 Benson Hill 2.1.7.15 Daicel Arbor Biosciences 2.1.7.16 Others 2.1.8 Europe 2.1.8.1 Eurofins Scientific 2.1.8.2 QIAGEN 2.1.8.3 LGC Biosearch Technologies 2.1.8.4 Oxford Nanopore Technologies 2.1.8.5 KeyGene 2.1.8.6 IGA Technology Services 2.1.8.7 SGS 2.1.8.8 Bayer Crop Science 2.1.8.9 BASF Agricultural Solutions 2.1.8.10 KWS SAAT 2.1.8.11 Limagrain 2.1.8.12 Syngenta Group 2.1.8.13 Others 2.1.9 Asia-Pacific 2.1.9.1 BGI Genomics 2.1.9.2 Novogene 2.1.9.3 Celemics 2.1.9.4 AgriGenome Labs 2.1.9.5 SciGenom Labs 2.1.9.6 Genotypic Technology 2.1.9.7 Others 2.1.10 Rest of World 2.1.10.1 NRGene Technologies 2.1.10.2 Evogene 2.1.10.3 Others 2.2 Competitive Landscape Overview of Key Market Participants 2.2.1 Global Agrigenomics Player Ranking & Competitive Positioning 2.2.2 Leading Technology Providers and Service Companies Analysis 2.2.3 Market Leaders vs. Emerging Agrigenomics Companies 2.2.4 Competitive Strengths and Capability Assessment 2.2.5 Technology Platform Differentiation Analysis 2.2.6 Regional Presence and Market Reach Comparison 2.2.7 Strategic Positioning Matrix of Key Players 2.2.8 Competitive Advantage and Market Opportunity Assessment 2.3 Company Business Strategy and Expansion Approaches 2.3.1 Genomics Technology Development Strategies 2.3.2 Product and Service Portfolio Expansion Plans 2.3.3 Geographic Expansion and Market Entry Strategies 2.3.4 Strategic Partnerships and Collaboration Initiatives 2.3.5 R&D Investment and Innovation Strategies 2.3.6 Acquisition and Alliance Strategies 2.3.7 Seed Company and Research Institution Partnerships 2.3.8 Long-Term Growth and Commercialization Approaches 2.4 Product Portfolio Analysis of Leading Market Players 2.4.1 Genomics Platform and Technology Portfolio Assessment 2.4.2 Sequencing Platform Offerings Analysis 2.4.3 Genotyping and Molecular Breeding Solutions 2.4.4 Marker-Assisted Selection and Genomic Selection Services 2.4.5 Bioinformatics and Data Analytics Capabilities 2.4.6 Crop-Specific Solution Portfolio 2.4.7 Service Offering and Application Benchmarking 2.4.8 Product Portfolio Strengths and Market Gaps 2.5 Revenue Performance and Financial Analysis Overview 2.5.1 Company Revenue Performance Analysis 2.5.2 Agrigenomics Segment Revenue Assessment 2.5.3 Revenue Growth and Business Expansion Trends 2.5.4 R&D Investment and Innovation Spending 2.5.5 Profitability and Financial Strength Assessment 2.5.6 Investment Capacity and Strategic Funding Analysis 2.5.7 Regional Revenue Contribution Overview 2.5.8 Financial Benchmarking Across Key Players 2.6 Future Strategic Outlook of Leading Market Players 2.6.1 Future Technology Development Roadmap 2.6.2 Expansion into Emerging Agricultural Markets 2.6.3 AI and Digital Breeding Integration Strategies 2.6.4 Gene Editing and Precision Breeding Opportunities 2.6.5 New Product and Platform Launch Plans 2.6.6 Strategic Partnership and Collaboration Outlook 2.6.7 Market Leadership Opportunities 2.6.8 Long-Term Competitive Positioning Assessment 3. SECTION C – STRATEGIC RECOMMENDATION 3.1 Key Findings 3.2 Analyst Recommendation 3.3 Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements