
Global Solid Sulfur Market Size by Manufacturing Process, Product Type, End‑User Industry, Application, Region and Forecast 2034
Overview
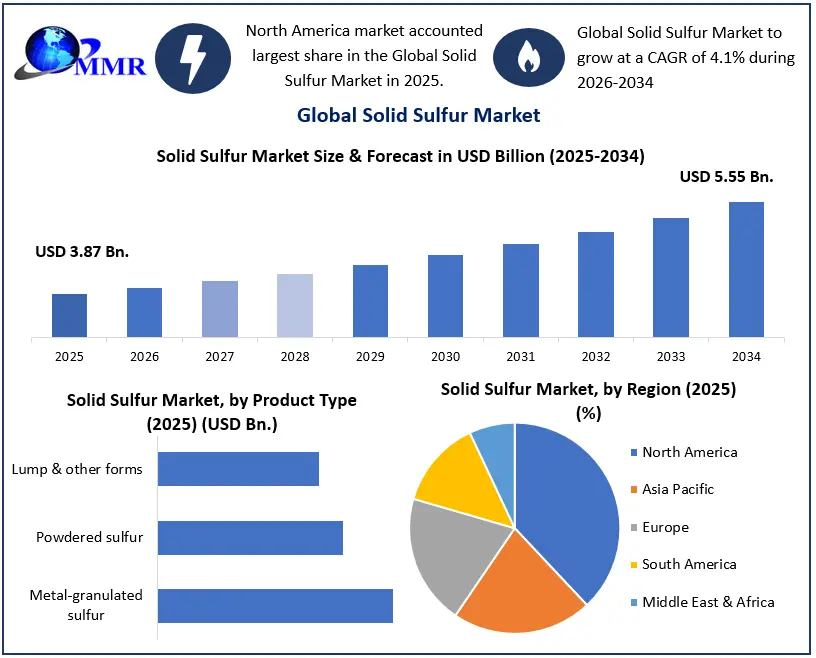
Global Solid Sulfur Market size was valued at USD 3.87 Bn. in 2025, and the total Global Solid Sulfur Market revenue is expected to grow by 4.1% from 2026 to 2034, reaching USD 5.55 Bn.
Solid Sulfur Market Overview:
Sulfur is a naturally occurring element and is the thirteenth most prevalent element in the earth's crust. It is mined in its elemental form, however, the sulfur production in this form has dwindled in recent years. Sulfur is a valuable commodity and an essential element of the global economy used to produce a variety of products such as fertilizers and other chemicals. Elemental solid Sulfur is produced all over the world. The highest output occurs where sour (sulfur-rich) gas and oil are treated and refined. International trade accounts for more than half of elemental sulfur production.
The sulfur industry differs from a variety of prominent modern mineral industries in that the management of surplus sulfur reserves is becoming a more pressing concern than how to maintain long-term production. Unlike other companies that are looking for cost-effective ways to produce a marketable product from diminishing reserves and lower-grade ore, sulfur producers are seeking to discover novel uses for the continuously growing sulfur supply. As environmental concerns grow, the aim is to reduce the environmental impact of mining by recycling mineral resources or adopting more ecologically friendly products. Higher environmental perception leads to increased sulfur supply and lower growth in sulfur demand in many industrial processes.
Solid Sulfur Market Growth and Share Analysis
To know about the Research Methodology :- Request Free Sample Report
Solid Sulfur Market Report Scope:
The Solid Sulfur market is segmented based on Manufacturing Process, Application, and Region. The growth of various segments helps report users in acquiring knowledge of the many growth factors expected to be prevalent throughout the market and develop different strategies to help identify core application areas and the gap in the target market. The report provides an in-depth analysis of the market and contains meaningful insights, facts, historical data, and statistically supported and industry-validated market statistics. It also includes estimates based on an appropriate set of assumptions and methodologies.
A bottom-up approach has been used to estimate the market size. Key Players in the Solid Sulfur market are identified through secondary research and their market revenues are determined through primary and secondary research. Secondary research included a review of annual and financial reports of leading manufacturers, while primary research included interviews with important opinion leaders and industry experts such as skilled front-line personnel, entrepreneurs, and marketing professionals. Some of the leading key players in the global Solid Sulfur market include Chemtrade, Citis SAS, Gazprom, and Jordan Sulfur.
The report is not only a representation of global players but also covers the market holding of local players in each country. Market structure by country with market holding by market leaders, market followers, and local players make this report a comprehensive and insightful industry outlook. The report has covered the mergers and acquisitions, strategic alliances, joint ventures, and partnerships happening in the market by region, by investment, and their strategic intent.
Solid Sulfur Market Dynamics:
A leap towards the eradication of world hunger:- The growing global population and calorie consumption will more than double food demand by 2050. To attain and sustain the level of food supply required to satisfy this demand, global agriculture would need to significantly improve crop yields. Although experts are aware of the nutrients nitrogen (N), phosphorus (P), and potassium (K), few are aware of the importance and significance of sulfur as an agricultural resource. Treatment of sulfur-deficient soils is a cost-effective strategy to increase food and feed production.
The Sulphur Institute conducted field trials in India, where rice is an important food staple for over one billion people. According to research, the introduction of sulfur fertilizer has the potential to improve the per capita food supply by more than 10%. For example, in the North American Corn Belt Sulphur fertilization maximizes maize yields by at least 11%.
Role of sulfur in eco-friendly concrete production:
Concrete is the most commonly used building material in the world, accounting for double the volume of all other building materials combined. A sulfur-based concrete binder is an environmentally friendly alternative to traditional Portland cement for paving stones, walkways, and building foundations. A sulfur binder is created with no water and less heat than Portland cement, leading to net energy savings, lower greenhouse gas emissions, and a diminished environmental footprint. Sulfur innovation may replace up to 30% of asphalt binder in road construction, which is a particularly labor-demanding input in blacktop roadways. Roads and parking lots that are sulfur-enhanced have a longer life cycle.
Negligible and colossal losses from production and processing respectively:
There are attempts in any industrial endeavor to reduce losses during manufacturing and processing to maximize the economic advantage of the operations. This is true in the sulfur mining industry, as companies attempt to maximize sulfur extraction. Sulfur mining varies from more traditional mining processes in ways that minimize losses throughout the Frasch mining process. Since ores are not mechanically treated to get the elemental sulfur product, almost no product is lost during handling. Sulfur leaks may occur in various Frasch plants, although in extremely small amounts that are negligible in comparison to overall sulfur output and environmental implications at particular locations. With the extinction of the Frasch industry in the United States and its severe decline in other nations, these losses to the sulfur industry are insignificant. Recovery of sulfur can be an economic burden rather than an asset in petroleum refining and natural gas processing. The expense of sulfur recovery equipment and operations greatly increases the cost of oil and gas processing. Costs vary greatly depending on location, size of operations, and type of equipment used. For example, a very small petroleum refinery in the United States paid an engineering company $22 million to increase its sulfur recovery capacity.
Environmental concerns about sulfur and SO2 emissions, on the other hand, prevent practically all losses to the atmosphere, necessitating these types of installations. Although recovered sulfur sales might be beneficial for certain producers, others suffer the costs to have sulfur removed from their premises. However, stopping sulfur recovery activities while still processing oil and gas is never an option. If a refinery or natural gas business cannot collect sulfur for whatever reason, it must close, at least temporarily, until the issue is remedied and sulfur recovery is feasible again.
Solid Sulfur Market Segment Analysis:
Based on Application, the fertilizers segment is expected to grow at a CAGR of 8.1% during the forecast period. Sulfur has long been an important raw ingredient in the fertilizer and chemical industries. It is the main source of sulfuric acid, the world's most frequently used chemical, which is utilized in a variety of manufacturing operations. The fertilizer industry uses sulfuric acid to make phosphates or phosphoric acid, as well as other fertilizers such as ammonium sulfate.
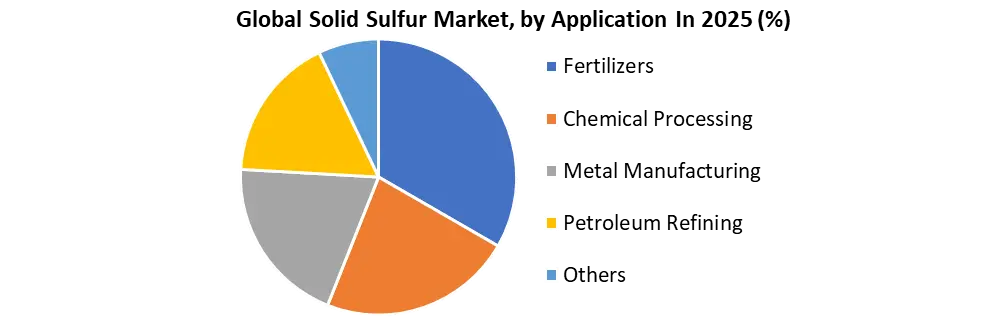
The sulfur industry has evolved dramatically during the last decade. The sector has grown from being primarily a mining enterprise to a non-voluntary output of the petroleum and non-ferrous metals industries. Sulfur usage has also changed significantly. Although sulfur is an increasingly essential plant nutrient in its own right, its primary usage in the fertilizer industry is as an ingredient in the production of phosphate fertilizer. The transition from low to high-concentration phosphate compounds resulted in a significant rise in sulfur consumption. Non-fertilizer sulfur use has lately garnered prominence as a result of growing use in hydrometallurgical applications.
Based on manufacturing process, the Solid Sulfur Market is segmented into Frasch Process and Claus Process. Among these, the Claus Process dominated the Solid Sulfur market in 2025, due to its widespread application in recovering sulfur from hydrogen sulfide gas in natural gas and petroleum refining. This process is more cost-effective, environmentally compliant, and widely integrated into industrial setups, especially in oil refineries. In contrast, the Frasch Process is less favored due to higher operational costs and limited applicability, making Claus the preferred method in large-scale sulfur production.
Solid Sulfur Market Regional Insights:
The North America solid sulfur market is expected to grow at a CAGR of 8.2% during the forecast period. In 2022, 95 facilities in 27 states produced recovered elemental sulfur and by-product sulfuric acid. The total value of the shipments was over $740 million. The output of elemental sulfur reached 7.5 million tons, with Louisiana and Texas accounting for around 55% of domestic production. Elemental sulfur was retrieved by 35 corporations at 90 plants in 26 states, in descending order of tonnage, at petroleum refineries, natural-gas processing plants, and coking plants. By-product sulfuric acid, accounting for roughly 7% of total sulfur output, was recovered by four enterprises at five nonferrous-metal smelters in four states. Local elemental sulfur accounted for 59% of domestic consumption, with by-product sulfuric acid accounting for 5%. Imported sulfur and sulfuric acid supplied the remaining 36% of sulfur consumed.
The India solid sulfur market is expected to grow at a CAGR of 7.6% during the forecast period. Sulfur recovered as a by-product from fertilizer plants and oil refineries totaled 890 thousand tonnes in 2018-19, up from 825 thousand tonnes the previous year. As per the sulfur output reported by public sector oil refineries during the fiscal year 2018-19, Indian Oil Corp. Ltd contributed around 69% of total production. Odisha accounted for 26.88% of total sulfur output, followed by Kerala (25.36%), Haryana (19.85%), Gujarat (10.33%), Uttar Pradesh (5.81%), Maharashtra (5.27%), West Bengal (4.90%), while Assam and Bihar supplied the rest of the production. Also, Hindustan Petroleum Corp. Ltd., RIL, and Essar Oil have reported recovering by-product sulfur, which is then utilized as feedstock in the production of fertilizers and medicines. Essar Oil Ltd's Vadinar refinery is also reported to manufacture the by-product sulfur.
Competitive Landscape of the Solid Sulfur Market
The global solid sulfur market is moderately concentrated, with competition primarily driven by production capacity, sulfur recovery efficiency, product quality, logistics infrastructure, and long-term supply agreements. Major players include Saudi Aramco, Abu Dhabi National Oil Company (ADNOC), Shell plc, Suncor Energy Inc., and China National Petroleum Corporation (CNPC). These companies benefit from integrated refining and natural gas processing operations, which enable them to recover elemental sulfur as a by-product and supply domestic and international markets.
Other significant participants include QatarEnergy, Chemtrade Logistics Inc., Aglobis AG, Indian Oil Corporation Limited, and Valero Energy Corporation. These companies participate in sulfur production, processing, handling, marketing, or distribution, depending on their operations. Market competition increasingly emphasizes reliable supply, efficient transportation and storage, and the ability to meet demand from fertilizer manufacturers, chemical processors, and metal-processing industries.
Looking ahead, market participants are expected to focus on expanding sulfur-handling infrastructure, strengthening international distribution networks, and improving operational efficiency. Fluctuations in sulfur availability and prices, influenced by refinery and gas-processing output as well as fertilizer-sector demand, remain important competitive factors. Companies with integrated production facilities, established export terminals, and long-term customer relationships are well positioned to compete in the global solid sulfur market.
Solid Sulfur Market Recent Development
| Date | Company | Development | Impact |
| 02 April 2026 | S&P Global Energy (Platts) | Platts launched a weekly FOB US Gulf Solid Sulfur price assessment covering bulk elemental sulfur shipments of 35,000–40,000 metric tonnes. | The new benchmark improves price transparency and provides market participants with an additional reference for US Gulf solid sulfur transactions. |
| 11 May 2026 | The Mosaic Company | Mosaic withdrew its 2026 phosphate production guidance and began reassessing operating rates amid sharply rising sulfur costs. | Higher solid sulfur input costs increased pressure on phosphate fertilizer production economics and highlighted the importance of reliable sulfur supplies. |
| 21 May 2026 | Egyptian Financial & Industrial Co. (EFIC) | EFIC began maintenance at its three granular single superphosphate plants, with high sulfur costs cited as a key factor. | The disruption demonstrated how expensive sulfur feedstock can constrain downstream fertilizer production and affect demand across the solid sulfur supply chain. |
| 26 June 2026 | Government of Russia | Russia extended its temporary sulfur export ban through 31 December 2026, according to S&P Global reporting. | The extension further restricted internationally available sulfur supplies and added uncertainty for fertilizer manufacturers and industrial buyers dependent on exports. |
| 25 September 2026 | S&P Global Energy (Platts) | Platts discontinued its quarterly FOB Middle East contract sulfur price assessment and related range and monthly-average assessments. | The change reflects evolving sulfur contract-pricing practices and alters the benchmark information available to participants trading solid sulfur from the Middle East. |
Solid Sulfur Market Scope: Inquiry Before Buying
| Solid Sulfur Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 3.87 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 4.1% | Market Size in 2034: | USD 5.55 Bn. |
| Segments Covered: | by Manufacturing Process | Frasch Process Claus Process |
|
| by Product Type | Metal‑granulated sulfur Powdered sulfur Lump & other forms |
||
| by End‑User Industry | Agriculture Chemical & Petrochemical Rubber Pulp & Paper Others |
||
| by Application | Fertilizers Chemical Processing Metal Manufacturing Petroleum Refining Others |
||
Solid Sulfur Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Solid Sulfur Market, Key Players are
1. Saudi Aramco
2. Abu Dhabi National Oil Company (ADNOC)
3. QatarEnergy
4. Gazprom
5. Shell plc
6. ExxonMobil Corporation
7. Chevron Corporation
8. Marathon Petroleum Corporation
9. Valero Energy Corporation
10. Repsol S.A.
11. Chemtrade Logistics Inc.
12. Enersul Limited Partnership
13. Motiva Enterprises LLC
14. Suncor Energy Inc.
15. Tengizchevroil LLP
16. China National Petroleum Corporation (CNPC)
17. Sinopec
18. Indian Oil Corporation Limited
19. Bharat Petroleum Corporation Limited (BPCL)
20. Hindustan Petroleum Corporation Limited (HPCL)
21. Reliance Industries Limited
22. PetroChina Company Limited
23. Kuwait Petroleum Corporation (KPC)
24. Kuwait Integrated Petroleum Industries Company (KIPIC)
25. PETRONAS
26. TotalEnergies SE
27. Petrobras
28. Pemex
29. Formosa Plastics Corporation
30. Oxbow Corporation
31. H.J. Baker & Bro., LLC
32. PVS Chemicals, Inc.
33. Alfa Aesar
34. Merck KGaA
35. Thermo Fisher Scientific Inc.
36. ChemPoint
37. Aglobis AG
38. Jordan Sulphur
39. OQ
40. Duqm Refinery and Petrochemical Industries Company (OQ8)
Frequently Asked Questions:
1. Which region is expected to dominate the Solid Sulfur Market at the end of the forecast period?
Ans. North America is expected to dominate the sulfur market at the end of the forecast period.
2. What is the growth rate of the Solid Sulfur Market?
Ans. Solid Sulfur Market is expected to grow at a CAGR of 4.1% during the forecast period.
3. What is expected to drive the growth of the Solid Sulfur Market in the forecast period?
Ans. Role of sulfur in eco-friendly concrete production.
4. What is the projected market size & growth rate of the sulfur Market?
Ans. Solid Sulfur Market was valued at USD 3.87 Bn. in 2025 and the total Solid Sulfur revenue is expected to grow at 4.1% from 2026 to 2034, reaching USD 5.55 Bn.
5. What segments are covered in the Solid Sulfur Market report?
Ans. The segments covered are Manufacturing Process, Application, Product type, end-user industry and Region.