
Sulfuric Acid Market - Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034
Overview
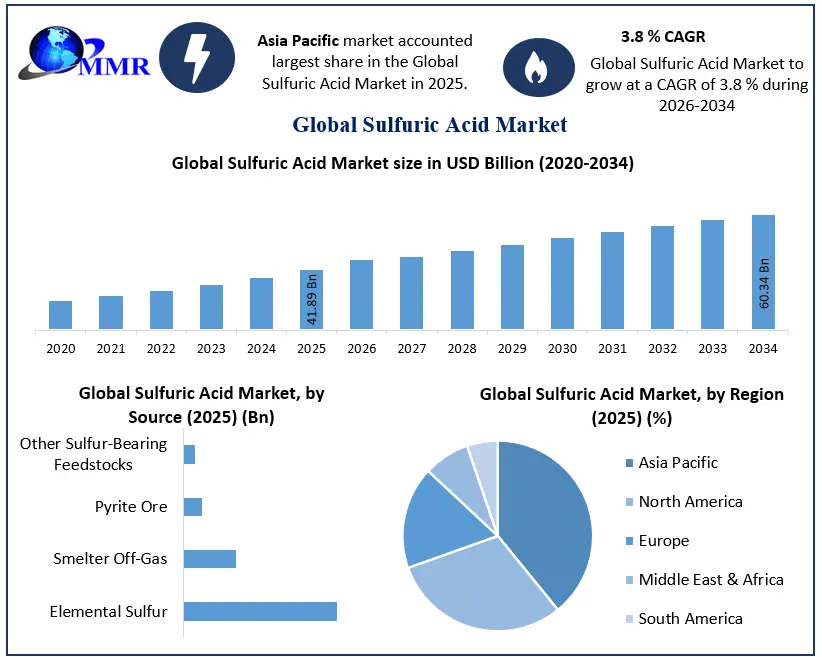
Global Sulfuric Acid Market size was USD 41.89 billion in 2025 and is expected to reach USD 60.34 billion by 2034, at a 3.8% CAGR, driven by fertilizer and phosphoric acid production, mining, metal processing, batteries, and stricter environmental norms.
Sulfuric Acid Market Overview
Sulfuric acid is a strong, corrosive inorganic acid (H₂SO₄) widely used in fertilizers, chemical manufacturing, metal processing, batteries, and industrial applications due to its powerful dehydrating and oxidizing properties. Strong fertilizer demand across the Asia Pacific, particularly China and India, continues to drive the Sulfuric Acid Market, where more than 55% of total H₂SO₄ output is used for phosphoric acid manufacturing. Industrial sulfuric acid applications in metal processing, pigments, detergents, and petrochemicals elevate global sulfuric acid demand, while increasing EV penetration boosts consumption of battery electrolytes.
Environmental regulations are encouraging low-emission technologies, supporting growth in wet sulfuric acid process markets and improving global production efficiency, driving the sulfuric acid market. Price volatility remains a challenge, as elemental sulfur costs fluctuated by 20–30% in 2024–25, affecting margins in fertilizer and chemical manufacturing industries. Rising wastewater treatment needs, expanding mining operations, and increasing demand for fertilizer acid across developing nations offer strong market opportunities. Asia Pacific leads the Market revenue by region, followed by North America and Europe.
Sulfuric Acid Market Growth Analysis
To know about the Research Methodology :- Request Free Sample Report
Trend: Rapid global shift toward low-emission DCDA sulfuric acid plant technology
Modern double contact double absorption units deliver up to 99.8% conversion efficiency, reduce SO₂ emissions by more than 85%, and generate substantial industrial steam, making them ideal for fertilizer, smelter, and chemical manufacturing operations. This trend is significantly shaping the Sulfuric Acid market, especially in the Asia Pacific, where large-scale expansions are underway in China, India, and Indonesia to meet rising fertilizer-grade sulfuric acid requirements. Governments and industry bodies are promoting integrated facilities that recover waste heat and use advanced gas cleaning systems.
Tightened sulfuric acid plant environmental regulations in Europe and North America further accelerate the migration from older lead chamber and basic contact systems to advanced DCDA or hybrid wet sulfuric acid process units. Investments from OCP, Ma’aden, DuPont Clean Technologies, BASF, and Chemtrade highlight the global momentum toward high-purity, energy-optimized production. Rising global sulfuric acid demand from phosphoric acid production, as well as growing mining and metal processing, reinforces the need for efficient, low-emission technologies. This technology-driven transition represents one of the most influential sulfuric acid market trends of the coming decade.
The increasing demand for phosphoric acid production using sulfuric acid
As the world’s population grows and fertilizer usage intensifies across Asia Pacific, Africa, and Latin America, the need for phosphate fertilizers such as DAP, MAP, SSP, and TSP continues to rise. This directly boosts the Sulphuric Acid Market, which remains a core input for fertilizer acid production. India and China together consume more than 65 million tonnes annually, positioning agriculture as the most influential segment of global sulfuric acid demand. Supportive government policies such as India’s nutrient-based subsidy (NBS) and China’s boosting of domestic fertilizer self-reliance enhance sulfuric acid market growth. Additionally, new fertilizer complexes in Morocco, Saudi Arabia, and Indonesia are creating strong sulfuric acid industry opportunities. Rising phosphate ore processing, integrated DCDA plant installations, and strong demand for industrial acids in crop protection chemicals also reinforce this momentum.
• Import Analysis of Fertilizers
Brazil remains the world’s largest fertilizer importer in 2024, driven by its extensive agricultural acreage and dependence on external nutrient inputs. India and the USA follow, reflecting strong crop production requirements, while China, France, Canada, Mexico, Australia, Turkey, and Thailand maintain steady import levels aligned with diverse farming activities. Parallelly, sulfuric acid demand is rising globally as it is essential for producing phosphoric acid used in phosphate fertilizers. Increased consumption of NPK fertilizers, industrial chemicals, and emerging battery applications is accelerating sulfuric acid production capacity, strengthening its role as a critical raw material in agriculture and manufacturing value chains
• Export Analysis of Fertilizers
Russia dominates global fertilizer exports in 2024, driven by large production capacity and competitive pricing. China and Canada follow with strong manufacturing bases and abundant resources, while the U.S., Morocco, and Saudi Arabia remain vital suppliers. Belgium, the Netherlands, and Turkey provide consistent export volumes supporting global supply chains. At the same time, sulfuric acid exports are rising as demand increases for phosphoric acid production, fertilizers, metals processing, and battery materials. Expanding industrialization in developing regions is boosting trade, reinforcing sulfuric acid’s role as a critical commodity chemical across agriculture and manufacturing sectors.
High Volatility in Elemental Sulfur to Sulfuric Acid Feedstock Prices
The refining industry, responsible for nearly 70% of sulfur feedstock, experienced 20–30% price fluctuations in 2024–25 due to refinery maintenance cycles, geopolitical disruptions, and shifting oil output levels. This instability affects the sulphuric acid market, especially in regions dependent on imported sulfur such as India, Brazil, and parts of Southeast Asia. When sulfur prices spike by USD 40–60 per tonne, fertilizer producers, smelters, and chemical manufacturers face margin pressure, affecting the broader sulfuric acid market outlook. Smelter shutdowns in Chile, the U.S., and Canada tighten supply, impacting by-product sulfuric acid from smelters and pushing up sulfuric acid price trends. Logistics bottlenecks, including port congestion and rising freight rates, add additional sulfuric acid industry challenges, disrupting procurement for large-scale DCDA plants. Environmental regulations requiring high-cost emission control systems also increase operational burdens for small and mid-size producers.
Sulfuric Acid Market Segment Analysis
By Source, The global sulfuric acid market is segmented by source into elemental sulfur, smelter off-gas, pyrite ore, and other sulfur-bearing feedstocks. Elemental sulfur represents an important raw material due to its availability and suitability for large-scale sulfuric acid production. Smelter off-gas supports sulfur recovery and helps reduce industrial emissions from metal processing operations. Pyrite ore serves as an alternative sulfur source, particularly in regions with suitable mineral resources. Other sulfur-bearing feedstocks contribute to diversified production pathways and resource utilization. Growing demand for sulfuric acid in fertilizer manufacturing, chemical processing, metal extraction, and petroleum refining supports market expansion.
By Concentration, The global sulfuric acid market is categorized by concentration into dilute sulfuric acid, standard or commercial concentration sulfuric acid, concentrated sulfuric acid, and oleum or fuming sulfuric acid. Dilute sulfuric acid is used in selected industrial processes, battery applications, and chemical treatment. Standard or commercial concentration sulfuric acid serves general industrial and chemical manufacturing requirements. Concentrated sulfuric acid plays a significant role in fertilizer production, petroleum refining, metal processing, and chemical synthesis. Oleum supports specialized chemical manufacturing processes that require high sulfur trioxide content. Increasing demand from the phosphate fertilizer industry, industrial chemicals, and metallurgical applications drives the need for different sulfuric acid concentrations.
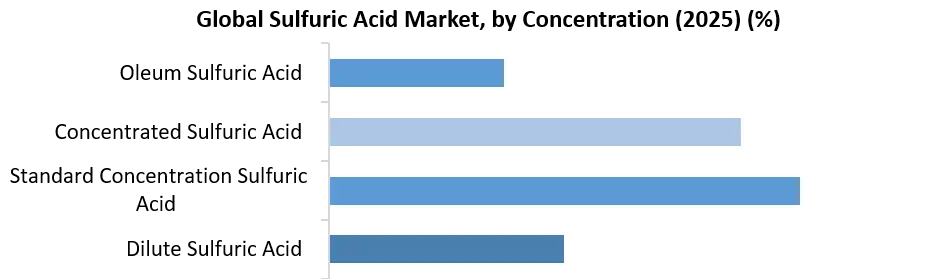
Sulfuric Acid Market Regional Insights
Asia Pacific dominated the Sulfuric Acid Market in 2025 and is expected to continue its dominance over the forecast period. The region’s leadership is driven by exceptionally high fertilizer consumption in China and India, where more than 55% of regional output supports phosphoric acid manufacturing and downstream phosphate fertilizers. Strong growth in metal processing, battery manufacturing, and chemical intermediates further strengthens regional demand. China alone produces nearly 90–95 million tonnes annually, while India exceeds 20 million tonnes, supported by refinery-based elemental sulfur conversion and expansions of DCDA units. Rising industrial acid usage, rapid agricultural intensification, and expanding smelter operations across ASEAN nations act as major global sulfuric acid demand drivers.
Asia Pacific benefits from new capacity additions, low-cost feedstock availability, and government-backed investments in fertilizer self-reliance, creating substantial sulfuric acid market opportunities. Increasing use of the contact process, modernization of wet-process facilities, and improved supply chains contribute to stable output and competitive pricing. Demand from EV battery electrolytes, wastewater treatment, and pigment manufacturing is expected to support regional expansion.
North America represents a significant market for sulfuric acid, driven by established fertilizer production, petroleum refining, and metal processing industries. The United States is a major contributor, with sulfuric acid widely used in phosphate fertilizer manufacturing, copper extraction, and chemical processing. Demand from mining and industrial applications continues to support regional consumption.
Europe’s sulfuric acid market is supported by its well-developed chemical manufacturing, fertilizer, and metal processing industries. Countries such as Germany, France, and the United Kingdom contribute to demand through industrial chemical production and metal treatment applications. Environmental regulations and improvements in sulfur recovery and resource efficiency also influence regional production practices.
South America’s market is primarily driven by mining activities and agricultural demand, particularly in Brazil, Chile, and Peru. Sulfuric acid is essential for copper ore leaching and the production of phosphate-based fertilizers. Continued investment in mining operations and fertilizer supply chains supports market demand across the region.
Middle East & Africa: The Middle East and Africa market is supported by sulfur availability from oil refining and natural gas processing, alongside growing fertilizer manufacturing and mining activities. Saudi Arabia, Morocco, and other regional producers contribute to demand through phosphate fertilizer and phosphoric acid production. Industrial diversification and investment in downstream chemical facilities are creating additional opportunities for sulfuric acid consumption.
Sulfuric Acid Market Competitive Landscape
The sulfuric acid industry is highly competitive, with global producers focusing on capacity expansion, cost-efficient elemental sulfur conversion, and low-emission technologies to strengthen their sulfuric acid market share. Key players such as BASF, OCP Group, Mosaic, Chemtrade, Aurubis, and Ma’aden dominate through integrated fertilizer production, securing raw material access, and expanding DCDA sulfuric acid plants to meet rising global sulfuric acid demand. The mining and metal processing companies are adopting sustainable leaching technologies, while chemical manufacturers invest in ultra-pure grades for electronics. Strategic collaborations, backward integration into elemental sulfur, and investments in the wet sulfuric acid process. Regionally, China, India, the U.S., and Morocco lead production due to strong sulfuric acid demand in the fertilizer industry, especially for phosphoric acid manufacturing. Price fluctuations, regulatory norms, and technological upgrades.
• On 30 April 2025, BASF announced a major investment in a new semiconductor-grade sulfuric acid (H₂SO₄) plant at its Ludwigshafen site. The high-purity facility costing a high double-digit million-euro amount supports Europe’s expanding semiconductor ecosystem, with operations starting in 2027. The project strengthens supply chain reliability by providing ultra-pure sulfuric acid for chip manufacturing, benefiting automotive, mobile communication, and AI applications, while reinforcing BASF’s strategic partnerships and leadership in advanced electronic chemicals.
• On 17 July 2024, OCP Group awarded Worley Chemetics a notice of award to develop three new greenfield sulfuric acid plants at the Mzinda Phosphate Hub in Morocco. The project includes delivery of proprietary sulfuric acid technology, engineering, procurement, specialized equipment, and site services. Designed for higher efficiency and lower emissions, the plants will support OCP’s Green Investment Programme, helping expand fertilizer production capacity from 12 million to 20 million tonnes by 2027 using clean energy and sustainable water resources.
Sulfuric Acid Market Recent Developments:
| Date | Company | Development | Impact |
| 07 January 2026 | Gujarat State Fertilizers & Chemicals Limited (GSFC) | GSFC commenced commercial production at its new Vadodara sulfuric acid plant with an installed capacity of 600 metric tonnes per day. | The facility strengthens domestic production capacity and supports the company’s downstream fertilizer and chemical operations. |
| 16 February 2026 | Jordan Phosphate Mines Company (JPMC) | JPMC signed an approximately US$193 million agreement to construct a sulfuric acid plant in Shidiya with planned capacity of 900,000 tonnes annually. | The planned facility is intended to secure feedstock for phosphoric acid production, improve vertical integration, and reduce dependence on external supplies. |
| 06 March 2026 | Indian Farmers Fertiliser Cooperative Limited (IFFCO) | IFFCO inaugurated Sulphuric Acid Plant-III at its Paradip facility in Odisha. | The plant enhances IFFCO’s captive sulfuric acid supply and supports fertilizer production while contributing to reduced reliance on imports. |
| 26 May 2026 | China National Chemical Engineering (CNCEC-TCC) | CNCEC-TCC announced successful commissioning and qualified product output from an 800,000-tonne-per-year sulfuric acid project in Kazakhstan. | The project advances large-scale sulfuric acid supply in Central Asia and supports development of the region’s industrial chemical supply chain. |
| 17 June 2026 | CNCEC-TCC and CNCEC International | The companies reported that the Kazakhstan sulfuric acid plant completed a 72-hour full-load performance test, with key operational, safety, environmental, and energy-efficiency indicators exceeding contractual requirements. | The successful test validates the plant’s operating performance and supports progress toward reliable large-scale production. |
Sulfuric Acid Market Scope: Inquire before buying
| Sulfuric Acid Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 41.89 USD Billion |
| Forecast Period 2026-2034 CAGR: | 3.8% | Market Size in 2034: | 60.34 USD Billion |
| Segments Covered: | by Source | Elemental Sulfur Smelter Off-Gas Pyrite Ore Other Sulfur-Bearing Feedstocks |
|
| by Concentration | Dilute Sulfuric Acid Standard/Commercial Concentration Sulfuric Acid Concentrated Sulfuric Acid Oleum/Fuming Sulfuric Acid |
||
| by Grade | Industrial/Technical Grade Battery Grade Reagent/Chemically Pure Grade Electronic/High-Purity Grade Other Specialty Grades |
||
| by Manufacturing Process | Single Contact Single Absorption (SCSA) Double Contact Double Absorption (DCDA) Wet Sulfuric Acid/Other Processes |
||
| by Application | Fertilizer Production Chemical Manufacturing Metal Processing & Metallurgy Petroleum Refining Batteries Pulp & Paper Textile Processing Water & Wastewater Treatment Electronics & Semiconductor Processing Others |
||
Sulfuric Acid Market, by Region
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)
Key Players / Competitores Proflies Coverd Sulfuric Acid Market Report in Strategic Perspective
North America
1. The Mosaic Company
2. Nutrien Ltd. (includes former PotashCorp, merged 2018)
3. Chemtrade Logistics Income Fund
4. PVS Chemicals, Inc.
5. Southern States Chemical
6. Honeywell International Inc.
7. Freeport-McMoRan Inc.
8. Grupo México, S.A.B. de C.V.
9. Southern Copper Corporation (Grupo México)
Europe
1. BASF SE
2. Nouryon (Carlyle Group — divested from Akzo Nobel N.V., 2018)
3.Aurubis AG
4. Veolia Environnement S.A.
5. KGHM Polska Miedź S.A.
6. Boliden AB
7. PhosAgro PJSC
8. EuroChem Group AG
9. Yara International ASA
10.Glencore plc
11. Anglo American plc
12. Rio Tinto Group
Middle East & Africa
1. Groupe Chimique Tunisien
2. Maaden (Saudi Arabian Mining Company)
3. OCP Group
4. ICL Group Ltd. (Israel Chemicals Ltd.)
Asia Pacific
1. China Petroleum & Chemical Corporation (Sinopec)
2. Mitsubishi Chemical Group Corporation
3. Jiangxi Copper Corporation
4. DMCC Specialty Chemicals Limited (formerly The Dharamsi Morarji Chemical Company Limited)
5. Indian Farmers Fertiliser Cooperative Limited (IFFCO)
6. Coromandel International Limited
7. Rashtriya Chemicals & Fertilizers Limited (RCF)
8. Gujarat State Fertilizers & Chemicals Limited (GSFC)
9.Hindustan Zinc Limited (Vedanta Limited)
10.PT Petrokimia Gresik (Pupuk Indonesia)
11. Sumitomo Chemical Co., Ltd.
12. Toho Zinc Co., Ltd.
13.BHP Group Limited
South America
1. Codelco (Corporación Nacional del Cobre de Chile)
2. Vale S.A.
Others
Frequently Asked Questions:
1.Which region has the largest share in the Global Sulfuric Acid Market?
Ans: The Asia Pacific region held the largest share of the Global Sulfuric Acid Market in 2025.
2. What is the growth rate of the Global Sulfuric Acid Market?
Ans: The Global Sulfuric Acid Market is growing at a CAGR of 3.8% during the forecast period of 2026–2034.
3. What is the scope of the Global Sulfuric Acid Market report?
Ans: The Global Sulfuric Acid Market report covers market dynamics, PESTLE analysis, Porter’s Five Forces analysis, regional and segment analysis, competitive landscape, market estimation, and forecasts.
4. Who are the key players in the Global Sulfuric Acid Market?
Ans: The key players in the Global Sulfuric Acid Market include BASF SE, The Mosaic Company, OCP Group, Chemtrade Logistics, PVS Chemicals, Aurubis AG, KANTO Chemical Co., Inc., INEOS Group, DuPont, and Ma’aden.
5. What is the study period of this market?
Ans: The Global Sulfuric Acid Market is studied from 2020 to 2034.