
Glycols Market by Product, by Application, by End User and Regional Insights 2034
Overview
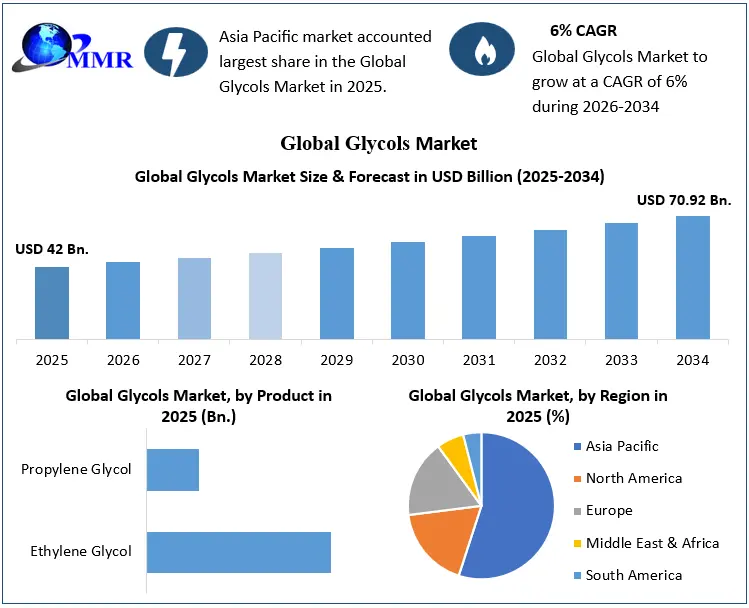
The Global Glycols Market was valued at USD 42 Billion in 2025 and is projected to reach USD 70.92 Billion by 2034, growing at a CAGR of 6% during the forecast period 2026–2034.
Global Glycols Market Overview
The Global Glycols Market covers a group of chemical compounds such as glycol, propylene glycol, diethylene glycol, and other glycol derivatives as raw materials and chemical intermediates. The market report analyzes the growth drivers in the application fields of polyester, antifreeze, packaging, and coatings, while reviewing the market growth potential based upon emerging demand in diverse end-use industries. The report provides valuable insights into the market dynamics, trends, and opportunities for the global glycols market.
The market report highlights the key distribution channels and end-use industries and the market Forecast, supply-demand scenarios and volume. Automotive industries, chemical manufacturers, textile industries, packing industries, pharmaceutical industries, personal care and cosmetics, and industrial applications are the major end-use industries for the global glycols market. Bio-based glycols, sustainable packaging, electric vehicle thermal management, coatings and inks, and high-purity glycols are the key areas with promising growth opportunities. The identified challenges for the global glycols market consist of a significant market gap between the demand for reduced dependence on petroleum feedstocks and volatile prices of raw materials. The market potential for glycols and derivatives remains promising as the consumption in diverse end-use industries is forecasted to rise during the forecast period (2026-2034). Asia Pacific is considered the key region for the global glycols market as it holds a significant share in the production of chemicals and pharmaceuticals and has a large consumer base. China, India, Japan, South Korea, and other ASEAN countries are majorly involved in the manufacturing process of glycols.
The key market players analyzed in the Global Glycols Market consist of BASF SE, Dow Inc., SABIC, Shell plc, LyondellBasell Industries, Mitsubishi Chemical Group, Reliance Industries, and Sinopec. According to the MMR research, the market is expected to witness diversification in the production portfolio for higher capacity utilization rates across the key producers. The research further identifies the potential for market growth for the global glycols market in the downstream application fields and regional expansion on the back of increasing production capacities for the base chemicals. The research forecasts that the global glycols market will witness moderate growth on the back of the rising demand in the end-use industries. Furthermore, the MMR analysis highlights the importance of the market gap between the production of conventional glycols and emerging sustainability-focused production for future market growth.
Glycols Market Growth and Share Analysis
To know about the Research Methodology:-Request Free Sample Report
Global Glycols Market Key Insights
- Market Size: The Global Glycols Market was valued at USD 42 Billion in 2025 and is projected to reach USD 70.92 Billion by 2034, growing at a CAGR of 6% during the forecast period 2026–2034.
- Leading Region: Asia Pacific market accounted largest share in the Global Glycols Market due to highly developed chemical, textile, automotive and PET industry in China, India, Japan and South Korea.
- Demand Area: Polyester fibers and PET resin remain the major application areas because glycols are key raw materials in textile and packaging production.
- Growth Opportunity: Bio based, recycled and high purity glycols are the emerging segments which provide the greatest potential for the manufacturers to explore.
- Market Trend: Producers increasingly focus on cleaner production processes and utilization of recycled feedstock and development of specialty glycols for higher value applications.
Glycols Market Dynamics
Rising Demand from Polyester, Automotive, Packaging, and Industrial Applications Expands Glycols Consumption
The Global Glycols Market continues to expand as glycols remain a critically important feedstock across textiles, PET packaging, automotive coolants, paints, coatings, personal care, pharmaceuticals, and industrial fluids. Ethylene glycol provides raw materials for high-volume polyester and PET production, while propylene glycol finds application as a solvent, moisture control agent, heat-transfer fluid, and chemical intermediate. The demand is also driven by construction materials, resins, adhesives, de-icing fluids, and specialty products, which contributes to the overall market size. The growth outlook is supported by the increase in vehicle production, demand for packaged food and beverages, synthetic fibers, and industrial manufacturing. Developing economies also play an essential role by increasing the need for construction, infrastructure, and consumer goods, as well as the level of urbanization. As a result, glycol producers strive to expand production, enhance processing efficiency, and raise capital expenditures in integrated chemical facilities to accommodate the growing demand and gain advantages.
Volatile Feedstock Prices and Dependence on Petrochemical Raw Materials Limit Stable Market Growth
The Global Glycols Market outlook remains highly dependent on petrochemical feedstocks such as ethylene and propylene. Thus, the major producers are sensitive to the fluctuations in energy, crude oil, natural gas, and transportation costs as the rising input prices directly impact the cost of goods sold. In addition, the increase in feedstock prices may result in higher-than-expected selling prices for glycols, while certain customers may seek to limit the passing-through of costs. These factors affect the long-term outlook and pose a challenge in negotiating favorable terms for supply contracts. The market gap is determined by the demand for traditional petrochemical feedstocks and the need for more sustainable and renewable products. Producers are under pressure to adapt to changing regulations, energy costs, emissions, and waste management, which adds to the operational complexity and expenditures. Such limitations are particularly profound for smaller players due to their lower bargaining power when it comes to negotiating energy and feedstock rates, as well as the ability to leverage economies of scale. As a consequence, the market outlook for the producers of glycols is subject to shifts in demand within the textile, automotive, construction, and packaging industries.
Bio-Based and Sustainable Glycols Create New Market Opportunities Across High-Value Applications
The growing demand for renewable feedstocks creates new opportunities for the producers of bio-based and lower-carbon products. The automotive, packaging, cosmetics, food-processing, and consumer-goods industries increasingly favor sustainable materials, which enables a broader adoption of bio-based ethylene glycol, renewable propylene glycol, and recycled feedstocks. This market preference supports the long-term outlook for glycols and helps to offset the impact of unfavorable pricing trends. The rising awareness of environmental issues encourages more companies to consider the benefits of using recycled materials and renewable energy. As a result, the use of bio-based and lower-carbon glycols will become more widespread. The current market gap is the ability to produce and sell lower-cost sustainable products at an affordable scale. Therefore, the companies that invest in renewable feedstocks, waste recycling, and lower-emissions processing technologies may benefit from the growing demand for more environmentally friendly products. Increased expenditures on research and development, as well as production, open the door for new market opportunities, including partnership and collaboration with the food-processing, packaging, automotive, and pharmaceutical industries.
Balancing Capacity Expansion with Changing Demand Creates a Major Supply-and-Profitability Challenge
One of the major market risks for glycols relates to the ability to meet the demand requirements in a cost-efficient manner. Large-scale, integrated chemical facilities require significant capital expenditures, and most of them operate at full capacity to meet the demand for polyester, PET packaging, automotive, construction, and industrial fluids. As a result, changes in the overall demand due to macroeconomic shifts and fluctuations in the downstream industry may have a profound impact on the utilization rate and, ultimately, the market. On the one hand, an increase in production capacity beyond the level of demand will lead to lower prices and, consequently, reduced revenues and profits. On the other hand, a sudden supply shortage due to insufficient production or unplanned maintenance may result in higher prices and the inability to meet customer needs. Lastly, the growth outlook for the glycols sector remains competitive with respect to the producers of alternative chemical products, as well as those that operate in regions that offer lower energy and labor costs. The need to respond to the changing demand environment impacts the producers’ ability to compete on price, quality, and sustainability while maintaining sufficient levels of capacity and supply.
Growth in PET Packaging and Polyester Manufacturing Continues to Strengthen Large-Volume Glycol Demand
The demand for polyester fiber and PET (Polyethylene Terephthalate) resins drives the need for ethylene glycols and, by extension, the overall market outlook. Textile and PET packaging are essential growth drivers that are expected to increase the utilization rate of certain chemical facilities. Certain emerging markets are of particular importance as the growing population, levels of urbanization, and disposable income contribute to the rise in polyester production and the use of PET packaging materials. This trend is especially pronounced in the developing world, where the demand for PET packaging is impacted by the rising middle class and growing need for safe and reliable beverage containers. Overall, the changes in the demand for polyester fiber and various plastics influence the supply-demand gap for glycols and, therefore, the market outlook. Producers that operate in countries that offer sufficient local supply and demand advantages have the potential to gain substantial market share by meeting the needs of downstream industries.
The Market Shifts Toward Cleaner Production, Circular Feedstocks, and Specialized High-Purity Glycols
A significant opportunity for the major glycol producers is the ability to shift from traditional petroleum-based feedstocks to renewable and recycled materials. The current market environment encourages companies to adopt more sustainable practices by reducing emissions and energy consumption in production, as well as the use of water and other resources. The market gap relates to the need to address the demand for high-purity products in the pharmaceutical, personal care, and food industries, as well as the growing automotive industry with its unique needs for heat-transfer and cooling fluids. The higher complexity of these products is an important factor that differentiates them from commodity grades of propylene and ethylene glycols. As a result, the market opportunity is to provide higher-quality products with enhanced specifications and purity levels. Producers are expected to increase their research and development efforts to ensure that they remain competitive and take advantage of the growing demand for specialty fluids and chemicals in the food processing and pharmaceutical industries.
Global Glycols Market Segment Analysis
By Application, The Global Glycols Market by application is segmented into Automotive, HVAC, Textiles, Airline, Medical, Pipeline Maintenance, Polyester Fibers & Resin, and Food & Beverage Processing. Polyester Fibers & Resin dominate the market due to the extensive use of glycols, particularly ethylene glycol, in the production of polyester and PET polymers. Automotive applications contribute significantly through the demand for antifreeze, coolants, brake fluids, and thermal-management systems. HVAC applications involve the utilization of glycol-based fluids for heating, ventilating, and air conditioning purposes. Textiles exhibit consistent demand for polyester fiber production, while Airline applications are driven by de-icing and anti-icing fluids. Medical and Food & Beverage Processing applications necessitate the use of high-purity glycols in specific formulations, process fluids, and temperature-control systems. Pipeline Maintenance is another emerging application area where glycol-based fluids help prevent freezing and ensure smooth flow in pipelines. The overall outlook for the Global Glycols Market remains positive as demand is expected to rise from automotive, industrial processing, packaging, and other applications while the market potential for cleaner formulations, high-purity products, and thermal-management solutions will increase.
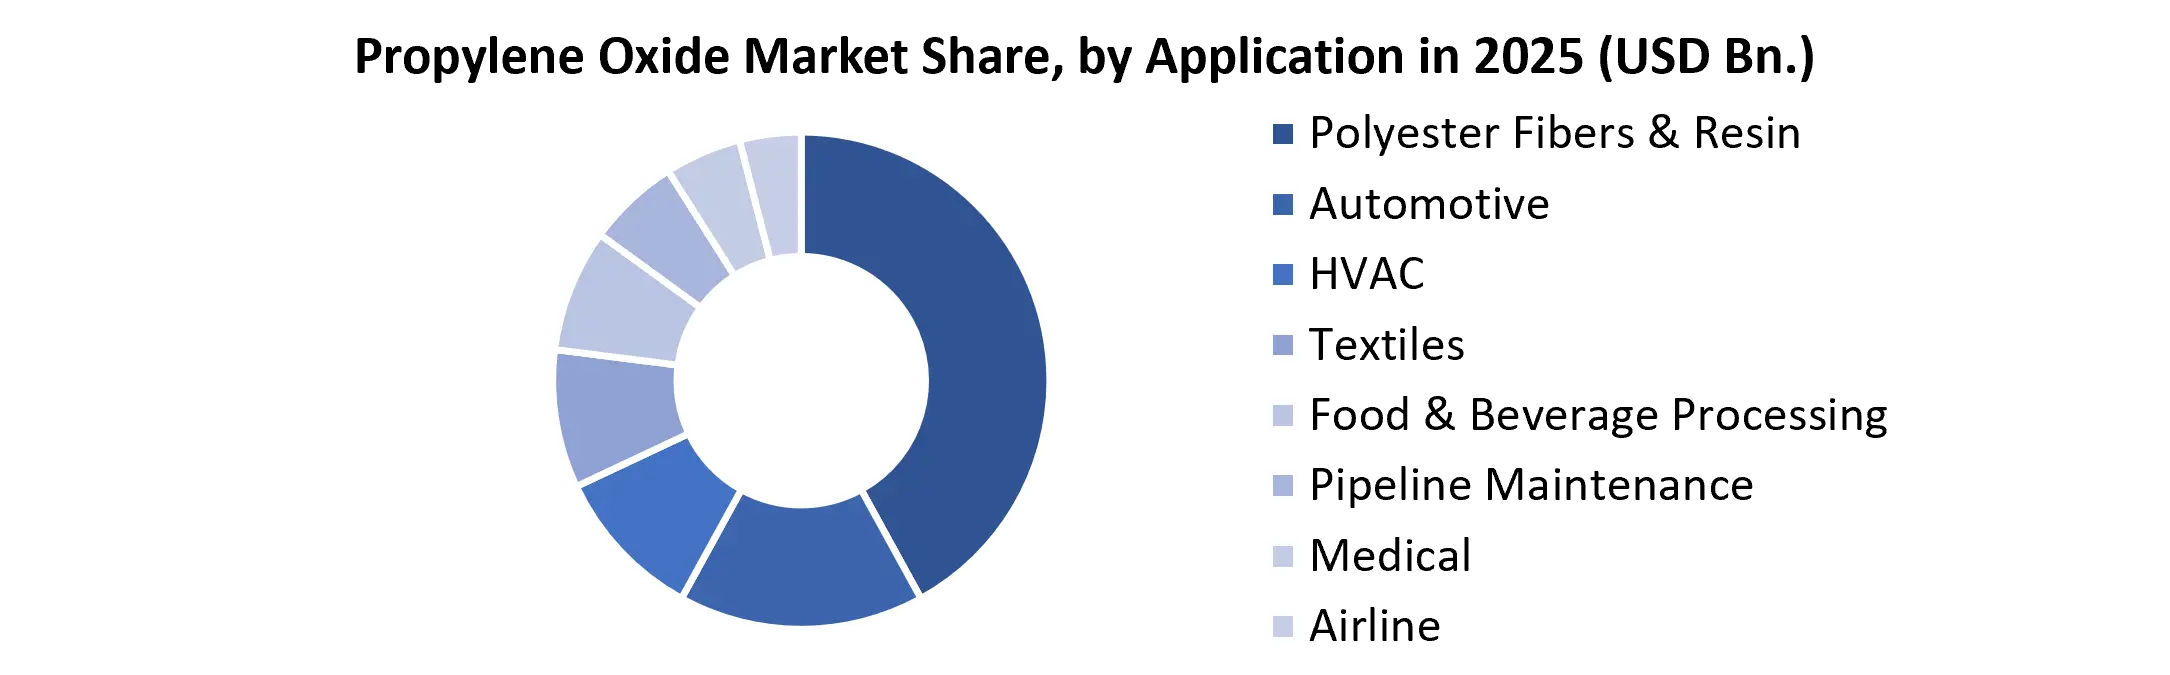
By End User, The Global Glycols Market by end users is divided into Automotive and Transportation, Packaging, Food and Beverage, Cosmetics, Glycol Markets, and Textile. The Automotive and Transportation sector is a significant contributor to the glycols market as ethylene glycol and propylene glycol are used in conventional and electric vehicles as heat-transfer fluids, antifreeze, and coolants. The Packaging industry constitutes a substantial portion of the Global Glycols Market as PET resin produced using ethylene glycol is used in beverage containers, packaging, and other related products. Food and Beverage companies utilize selected glycols in their production processes, and temperature-control applications. Cosmetics are a growing application area for glycols as they are used as solvents and humectants. Textile manufacturing is another major end-use industry for glycols as ethylene glycol is a critical raw material in polyester production. The market potential for glycols is also emerging in specialty products, bio-based variants, and higher-purity grades. The major market opportunity for the glycols market is to reduce the reliance on petrochemical feedstocks while maintaining cost-effectiveness, and this will drive the demand for glycols across various applications for an extended period.
 Glycols Market Regional Insights
Asia Pacific constitutes the largest region for the Global Glycols Market, due to extensive textiles, PET packaging, automotive, chemical, and industrial manufacturing. China, India, Japan, and South Korea provide a substantial share due to high production and consumption of polyester fibers and resins. The market forecast for Asia Pacific is optimistic due to a continuous rise in manufacturing, urbanization, and demand for glycols. The major market gap in this region is the need for cleaner and more efficient production, while the market potential is attributed to bio- and specialty-glycols.
North America has a developed market for glycols, due to the significant automotive, packaging, pharmaceutical, industrial, and HVAC industries. The market forecast for North America is based on a considerable contribution of the United States to the overall market size. The growth is supported by chemicals and plastics manufacturing, petrochemical refining, air conditioning, and the use of glycols in paper production, as well as the demand for sustainable and specialty products. The market gap in North America is the replacement of petrochemical feedstocks, with market potential for renewable and recyclable sources.
Europe has a consistent demand for glycols due to the automotive, packaging, cosmetics, pharmaceutical, construction, and textiles industries. Germany, France, Italy, and the United Kingdom provide the significant share of the market, based on manufacturing, chemicals, and paper production. The market forecast for Europe is moderate, due to the emphasis on sustainability and decreased carbon footprint, as well as the need for novel approaches in production in various industries. The market gap in this region is the necessity to meet the environmental demands for resource efficiency, with market potential for bio-glycols, as well as chemicals derived from recycled feedstocks.
South America is a growing market for glycols, due to the increasing demand from the automotive, packaging, textile, and food and beverage sectors. The significant countries in this region are Brazil and Argentina, which contribute the majority of the market. The market forecast is based on the expected increase in production and manufacturing, as well as consumer goods and industrial applications. South America has a market gap in terms of supply and production, which offers substantial market potential for investment, production facilities, and new entrants.
The Middle East and Africa region has a moderate demand for glycols in petrochemical, automotive, construction, paper, packaging, and HVAC fields, as well as industrial applications. In the Middle East, the market size is determined by the availability of petrochemical feedstocks, and the market forecast is based on the expected increase in downstream industries. Africa has lower demand due to less developed manufacturing, but the market potential is considerable due to growing export opportunities and industrial applications.
Glycols Market Recent Development
| Date | Recent Development |
| September-2026 | LG Chem and Volkswagen Group announced a strategic collaboration to develop lightweight and sustainable mobility materials. This collaboration builds upon LG Chem’s position as a producer of materials for the automotive industry, and the demand from the transportation sector relevant to the broader chemicals value-chain. |
| September-2026 | Shell has completed the acquisition of ARC Resources Ltd., adding around 370 kboe/d of liquids and gas production. This acquisition enhances Shell’s upstream feedstocks position, relevant to the company’s integrated petrochemical and chemical production. |
| August-2026 | INEOS Inovyn has agreed to acquire the UK’s only ethylene dichloride asset, in addition to the remaining 50% share of Runcorn MCP Limited owned by Vynova Runcorn. This acquisition builds upon the integrated chemical production footprint of INEOS in the UK. |
| August-2026 | Reliance Industries and Rolls-Royce announced a strategic partnership to develop an indigenous combat-aircraft engine and Aerospace Gas Turbine Complex in India. Whilst this development enhances Reliance’s footprint in advanced material and industrial manufacturing, it is unrelated to glycols. |
| July-2026 | SABIC and Rongsheng Petrochemical have signed a Project Development Agreement for the Jintang New Materials Project in China. SABIC is considering an equity investment of up to 50% in Rongsheng New Materials, enhancing the company’s position as a producer of advanced petrochemical materials in the region. |
Global Glycols Market Competitive Landscape
The Global Glycols Market is moderately competitive, with the largest chemical and petrochemical multinationals competing for dominance through extensive production networks, access to feedstocks, high-quality products, regional reach, and downstream diversification. Glycols market leaders include BASF SE, Dow Inc., SABIC, Shell plc, Reliance Industries Limited, LyondellBasell Industries N.V., INEOS Group Limited, LG Chem Ltd., Mitsubishi Chemical Group Corporation, and Indorama Ventures which dominate the market due to their extensive production capacities and the presence in multiple downstream areas of the industry. The overall demand for glycols is driven by the need for polyester, PET packaging, automotive, textile, HVAC, food processing, cosmetic, industrial, and other applications.
As a result, firms focus on improving production efficiency, forming strategic partnerships, and ensuring access to raw materials to obtain higher production volumes, better raw materials, and greater downstream exposure. Thus, the leading companies’ efforts are directed toward lowering production costs and achieving an advantage over smaller rivals. In addition, companies attempt to differentiate their products by offering to downstream users more sustainable and high-performance products with a lower carbon footprint and higher purity levels. The most critical threat to producers comes from bio-based and circular economy entrants with compelling pricing proposals. The most crucial gap in the global glycols market is the value gap between traditional low-cost petrochemical products and more expensive sustainable products. Those firms which manage to decrease the cost of their sustainable products to approach the cost of petrochemical-based materials, will dominate the market.
The outlook for the glycols market is positive as demand rises due to increasing use in packaging, automotive, and textile applications. The growth will be driven by the need for high-quality products in the fastest-growing industry segments. It is anticipated that companies will continue to dominate the market by forming joint ventures, engaging in mergers and acquisitions, expanding production capacities, and focusing on high-growth products and regions to achieve greater downstream exposure and diversify their product offerings.
Glycols Market Scope: Inquire before buying
| Glycols Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | 42 USD Billion |
| Forecast Period 2026-2034 CAGR: | 6% | Market Size in 2034: | 70.92 USD Billion |
| Segments Covered: | by Product | Ethylene Glycol Mono-ethylene glycol Di-ethylene glycol Tri-ethylene glycol Propylene Glycol |
|
| by Application | Automotive HVAC Textiles Airline Medical Pipeline Maintenance Polyester Fibers & resin Food & Beverage Processing |
||
| by End User | Automotive and Transportation Packaging Food and Beverage Cosmetics Glycol Markets Textile |
||
Glycols Market, by Region:
North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (razil, Argentina Rest of South America)
Key Players:
1. BASF SE
2. Dow Inc.
3. SABIC
4. Shell plc
5. Exxon Mobil Corporation
6. China Petroleum & Chemical Corporation (Sinopec)
7. Reliance Industries Limited
8. LyondellBasell Industries N.V.
9. INEOS Group Limited
10. LG Chem Ltd.
11. Mitsubishi Chemical Group Corporation
12. LOTTE Chemical Corporation
13. Indorama Ventures Public Company Limited
14. Formosa Plastics Corporation
15. PTT Global Chemical Public Company Limited
16. EQUATE Petrochemical Company
17. ME Global International FZE
18. Indian Oil Corporation Limited
19. India Glycols Limited
20. Petro Rabigh
21. PETRONAS Chemicals Group Berhad
22. Sumitomo Chemical Co., Ltd.
23. Eastman Chemical Company
24. Huntsman Corporation
25. Wanhua Chemical Group Co., Ltd.
26. Celanese Corporation
27. Chevron Phillips Chemical Company LLC
28. Repsol S.A.
29. Manali Petrochemicals Limited
30. Sasol Limited
31. Kuwait Petroleum Corporation
32. China Sanjiang Fine Chemicals Company Limited
33. SKC Ltd.
34. Asahi Kasei Corporation
35. PetroChina Company Limited
36. Shandong Shida Shenghua Chemical Group Co., Ltd.
37. PCC Rokita S.A.
38. Cargill Incorporated
39. Oleon NV
40. Arkema S.A.
Frequently Asked Questions:
1. What is the current size of the Global Glycols Market
The Global Glycols Market was valued at USD 42 Billion in 2025 and is projected to reach USD 70.92 Billion by 2034, growing at a CAGR of 6% during the forecast period 2026–2034.
2. What are the key factors driving the Global Glycols Market
The market growth is driven by rising demand from polyester, PET packaging, automotive, textile, industrial fluids, and specialty applications.
3. Which application segment holds the largest share of the Global Glycols Market
Polyester Fibers & Resin dominates the market due to significant usage of ethylene glycol in polyester and PET production.
4. Which region dominates the Global Glycols Market
Asia Pacific region accounted largest share in the Global Glycols Market due to highly developed chemical, textile, automotive and PET industry in China, India, Japan and South Korea.
5. Who are the major players operating in the Global Glycols Market
Key players include BASF SE, Dow Inc. SABIC, Shell plc, Exxon Mobil Corporation, PCC Rokita S.A., Cargill Incorporated, Oleon NV, Arkema S.A.