Chewing Gum Market - Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034

2.01%
CAGR (2026-2034)
18.86 USD Bn.
Forecast Market Size
307
Report Pages
159
Market Tables

Overview

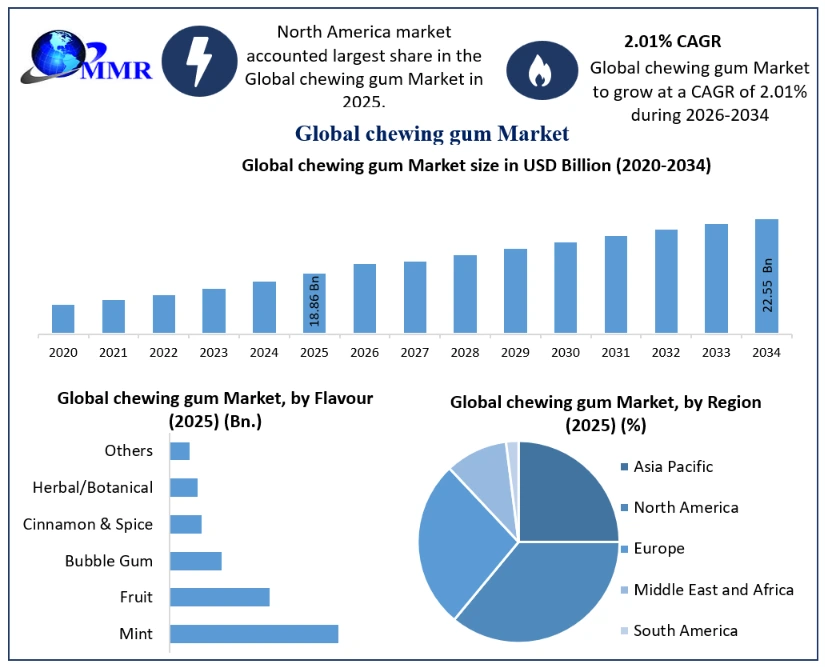
The Chewing Gum Market size was valued at USD 18.86 Billion in 2025 and the total Chewing Gum revenue is expected to grow at a CAGR of 2.01% from 2026 to 2034, reaching nearly USD 22.55 Billion in 2034.

The Chewing Gum operates the broader confectionery and fast-moving consumer goods (FMCG) industry, shaped by behavioral consumption patterns, socio-cultural influences, and innovation-driven product development. The Chewing Gum market is fundamentally driven by the psychological and sensory appeal of chewing, which is associated with refreshment, stress relief, habit-forming behavior, and social acceptance. Chewing gum functions as both a recreational product and a utilitarian item, creating dual demand from pleasure-seeking consumers and seeking functional benefits such as oral hygiene, energy enhancement, smoking cessation, or nutritional supplementation.

The Chewing Gum consumer behavior, where preference formation is influenced by taste, convenience, health perceptions, price sensitivity, and brand loyalty. The shift toward sugar-free and functional gums reflects the health belief model, where consumers choose products that align with preventive health behaviors. Additionally, the rise of natural, clean-label, and biodegradable gums aligns with theories of sustainable consumption and ethical purchasing, driven by environmental consciousness.

Chewing Gum Market Growth and Share Analysis
Chewing Market Growth Outlook

To know about the Research Methodology:-Request Free Sample Report

Chewing Gum Market Dynamics:

The global chewing gum market is undergoing a significant transformation driven by shifting consumer preferences, lifestyle changes, and continuous innovation across formulation, flavor, and functionality. One of the foremost developments shaping market dynamics is the rapid rise of sugar-free and functional chewing gums. With increasing global awareness about oral hygiene, dental health, and low-calorie intake, sugar-free chewing gum now accounts for nearly 58–60% of the total market share, up from 48% ten years ago. Consumers are choosing xylitol- and sorbitol-based formulations due to their proven dental benefits, including reduced cavity risks and enhanced salivary flow. Parallel to this shift, the market is witnessing unprecedented growth in functional gum categories such as nicotine gum, vitamin-infused gum, probiotic gum, energy gum, and CBD gum. These specialized products are supported by demand from health-conscious consumers, urban professionals, and individuals seeking convenient wellness formats. Such trends highlight the evolution of chewing gum from a traditional confectionery item to a multifunctional, on-the-go wellness product.

The major factor influencing the chewing gum market is the boom in flavor innovation and clean-label product development. Manufacturers are investing in new flavor combinations, long-lasting flavor technologies, and multi-layer gum formats to enhance consumer experience and strengthen brand differentiation. Fruit, mint, cooling-effect, and hybrid flavors dominate new global launches, driven by the preferences of younger demographics. Clean-label gum, which avoids artificial sweeteners such as aspartame and synthetic plasticizers, is gaining substantial traction in developed markets such as the United States, Germany, France, Japan, and the Nordic region, where natural ingredients are increasingly valued. These natural gums are contributing to the growth of eco-friendly chewing gum alternatives, with the biodegradable gum segment, presenting new opportunities for sustainability-driven manufacturers.

Production trends the competitive landscape of the global chewing gum market. Annual global production ranges between 1.7 and 1.9 million tonnes, dominated by multinational giants such as Mars Wrigley, Mondelez International, Perfetti Van Melle, Lotte Confectionery, and Ferrero. These companies collectively hold 55–60% of global market share, supported by advanced manufacturing capabilities, extensive product portfolios, international distribution networks, and long-established brand recognition. The United States leads production with an estimated 580,000–600,000 tonnes annually, particularly in sugar-free and functional gum categories. China, producing around 320,000–350,000 tonnes, is a major global exporter and a key supplier for Asia-Pacific markets. Turkey, Mexico, and select European countries remain important production hubs due to their cost-efficient manufacturing bases and strategic export capabilities.

Price dynamics play a critical role in shaping profitability and market competitiveness. In 2025, average global prices ranged between USD 3.2 and 5.5 per kg for standard chewing gum, USD 4.5–7.2 per kg for sugar-free gum, and USD 11–18 per kg for functional gum variants. Premium natural gum products, including plant-based gum bases, fetch USD 12–16 per kg due to higher production costs and niche demand. Raw material price fluctuations—particularly in natural sweeteners and mint oils—have affected production economics. Xylitol prices increased by 6–8% in late 2024, primarily due to limited birchwood supply in Finland and China. Similarly, mint oil prices showed volatility after lower-than-expected crop yields in India, which supplies nearly 80% of the world’s mint oils. These fluctuations have encouraged manufacturers to adopt cost-optimization strategies, alternative sweetener blends, and more efficient packaging solutions.

Evolving consumer behavior is among the core drivers reshaping demand patterns. Young consumers, particularly teens and young adults, represent 45–48% of global gum consumption, preferring innovative flavors, sensory cooling effects, and interactive product formats. With growing concern over sugar content and oral hygiene, a substantial portion of consumers in urban markets now opt for sugar-free gum after meals, supported by dental associations worldwide. The rise of “on-the-go freshness” lifestyles has also boosted demand for pocket-sized packs and mini-format gums, which have grown 18–20% year-on-year. Meanwhile, smoking reduction trends have propelled the rapid growth of nicotine gum, expanding at 10–12% CAGR, supported by smoking cessation programs and increasing health awareness. The trend toward mindful snacking is pushing consumers away from high-calorie sweets toward healthier chewing alternatives, reinforcing long-term growth prospects for the chewing gum industry.

Global trade patterns underscore the increasing demand for value-added gum products across international Chewing Gum market. Turkey emerged as the world’s largest exporter in 2025–2026, with export revenues of USD 475–520 million, followed by the United States with USD 420–460 million, China with USD 310–335 million, and the Netherlands, which recorded USD 190–210 million. Countries in Southeast Asia, Africa, and Latin America are becoming rapidly expanding import markets due to growing urban populations, Western-style retail formats, and rising demand for affordable yet high-quality confectionery products. Functional gums—particularly nicotine, vitamin, and energy variants are becoming the fastest-growing export segment, presenting strong opportunities for manufacturers investing in R&D and technological innovation.

Chewing Gum Market Segment Analysis:

Based On Flavour: The global chewing gum market is segmented by flavour into Mint, Fruit, Bubble Gum, Cinnamon & Spice, Herbal/Botanical, and Others. Mint remains a highly preferred flavour due to its refreshing taste, cooling sensation, and association with oral freshness. Fruit flavours, including strawberry, watermelon, apple, and citrus, attract consumers seeking sweet and fruity experiences. Bubble gum flavours appeal particularly to younger consumers through their sweet taste and nostalgic appeal. Cinnamon and spice variants offer distinctive sensory experiences, while herbal and botanical flavours, including eucalyptus and plant-based extracts, support demand for alternative flavour profiles. Product innovation, changing consumer preferences, sugar-free formulations, and longer-lasting flavour technologies continue to influence flavour diversification.

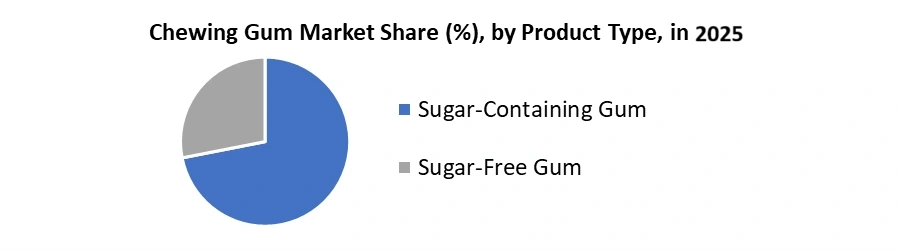
Based On Sugar Content: Sugar-free gum remained the dominant and fastest-growing segment in 2025, accounting for more than 55–60% of the global market. Its leadership was supported by strong consumer preference for oral-care benefits, lower calories, and dentist-endorsed ingredients such as xylitol. The segment benefited from lifestyle shifts toward preventive health, sugar reduction, and functional products. Innovations such as long-lasting flavours, whitening agents, vitamin-infused gums, and natural sweeteners further strengthened its appeal. Sugar-free gum also gained traction through supermarkets, pharmacies, and online platforms. With rising health consciousness, this segment consistently outperformed traditional sugar-containing variants.

Sugar-containing gum dominated the traditional and legacy segment of the chewing gum market in 2024. Its demand driven due to strong penetration in developing countries, affordable pricing, and a wide variety of sweet flavours targeted at children and younger consumers. The segment continued to hold relevance due to impulse purchases at convenience stores and cultural preferences for sugary products. However, its growth had slowed significantly as global consumers became more aware of the negative health effects linked to sugar intake and dental decay. Increasing oral-health awareness campaigns, rising regulatory pressure on sugar consumption, and the growing popularity of healthier snacking habits further reduced demand. The sugar-containing gum-maintained importance in regions such as Asia, Latin America, and the Middle East, it increasingly lost share to healthier alternatives.Chewing-Gum-Market-by-Product-Type
Chewing Gum Market Regional Analysis:

North America is the dominant market with a 33–35% share in 2025, supported by high per capita consumption and strong demand for sugar-free and functional gum products. Europe, accounting for 27–29%, shows stable growth, driven by premium and natural gum offerings. The Asia-Pacific region, with a 26–28% market share, is forecast to be the fastest-growing region, supported by rising disposable incomes, rapid urbanization, and increasing consumer interest in flavored and sugar-free chewing gum. Markets such as India, China, Indonesia, and Vietnam display strong upward trends, while Japan and South Korea lead in consumption of wellness-oriented mouth-freshening gums. Latin America and the Middle East & Africa contribute modest shares, rapid expansion of modern retail and increasing exposure to Western confectionery trends are creating new sales opportunities.

Competitive Landscape:

The chewing gum market characterized by strong consolidation, with a few global players dominating share through extensive distribution networks, brand loyalty, and continuous product innovation. Key companies such as Mars Wrigley, Mondelez International, Perfetti Van Melle, Lotte Confectionery, and Cloetta held leadership positions. These firms competed through flavour innovation, sugar-free formulations, long-lasting taste technologies, and functional gum offerings such as oral-care and nicotine-replacement gums. Regional players in Asia and Latin America expanded their presence through affordable price points and localized flavours. Sustainability, clean-label ingredients, and natural gum bases increasingly shaped competitive strategies.

Chewing Gum Market Recent Industry Developments

Date Company Development Impact
22 October 2025 Mars Wrigley Mars Wrigley showcased its 2026 gum innovation pipeline, including the upcoming 5® Gum EVOLUTION flavor-changing chewing gum, at the NACS Show Expo 2025. The preview reinforced the company's innovation-led strategy to drive premiumization and consumer engagement in the global chewing gum market.
27 March 2026 Mars Snacking Mars Snacking announced a US$100 million expansion of its Chicago headquarters to support its confectionery and gum business operations. The investment strengthens R&D, innovation, and commercial capabilities for iconic chewing gum brands such as Orbit, Extra, Doublemint, and 5 Gum.
21 April 2026 Mars Wrigley Mars Wrigley officially launched 5® Gum EVOLUTION, the brand's first flavor-changing chewing gum that transitions from a sour taste to layered berry flavors. The launch expands the premium gum portfolio through product differentiation and sensory innovation, supporting category growth.
14 April 2026 GUD GUM GUD GUM reported significant commercial growth after expanding its plastic-free, biodegradable chewing gum business across the Indian market. The expansion highlights the growing demand for sustainable chewing gum alternatives and encourages innovation in eco-friendly formulations.


Scope of the Global Chewing Gum Market: Inquire before buying

Chewing Gum Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: USD 18.86 Billion
Forecast Period 2026-2034 CAGR: 2.01% Market Size in 2034: USD 22.55 Billion
Segments Covered: by Product Type Chewing Gum
Bubble Gum
by Sugar Content Sugar-Based
Sugar-Free
by Flavour Mint
Fruit
Bubble Gum
Cinnamon & Spice
Herbal/Botanical
Others
by Product Format Sticks
Pellets/Tabs
Balls
Cubes/Pieces
Liquid-Filled
Others
by Consumer Age Children
Teenagers
Young Adults
Adults
Seniors
by Distribution Channel Supermarkets & Hypermarkets
Convenience Stores
Traditional/Grocery Retail
Specialty Stores
Pharmacies & Drugstores
Vending Machines
Online/E-Commerce
Others

Global Chewing Gum Market, by Region

Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe)
North America (United States, Canada and Mexico)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina Rest of South America)

Key Players / Competitors Profiles Covered in Brief in Global Chewing Gum Market Report in Strategic Perspective:

North America
1.Mars, Incorporated (Wrigley)
2.Mondelēz International, Inc.
3.The Hershey Company
4.The PUR Company Inc.
5.Simply Gum Inc.
6.Tootsie Roll Industries, Inc.
7.Ford Gum & Machine Co.
8.Kenvue Inc.

Europe
1.Perfetti Van Melle Group B.V.
2.Cloetta AB
3.Haribo GmbH & Co. KG
4.Gumlink Confectionery Company A/S
5.Ferrero International S.A.
6.Fini Company S.A.
7.Peppersmith
8.Yıldız Holding A.Ş.

Asia-Pacific
1.Lotte Corporation / LOTTE Wellfood Co., Ltd.
2.Meiji Holdings Co., Ltd.
3.Orion Corporation
4.Lotte India Corporation Limited
5.Ferndale Confectionery Pty Ltd
6.Ezaki Glico Co., Ltd.
7.Morinaga & Co., Ltd.

Middle East & Africa
1.Batook Holding Company
2.TopGum
3.MasterFoodeh Co.
4.Niger Biscuit Company Limited

South America
1.Grupo Arcor S.A.I.C.
2.Canel's S.A. de C.V.
3.Confiteca C.A.
4.Colombina S.A.
5.Fini Company S.A.
6.Chicza
7.Dulces de la Rosa S.A. de C.V.
8.Riclan S.A.
Others

Frequently Asked Questions

1. What is the projected Global Chewing Gum Market size and growth rate?
Ans. Valued at USD 18.86 Billion in 2025, the market reaches USD 22.55 Billion by 2034. Chewing Gum Market Trends 2026 show a steady 2.01% CAGR.

2. Which region leads the industry in Chewing Gum Share Analysis?
Ans. North America dominates with a 35% share, driven by high per capita consumption of functional variants. The United States leads global production, exceeding 580,000 tonnes.

3. What are the primary Industry Growth Drivers for sugar-free gum?
Ans. Rising dental health awareness and low-calorie preferences drive demand. Sugar-free formulations now hold a 60% market share, utilizing xylitol and sorbitol for oral hygiene benefits.

4. How is the demand for functional gum impacting the market?
Ans. Consumer interest in wellness fuels growth in nicotine, caffeine, and vitamin-infused gums. The nicotine segment alone expands at a 12% CAGR, boosting high-value exports.

5. What role does sustainability play in Global Chewing Gum Market Trends 2026?
Ans. Environmental consciousness drives the shift toward biodegradable, plastic-free bases. Clean-label, natural gums are gaining significant traction in developed markets like Germany, Japan, and France.

6. How do raw material price fluctuations affect global market profitability?
Ans. Volatility in xylitol and mint oil supplies impacts production economics. Manufacturers use cost-optimization strategies and alternative sweetener blends to maintain competitive pricing amid supply constraints.

7. What are the key consumer demographics driving innovation in flavors?
Ans. Younger demographics, representing 48% of consumption, demand cooling effects and hybrid flavors. This pushes brands toward multi-layer formats and innovative, long-lasting sensory technology developments.

Table of Contents

1. Executive Chewing Gum Market Landscape & Industry Overview 1.1 Global Chewing Gum Market Size (Value USD Mn & Volume in 000' Pieces), 2026–2034 1.2 Evolution from conventional gum toward functional chewing formats 1.3 Role of gum in confectionery and impulse consumption 1.4 Shifting consumer preferences toward sugar-free chewing gum products 1.5 Premiumization across flavors, formats, packaging, and ingredient profiles 1.6 Regional differences in chewing gum consumption and penetration 1.7 CAGR Analysis Chewing Gum Market (2025–2034) 2. Global Chewing Gum Market Dynamics 2.1 Market Trends 2.2 DROC Analysis 2.3 Drivers 2.4 Restraints 2.5 Opportunities 2.6 Challenges 2.7 PORTER'S Five Forces 2.8 PESTLE Analysis 3. Chewing Gum Cost Structure, Economics & Pricing Dynamics 3.1 Cost contribution of gum base and sweetener ingredients 3.2 Flavoring and functional ingredient costs across product formulations 3.3 Packaging material costs across major chewing gum formats 3.4 Manufacturing costs across conventional and specialized production lines 3.5 Distributor margins influencing retail chewing gum pricing structures 3.6 Premium pricing dynamics across functional and specialty gums 4. Chewing Gum Supply Chain & Ingredient Ecosystem 4.1 Procurement structure for gum bases and sweetening ingredients 4.2 Flavor supplier ecosystem supporting differentiated chewing gum formulations 4.3 Sourcing patterns for natural and synthetic flavor ingredients 4.4 Packaging suppliers supporting blister, bottle, pouch, and wrapper formats 4.5 Manufacturing dependencies affecting chewing gum production continuity 4.6 Distribution networks connecting manufacturers with retail consumption channels 5. Consumer Consumption & Demand Pattern Analysis 5.1 Chewing frequency across different consumer demographic groups 5.2 Consumption occasions spanning leisure, refreshment, and oral-care needs 5.3 Demand differences between sugar-free and sugar-containing products 5.4 Flavor preferences influencing repeat purchase behavior across markets 5.5 Functional benefits driving incremental chewing gum consumption 5.6 Seasonal and situational factors affecting category demand patterns 6. Chewing Gum Product Formulation & Ingredient Development 6.1 Gum base composition across conventional chewing gum formulations 6.2 Sweetener selection according to target consumer and product positioning 6.3 Flavor systems supporting long-lasting taste experiences 6.4 Functional ingredients targeting oral health and wellness benefits 6.5 Natural ingredient adoption across premium chewing gum formulations 6.6 Texture characteristics influencing chewability and consumer acceptance 7. Gum Base Technology & Manufacturing Process Evolution 7.1 Natural versus synthetic gum base utilization across products 7.2 Gum base processing technologies influencing texture and elasticity 7.3 Mixing processes integrating sweeteners, flavors, and functional ingredients 7.4 Extrusion technologies supporting standardized chewing gum production 7.5 Cooling and conditioning processes affecting final product characteristics 7.6 Manufacturing automation improving production consistency and operational efficiency 8. Sweeteners, Flavors & Functional Ingredient Ecosystem 8.1 Sugar and polyol sweetener usage across chewing gum 8.2 Sugar selection based on product positioning requirements 8.3 Sorbitol usage across sugar-free gum formulations 8.4 Xylitol adoption for oral-care chewing gum 8.5 Mannitol applications in specialized gum formulations 8.6 Polyol blends optimizing sweetness and texture performance 8.7 High-intensity sweeteners supporting reduced-calorie product formulations 8.8 Mint, fruit, herbal, and specialty flavor development 8.9 Natural flavor adoption across clean-label chewing gum products 8.10 Vitamins, minerals, and botanical ingredients in functional gums 8.11 Ingredient combinations supporting differentiated sensory and functional positioning 9. Packaging Formats, Materials & Shelf-Life Management 9.1 Stick, pellet, tablet, coated, and liquid-filled gum formats 9.2 Blister, bottle, pouch, carton, and wrapper packaging structures 9.3 Packaging material selection according to product protection requirements 9.4 Moisture and temperature management across chewing gum packaging 9.5 Portable packaging formats supporting convenience-oriented consumption occasions 9.6 Sustainability initiatives influencing chewing gum packaging material selection 10. Manufacturing Equipment & Production Infrastructure 10.1 Mixing and kneading equipment for gum base processing 10.2 Extrusion systems supporting continuous chewing gum production 10.3 Rolling and scoring equipment for stick-format products 10.4 Pelletizing and coating equipment for center-filled chewing gums 10.5 Cooling systems supporting texture stabilization during manufacturing 10.6 Automated packaging lines improving production speed and consistency 11. Product Innovation, Functional Benefits & Formulation Trends 11.1 Oral-care gums incorporating ingredients supporting dental health 11.2 Energy gums formulated with caffeine and stimulating ingredients 11.3 Vitamin-enriched gums targeting wellness-focused consumers 11.4 Nicotine-free functional concepts expanding specialized gum applications 11.5 Probiotic and botanical formulations supporting emerging wellness positioning 11.6 Long-lasting flavor technologies improving consumer product experience 12. Retail, Distribution & Chewing Gum Sales Channels 12.1 Supermarket and hypermarket distribution across developed consumer markets 12.2 Convenience-store sales supporting impulse chewing gum purchases 12.3 Independent retailers serving localized chewing gum demand 12.4 Pharmacies supporting functional and oral-care gum distribution 12.5 E-commerce platforms expanding specialty chewing gum accessibility 12.6 Vending channels supporting immediate consumption and impulse purchasing 13. Installed Manufacturing Base & Production Capacity Analysis 13.1 Existing chewing gum manufacturing facilities across major regions 13.2 Production capacity distribution among leading chewing gum manufacturers 13.3 Manufacturing footprint by product format and technology 13.4 Capacity utilization across established chewing gum production facilities 13.5 New production investments supporting regional demand expansion 13.6 Contract manufacturing capacity supporting emerging chewing gum brands 14. Production Volume, Utilization & Inventory Management 14.1 Chewing gum production volumes across major manufacturing regions 14.2 Capacity utilization trends among leading production facilities 14.3 Inventory turnover across manufacturers and distribution networks 14.4 Finished-product inventory management across seasonal demand cycles 14.5 Production scheduling according to flavor and format requirements 14.6 Supply balancing between domestic and export markets 15. Product Portfolio, Flavor Architecture & Premiumization Strategies 15.1 Flavor portfolio diversification across mint and fruit categories 15.2 Multi-layer and center-filled products supporting premium positioning 15.3 Sugar-free portfolios targeting health-conscious consumer segments 15.4 Premium ingredients supporting differentiated sensory experiences 15.5 Limited-edition flavors creating consumer engagement and trial 15.6 Brand extensions targeting specialized consumer preferences and occasions 16. Consumer Health, Oral Care & Regulatory Considerations 16.1 Dental benefits associated with sugar-free chewing gum consumption 16.2 Tooth-friendly sweeteners supporting oral-health product positioning 16.3 Ingredient safety requirements affecting chewing gum formulations 16.4 Labeling requirements for functional and nutritional product claims 16.5 Advertising restrictions influencing health-related chewing gum communications 16.6 Consumer awareness shaping demand for healthier gum alternatives 17. Regulatory Framework & Product Compliance Analysis 17.1 Food safety regulations governing chewing gum manufacturing processes 17.2 Permitted sweeteners and additives across major regional markets 17.3 Flavoring substance requirements affecting formulation and commercialization 17.4 Nutritional labeling standards for packaged chewing gum products 17.5 Health-claim regulations affecting functional chewing gum marketing 17.6 Import and export compliance requirements across international markets 18. Trade Flow, Import-Export & Regional Market Connectivity 18.1 Global chewing gum trade flows across major producing countries 18.2 Import dependency influencing regional chewing gum availability 18.3 Export-oriented manufacturing hubs serving international consumer markets 18.4 Cross-border distribution networks connecting major retail markets 18.5 Trade policies affecting confectionery ingredient and product movement 18.6 Logistics costs influencing international chewing gum competitiveness 19. Consumer Demographics, Preferences & Purchasing Behavior 19.1 Consumption patterns across children, adults, and older consumers 19.2 Gender differences influencing flavor and format preferences 19.3 Urban versus rural chewing gum consumption patterns 19.4 Health-conscious consumers driving sugar-free product adoption 19.5 Brand loyalty and switching behavior across competing products 19.6 Price sensitivity influencing chewing gum purchase decisions 20. Technology Innovation & Future Chewing Gum Development 20.1 Advanced flavor-release technologies extending sensory performance 20.2 Microencapsulation technologies improving functional ingredient delivery 20.3 Smart manufacturing systems optimizing production quality and efficiency 20.4 Novel gum bases supporting improved biodegradability and performance 20.5 Digital product development accelerating new flavor commercialization 21. Sustainability, Natural Ingredients & Environmental Impact 21.1 Natural gum base adoption supporting sustainable product positioning 21.2 Plant-derived ingredients across clean-label chewing gum formulations 21.3 Plastic reduction initiatives across packaging and production 21.4 Sustainable sourcing practices for key agricultural ingredients 21.5 Manufacturing waste reduction across chewing gum production facilities 21.6 Environmental considerations across product lifecycle and packaging disposal 21.7 Emerging formulations targeting evolving consumer wellness requirements 22. Global Chewing Gum Market Size and Forecast by Segmentation (by Value USD Million and Volume in 000' Pieces) (2025-2034) 22.1 Global Chewing Gum Market Size And Forecast, By Product Type 22.2 Chewing Gum 22.3 Bubble Gum 22.4 Global Chewing Gum Market Size And Forecast, By Sugar Content 22.5 Sugar-Based 22.6 Sugar-Free 22.7 Global Chewing Gum Market Size And Forecast, By Flavour 22.8 Mint 22.9 Fruit 22.10 Bubble Gum 22.11 Cinnamon & Spice 22.12 Herbal/Botanical 22.13 Others 22.14 Global Chewing Gum Market Size And Forecast, By Product Format 22.15 Sticks 22.16 Pellets/Tabs 22.17 Balls 22.18 Cubes/Pieces 22.19 Liquid-Filled 22.20 Others 22.21 Global Chewing Gum Market Size And Forecast, By Consumer Age 22.22 Children 22.23 Teenagers 22.24 Young Adults 22.25 Adults 22.26 Seniors 22.27 Global Chewing Gum Market Size And Forecast, By Distribution Channel 22.28 Supermarkets & Hypermarkets 22.29 Convenience Stores 22.30 Traditional/Grocery Retail 22.31 Specialty Stores 22.32 Pharmacies & Drugstores 22.33 Vending Machines 22.34 Online/E-Commerce 22.35 Others 22.36 Global Chewing Gum Market Size and Forecast, By Region & Country 22.37 North America 22.38 United States 22.39 Canada 22.40 Mexico 22.41 Europe 22.42 United Kingdom 22.43 France 22.44 Germany 22.45 Italy 22.46 Spain 22.47 Sweden 22.48 Russia 22.49 Rest of Europe 22.50 Asia Pacific 22.51 China 22.52 South Korea 22.53 India 22.54 Japan 22.55 Australia 22.56 Indonesia 22.57 Philippines 22.58 Malaysia 22.59 Vietnam 22.60 Thailand 22.61 Rest of Asia Pacific 22.62 Middle East & Africa 22.63 South Africa 22.64 Saudi Arabia 22.65 United Arab Emirates 22.66 Qatar 22.67 Kuwait 22.68 Bahrain 22.69 Oman 22.70 Egypt 22.71 Nigeria 22.72 Rest of Middle East & Africa 22.73 South America 22.74 Brazil 22.75 Argentina 22.76 Chile 22.77 Colombia 22.78 Rest of South America 23. Chewing Gum Market Competitive Landscape 23.1 Competitive Matrix 23.2 Key Player Benchmarking 23.3 Company Name 23.4 Headquarters 23.5 Chewing Gum Product Portfolio 23.6 Gum Base & Formulation Technology 23.7 Flavor & Sweetener Innovation 23.8 Functional & Oral Care Benefits 23.9 Product Format & Texture Variety 23.10 Packaging & Shelf-Life Performance 23.11 Manufacturing & Production Capacity 23.12 Retail & Distribution Partnerships 23.13 Revenue 23.14 Market Share 23.15 R&D Investment 23.16 Operating Margin 23.17 Year-on-Year Growth 23.18 Geographic Presence 23.19 Market Structure 23.20 Market Leaders 23.21 Market Followers 23.22 Emerging Players 23.23 Mergers & Acquisitions Details 23.24 Recent Key Developments 24. Company Profiles: Key Players 24.1 Overview 24.2 Business Portfolio 24.3 Financial Overview 24.4 SWOT Analysis 24.5 Strategic Analysis 24.6 Recent Developments 25. Global Chewing Gum Market Company Profiles: 35+ Key Players 25.1 Mars, Incorporated (Wrigley) 25.2 Mondelēz International, Inc. 25.3 The Hershey Company 25.4 The PUR Company Inc. 25.5 Simply Gum Inc. 25.6 Tootsie Roll Industries, Inc. 25.7 Ford Gum & Machine Co. 25.8 Kenvue Inc. 25.9 Perfetti Van Melle Group B.V. 25.10 Cloetta AB 25.11 Haribo GmbH & Co. KG 25.12 Gumlink Confectionery Company A/S 25.13 Ferrero International S.A. 25.14 Fini Company S.A. 25.15 Peppersmith 25.16 Yıldız Holding A.Ş. 25.17 Lotte Corporation / LOTTE Wellfood Co., Ltd. 25.18 Meiji Holdings Co., Ltd. 25.19 Orion Corporation 25.20 Lotte India Corporation Limited 25.21 Ferndale Confectionery Pty Ltd 25.22 Ezaki Glico Co., Ltd. 25.23 Morinaga & Co., Ltd. 25.24 Batook Holding Company 25.25 TopGum 25.26 MasterFoodeh Co. 25.27 Niger Biscuit Company Limited 25.28 Grupo Arcor S.A.I.C. 25.29 Canel's S.A. de C.V. 25.30 Confiteca C.A. 25.31 Colombina S.A. 25.32 Fini Company S.A. 25.33 Chicza 25.34 Dulces de la Rosa S.A. de C.V. 25.35 Riclan S.A. 25.36 Others 25.37 B4. Product Portfolio & Brand Strength Benchmarking 25.38 Brand portfolio breadth across chewing gum categories 25.39 Sugar-free product penetration across leading company portfolios 25.40 Functional gum offerings and health-oriented product positioning 25.41 Flavor diversity and differentiated product architecture 25.42 Premium product presence across developed consumer markets 25.43 New product launches and portfolio expansion strategies 26. Manufacturing Capacity & Production Technology Benchmarking 26.1 Manufacturing capacity comparison among leading gum producers 26.2 Production facility footprint across major geographic markets 26.3 Gum base processing technology capabilities across competitors 26.4 Coating, filling, extrusion, and packaging technology comparison 26.5 Manufacturing automation and production efficiency benchmarking 26.6 Capacity expansion and facility investment strategies 27. Ingredient Sourcing & Supplier Ecosystem Benchmarking 27.1 Gum base sourcing strategies across leading manufacturers 27.2 Sweetener procurement and supplier diversification approaches 27.3 Flavor ingredient sourcing across global production networks 27.4 Natural ingredient procurement supporting clean-label product development 27.5 Packaging material sourcing and supplier relationships 27.6 Supply-chain resilience and procurement risk management 28. Distribution, Retail Reach & Channel Performance Benchmarking 28.1 Retail distribution breadth across leading chewing gum brands 28.2 Convenience-store penetration across major consumer markets 28.3 Supermarket and hypermarket channel presence comparison 28.4 E-commerce distribution strategies across specialty product portfolios 28.5 Vending-machine presence and impulse-channel penetration 28.6 Distributor partnerships supporting regional market expansion 29. Marketing, Branding & Consumer Engagement Benchmarking 29.1 Brand positioning strategies across leading chewing gum companies 29.2 Advertising investment across major consumer demographics 29.3 Celebrity and influencer partnerships supporting brand visibility 29.4 Digital marketing strategies targeting younger consumers 29.5 Promotional campaigns supporting product trial and loyalty 29.6 Packaging differentiation supporting shelf visibility and recognition 30. Pricing, Premiumization & Commercial Strategy Benchmarking 30.1 Retail price positioning across competing chewing gum brands 30.2 Premium product strategies targeting higher-value consumer segments 30.3 Promotional pricing approaches across retail distribution channels 30.4 Pack-size strategies influencing consumer affordability and value 30.5 Functional benefits supporting premium pricing opportunities 30.6 Regional pricing differences across major chewing gum markets 31. Financial, Investment & Expansion Benchmarking 31.1 Revenue performance comparison among leading chewing gum companies 31.2 Profitability trends across major confectionery manufacturers 31.3 Capital investment in chewing gum production facilities 31.4 Research and development spending across leading companies 31.5 Acquisition and partnership activity across chewing gum industry 31.6 Geographic expansion strategies targeting emerging consumer markets 32. Key Findings 33. Strategic Moves & Industry Outlook 34. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements