
Protein Drugs Market Size – Industry Structure Evaluation, Demand Drivers Analysis, Regional Growth Analysis and Identification, Competitive Positioning Review & Global Market Size Forecast to 2034
Overview
The Protein Drugs Market Size was valued at USD 336.34 Billion in 2025 and is estimated to grow at a CAGR of 8.25% over the forecast period, reaching USD 686.48 Billion by 2034.
Protein Drugs Market Overview:
Protein therapies, which were once a small subgroup of medical interventions, have expanded drastically in quantity and frequency of usage since the release of the first synthetic protein therapeutic i.e. human insulin. Protein therapies are already playing an important role in practically every sector of medicine, yet they are still in their infancy.
Protein-based treatments are proving to be very effective in clinical trials, and their promise is being recognized at an unprecedented scale. More than 100 authentic and comparable recombinant protein therapeutics are available for clinical use in the European Union and the United States, with total sales of US$ 30 billion in 2025; monoclonal antibodies accounted for over 10 percent of total sales.
Newly designed proteins are constantly being developed, including biospecific medicines and multispecific fusion proteins, monoclonal antibodies coupled with small molecule medicines, and proteins with enhanced pharmacokinetics. However, there have been no theoretically novel procedural advancements in the recent few decades equivalent, for example, to gene editing leading to the production of innovative therapeutic proteins. To overcome fundamental hurdles such as tolerance to therapy, accessibility to targets, the intricacy of biomolecules, and individual variances, it seems that a paradigm shift in approaches and knowledge of processes is required.
In this report, the Protein Drugs market's growth reasons, as well as the market's many segments (Product, Application, Function, and Region), are discussed. Data has been given by market players, regions, and specific requirements. This market report includes a comprehensive overview of all the significant improvements that are presently prevailing in all market segments. Key data analysis is presented in the form of statistics, infographics, and presentations. The study discusses the Protein Drugs market's Drivers, Restraints, Opportunities, and Challenges. The report helps to assess the market growth drivers and determines how to use these drivers as a tool. The report also helps to rectify and resolve issues related to the global Protein Drugs market situation.
Protein Drugs Market Size, Growth & Share Analysis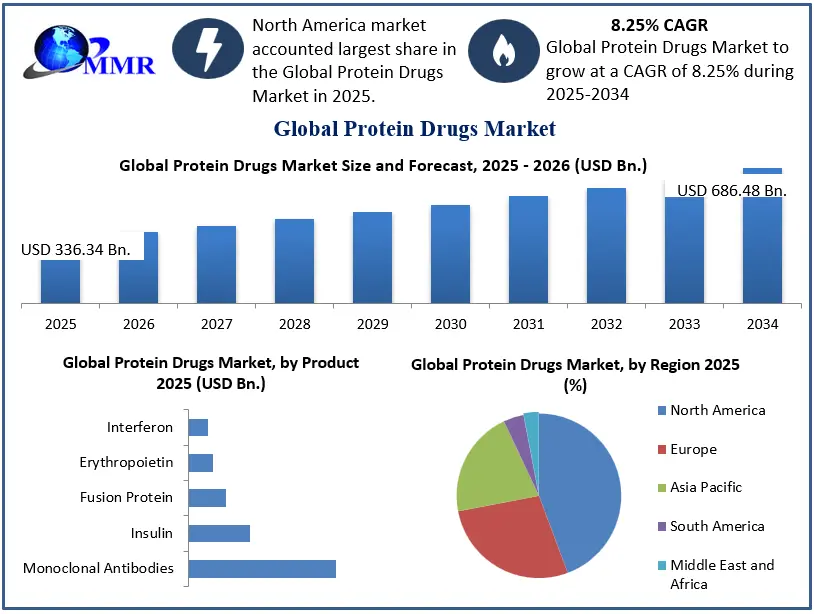
To know about the Research Methodology :- Request Free Sample Report
Protein Drugs Market Dynamics:
One of the major drivers of the market is growing government financing and research and development spending in pharmaceutical and biotechnology firms.
The R&D business has traditionally been investment-intensive due to substantial investigations and licensing procedures. Technology investments are at the top of the worldwide spending list. Governments see Investments in research and development as an essential component of a country's growth, global competitiveness, and public welfare. As a result, R&D spending and financing have steadily increased throughout the years. The global life science research and innovation spending is expected to increase by 4.1 percent to USD 2.7 trillion by 2025, as per the 2025 Global Research and innovation Funding Forecast. While the industry is the primary source of research and innovation financing, academia is equally important since research articles are written by academics.
A major restraint of the market is that the cost of recombinant proteins is decreasing.
Whenever a growing number of firms enter a narrow market and provide comparable items with little uniqueness, price erosion occurs. In this situation, the price of such items has been found to consistently fall, slowing market growth. Progress in the field of recombinant protein manufacturing has reversed the previous trend, increasing output while decreasing cost, allowing such proteins to be produced on an industrial scale, and opening the door to the treatment of a wide range of illnesses and disorders.
Next-Generation Protein Engineering Creates New Drug Opportunities
Advances in protein engineering are creating opportunities to develop therapies with improved half-life, greater target selectivity, and multiple biological functions. Bispecific antibodies, fusion proteins, engineered enzymes, and other multifunctional protein formats are opening applications across oncology, autoimmune disorders, metabolic diseases, and rare diseases.
High Manufacturing Complexity Limits Cost Efficiency
Protein drugs require specialized production systems, controlled biological processes, purification, formulation, and quality testing. Complex proteins can also experience aggregation, instability, or changes in biological activity, making consistent large-scale production difficult.
| Current Market Trend | Present Market Direction |
| Longer-Acting Protein Therapies | Drug developers are putting greater emphasis on proteins that remain active for longer periods, allowing less frequent administration. The 2026 approval of once-weekly insulin icodec in the United States is a clear example of this shift toward reducing the treatment burden for patients. |
| Growth of Engineered Protein Formats | Protein drugs are moving beyond conventional molecules toward engineered formats such as bispecific antibodies, fusion proteins, nanobodies, and other multifunctional designs. These formats allow developers to combine targeting or biological functions within a single therapy. |
| Patient-Friendly Drug Delivery | Convenience is becoming an important part of protein drug development. Companies are working on high-concentration formulations, self-administration devices, wearable systems, and alternative administration routes to make long-term treatment easier for patients. |
| Oral Delivery of Protein Medicines | Oral administration remains a major research direction because it could reduce dependence on injections. However, protein absorption through the digestive system remains technically difficult, so current development is becoming more selective about which molecules are suitable for oral delivery. |
| Biosimilar Competition in Mature Protein Drugs | More biosimilars are entering established protein-drug categories, particularly where patent protection has ended. United States approvals in 2026 already include biosimilars for insulin, rituximab, ranibizumab, golimumab, pegfilgrastim, and other biological medicines. |
| More Targeted Protein Treatments | Protein drugs are increasingly being designed around specific disease pathways and patient groups rather than relying only on broad biological activity. This is particularly relevant in cancer, autoimmune disorders, metabolic diseases, and rare diseases. |
| Manufacturing Designed Alongside the Drug | Manufacturers are giving more attention to cell-line engineering, production systems, formulation, stability, and manufacturability earlier in development. This is helping companies address the practical production challenges of complex protein molecules before late-stage commercialization. |
| Shift Toward Home-Based Treatment | Protein therapy development is increasingly considering how treatment can move from hospitals and clinics to the patient's home. Weekly dosing, self-injection devices, and easier-to-use formulations are supporting this change, particularly for chronic diseases requiring long-term treatment. |
Protein Drugs Market Segment Analysis:
By Product, the insulin segment is expected to grow at the fastest CAGR of 3.3% in the aforementioned forecast period. Diabetes is widely seen as a habits-related illness. With the growth in population throughout the world, the condition's prevalence has risen dramatically over time. Approximately 110 million individuals worldwide use insulin, including all patients with Type 1 diabetes and 10-20 percent of individuals with Type 2 diabetes. Even though insulin has been used to control diabetes for over 90 years, more than half of individuals who require it today cannot purchase or obtain it. Insulin treatment, which maintains blood sugar levels combined with insulin, nutrition, and lifestyle, is required for patients with Type 1 diabetes to avoid complications.
North America, particularly the United States, dominates the worldwide human insulin sector, mainly due to the country's high incidence of diabetes as a result of lifestyle choices. The cost aspect is a key problem in the United States since the country generates over half of the insulin income for the makers. The United States is the world's largest seller of long-acting insulin, Lantus. The bulk of diabetic medicine manufacturers sees the region as a vital market for increasing overall worldwide sales. Lantus is the most commonly used basal insulin in the world, with the largest chunk of the market in the United States.
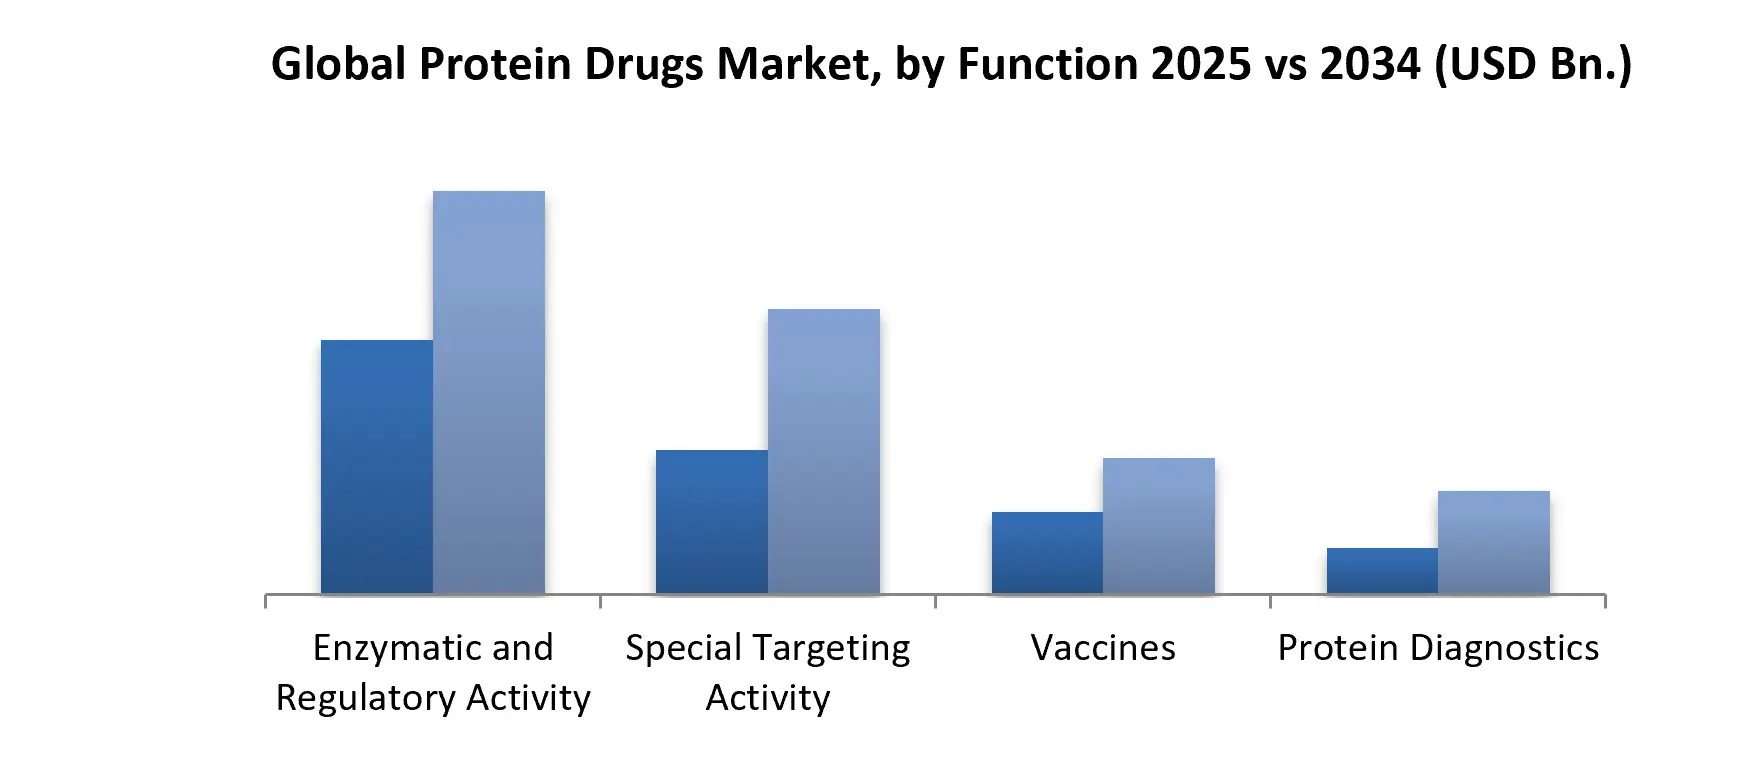
By Function, the Enzymatic and Regulatory Activity segment is currently the leading segment in the Protein Drugs Market and is also showing strong demand across therapeutic applications. This segment benefits from the broad role of protein-based therapies in replacing deficient proteins, regulating biological pathways, and supporting metabolic functions. Special Targeting Activity is another important and technology-driven segment, supported by the increasing use of monoclonal antibodies and other targeted protein therapies in cancer and immune-related diseases. Vaccines continue to maintain significant demand because protein-based vaccine platforms support preventive healthcare and infectious-disease control. Protein Diagnostics is gaining attention as healthcare providers increasingly focus on early disease detection, biomarker identification, and treatment monitoring. Current market analysis identifies enzymatic and regulatory activity as the largest function segment, with one recent estimate placing its 2025 share at 48.2%.
Protein Drugs Market Regional Insights:
North America is the leading region in the Protein Drugs Market, supported by a mature biotechnology ecosystem, high adoption of biologic medicines, strong pharmaceutical research activity, and extensive treatment demand for cancer, diabetes, and immune-related conditions. The United States accounts for the majority of regional activity because of its large pharmaceutical industry, advanced clinical infrastructure, and strong commercial presence of protein-drug manufacturers. High-value monoclonal antibodies and insulin therapies remain particularly important to regional revenue.
Europe holds the second-largest regional position, with established pharmaceutical manufacturing, strong regulatory systems, and broad use of biological medicines across major healthcare markets. Germany, France, the United Kingdom, Italy, and Spain provide an important base for protein-drug consumption and research. The region is also seeing greater use of biosimilars, which is influencing pricing, treatment access, and competition among established biological drug suppliers.
Asia Pacific is the fastest-growing region in the Protein Drugs Market, driven by rising healthcare expenditure, a large patient population, increasing investment in biotechnology, and stronger domestic production capabilities. China, Japan, India, and South Korea are particularly important to the regional market. China is strengthening its biologics pipeline, while India is gaining importance in cost-efficient manufacturing and biosimilar production. These developments are increasing access to protein-based treatments beyond traditional pharmaceutical markets.
South America is an emerging regional market, with Brazil and Argentina representing important demand centers. Increasing healthcare requirements, wider availability of biological medicines, and efforts to improve access to advanced treatments are supporting regional adoption. However, differences in healthcare budgets, reimbursement availability, and access to specialized therapies continue to influence the pace of market development across individual countries.
Middle East and Africa represents a developing regional market, where demand is being supported by improving healthcare infrastructure, government-led healthcare programs, and increasing attention toward specialty medicines. Countries such as Saudi Arabia, the United Arab Emirates, and South Africa are important contributors, particularly as healthcare systems invest in advanced treatment capabilities. Nevertheless, uneven access to biologic medicines, affordability constraints, and specialized storage requirements remain important considerations for suppliers.
Global Protein Drugs Competitive Landscape
The Protein Drugs Market has a highly competitive structure, with established pharmaceutical and biotechnology companies competing through protein engineering, monoclonal antibodies, insulin therapies, recombinant proteins, biosimilars, targeted biologics, and next-generation drug delivery technologies. Roche, Amgen, Eli Lilly, Novo Nordisk, Sanofi, Pfizer, Johnson & Johnson, Merck & Co., AstraZeneca, AbbVie, Novartis, and Biogen remain prominent participants because of their broad protein-drug portfolios, research capabilities, manufacturing capacity, and established commercial networks. Competition is increasingly shifting from simply introducing new protein medicines toward improving clinical effectiveness, dosing frequency, treatment convenience, manufacturing efficiency, and product differentiation. Novo Nordisk and Eli Lilly are particularly active in metabolic and obesity-related protein therapies, while Roche, Amgen, AstraZeneca, Merck & Co., and Johnson & Johnson maintain strong positions across oncology and immune-related biological treatments. At the same time, companies such as Biocon, Celltrion, Sandoz, Teva Pharmaceuticals, and Intas Pharmaceuticals are strengthening the biosimilar side of the market, creating additional pricing pressure for mature biological products. Strategic partnerships, licensing agreements, pipeline acquisitions, biosimilar launches, and investment in advanced protein platforms are therefore becoming important competitive strategies.
Protein Drugs Market Recent Development:
| Month | Company | Recent Development |
| January 2026 | Sanofi | Sanofi received priority review from the United States Food and Drug Administration for Tzield (teplizumab), a monoclonal antibody, seeking to extend its use to children aged one year and older with stage 2 type 1 diabetes. |
| January 2026 | AstraZeneca | AstraZeneca entered a collaboration with CSPC Pharmaceuticals covering eight obesity and type 2 diabetes programs, including a clinical-ready long-acting peptide candidate and monthly dosing technology. |
| January 2026 | Eli Lilly and Company | Eli Lilly's sofetabart mipitecan received Breakthrough Therapy designation for certain patients with platinum-resistant ovarian cancer. The treatment is an antibody-drug conjugate designed to deliver a therapeutic payload to folate receptor alpha-positive cancer cells. |
| February 2026 | Novo Nordisk | Novo Nordisk partnered with Vivtex to develop next-generation oral peptide and protein medicines for obesity and diabetes, using oral formulation technology intended to improve biological drug absorption. The agreement provides for potential payments of up to USD 2.1 billion plus royalties. |
| March 2026 | Novo Nordisk | Novo Nordisk announced United States approval of Awiqli (insulin icodec), making it the first once-weekly basal insulin approved by the United States Food and Drug Administration for adults with type 2 diabetes. |
| March 2026 | GSK | GSK completed its acquisition of RAPT Therapeutics, adding ozureprubart, a long-acting anti-immunoglobulin E monoclonal antibody in Phase IIb development for protection against food-allergy reactions, to its development portfolio. |
| June 2026 | Sanofi | Sanofi received accelerated United States approval for Tzield in children aged 8 to 17 years recently diagnosed with stage 3 type 1 diabetes. The therapy is intended to delay the decline of the body's own insulin production. |
Protein Drugs Market Scope: Inquire before buying
| Global Protein Drugs Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 336.34 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 8.25% | Market Size in 2034: | USD 686.48 Bn. |
| Segments Covered: | by Product | Monoclonal Antibodies Insulin Fusion Protein Erythropoietin Interferon |
|
| by Application | Metabolic Disorders Immunologic Disorders Hematological Disorders Cancer Genetic Disorders Hormonal Disorders |
||
| by Function | Enzymatic and Regulatory Activity Special Targeting Activity Vaccines Protein Diagnostics |
||
| by Region | North America (United States, Canada and Mexico) Europe (UK, France, Germany, Italy, Spain, Sweden, Austria and Rest of Europe) Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Malaysia, Vietnam, Taiwan, Bangladesh, Pakistan and Rest of APAC) Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A) South America (Brazil, Argentina Rest of South America) |
||
Protein Drugs Market, Key Players are:
1. Abbott Laboratories
2. AbbVie Inc.
3. Amgen Inc.
4. AstraZeneca PLC
5. Baxter International Inc.
6. Bayer AG
7. Biocon Limited
8. Biogen Inc.
9. Bristol Myers Squibb Company
10. Boehringer Ingelheim International GmbH
11. CSL Limited
12. Eli Lilly and Company
13. F. Hoffmann-La Roche AG
14. Genentech Inc.
15. Gilead Sciences, Inc.
16. GlaxoSmithKline plc
17. Johnson & Johnson
18. Merck & Co., Inc.
19. Merck KGaA
20. Novartis AG
21. Novo Nordisk A/S
22. Pfizer Inc.
23. Sanofi S.A.
24. Teva Pharmaceutical Industries Ltd.
25. Takeda Pharmaceutical Company Limited
26. Regeneron Pharmaceuticals, Inc.
27. Chugai Pharmaceutical Co., Ltd.
28. Kyowa Kirin Co., Ltd.
29. Grifols, S.A.
30. Fresenius Kabi AG
31. Sandoz Group AG
32. Celltrion Inc.
33. Samsung Bioepis Co., Ltd.
34. Boehringer Ingelheim Biopharmaceuticals
35. Lonza Group AG
36. WuXi Biologics
37. FUJIFILM Biotechnologies
38. Thermo Fisher Scientific Inc.
39. Shanghai Fosun Pharmaceutical Group Co., Ltd.
40. Hualan Biological Engineering Inc.
41. Panacea Biotec Ltd.
42. GeneScience Pharmaceuticals Co., Ltd.
43. Generex Biotechnology Corporation
44. Oramed Pharmaceuticals Inc.
45. Diasome Pharmaceuticals, Inc.
46. ADMA Biologics, Inc.
47. BioNTech SE
48. Ipsen Pharma
49. Intas Pharmaceuticals Ltd.
50. UCB S.A.
Frequently Asked Questions
1. Which is the potential market for Protein Drugs in terms of the region?
Ans. The North America is expected to offer significant growth opportunities to market players in the forecast period.
2. What are the restraints for new market entrants?
Ans. A major restraint of the market is that the cost of recombinant proteins is decreasing.
3. What is expected to drive the growth of the Protein Drugs market in the forecast period?
Ans. One of the major drivers of the market is growing government financing and research and development spending in pharmaceutical and biotechnology firms.
4. What is the projected market size & growth rate of the Protein Drugs Market?
Ans. Protein Drugs Market size was valued at USD 336.34 Bn. in 2025 and the total Protein Drugs revenue is expected to grow at 8.25% through 2026 to 2034, reaching nearly USD 686.48 Bn.
5. What segments are covered in the Protein Drugs Market report?
Ans. The segments covered are Product, Application, Function, and Region.