
Defense Navigation Market Size by Platform Type, Application, Technology, Region, Industry-Wide Analysis, Competitive Landscape Assessment & Long-Term Forecast to 2034
Overview
The Defence Navigation Market size was valued at USD 320.90 Bn. in 2025, and the total Defence Navigation Market revenue is expected to grow at a CAGR of 8.36% from 2026 to 2034, reaching USD 660.98 Bn. by 2034.
Defense Navigation Market Overview
The defense navigation comprises advanced systems such as GPS, inertial navigation (INS), and fiber optic gyros, enabling precise positioning, navigation, and timing (PNT) for military aircraft, naval vessels, and unmanned platforms.
The Defense navigation market is growing due to increasing defense modernization programs, rising demand for unmanned combat systems, and the need for resilient PNT solutions amid GPS vulnerabilities. Growing investments in naval and aerial platforms, mainly in Europe and North America, are driving demand, while supply is bolstered by innovations in AI, quantum navigation, and anti-jamming technologies.
North America dominated with 38.95% market share in 2025, growing by U.S. defense contracts and fleet upgrades, while Europe benefits from indigenous R&D led by firms like BAE Systems and Thales. Key players like Northrop Grumman, Raytheon, and Honeywell lead through cutting-edge R&D and strategic partnerships. Trade policies and export controls, mainly on dual-use technologies, impact market dynamics, with end-users like navies and air forces prioritizing precision and cybersecurity in navigation systems.
The report covered the Defense Navigation Market dynamics, structure by analyzing the market segments and projecting the Defense Navigation Market size. Competitive analysis of key players by type, price, financial position, product portfolio, growth strategies, and regional presence in the Defense Navigation Market.
Defence Navigation Market Size, Growth & Share Analysis

To know about the Research Methodology :- Request Free Sample Report
Defense Navigation Market Dynamics
The MMR report covers all the trends and technologies playing a major role in the growth of the Defense Navigation Market over the forecast period. It highlights the drivers, restraints, and opportunities expected to impact the market growth during 2026-2034.
| Dynamics Factor | Description |
| Driver | Technological innovations and growing maritime security requirements are driving demand for advanced defence navigation systems. |
| Restraint | High development, integration, and maintenance costs limit the adoption of advanced military navigation technologies. |
| Opportunity | Alternative positioning, navigation, and timing technologies create opportunities for reliable navigation in GPS-denied environments. |
| Challenge | Cyberattacks targeting electronic navigation and connected shipboard systems threaten operational reliability and data security. |
Technological Innovations and Maritime Security to Drive Defense Navigation Market Growth
In the previous few years, the Defense Navigation Market has been greatly influenced by copious changes in technology. Companies, along with governments, are consistently working on innovating new technologies to increase efficiency. For example, augmented reality applications in marine navigation systems are a key upcoming trend in the market. Seas and oceans cover more than 70% of the global surface. With the increasing awareness of seaborne navigation and safety, there have been extensive developments on the marine navigation system front, due to which the global market has gained momentum. Factors such as growing emphasis on maritime security and subsequent increase in naval budgets worldwide, surge in international seaborne trade, and rise in coastal and maritime tourism are the prime driving factors of the Defense Navigation Market.
High Development and Integration Costs to Restrain Defence Navigation Market Growth
The high cost of developing, procuring, integrating, and maintaining advanced navigation systems can restrain the growth of the Defence Navigation Market. Military-grade inertial navigation systems, anti-jamming receivers, encrypted satellite navigation equipment, and integrated positioning, navigation, and timing solutions require specialized components, extensive testing, and strict reliability standards. Integrating these technologies into existing aircraft, naval vessels, ground vehicles, and unmanned platforms can also require costly hardware modifications and software upgrades. Furthermore, the need for regular calibration, component replacement, and long-term technical support increases lifecycle expenses. These financial and technical requirements can delay procurement decisions, particularly for defence organizations operating under limited budgets.
Alternative Positioning Technologies to Create Lucrative Opportunities in the Defence Navigation Market
The growing need for reliable navigation in GPS-denied environments is creating opportunities for manufacturers of alternative positioning, navigation, and timing technologies. Defence organizations are increasingly exploring inertial sensors, celestial navigation, magnetic navigation, terrain-referenced systems, and signals from alternative satellite networks to maintain operational accuracy when conventional GPS signals are disrupted. According to the U.S. Government Accountability Office, the Department of Defence has investigated two broad approaches to alternative positioning, navigation, and timing: improved sensors that provide relative positioning information and external sources that provide absolute positioning information. Combining multiple technologies can improve navigation resilience across military aircraft, naval platforms, guided systems, and autonomous vehicles. Investment in sensor fusion, compact navigation components, and interoperable system architectures is therefore expected to create opportunities for defence technology suppliers during the forecast period..
The Vulnerability of Electronic Navigation Systems to Cyber-Attacks Hinders the Defense Navigation Market Growth:
Shipboard systems are susceptible to a cyber-attack. Modern technologies have integrated IT (Information Technology) and OT (Operational Technology) onboard ships through networking and connectivity to the internet. However, there is no real segregation between the IT and OT networks. There are some issues, like hackers trying to disrupt ships’ electronics/computers or steal sensitive information. The impact of these kinds of attacks could be enormous. It has been noted that successful IT network hacks have their origins in the initial penetration of the OT system. To gain remote access to the IT or OT systems, the satellite, 4G, or Wi-Fi connections of the vessel must be breached. Concerning security, time is a complicating factor.
Defence Navigation Market Key Trends
| No. | Market Trend | Description |
| 1 | GPS Anti-Jamming and Anti-Spoofing Technology | Defence forces are prioritizing navigation receivers and protective antenna systems that can maintain reliable positioning when adversaries attempt to block or falsify satellite signals. This is increasing demand for secure military GPS receivers and electronic interference detection technologies. |
| 2 | Multi-Sensor Navigation System Integration | Defence manufacturers are combining inertial navigation systems, satellite receivers, motion sensors, and environmental data to improve positioning reliability. This integrated approach helps aircraft, ships, and military vehicles maintain navigation when individual data sources become unreliable. |
| 3 | AI-Based Navigation and Sensor Fusion | Artificial intelligence is being used to interpret sensor inputs, recognize terrain features, and support continuous position estimation. These capabilities are particularly relevant to autonomous military platforms that must navigate through complex environments with limited access to satellite signals. |
| 4 | Compact Navigation Systems for Unmanned Platforms | The growing use of military drones and autonomous vehicles is creating demand for lightweight, low-power navigation components that fit within restricted payload and space requirements. Manufacturers are focusing on smaller inertial measurement units and integrated navigation solutions for unmanned aerial, ground, and underwater systems. |
| 5 | Quantum Navigation and Precision Timing Development | Defence research programs are exploring quantum sensors and advanced atomic clocks to improve motion measurement and timing without continuous dependence on satellite signals. Recent military trials indicate progress toward practical applications, although wider deployment still depends on durability, integration, and operational testing. |
| 6 | Alternative Satellite and Terrestrial Positioning Sources | Defence agencies are exploring navigation inputs beyond conventional GPS, including other satellite signals and terrestrial sources. Combining these with onboard sensors can reduce reliance on a single navigation network and improve operational continuity during signal disruption. |
Defense Navigation Market Segment Analysis
Based on Technology, the Fiber optic gyro navigation system segment dominated the Defense Navigation Market in 2025, with a nearly 28.47% Defense Navigation Market share. Over the last few years, the navigation systems industry has been greatly influenced by copious changes in technology. Companies, along with governments, are consistently working on innovating new technologies to increase efficiency. With the increasing awareness of seaborne navigation and safety, there have been extensive developments on the marine navigation system front, owing to which the global market has gained momentum.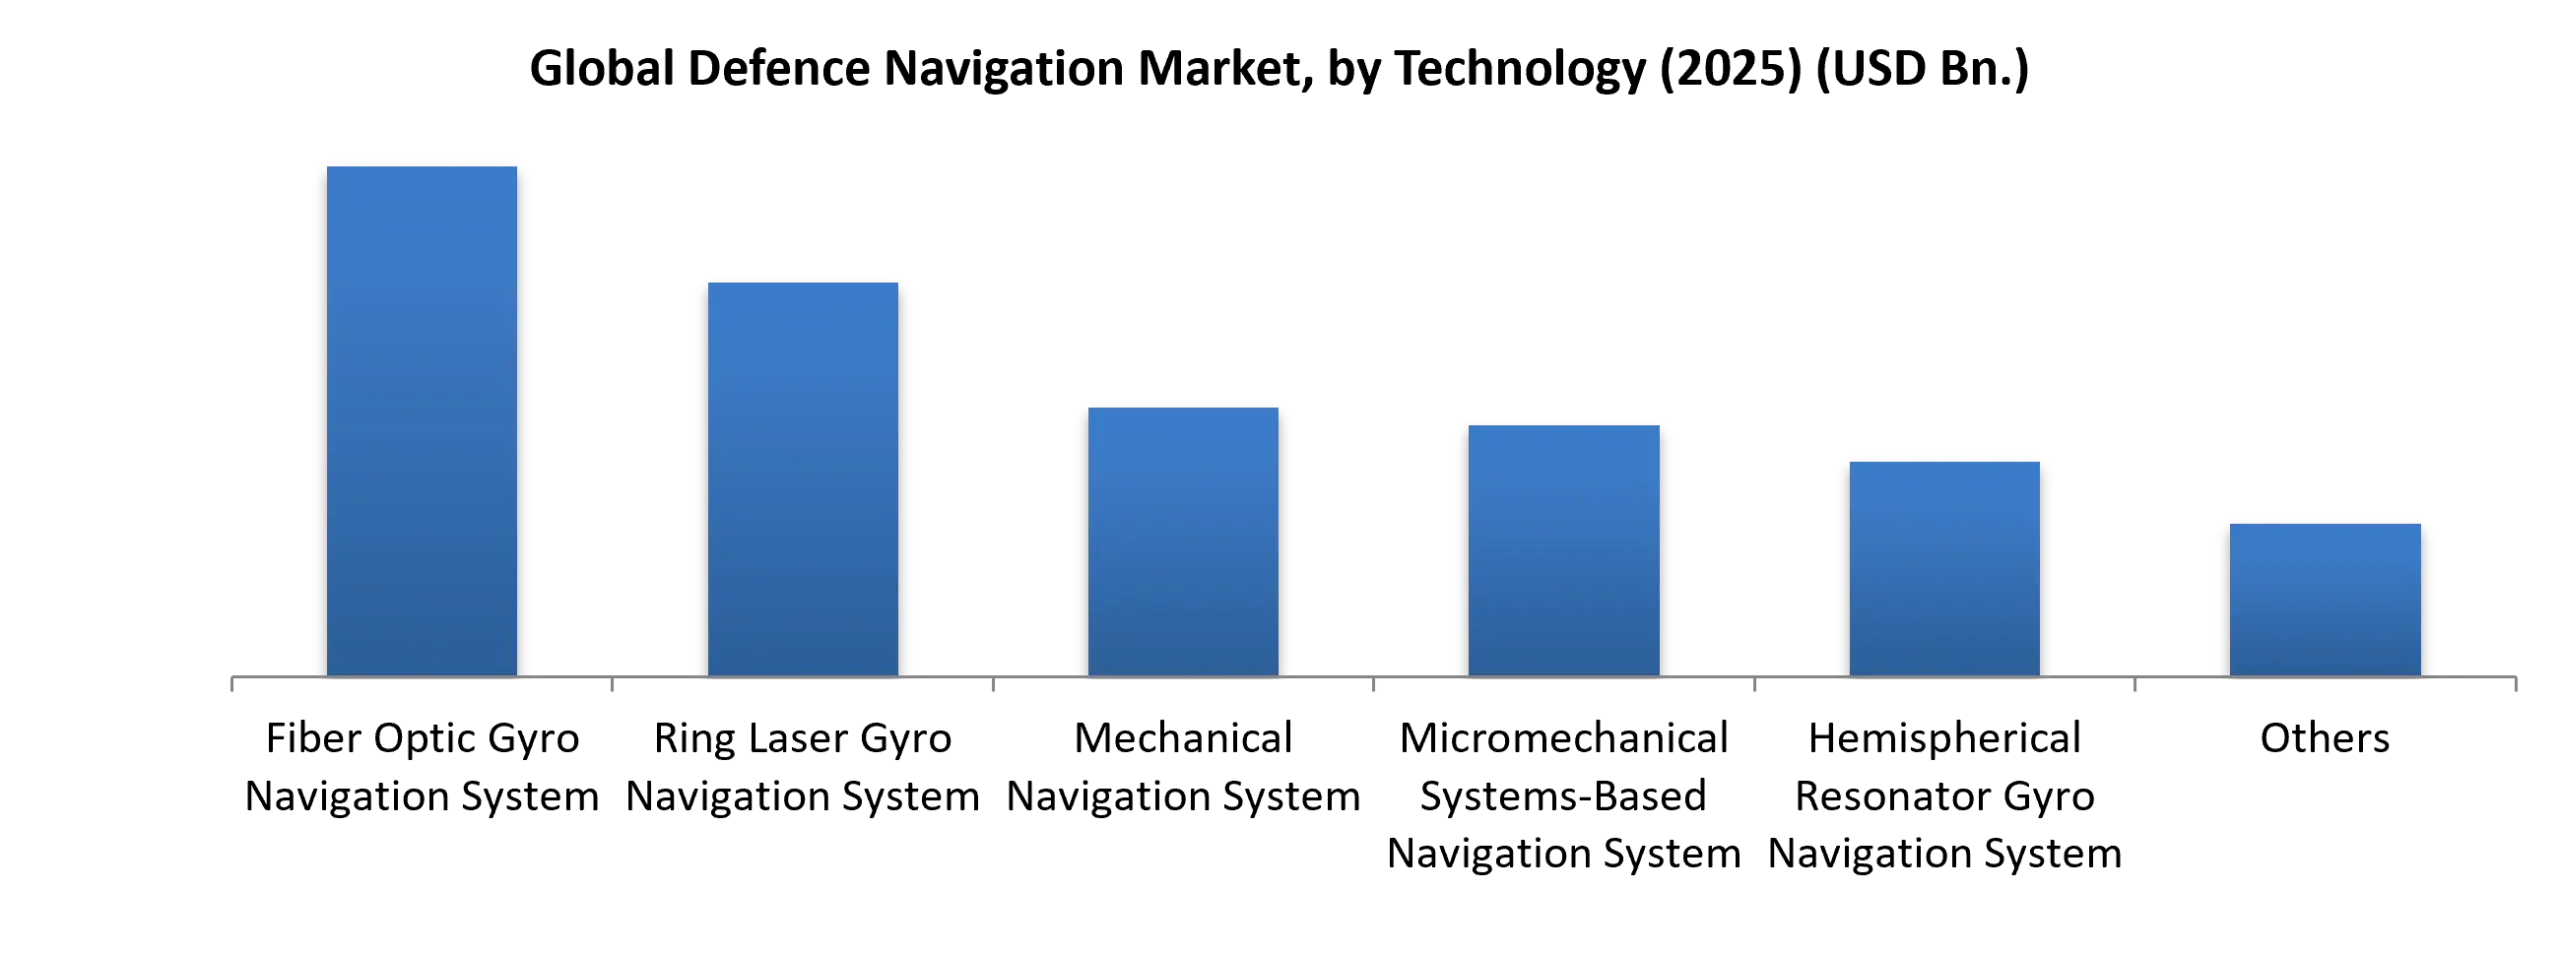 Based on Application, the Navy (Ship, Boat, Underwater Vehicles) dominated the Defense Navigation Market in 2025. This dominance is driven by increasing global investments in naval modernization programs, especially by countries with extensive maritime borders and strategic naval interests. Advanced navigation systems are critical for precision, underwater communication, and combat operations in naval fleets. Additionally, the rising need for surveillance and maritime security in contested sea regions boosts demand for cutting-edge navigation technologies in naval applications.
Defence Navigation Market Regional Analysis
| Region | Regional position | Key demand drivers | Analytical outlook |
| North America | Established technology and procurement base | Military aircraft modernization, naval systems, GPS resilience, and advanced inertial navigation | Strong position supported by established defence contractors and domestic navigation technology development. |
| Europe | Rapidly increasing defence investment | Military readiness, aircraft upgrades, naval modernization, and demand for secure positioning | Attractive market as governments strengthen defence capabilities and invest in advanced military equipment. |
| Asia Pacific | Significant modernization and procurement demand | Indigenous defence manufacturing, naval expansion, unmanned systems, and electronic warfare preparedness | Strong growth potential, supported by rising military expenditure and modernization programs across major economies. |
| Middle East and Africa | Uneven demand across countries | Military aircraft procurement, border security, naval requirements, and defence technology upgrades | Opportunities are concentrated in countries with substantial procurement budgets and active modernization programs. |
| South America | Selective procurement and modernization | Military aircraft upgrades, naval modernization, and operational requirements in remote terrain | More selective demand, with opportunities linked to equipment replacement and targeted defence investment. |
North America is a leading region in the Defence Navigation Market, which has advanced military technology, established defence manufacturers, and continuous modernization of air, land, and naval platforms. The United States drives regional demand through investments in precision navigation, inertial navigation systems, secure satellite positioning, and technologies designed to maintain operational accuracy when GPS signals are disrupted. The presence of established suppliers and strong research capabilities further supports the development of reliable military navigation solutions for aircraft, guided systems, naval vessels, and unmanned platforms.
Europe holds a significant position in the Defence Navigation Market, which is increasing defence modernization efforts, regional security requirements, and investments in advanced aerospace and naval technologies. Countries such as France, the United Kingdom, Germany, and Italy support demand through military aircraft upgrades, naval equipment development, and indigenous defence manufacturing. The presence of established companies specializing in inertial navigation, fiber optic gyroscopes, avionics, and defence electronics strengthens the region's technological capabilities. The growing focus on secure positioning and navigation resilience also encourages the adoption of advanced military navigation systems.
Asia Pacific is an important growth region in the Defence Navigation Market, for its military modernization, domestic defence production, and rising demand for advanced surveillance and autonomous platforms. China, India, Japan, and South Korea are strengthening their defence capabilities through investments in military aircraft, naval fleets, unmanned systems, and electronic warfare technologies. The need for accurate positioning in contested operating environments is encouraging interest in fiber optic gyro navigation, integrated inertial systems, and alternative positioning technologies. Regional manufacturers and government-backed research programs are also contributing to the development of indigenous navigation capabilities.
The Middle East and Africa Defence Navigation Market is shaped by military equipment procurement, border protection requirements, and the modernization of air and naval capabilities. Countries across the Gulf region are investing in advanced military platforms and defence electronics, creating demand for reliable navigation and positioning technologies. In Africa, requirements are more varied, with procurement influenced by national security priorities, operational terrain, and available defence budgets. The need for dependable navigation in remote areas and challenging environments supports opportunities for inertial navigation systems, secure positioning equipment, and integrated military navigation solutions.
South America represents a developing market for defence navigation technologies, with demand primarily linked to military aircraft maintenance, naval modernization, and the replacement of ageing equipment. Brazil is an important contributor through its aerospace and defence manufacturing capabilities, while other countries pursue selective upgrades to improve operational readiness. The region's varied terrain and extensive maritime areas create requirements for reliable navigation across aircraft, ground vehicles, and naval platforms. Budget constraints and procurement priorities can influence adoption rates, encouraging defence organizations to focus on cost-effective navigation upgrades, system integration, and long-term equipment support.
Defence Navigation Market Competitive Landscape
The competitive landscape of the Defence Navigation Market has established aerospace and defence manufacturers competing through navigation accuracy, system reliability, technological innovation, and integration capabilities. Key players such as Northrop Grumman Corporation, Honeywell International Inc., Safran Electronics & Defence, Thales Group, and RTX Corporation maintain strong positions in military navigation technologies, including fiber optic gyro navigation systems, ring laser gyro systems, inertial navigation equipment, and integrated positioning, navigation, and timing solutions. Other significant participants, including L3Harris Technologies, BAE Systems, Lockheed Martin, and Elbit Systems, strengthen competition through defence electronics, avionics, precision guidance, and navigation solutions for aircraft, naval vessels, ground vehicles, and unmanned platforms. Companies are increasingly focusing on GPS anti-jamming technology, alternative navigation capabilities, compact inertial sensors, and multi-sensor integration to address the growing need for reliable positioning in contested environments.
Defence Navigation Market Competitive analysis: technology and market positioning
| Analytical factor | Companies with relevant capabilities | Implication for competition |
| Fiber optic gyro navigation | Safran, Honeywell, Northrop Grumman | Precision, reliability, and performance in GPS-denied conditions are important differentiators. |
| Ring laser gyro and inertial navigation | Honeywell, Northrop Grumman, Safran | Established expertise and integration into existing military platforms can support competitive advantages. |
| Integrated military navigation | Thales, RTX, L3Harris, BAE Systems | Buyers value integration with avionics, guidance, communications, and mission systems. |
| Naval and maritime navigation | Kongsberg, Thales, Honeywell | Marine operating conditions and integration with shipboard systems influence procurement decisions. |
| Unmanned and autonomous navigation | Elbit Systems, Northrop Grumman, L3Harris | Compact sensors, navigation resilience, and autonomous operation are increasingly relevant capabilities. |
Defense Navigation Market Recent Developments
| Month in 2026 | Company | Recent development |
| January 2026 | Safran Federal Systems | Safran Federal Systems demonstrated its Blacknaute inertial navigation system aboard a US Army Black Hawk helicopter in GPS denied conditions. |
| February 2026 | Safran Electronics and Defence | Safran Electronics and Defence delivered its 2500th Geonyx inertial navigation system for military land platforms operating in challenging navigation environments. |
| March 2026 | L3Harris Technologies | L3Harris Technologies announced delivery of its 100000th next generation Military Code GPS receiver through the Modernized GPS User Equipment program. |
| April 2026 | Northrop Grumman | Northrop Grumman delivered the first production unit of its EGI M airborne navigation system, designed to provide resilient positioning, navigation, and timing for military aircraft. |
| June 2026 | Honeywell Aerospace | Honeywell Aerospace launched Kestrel, a compact navigation system for uncrewed aircraft designed to operate in GPS jammed and spoofed environments. |
| June 2026 | Exail | Exail introduced a rapidly deployable navigation solution using fiber optic gyroscope technology for military forces operating without reliable satellite navigation. |
| July 2026 | Thales and Eviden | Thales and Eviden announced integration of Thales Galileo Public Regulated Service capability into Eviden's military satellite navigation receiver for French Army vehicles, strengthening resistance to jamming and spoofing. |
Defense Navigation Market Scope: Inquire before buying
| Defense Navigation Market | |||
|---|---|---|---|
| Report Coverage | Details | ||
| Base Year: | 2025 | Forecast Period: | 2026-2034 |
| Historical Data: | 2020 to 2025 | Market Size in 2025: | USD 320.90 Bn. |
| Forecast Period 2026 to 2034 CAGR: | 8.36% | Market Size in 2034: | USD 660.98 Bn. |
| Segments Covered: | by Platform Type | Airborne platform Naval platform Land platform |
|
| by Application | Navy (Ship, Boat, Underwater vehicles) Airforce Military |
||
| by Technology | Fiber optic gyro navigation system Ring laser gyro navigation system Mechanical navigation system Hemispherical resonator gyro navigation system Micromechanical systems-based navigation system Others |
||
Defense Navigation Market, by Region
North America (United States, Canada, and Mexico)
Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
Asia Pacific (China, South Korea, Japan, India, Australia, Indonesia, Philippines, Malaysia, Vietnam, Thailand, Rest of Asia Pacific)
Middle East and Africa (South Africa, Saudi Arabia, UAE, Rest of the Middle East &Africa)
South America (Brazil, Argentina, Rest of South America)
Defense Navigation Market Key Players
1. Northrop Grumman Corporation
2. Honeywell International Inc.
3. Safran Electronics and Defence
4. Thales Group
5. RTX Corporation
6. L3Harris Technologies
7. BAE Systems plc
8. Lockheed Martin Corporation
9. Leonardo S.p.A.
10. Elbit Systems Ltd.
11. Kongsberg Gruppen ASA
12. Moog Inc.
13. Garmin Ltd.
14. KVH Industries Inc.
15. CMC Electronics
16. GE Aerospace
17. Israel Aerospace Industries
18. Advanced Navigation
19. Inertial Labs
20. Exail Technologies
21. EMCORE Corporation
22. Curtiss-Wright Corporation
23. General Dynamics Corporation
24. Saab AB
25. Furuno Electric Co Ltd
26. Anschütz GmbH
27. Teledyne Technologies Incorporated
28. VIAVI Solutions Inc.
29. NovAtel
30. SBG Systems
31. Advanced Navigation
32. ANELLO Photonics
33. Aeron Systems
34. Q-CTRL Pty Ltd.
35. Leidos Holdings Inc.
36. Ultra Electronics
37. Cobham Limited
38. Collins Aerospace
39. VectorNav Technologies
40. Trimble Inc.
41. Rohde and Schwarz
42. STMicroelectronics
43. Analog Devices Inc.
44. Safran Federal Systems
45. Tersus GNSS
46. iXblue
47. Sensonor AS
48. India Optel Limited
49. Bharat Electronics Limited
50. Hindustan Aeronautics Limited
| Company | Headquarters | Core navigation capabilities | Competitive positioning |
| Northrop Grumman Corporation | United States | Inertial navigation, integrated navigation, and precision guidance | Strong defence systems integration and military platform expertise |
| Honeywell International Inc. | United States | Inertial sensors, navigation systems, and aerospace avionics | Broad aerospace portfolio and established navigation technology |
| Safran Electronics & Defence | France | Fiber optic gyroscopes, inertial navigation, and navigation electronics | Important specialist in high-precision inertial technologies |
| Thales Group | France | Military navigation, avionics, and secure positioning solutions | Broad defence electronics and platform integration capabilities |
| RTX Corporation | United States | Military avionics, navigation, and precision guidance | Strong integration across aerospace and defence systems |
| L3Harris Technologies, Inc. | United States | Navigation electronics, inertial systems, and defence mission equipment | Focus on mission-critical electronics and military platforms |
| BAE Systems plc | United Kingdom | Navigation and guidance technologies, avionics, and electronic warfare systems | Strong defence integration and military electronics portfolio |
| Lockheed Martin Corporation | United States | Integrated navigation, guidance, and military mission systems | Significant presence in aircraft, missile, and space-related defence programs |
| Leonardo S.p.A. | Italy | Avionics, navigation equipment, and defence electronics | European aerospace and defence platform integration |
| Elbit Systems Ltd. | Israel | Inertial navigation, avionics, and unmanned platform technologies | Focus on integrated defence electronics and autonomous platforms |
| Kongsberg Gruppen ASA | Norway | Naval navigation, maritime systems, and defence electronics | Relevant expertise in naval and maritime defence applications |
| Moog Inc. | United States | Precision motion control, navigation-related systems, and aerospace components | Supplies specialized technologies for demanding aerospace and defence applications |
Frequently Asked Questions:
1] What segments are covered in the Global Defense Navigation Market report?
Ans. The segments covered in the Defense Navigation Market report are based on Platform Type, Technology, Application, and Region.
2] Which region is expected to hold the highest share in the Global Defense Navigation Market?
Ans. The North American region is expected to hold the highest share of the Defense Navigation Market.
3] What is the market size of the Global Defense Navigation Market by 2034?
Ans. The market size of the Defense Navigation Market by 2034 is expected to reach US$ 660.98 Bn.
4] What is the forecast period for the Global Defense Navigation Market?
Ans. The forecast period for the Defense Navigation Market is 2026-2034.
5] What was the market size of the Global Defense Navigation Market in 2025?
Ans. The market size of the Defense Navigation Market in 2025 was valued at USD 320.90 Bn.