1. GLOBAL AIR HANDLING UNITS MARKET INTRODUCTION
1.1 Executive Market Landscape and Industry Overview
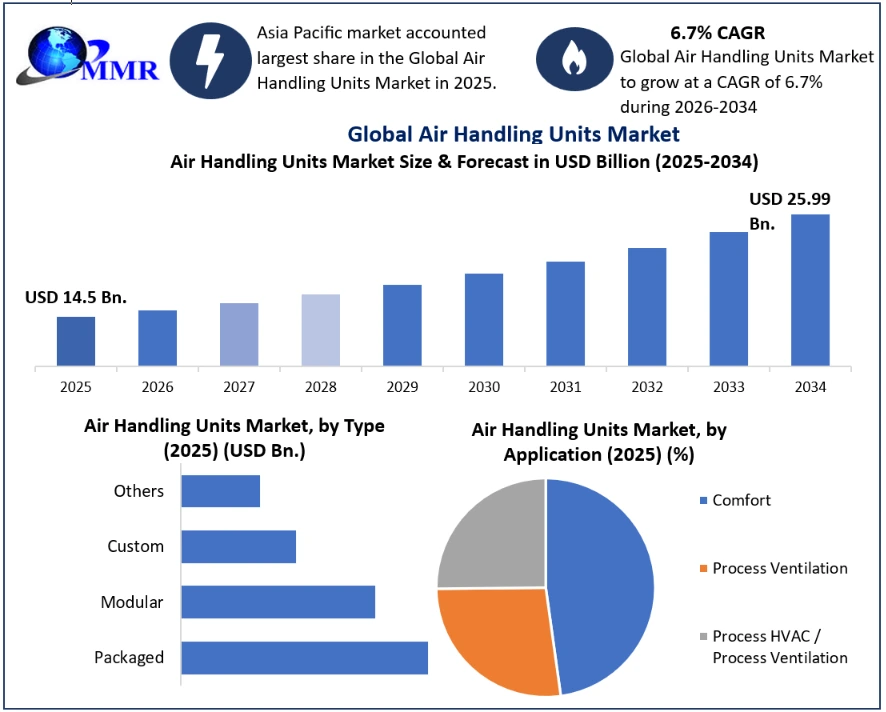
1.1.1 Global Air Handling Units Market Size Valuation Tracking and Projections (Value in USD Bn & Volume in 000' Units), 2026–2034
1.1.2 Global Market Structure, Competitive Ecosystem, and Industry Value Creation Analysis
1.1.3 Macroeconomic Factors, Construction Activity, and HVAC Investment Trends
1.1.4 Key Market Drivers, Industry Challenges, Emerging Growth Opportunities, and Business Outlook
1.1.5 Emerging High-Value Growth Opportunities Across the Forecast Period
1.1.6 Strategic Long-Term Investment and Market Development Outlook Through 2034
1.2 Global Air Handling Units Market Dynamics & Strategic
1.2.1 Global Air Handling Units Market Trends and Industrial Sector Transformations
1.2.2 Global Air Handling Units Market DROC Framework Analysis
1.2.2.1 Drivers
1.2.2.2 Restraints
1.2.2.3 Opportunities
1.2.2.4 Challenges
1.2.3 PORTER’S Five Forces Analytical Framework
1.2.4 PESTLE Macroeconomic Influence Grid Analysis
1.3 Global Pricing Analysis and Cost Structure Assessment (2020–2025)
1.3.1 AHU Manufacturing Cost Structure Assessment by Major Cost Components
1.3.2 Raw Material Price Trends for Steel, Aluminum, Copper, Motors, Insulation, Filters, and Controls
1.3.3 OEM Selling Price Benchmarking by Product Type, Capacity, Configuration, and Application
1.3.4 Regional Price Comparison Across North America, Europe, Asia Pacific, Middle East & Africa, and South America
1.3.5 Installation, Commissioning, Operation, Maintenance, and Total Lifecycle Cost Assessment
1.3.6 Future Pricing Trends, Profitability Analysis, and Margin Optimization Strategies
1.4 Global Air Handling Unit Product Configuration and Market Segmentation Assessment
1.4.1 Air Handling Unit Product Scope, Classification, and Market Definition
1.4.2 Segmentation by Airflow Configuration, Including Single Flux and Double Flux
1.4.3 Segmentation by Component Type, Including Fans, Coils, Filters, Dampers, and Heat Exchangers
1.4.4 Segmentation by Type, Capacity, and Installation Configuration
1.4.5 Segmentation by Heat Recovery Technology, Application, and End User
1.4.6 Segmentation by Distribution Channel and Comparative Product Configuration Assessment
1.5 HVAC Engineering, System Design, and Air Distribution Assessment
1.5.1 HVAC System Design Principles and AHU Engineering Requirements Across Building Types
1.5.2 Cooling and Heating Load Assessment, Equipment Selection, and AHU Sizing Methodology
1.5.3 Air Distribution System Design, Ductwork, Airflow Optimization, and Static Pressure Management
1.5.4 Fresh Air, Return Air, Exhaust Air, and Air Mixing Configuration Assessment
1.5.5 VAV, CAV, and Demand-Controlled Ventilation System Design and Integration
1.5.6 Airflow Balancing, Pressure Management, and Thermal Comfort Optimization
1.6 B2B Procurement Strategy, Buyer Behaviour, and Project Delivery Assessment
1.6.1 Procurement Models Across OEMs, EPC Contractors, MEP Contractors, Facility Owners, and Developers
1.6.2 Direct Procurement, Distributor Networks, and System Integrator Sales Channel Assessment
1.6.3 Technical Vendor Evaluation Criteria Including Efficiency, IAQ, Reliability, and Lifecycle Cost
1.6.4 Tendering Practices, Project Specifications, and HVAC Equipment Procurement Workflow
1.6.5 Contract Structures, Warranty Terms, Service Agreements, and Performance Guarantees
1.6.6 Future Procurement Strategies, Digital Purchasing Platforms, and Supplier Partnership Trends
1.7 Air Handling Unit Technology Advancement and Product Innovation Assessment
1.7.1 Evolution of Modular, Custom, Hygienic, Rooftop, Ceiling-Mounted, and Packaged AHU Technologies
1.7.2 High-Efficiency EC Fans, Variable Frequency Drives, and Advanced Motor Technology Assessment
1.7.3 Advanced Heating and Cooling Coil Technologies for Air Handling Applications
1.7.4 Advanced Filtration Technologies Including HEPA, ULPA, Activated Carbon, UV-C, and Electrostatic Systems
1.7.5 Heat Recovery Wheels, Plate Heat Exchangers, and Energy Recovery Technology Development
1.7.6 Cabinet Design, Thermal Insulation, Corrosion Protection, Acoustic Performance, and Product Innovation
1.8 Smart HVAC, Digitalization, and Building Automation Assessment
1.8.1 Building Management System Integration and Smart HVAC Control Architecture
1.8.2 IoT-Enabled Air Handling Unit Monitoring and Connected Building Solutions
1.8.3 Artificial Intelligence-Based Predictive Maintenance and Fault Detection Technologies
1.8.4 Cloud-Based HVAC Analytics, Remote Asset Monitoring, and Performance Optimization Platforms
1.8.5 Digital Twin Applications Supporting HVAC Design, Commissioning, and Operational Efficiency
1.8.6 Connected Air Handling Units, Digital Asset Management, and Future Smart Building Technologies
1.9 HVAC Controls, Sensors, and Automation Ecosystem Assessment
1.9.1 HVAC Control System Architecture and Intelligent Automation Framework
1.9.2 Temperature, Humidity, Pressure, Airflow, CO₂, VOC, and Occupancy Sensor Technology
1.9.3 VAV, CAV, and Demand-Controlled Ventilation Control System Evaluation
1.9.4 Smart Dampers, Control Valves, Actuators, and Airflow Regulation Technologies
1.9.5 Variable Frequency Drives, Motor Controls, and Energy Management Systems
1.9.6 Intelligent Control Algorithms, System Interoperability, and Future Automation Trends
1.10 Air Handling Unit Technical Performance and Efficiency Assessment
1.10.1 Airflow Capacity, Static Pressure, and Air Distribution Performance Benchmarking
1.10.2 Energy Consumption, Operational Efficiency, and Power Utilization Assessment
1.10.3 Heating, Cooling, and Thermal Transfer Performance Analysis
1.10.4 Filtration Performance, Indoor Air Quality, and Contaminant Removal Efficiency Analysis
1.10.5 Humidity Control, Dehumidification, Acoustic Performance, and Vibration Assessment
1.10.6 Product Reliability, Operational Life, Maintenance Performance, and Configuration Benchmarking
1.11 Installation, Commissioning, Operations, and Lifecycle Service Assessment
1.11.1 AHU Installation Methodologies Across Commercial, Industrial, Healthcare, and Institutional Buildings
1.11.2 Testing, Adjusting, Balancing, and HVAC System Commissioning Procedures
1.11.3 Preventive, Predictive, and Condition-Based Maintenance Strategies
1.11.4 Retrofit, Modernization, Capacity Expansion, and Equipment Replacement Assessment
1.11.5 Facility Management, Annual Maintenance Contracts, Spare Parts, and Aftermarket Services
1.11.6 Long-Term Lifecycle Cost Optimization and Asset Performance Management
1.12 Country-Level Air Handling Unit Adoption and Regional Market Assessment
1.12.1 Regional AHU Demand Assessment Across North America, Europe, Asia Pacific, Middle East & Africa, and South America
1.12.2 Country-Level Commercial Construction, Industrial Development, and HVAC Infrastructure Evaluation
1.12.3 Government Infrastructure Investments, Urbanization, and Smart City Projects Supporting AHU Demand
1.12.4 Building Energy Regulations, Indoor Air Quality Standards, and Mechanical Ventilation Adoption
1.12.5 Comparative Market Penetration, Technology Adoption, and Growth Potential by Country
1.12.6 Long-Term Country-Level Market Development and Investment Opportunity Outlook
1.13 End-Use Industry Adoption Assessment
1.13.1 Commercial Offices, Mixed-Use Developments, and Retail Infrastructure Driving AHU Demand
1.13.2 Industrial Manufacturing, Food Processing, Electronics, and Automotive HVAC Requirements
1.13.3 Healthcare, Pharmaceutical, Laboratory, and Cleanroom Air Management System Assessment
1.13.4 Data Centers, Telecommunication Facilities, and Mission-Critical Infrastructure Cooling Requirements
1.13.5 Hospitality, Educational Institutions, Airports, and Public Infrastructure HVAC Deployment
1.13.6 Residential and Multi-Family Building AHU Adoption and Long-Term End-Use Outlook
1.14 Global Manufacturing Capacity and Production Footprint Assessment
1.14.1 Global AHU Manufacturing Capacity Assessment by Region and Major Manufacturers
1.14.2 Regional Production Hubs, Factory Locations, and Manufacturing Cluster Evaluation
1.14.3 Capacity Expansion Projects, Greenfield Investments, and Production Modernization Initiatives
1.14.4 Manufacturing Utilization Rates, Production Efficiency, and Operational Benchmarking
1.14.5 Localization Strategies, Export Competitiveness, and Regional Manufacturing Advantages
1.14.6 Long-Term Production Capacity Outlook and Manufacturing Investment Opportunities
1.15 Global HVAC Systems and Equipment Ecosystem Assessment
1.15.1 Global HVAC System Architecture, Equipment Categories, and Market Ecosystem Overview
1.15.2 Centralized and Decentralized HVAC System Configurations and Application Assessment
1.15.3 Air Handling Unit Positioning Within Commercial, Industrial, and Institutional HVAC Systems
1.15.4 Chiller-Based HVAC Systems, Chilled-Water Networks, and AHU Integration Assessment
1.15.5 Direct Expansion (DX) Systems and DX-Integrated Air Handling Unit Applications
1.15.6 Decentralised Recuperators, Heat Recovery Ventilation, and Alternative Air Management Technologies
1.16 Global Supply Chain, Distribution Network, and Logistics Assessment
1.16.1 Global Supply Chain Structure From Raw Material Suppliers to Final AHU Installation
1.16.2 Regional Supplier Network Assessment for Fans, Motors, Controls, Filters, Coils, and Heat Exchangers
1.16.3 Manufacturing-to-Distribution Logistics, Warehousing, and Inventory Management Analysis
1.16.4 Distribution Channels Including OEM Sales, Distributors, HVAC Contractors, and System Integrators
1.16.5 Import and Export Flows, Supply Chain Risks, and Geopolitical Disruption Assessment
1.16.6 Long-Term Localization, Nearshoring, Inventory Optimization, and Supply Chain Resilience Outlook
1.17 End-to-End Value Chain, Manufacturing Supply Base, and Sourcing Risk Analysis
1.17.1 End-to-End AHU Value Chain Assessment From Raw Material Procurement to Final Installation
1.17.2 Critical Component Supply Base Analysis Including Fans, Motors, Heat Exchangers, Filters, Dampers, and Controls
1.17.3 Manufacturing Process Assessment Covering Fabrication, Assembly, Testing, Quality Assurance, and FAT
1.17.4 Regional Manufacturing Footprint, Production Clusters, and OEM Supply Network Evaluation
1.17.5 Raw Material Availability, Supplier Dependency, and Component Supply Risk Assessment
1.17.6 Demand–Supply Gap, Import Dependency, Domestic Production, and Long-Term Sourcing Outlook
1.18 Global Regulatory Framework, Quality Certifications, and Compliance Assessment
1.18.1 International AHU Design Standards Including AHRI, AMCA, Eurovent, and ISO Requirements
1.18.2 HVAC Energy Efficiency Regulations Covering ASHRAE, Ecodesign, IECC, and Regional Frameworks
1.18.3 Indoor Air Quality, Ventilation Performance, and Occupational Health Standards Assessment
1.18.4 Fire Safety, Mechanical Safety, Acoustic Performance, and Product Reliability Compliance
1.18.5 Product Testing, Factory Acceptance Testing, Performance Certification, and Third-Party Validation
1.18.6 DX Refrigerant Regulations, Environmental Compliance, and Future Regulatory Developments
1.19 Global Investment Trends, Funding, and Expansion Opportunities
1.19.1 Global Investment Trends Across the Air Handling Unit and HVAC Equipment Industry
1.19.2 Private Equity, Venture Capital, and Strategic Investments in HVAC Technologies
1.19.3 Manufacturing Capacity Expansion, Greenfield Projects, and Production Facility Investments
1.19.4 Commercial Buildings, Data Centers, Healthcare, and Industrial Infrastructure Investment Opportunities
1.19.5 Government Incentives, Energy-Efficiency Programs, and Green Building Investment Support
1.19.6 Regional Investment Attractiveness, Emerging Markets, and Long-Term ROI Outlook
1.20 Sustainability, ESG, and Green Building Assessment
1.20.1 Carbon Emission Reduction Initiatives and HVAC Decarbonization Strategies
1.20.2 Green Building Certification Programs Including LEED, BREEAM, WELL, and IGBC
1.20.3 Sustainable Manufacturing, Circular Economy, and Material Efficiency Assessment
1.20.4 High-Efficiency HVAC Technologies Supporting Energy Conservation and Net-Zero Buildings
1.20.5 Energy Recovery, Heat Recovery, Refrigerant Transition, and Low-Carbon AHU Technologies
1.20.6 ESG Investment Trends, Corporate Sustainability Targets, and Long-Term Environmental Outlook
1.21 Future Technology Roadmap and Innovation Outlook
1.21.1 Next-Generation Air Handling Unit Design and High-Efficiency Product Development Trends
1.21.2 Artificial Intelligence, Smart Controls, and Autonomous HVAC System Innovation Assessment
1.21.3 Advanced Air Purification, Energy Recovery, and Sustainable Ventilation Technology Roadmap
1.21.4 Next-Generation DX-Integrated, Hybrid, and High-Performance Air Handling Unit Development
1.21.5 Decentralised Ventilation, Recuperator, and Advanced Heat Recovery Technology Evolution
1.21.6 Emerging R&D Activities, Commercialization Potential, and Long-Term Technology Evolution Through 2034
1.22 Global Air Handling Units Market: Market Size and Forecast by Segmentation (by Value USD Billion and Volume in 000' Units) (2025–2034)
1.22.1 Global Air Handling Units Market Size and Forecast, By Product
1.22.1.1 Single Flux
1.22.1.2 Double Flux
1.22.2 Global Air Handling Units Market Size and Forecast, By Type
1.22.2.1 Custom
1.22.2.2 Packaged
1.22.2.3 Modular
1.22.2.4 Others
1.22.3 Global Air Handling Units Market Size and Forecast, By Installation
1.22.3.1 Indoor
1.22.3.2 Outdoor/Rooftop
1.22.4 Global Air Handling Units Market Size and Forecast, By Capacity
1.22.4.1 Up to 5,000 m³/h
1.22.4.2 5,001 to 10,000 m³/h
1.22.4.3 10,001 to 30,000 m³/h
1.22.4.4 30,001 to 50,000 m³/h
1.22.4.5 Above 50,001 m³/h
1.22.5 Global Air Handling Units Market Size and Forecast, By Technology
1.22.5.1 Heat-Pipe
1.22.5.2 Run-Around Coil
1.22.5.3 Plate Heat Exchanger
1.22.5.4 Others
1.22.6 Global Air Handling Units Market Size and Forecast, By Application
1.22.6.1 Comfort
1.22.6.2 Process Ventilation
1.22.6.3 Process HVAC / Process Ventilation
1.22.7 Global Air Handling Units Market Size and Forecast, By End User
1.22.7.1 Residential
1.22.7.2 Commercial
1.22.7.3 Industrial
1.22.8 Global Air Handling Units Market Size and Forecast, By Region
1.22.8.1 North America
1.22.8.2 Europe
1.22.8.3 Asia Pacific
1.22.8.4 Middle East & Africa
1.22.8.5 South America
2. COMPETITIVE INTELLIGENCE & AIR HANDLING UNITS ECOSYSTEM
2.1 Competitive Landscape
2.1.1 MMR Competition Matrix
2.1.2 Competitive Positioning of Leading Air Handling Units System Vendors [Revenue and Market Share (%)]
2.1.3 Key Players Benchmarking
2.1.3.1 Company Name
2.1.3.2 Headquarters
2.1.3.3 Business Portfolio
2.1.3.4 Air Handling Unit Product Portfolio
2.1.3.5 Manufacturing Facilities
2.1.3.6 Annual Production Capacity
2.1.3.7 Production Capacity
2.1.3.8 Revenue (2025)
2.1.3.9 Market Share (%)
2.1.3.10 R&D Investment
2.1.3.11 Patent Portfolio
2.1.3.12 Service Network Strength
2.1.3.13 Geographic Presence
2.1.3.14 Dealer Network Coverage
2.1.4 Market Structure
2.1.4.1 Market Leaders
2.1.4.2 Market Followers
2.1.4.3 Emerging Players
2.1.5 Mergers & Acquisitions Details
2.1.6 Recent Key Developments
2.1.7 Tier-I Global Air Handling Unit Manufacturers
2.1.8 Tier-II Regional Air Handling Unit Manufacturers
2.1.9 Specialized Hygienic and Custom Air Handling Unit Manufacturers
2.2 Product Portfolio and Technology Differentiation
2.2.1 Comparative Assessment of Air Handling Unit Product Portfolios Across Leading Manufacturers
2.2.2 Comparative Analysis of Modular, Packaged, Rooftop, Hygienic, Ceiling-Suspended, and Custom Air Handling Unit Technologies
2.2.3 Assessment of Energy Recovery Systems, EC Fan Technologies, Variable Frequency Drives (VFDs), and High-Efficiency Motors
2.2.4 Comparative Evaluation of Filtration Technologies Including HEPA, ULPA, Activated Carbon, UV-C, and Electrostatic Filters
2.2.5 Assessment of Smart Controls, Building Management System (BMS) Integration, IoT Connectivity, and Digital HVAC Platforms
2.2.6 Evaluation of Product Customization, Modular Design, and Application-Specific Engineering Solutions
2.2.7 Future Technology Differentiation Supporting Competitive Advantage
2.3 Research & Development and Innovation Benchmarking
2.3.1 Comparative Assessment of Research & Development Investments Across Leading Air Handling Unit Manufacturers
2.3.2 Analysis of Patent Portfolio, Intellectual Property Strength, and Product Innovation Trends
2.3.3 Evaluation of Next-Generation Air Handling Unit Technologies and Energy-Efficient Product Development
2.3.4 Assessment of Artificial Intelligence, Predictive Maintenance, Digital Twin, and Smart HVAC Innovations
2.3.5 Comparative Analysis of University, Research Institute, and Industry Collaboration Programs
2.3.6 Evaluation of Product Development Pipeline Supporting Future Market Growth
2.3.7 Future Technology Roadmap and Innovation Landscape Outlook
2.4 Manufacturing Footprint and Production Capacity Benchmarking
2.4.1 Comparative Assessment of Global Manufacturing Facilities and Assembly Plants
2.4.2 Analysis of Production Capacity, Factory Utilization, and Manufacturing Efficiency
2.4.3 Evaluation of Regional Manufacturing Hubs, Localization Strategies, and Export Capabilities
2.4.4 Assessment of Manufacturing Automation, Lean Production, and Quality Management Systems
2.4.5 Comparative Analysis of Capacity Expansion Projects, Greenfield Investments, and Production Modernization
2.4.6 Future Manufacturing Expansion and Capacity Development Outlook
2.5 Financial Performance and Market Share Benchmarking
2.5.1 Comparative Assessment of Revenue Performance Across Leading Air Handling Unit Manufacturers
2.5.2 Analysis of Company Market Share Based on Revenue and Unit Shipments
2.5.3 Evaluation of Operating Margin, EBITDA, Capital Investment, and Profitability Trends
2.5.4 Assessment of Regional Revenue Contribution and Business Diversification Strategies
2.5.5 Comparative Analysis of Order Backlog, Commercial Project Pipeline, and Sales Performance
2.5.6 Evaluation of Financial Stability and Long-Term Growth Strategies
2.6 Regional Presence and Project Execution Benchmarking
2.6.1 Comparative Assessment of Geographic Presence Across Major Construction and Infrastructure Markets
2.6.2 Analysis of Commercial Buildings, Healthcare, Data Centers, Industrial Facilities, Hospitality, and Public Infrastructure Project Experience
2.6.3 Evaluation of EPC Partnerships, MEP Contractor Relationships, and Engineering Service Capabilities
2.6.4 Assessment of Project Execution Capability Across Large-Scale HVAC Installations
2.6.5 Comparative Analysis of International Expansion, Regional Manufacturing Presence, and Localization Strategies
2.6.6 Evaluation of Customer Base and Long-Term Service Agreements
2.7 Distribution Network and Aftermarket Service Benchmarking
2.7.1 Comparative Assessment of Global Distribution Networks and Regional Dealer Presence
2.7.2 Analysis of Warehousing Infrastructure, Inventory Availability, and Spare Parts Management
2.7.3 Evaluation of Technical Service Centers, Commissioning Support, and Customer Service Networks
2.7.4 Assessment of Preventive Maintenance, Retrofit, Modernization, and Equipment Upgrade Services
2.7.5 Comparative Analysis of Annual Maintenance Contracts (AMC), Lifecycle Support, and Service Portfolio
2.7.6 Evaluation of Digital Service Platforms, Remote Monitoring, and Predictive Maintenance Solutions
2.8 Company Profiles: 50+ Key Players
2.8.1 Detailed Profile Parameters
2.8.1.1 Overview
2.8.1.2 Business Portfolio
2.8.1.3 Product Portfolio
2.8.1.4 Financial Performance (2023–2025)
2.8.1.5 Manufacturing Infrastructure
2.8.1.6 Air Handling Units Capabilities
2.8.1.7 Geographic Presence
2.8.1.8 Recent Developments
2.8.2 North America
2.8.2.1 Carrier Global Corporation
2.8.2.2 Lennox International Inc.
2.8.2.3 Greenheck Fan Corporation
2.8.2.4 Nortek Air Solutions LLC
2.8.2.5 Modine Manufacturing Company
2.8.2.6 Rheem Manufacturing Company
2.8.2.7 AirEase
2.8.2.8 Hastings HVAC Inc.
2.8.3 Europe
2.8.3.1 Trane Technologies plc
2.8.3.2 Johnson Controls International plc
2.8.3.3 Systemair AB
2.8.3.4 TROX GmbH
2.8.3.5 Swegon Group AB
2.8.3.6 FläktGroup
2.8.3.7 GEA Group AG
2.8.3.8 Dantherm A/S
2.8.3.9 VTS Group
2.8.3.10 Munters AB
2.8.3.11 Howden Group
2.8.3.12 CIAT Group
2.8.3.13 Zehnder Group International AG
2.8.3.14 AMX ITALIA
2.8.3.15 Air Design
2.8.3.16 STULZ GmbH
2.8.3.17 Sabiana S.p.A.
2.8.3.18 Airedale International Air Conditioning Ltd.
2.8.3.19 Euroclima S.p.A.
2.8.3.20 WOLF GmbH
2.8.3.21 Novenco
2.8.4 Asia Pacific
2.8.4.1 Daikin Industries Ltd.
2.8.4.2 Hitachi Ltd.
2.8.4.3 Mitsubishi Electric Hydronics
2.8.4.4 Johnson Controls-Hitachi Air Conditioning
2.8.4.5 TICA Industries
2.8.4.6 LG Electronics
2.8.4.7 Blue Star Limited
2.8.4.8 Voltas Limited
2.8.4.9 Waves Aircon Pvt. Ltd.
2.8.4.10 Flaktwoods India Pvt. Ltd.
2.8.5 South America
2.8.5.1 Elgin S.A.
2.8.6 Middle East & Africa
2.8.6.1 Trosten Industries Co. LLC
2.8.6.2 Evapoler Eco Cooling Solutions
2.8.7 Others
3. KEY INSIGHTS, STRATEGIC OUTLOOK & METHODOLOGICAL FRAMEWORK
3.1 Key Findings
3.2 Strategic Moves & Industry Outlook
3.3 Research Methodology