Artificial Intelligence in Agriculture Market Size by Technology, Component, Deployment Mode, Enterprise Type, Application, End User and Region – Segment-Level Market Assessment, Growth Opportunity Analysis, Competitive Mapping & Forecast to 2034

21.5%
CAGR (2026-2034)
2.96 USD Bn.
Forecast Market Size
321
Report Pages
135
Market Tables

Overview

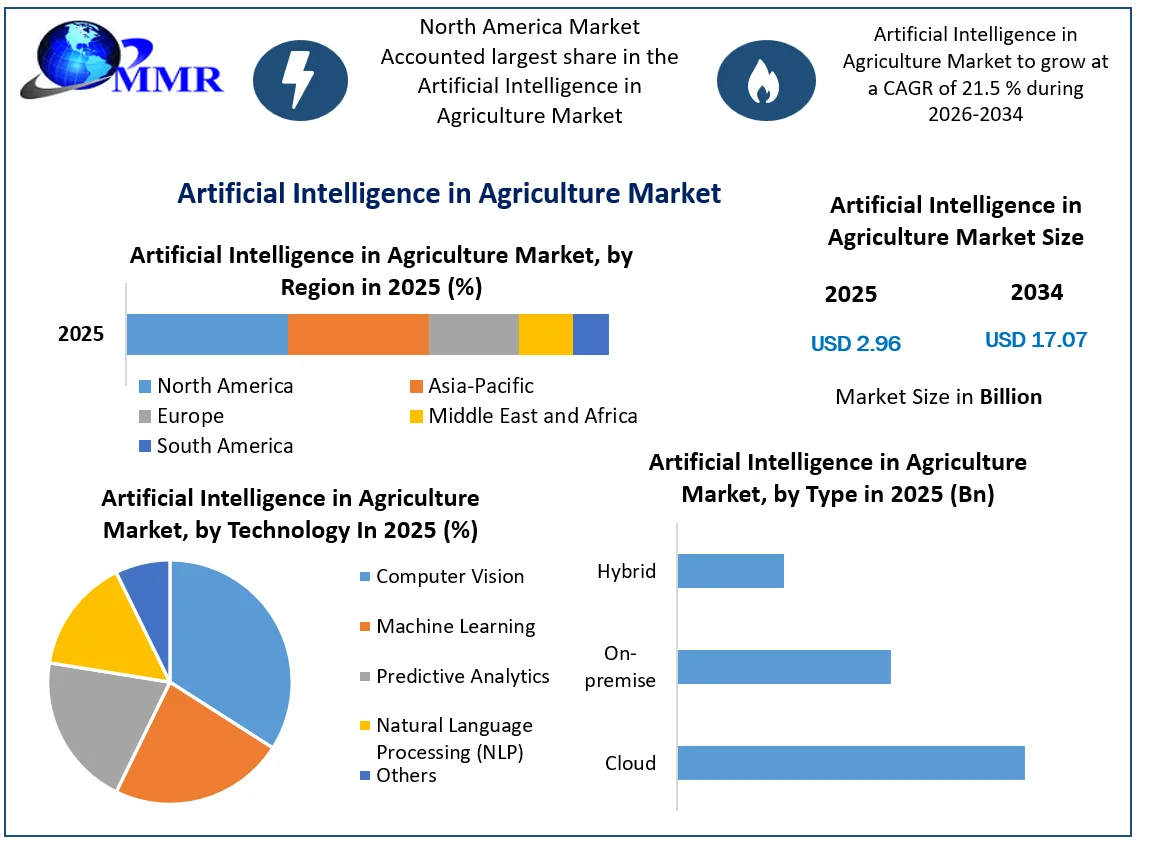
The Artificial Intelligence in Agriculture Market size was valued at USD 2.96 Billion in 2025, and the total revenue is expected to grow at a CAGR of 21.5 % from 2026 to 2034, reaching nearly USD 17.08 Billion.

The MMR report provides analysis of the Artificial Intelligence in Agriculture market by covering the regulatory and policy landscape, including global regulations, data privacy, cybersecurity, regional policy support, and certification standards for AI solutions. It evaluates pricing and market economics, with detailed pricing trends by technology, ROI and value proposition assessment, total cost of ownership, regional price comparisons, and the impact of government incentives and subsidies on adoption. The report further examines AI adoption and maturity levels across farm sizes and regions, highlighting readiness, barriers, productivity impacts, and sustainability outcomes. In addition, it delivers deep insights into the technological and innovation landscape, tracking emerging AI advancements, R&D initiatives, and strategic collaborations shaping agricultural productivity. The study also analyzes investment and funding trends, including venture capital, private equity, government funding, and M&A activity. Finally, it presents real-world use cases and implementation insights, showcasing practical applications, ROI outcomes, best practices, and challenges associated with deploying AI solutions across farming and agro-tech ecosystems.

The use of advance technological solutions to make cultivation more efficient, remains one of the greatest requirements. While, AI sees many direct use across sectors, i.e. AI-powered solutions will not only empower farmers to do better with less, it will also increase quality and assure faster go to market for crops. The report directed towards how AI can transform the agriculture landscape, the use of drone-made image processing techniques, exactitude farming landscape, the future of agriculture, challenges and overall Artificial Intelligence in Agriculture market position in forecast period.

Artificial Intelligence in Agriculture Market Size ,Share and Growth AnalysisArtificial Intelligence in Agriculture Market Growth
To know about the Research Methodology :- Request Free Sample Report

 Artificial Intelligence in Agriculture Market Scope

Agriculture is seeing prompt implementation of AI and Machine Learning (ML) both in terms of agricultural products and in-field agriculture techniques. Intellectual computing in specific, is all set to become the most disruptive technology in agriculture service sector as it can understand, learn, and respond to different circumstances to rise efficacy. Providing some of these solutions as a service such as chatbot or other conversational platform to all the farmers will help them keep pace with technological innovations as well as apply the same in their day-to-day farming to obtain the benefits of this service. Now, Microsoft is working with 175 farmers in India to deliver counselling services for sowing, land and fertilizer. This initiative has previously resulted in 30% higher yield per hectare on an average compared to last year.

Artificial Intelligence in Agriculture Market Industry Dynamics

Drivers

Growth driven by IOT

Large volumes of data get produced every day together with structured and unstructured format. These re-count to data on historic weather pattern, soil reports, new research, rainfall, pest invasion, images from drones and cameras. Intellectual IOT solutions can sense all this data and deliver strong perceptions to increase yield. Proximity Sensing and Remote Sensing are two technologies which are mainly used for intelligent data fusion. This supports in soil characterization based on the soil below the surface in a specific place. Hardware solutions like Rowbot are already coupling data collecting software with robotics to formulate the best fertilizer for growing corns as well to other activities to maximize output.

Image-based insight generation

Exactitude farming is one of the maximum discussed areas in farming today. Drone-based images can support in in-depth field analysis, crop observing and scanning of fields. Computer vision technology, IOT and drone data can be collective to assure rapid actions by farmers. Feeds from drone image data can create alerts in real time to increase the speed of precision farming. Companies such as Aerialtronics have employed IBM Watson IoT Platform and the Visual Recognition APIs in commercial drones for image analysis in real time. More or less areas where computer vision technology can be put to utilization in Disease detection, Crop readiness identification, Field management, etc.

Health monitoring of crops

Remote sensing techniques together with hyper spectral imaging and 3d laser scanning are crucial to create crop metrics thru thousands of acres. It has the likely to lead in a revolutionary change regarding of how farmlands are observed by farmers both from time and effort outlook. This technology will also be utilized to monitor crops along their complete lifecycle containing report generation in case of anomalies.

Automation techniques in irrigation and enabling farmers

With regard to human intensive processes in farming, irrigation is one of the process. Machines trained on historic weather pattern, soil quality and kind of crops to be grown, can automate irrigation and amplify overall yield. With close to 65-75% of the world’s fresh water being utilized in irrigation, automation can assist to farmers for better management of their water problems.

Artificial Intelligence in Agriculture Market Challenges

Lack of familiarity with high tech machine learning solutions

However, AI offers huge opportunities for application in agriculture, there still exists a lack of awareness with high tech machine learning solutions in farms across most of the region in a globe. Introduction of farming to external factors like weather conditions, soil situations and existence of pests is relatively high. Similarly, AI systems also require a lot of data to train machines and to make accurate predictions.

Artificial Intelligence in Agriculture Market Segment Analysis

Based on the Technology, in 2025, Machine Learning dominates the Artificial Intelligence in Agriculture Market due to its widespread use in yield prediction, crop health monitoring, and precision farming decision-making. Computer Vision follows, driven by applications in crop disease detection, weed identification, and automated harvesting through drones and smart imaging systems. Predictive Analytics is gaining strong adoption for weather forecasting, demand planning, and resource optimization, supporting risk mitigation in farming operations. Natural Language Processing (NLP) plays a growing role in voice-enabled advisory platforms, farm management software, and multilingual farmer support systems, particularly in emerging economies.

Based on Application, In 2025,Precision Farming segment dominated the AI in Agriculture Market.  This is driven by the increasing adoption of AI-powered technologies for crop monitoring, precision irrigation, soil analysis, and yield optimization. Farmers are leveraging AI-based analytics and predictive insights to improve productivity, reduce input costs, and support sustainable farming practices.

The Agriculture Robots segment is witnessing strong growth due to rising issue of  labor shortages and operational costs.  This encourages the adoption of autonomous tractors, robotic harvesters, and AI-enabled drones. Livestock Monitoring is also expanding steadily, supported by the use of AI for animal health tracking, behavior analysis, and productivity management. Meanwhile, Labor Management solutions are gaining traction by helping farmers  in optimizing  workforce planning, task scheduling, and operational efficiency through AI-driven automation. The Others segment, including AI applications in greenhouse management, pest detection, and supply chain optimization, continues to contribute to market growth as digital agriculture adoption increases globally.

Artificial Intelligence in Agriculture Market Trends

Agricultural Drones to Amplify the Growth of the Market

As global population anticipated to reach over 9.8 billion by 2050, agricultural consumption is anticipated to rise by a massive 75%, where drones have now been mainstreamed for smart farming supporting farmers in a range of tasks from analysis and planning to the real planting of crops, and the ensuing observing of fields to determine health and growth. Also, drones prepared with hyperspectral, multispectral, or thermal sensors are capable to detect areas that need changes in irrigation. Once crops have started growing, these sensors are capable to estimate their vegetation index, and indicator of health through AI, by determining the crop’s heat signature.

Artificial Intelligence in Agriculture Market Geographic Overview

North America dominated Artificial Intelligence in Agriculture Market in 2025.  The growth of the market is attributed to the high selection of trend setting innovations and item in agriculture part. Asia Pacific is estimated to have high growth rate in the forecast period due to the rising demand from emerging nations, for instance, India and China. Also, rising adoption of mechanical technology and IoT devices in agriculture is additionally evaluated to drive the Artificial Intelligence in Agriculture market.

Europe is estimated to account for the largest market growth due to their farmers manage almost half of the land area for agriculture and it makes dominant industry in Europe. Trend in observing and reporting utensils for indoor and outdoor farms, and delivering a visualization of the farmer’s intact production using computer vision and AI are increasing the AI market in agriculture. The European Soil Data Centre (ESDAC) is the thematic center for soil associated data in Europe, where its goal is to be the single reference point for and to host all appropriate soil data and statistics at European level. AI firms are handling 'Internet of the Soil', which is a software and hardware solution for observing soil conditions like humidity, temperature, electrical conductivity, and more in European countries.

Their sensors connect wirelessly to a cloud-based platform where it can be retrieved by any internet connected device. Berlin-based InFarm has urbanized a vertical indoor farming system using IoT, Big Data, and cloud analytics, which can be employed in supermarkets, restaurants, local distribution warehouses, permitting businesses to grow their own fresh crop on site to deliver to customers. I The report covers the market leaders, followers and new entrants in the industry with the market dynamics by region. It will also help to understand the position of each player in the market by region, by segment with their expansion plans, R&D expenditure and organic & in-organic growth strategies. alliances and agreement in forecast period will give future course of action in the market to the readers. More than ten companies are profiled, benchmarked in the report on different parameters that will help reader to gain insight about the market in minimum time.

The objective of the report is to present a comprehensive analysis of the Global Artificial Intelligence in Agriculture Market including all the stakeholders of the industry. The past and current status of the industry with forecasted market size and trends are presented in the report with the analysis of complicated data in simple language. The report covers all the aspects of the industry with a dedicated study of key players that includes market leaders, followers and new entrants by Vehicle. PORTER, SWOT, PESTEL analysis with the potential impact of micro-economic factors by Vehicle on the market have been presented in the report.

External as well as internal factors that are supposed to affect the business positively or negatively have been analyzed, which will give a clear futuristic view of the industry to the decision-makers. The report also helps in understanding Global Artificial Intelligence in Agriculture Market dynamics, structure by analyzing the market segments and project the Global Artificial Intelligence in Agriculture Market size. Clear representation of competitive analysis of key players by Application, price, financial position, Product portfolio, growth strategies, and regional presence in the Global Artificial Intelligence in Agriculture Market make the report investor’s guide.

Recent Industry Developments

Date Company Development Impact
12 June 2025 CNH Industrial CNH Industrial unveiled its latest AI-driven precision spraying platform integrating machine learning and camera-sensing technology. The system optimizes targeted weed detection to significantly reduce herbicide usage and chemical input costs for commercial farmers.
07 January 2026 Bayer AG Bayer entered a strategic collaboration with Cradle to deploy its machine learning AI software platform for agricultural bio-engineering. The partnership accelerates the design and optimization of bio-based products, enzymes, and crop-protection solutions.
14 January 2026 Kubota Corporation Kubota unveiled its new electric autonomous tractor concept powered by AI computer vision at CES 2026. The release demonstrates scalable driverless operation and automated field management to address global agricultural labor shortages.
27 August 2026 John Deere John Deere formed a $10 million multi-year strategic partnership with Reservoir to advance rugged edge-AI computing hardware for smart farm equipment. The collaboration speeds up real-time on-machinery predictive processing and autonomous field decision-making in harsh environments.
01 September 2026 John Deere John Deere officially introduced the JD AI Assistant within the John Deere Operations Center for conversational farm data queries. The generative AI tool enables growers to analyze field performance, yield variations, and equipment metrics via natural language commands.

Artificial Intelligence in Agriculture Market Scope : Inquire before buying

Artificial Intelligence In Agriculture Market
Report Coverage Details
Base Year: 2025 Forecast Period: 2026-2034
Historical Data: 2020 to 2025 Market Size in 2025: 2.96 USD Billion
Forecast Period 2026-2034 CAGR: 21.5% Market Size in 2034: 17.08 USD Billion
Segments Covered: by Component Hardware
Services
Solution
by Technology Computer Vision
Machine Learning
Predictive Analytics
Natural Language Processing (NLP)
by Deployment Mode Cloud
On-premise
Hybrid
by Enterprise Type Large
Small and Medium Enterprise (SMEs)
by Application Agriculture Robot
Crop and Soil Monitoring
Weed Detection
Livestock Health Monitoring
Others
by End User Farms & Agricultural Producers
Agro-Tech Companies
Agrochemical Companies
Research Institutes
Others

Artificial Intelligence in Agriculture Market, by Region

North America (United States, Canada and Mexico)
Europe (UK, France, Germany, Italy, Spain, Sweden, Austria, Turkey, Russia and Rest of Europe)
Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN and Rest of APAC)
Middle East and Africa (South Africa, GCC, Egypt, Nigeria and Rest of ME&A)
South America (Brazil, Argentina, Columbia and Rest of South America)

Key players/Competitors profiles covered in the Artificial Intelligence in Agriculture Market report in strategic perspective

1. Deere & Company
2. Microsoft Corporation
3. IBM Corporation
4. AWS
5. Global Agriculture
6. Bayer AG
7. Climate LLC.
8. Farmers Edge Inc.
9. Granular Inc.
10. AgEagle Aerial Systems Inc
11. Raven Industries Inc.
12. AGCO Corporation
13. Gamaya SA
14. Trimble Inc.
15. CropIn
16. Intello Labs
17. The Conservation Foundation
18. Fasal
19. Blue River Technology
20. Taranis
21. InData Labs
22. Itransition
23. Syngenta
24. Tule Technologies Inc.
25 EOS Data Analytics Ltd.
26 Agremo Ltd.
27 FarmWise Labs Inc.
28 Monarch Tractor Inc.
29 Evogene Ltd.
30. CropX Technologies
Others

Frequently Asked Questions:
1. What are the major growth drivers of the global AI in Agriculture Market?
Ans:
Major Artificial Intelligence in Agriculture Market growth drivers include rising demand for precision agriculture, agricultural labor shortages, increasing farm automation, growing adoption of IoT-enabled agricultural sensors, and the need for improved crop productivity. AI-based weather forecasting, soil health monitoring, smart irrigation management, and automated pest detection further accelerate the adoption of intelligent farming solutions worldwide.
2. Which region dominates the global Artificial Intelligence in Agriculture Market?
Ans:
North America dominates the Artificial Intelligence in Agriculture Market in 2025, supported by technological innovation, adoption of precision agriculture equipment, advanced farm management software, and investment in agricultural automation. The United States and Canada contribute to regional demand through AI-enabled agricultural machinery, digital farming platforms, smart crop monitoring, and data-driven agricultural productivity solutions.
3. How is artificial intelligence transforming precision farming and smart agriculture?
Ans:
Artificial intelligence in precision farming improves agricultural efficiency through real-time crop monitoring, predictive yield analytics, automated irrigation, soil nutrient assessment, and early pest detection. Machine learning algorithms, computer vision systems, agricultural drones, and IoT-enabled sensors help farmers make data-driven decisions, optimize fertilizer and water usage, reduce operational inefficiencies, and support sustainable agricultural production.
4. What role do AI-powered drones and agricultural robots play in market growth?
Ans:
AI-powered agricultural drones and farming robots support market growth by enabling automated field surveillance, crop disease detection, precision spraying, robotic harvesting, and intelligent weed management. Computer vision, machine learning, remote sensing, and autonomous navigation technologies improve operational accuracy and reduce dependence on manual agricultural activities, supporting demand for smart farming equipment.
5. Who are the leading companies in the global Artificial Intelligence in Agriculture Market?
Ans:
Leading companies operating across the Artificial Intelligence in Agriculture Market competitive landscape include John Deere, IBM, Microsoft, Bayer, Trimble, AGCO, Corteva Agriscience, CropX, Taranis, and DJI Agriculture. Companies compete through AI-based farm management software, agricultural robotics, precision agriculture platforms, computer vision technologies, strategic partnerships, and research and development investments.

Table of Contents

1. Global Artificial Intelligence in Agriculture Market Introduction 1.1. Executive Market Landscape and Industry Overview 1.1.1. Global Artificial Intelligence in Agriculture Market Size (Value USD Bn.), 2025–2034 1.1.2. Global AI in agriculture ecosystem definition, scope boundaries, and segmentation framework 1.1.3. Adoption intensity comparison by region (technology penetration, farm size distribution, digital infrastructure, income levels) 1.1.4. Organized vs fragmented market structure mapping (global technology providers vs AgriTech startups vs regional solution integrators) 1.1.5. Investor thesis: precision farming adoption, yield optimization demand, labor cost reduction, and data-driven decision-making advantages 1.1.6. Competitive intensity and consolidation signals (technology partnerships, platform integrations, funding rounds, regulatory shifts, and acquisition trends) 1.2. Global Artificial Intelligence in Agriculture Market Dynamics 1.2.1. Artificial Intelligence in Agriculture Market Trends 1.2.2. Artificial Intelligence in Agriculture Market DROC 1.2.3. Drivers 1.2.4. Restraints 1.2.5. Opportunities 1.2.6. Challenges 1.2.7. PORTER’s Five Forces Analysis 1.2.7.1. Supplier power 1.2.7.2. Buyer power 1.2.7.3. Threat of substitutes 1.2.7.4. Threat of new entrants 1.2.7.5. Competitive rivalry 1.2.8. PESTLE Analysis 1.3. Regulatory & Policy Landscape 1.3.1. Overview of Global Regulatory Framework for AI in Agriculture 1.3.2. Data Privacy, Cybersecurity, and Compliance Requirements 1.3.3. Regional Policies and Government Initiatives Supporting AI Adoption 1.3.4. Certifications, Standards, and Governance Frameworks for AI Solutions 1.3.5. Impact of Regulatory Environment on Market Growth and Technology Deployment 1.4. Pricing Analysis & Market Economics (2025) 1.4.1. Pricing Analysis by Technology (2020–2025) 1.4.2. Comparative Pricing Analysis Across Key Regions 1.4.3. Total Cost of Ownership (TCO) of AI Solutions in Agriculture 1.4.4. Cost-Benefit Analysis and ROI Assessment for AI Adoption 1.4.5. Impact of Government Incentives, Subsidies, and Funding on Pricing Dynamics 1.4.6. Value Proposition of AI Solutions for Different Enterprise Segments 1.5. Adoption & Maturity Analysis 1.5.1. Adoption of AI Technologies Across Small, Medium, and Large Farms (Hectares, 2025) 1.5.2. Regional Adoption Trends (North America, Europe, Asia-Pacific, etc.) 1.5.3. Technology Maturity Assessment and Readiness Levels 1.5.4. Key Challenges and Barriers to AI Adoption 1.5.5. Opportunities to Accelerate Adoption and Market Penetration 1.5.6. Impact of AI Adoption on Productivity, Efficiency, and Sustainability 1.6. Technological Landscape & Innovation 1.6.1. Overview of AI Technologies Transforming Agriculture 1.6.2. Emerging and Disruptive Innovations in AI-driven Farming 1.6.3. Global Technology Trends and Adoption Patterns 1.6.4. Key R&D Initiatives and Strategic Collaborations 1.6.5. Impact of Technological Advancements on Productivity, Sustainability, and Profitability 1.6.6. Application of AI Across Advanced Agricultural Sciences 1.6.6.1. AI in Molecular Biology and Genomics 1.6.6.2. AI in Plant Breeding and Genetic Improvement 1.6.6.3. AI in Plant Tissue Culture and Controlled Propagation 1.6.6.4. AI in Plant Physiology and Crop Response Modeling 1.6.6.5. AI Applications in Horticulture and High-Value Crops 1.6.6.6. AI for Microplastics Detection and Environmental Monitoring 1.7. Investment & Funding Trends 1.7.1. Venture Capital and Private Equity Investments in AI-driven Agriculture 1.7.2. Strategic Investments by AgriTech and Technology Providers 1.7.3. Government Grants, Subsidies, and Funding Programs 1.7.4. Mergers, Acquisitions, and Strategic Partnerships 1.7.5. Impact of Investments on Innovation and Market Expansion 1.8. Use Cases & Implementation Insights 1.8.1. Real-world Implementation of AI in Agricultural Operations 1.8.2. Key Use Cases: Precision Farming, Crop Monitoring, Livestock, and Irrigation 1.8.3. Operational Benefits and ROI from AI Deployment 1.8.4. Case Studies and Lessons from Successful Implementations 1.8.5. Best Practices for Scalable, Sustainable, and Ethical AI Adoption 1.9. Supply Chain & Ecosystem Analysis 1.9.1. End-to-End AI in Agriculture Value Chain Mapping (Data → Platform → Application → End-User) 1.9.2. Key Stakeholders Analysis (Farmers, AgriTech Companies, Input Providers, Technology Vendors) 1.9.3. Role of Data Providers, Cloud Platforms, and Connectivity Infrastructure 1.9.4. Strategic Partnerships and Ecosystem Collaborations 1.10. Consumer / Farmer Behavior & Decision-Making Analysis 1.10.1. Farmer Awareness and Perception of AI Technologies 1.10.2. Adoption Behavior Across Farm Sizes and Enterprise Types 1.10.3. Key Decision-Making Factors (Cost, ROI, Ease of Use, Scalability) 1.10.4. Willingness to Invest in AI Solutions and Financing Preferences 1.10.5. Digital Literacy and Skill Gaps Impacting Adoption 1.11. Sustainability & ESG Impact Analysis 1.11.1. Role of AI in Promoting Sustainable Agricultural Practices 1.11.2. Impact on Resource Optimization (Water, Fertilizers, Pesticides) 1.11.3. Contribution to Carbon Footprint Reduction and Climate-Smart Agriculture 1.11.4. ESG Compliance and Alignment with Global Sustainability Goals 1.11.5. Environmental and Social Benefits of AI Adoption in Agriculture 1.12. Regional Policy & Government Initiatives Deep Dive 1.12.1. Key Government Programs Supporting AI in Agriculture (by Region) 1.12.2. Public-Private Partnerships Driving Adoption 1.12.3. National Digital Agriculture Strategies and Roadmaps 1.12.4. Funding Allocation and Subsidy Structures by Country 1.12.5. Impact of Policy Frameworks on Market Growth 1.13. Global Artificial Intelligence in Agriculture Market: Market Size and Forecast by Segmentation (by Value USD Billion) (2025–2034) 1.13.1. Global Artificial Intelligence in Agriculture Market Size and Forecast, By Technology 1.13.1.1. Computer Vision 1.13.1.2. Machine Learning 1.13.1.3. Predictive Analytics 1.13.1.4. Natural Language Processing (NLP) 1.13.2. Global Artificial Intelligence in Agriculture Market Size and Forecast, By Component 1.13.2.1. Hardware 1.13.2.2. Services 1.13.2.3. Software 1.13.3. Global Artificial Intelligence in Agriculture Market Size and Forecast, By Deployment Mode 1.13.3.1. Cloud 1.13.3.2. On-premise 1.13.3.3. Hybrid 1.13.4. Global Artificial Intelligence in Agriculture Market Size and Forecast, By Type of Enterprise 1.13.4.1. Large 1.13.4.2. Small and Medium Enterprise (SMEs) 1.13.5. Global Artificial Intelligence in Agriculture Market Size and Forecast, By Application 1.13.5.1. Precision Farming 1.13.5.2. Agriculture Robots 1.13.5.3. Livestock Monitoring 1.13.5.4. Labor Management 1.13.5.5. Others 1.13.6. Global Artificial Intelligence in Agriculture Market Size and Forecast, By End-User 1.13.6.1. Farms 1.13.6.2. Agro-Tech Companies 1.13.6.3. Agrochemical Companies 1.13.6.4. Research Institutes 1.13.6.5. Others 2. Competitive Intelligence & Industrial Ecosystem 2.1. Company Profiles: Key Players 2.1.1. Global Technology & Platform Leaders (High scale, global presence, integrated AI capabilities) 2.1.1.1. Microsoft Corporation (global leader in cloud-based AI platforms and digital agriculture solutions) 2.1.1.2. Amazon Web Services (strong global presence in AI infrastructure, data analytics, and scalable cloud deployment) 2.1.1.3. IBM Corporation (advanced AI, data analytics, and enterprise-grade agricultural intelligence solutions) 2.1.1.4. Deere & Company (integrated precision agriculture ecosystem with AI-enabled machinery and automation) 2.1.1.5. Trimble Inc. (global provider of positioning, analytics, and AI-driven farm management solutions) 2.1.2. Tier-2 AgriTech Platforms & Integrated Solution Providers (Strong data integration + application focus) 2.1.2.1. Bayer AG (digital farming platforms and AI-driven crop science solutions) 2.1.2.2. Syngenta (integrated agri-inputs with AI-enabled decision support systems) 2.1.2.3. The Climate Corporation (data-driven farm analytics and predictive modeling capabilities) 2.1.2.4. Farmers Edge Inc. (precision agriculture analytics and farm data platforms) 2.1.2.5. CropIn (AI-powered farm intelligence and supply chain traceability solutions) 2.1.3. Tier-3 Regional / Value Players and Solution Integrators (Price-led, localized, service-driven) 2.1.3.1. Region-specific players (Asia Pacific, Europe, North America, Middle East & Africa, South America) mapped by country 2.1.3.2. Regional AgriTech startups, AI solution providers, and system integrators offering localized services 2.1.3.3. Farm management software vendors, advisory platforms, and agri-data service providers 2.1.3.4. Contract-based AI deployment firms and agricultural consulting companies supporting digital transformation 2.1.4. Emerging Innovation Players and Ecosystem Enablers (AI, robotics, and sustainability-driven) 2.1.4.1. Blue River Technology (AI-driven precision spraying and computer vision solutions) 2.1.4.2. Taranis (high-resolution imaging and AI-based crop intelligence platforms) 2.1.4.3. AgEagle Aerial Systems Inc. (drone analytics and aerial data acquisition solutions) 2.1.4.4. FarmWise Labs Inc. (autonomous weeding and robotic farming technologies) 2.2. Competitive Benchmarking Matrix 2.2.1. Product portfolio breadth by AI application (precision farming, livestock monitoring, robotics, farm management) + end-use fit (row crops, horticulture, greenhouse, livestock) 2.2.2. Feature benchmarking: analytics accuracy, automation capability, scalability, integration with farm systems, sustainability compliance 2.2.3. Price-position map: basic digital advisory tools vs advanced AI platforms vs fully autonomous farming solutions 2.3. Strategic Moves and Partnership Mapping 2.3.1. Data partnerships, cloud collaborations, and integration with IoT and sensor providers 2.3.2. Technology licensing, platform integrations, and regional deployment partnerships 2.3.3. Distribution alliances with agribusiness firms, cooperatives, and food supply chains 2.3.4. M&A radar: acquisition of AgriTech startups, AI analytics firms, and robotics solution providers 2.4. Competitive Benchmarking & Brand Positioning 2.4.1. Market share comparison by application (precision farming vs robotics vs analytics vs farm management vs others) 2.4.2. Product differentiation benchmarking (analytics capability, automation level, ease of use, sustainability focus) 2.4.3. Distribution footprint comparison by region and deployment model (cloud vs on-premise) 2.4.4. R&D investment intensity versus platform scalability and revenue positioning 2.4.5. Brand and solution positioning analysis (technology leadership vs cost efficiency vs innovation-driven offerings) 2.5. Competitive Intelligence & Strategic Analysis Report 2.5.1. Year-Over-Year (Y-o-Y) Revenue Growth Rate (%) Comparison 2.5.2. Profit Margin (%) Comparison Across Key Players 2.5.3. R&D Investment (% of Revenue) – Innovation Intensity 2.5.4. Revenue vs Net Earnings – Financial Health Benchmarking (FY2025 / Latest) 2.6. Company Profile: Key Players 2.6.1. Detailed Profile considering the parameters: 2.6.1.1. Overview 2.6.1.2. Business Portfolio 2.6.1.3. Financial Overview 2.6.1.4. SWOT Analysis 2.6.1.5. Strategic Analysis 2.6.1.6. Recent Developments 2.6.2. Key Companies 2.6.2.1. Deere & Company 2.6.2.2. Microsoft Corporation 2.6.2.3. IBM Corporation 2.6.2.4. AWS 2.6.2.5. Global Agriculture 2.6.2.6. Bayer AG 2.6.2.7. Climate LLC. 2.6.2.8. Farmers Edge Inc. 2.6.2.9. Granular Inc. 2.6.2.10. AgEagle Aerial Systems Inc 2.6.2.11. Raven Industries Inc. 2.6.2.12. AGCO Corporation 2.6.2.13. Gamaya SA 2.6.2.14. Trimble Inc. 2.6.2.15. CropIn 2.6.2.16. Intello Labs 2.6.2.17. The Conservation Foundation 2.6.2.18. Fasal 2.6.2.19. Blue River Technology 2.6.2.20. Taranis 2.6.2.21. InData Labs 2.6.2.22. Itransition 2.6.2.23. Syngenta 2.6.2.24. Tule Technologies Inc. 2.6.2.25. EOS Data Analytics Ltd. 2.6.2.26. Agremo Ltd. 2.6.2.27. FarmWise Labs Inc. 2.6.2.28. Monarch Tractor Inc. 2.6.2.29. Evogene Ltd. 2.6.2.30. CropX Technologies 2.6.2.31. Others 3. Strategic Outlook: Global Artificial Intelligence in Agriculture Market 3.1. Revenue Pool Mapping & Value Hotspots 3.1.1. Revenue distribution by application type (precision farming, livestock monitoring, robotics, farm management systems) 3.1.2. Regional revenue concentration across Asia-Pacific, North America, Europe, and Middle East & Africa 3.1.3. Crop farming vs horticulture vs livestock application mix and technology penetration 3.1.4. Replacement demand versus new demand driven by digital transformation and farm modernization 3.1.5. High-value AI platforms share and advanced analytics adoption rate (2025) 3.2. Impact of Macro Drivers & Industry Trends on Market Expansion 3.2.1. Rising demand for food security and agricultural productivity enhancement 3.2.2. Growth in digital agriculture adoption and smart farming technologies 3.2.3. Urbanization and labor shortages influencing automation and AI adoption 3.2.4. Climate variability and resource constraints impacting farming practices 3.2.5. Sustainability and precision agriculture initiatives influencing technology adoption 3.3. Value-Led vs Volume-Led Competitive Strategy 3.3.1. Premium AI platforms and advanced analytics solution portfolio expansion 3.3.2. Volume-driven strategy in emerging markets (basic digital tools and advisory platforms focus) 3.3.3. Brand positioning of global technology leaders versus regional AgriTech solution providers 3.3.4. Enterprise contracts and subscription-based models versus transactional service offerings 3.3.5. Cost competitiveness as a growth enabler for small and medium-sized farm adoption 3.4. Portfolio Prioritization & Product Mix Strategy 3.4.1. Expansion of advanced AI platforms and precision agriculture solutions 3.4.2. Growth in farm management systems, predictive analytics, and automation tools demand 3.4.3. Development of sustainable and resource-efficient farming solutions 3.4.4. Focus on high-value analytics, robotics, and decision-support platforms 3.4.5. Integration of sustainability, climate-smart agriculture, and data-driven farming strategies 3.4.6. Application-specific solution innovation and product development roadmap 3.5. Regional Expansion & Market Entry Roadmap 3.5.1. Asia Pacific digital agriculture growth and large-scale farm adoption strategy 3.5.2. North America technology leadership and advanced AI deployment roadmap 3.5.3. Europe regulatory-driven sustainability and smart farming strategy 3.5.4. South America agricultural expansion and AgriTech adoption growth strategy 3.5.5. Middle East & Africa emerging market potential and digital farming initiatives 3.6. Pricing & Margin Sustainability Strategy 3.6.1. Solution-based pricing across AI platforms, software, and service models 3.6.2. Technology cost impact including sensors, data infrastructure, and cloud services 3.6.3. Subscription pricing and platform-based revenue optimization strategies 3.6.4. End-user pricing dynamics across farm sizes and enterprise segments 3.6.5. Premium pricing through analytics accuracy, automation, and sustainability value 3.7. R&D & Product Strategy Linked to Commercial Outcomes 3.7.1. Advanced AI model development and predictive analytics innovation 3.7.2. Process optimization through automation and data-driven decision systems 3.7.3. Sustainable agriculture technologies and climate-smart innovation focus 3.7.4. Data integration, traceability, and compliance in solution development 3.7.5. AI-enabled monitoring and precision farming innovation strategies 3.8. Customer Engagement & Long-Term Partnerships 3.8.1. Partnerships with farmers, agribusiness firms, and food supply chain players 3.8.2. Collaborations with AgriTech platforms, input providers, and cooperatives 3.8.3. Strategic alliances with technology providers and cloud service platforms 3.8.4. Data partnerships and integrated digital agriculture ecosystems 3.8.5. Long-term service agreements and platform-based engagement models 3.9. Delivery Model & Operational Strategy 3.9.1. Cloud-based deployment and digital platform delivery optimization 3.9.2. Solution deployment aligned with seasonal farming cycles and crop patterns 3.9.3. Data management, analytics integration, and real-time decision support systems 3.9.4. Operational scalability through platform-based and SaaS delivery models 3.10. Business Model & Value Proposition Canvas 3.10.1. Key partners including technology providers, AgriTech firms, and data platforms 3.10.2. Core value propositions centered on productivity, efficiency, and cost optimization 3.10.3. Target segments covering farms, agribusinesses, and agricultural enterprises 3.10.4. Revenue streams from software platforms, analytics services, and AI solutions 3.10.5. Cost structure analysis across technology infrastructure, data, and service delivery 3.11. Risk & Downside Scenarios (2026–2034) 3.11.1. Technology adoption barriers affecting AI implementation in agriculture 3.11.2. Price sensitivity and ROI concerns among small and medium farmers 3.11.3. Data privacy, cybersecurity, and regulatory compliance challenges 3.11.4. Infrastructure limitations and connectivity issues in rural areas 3.11.5. Intensifying competition from low-cost and regional solution providers 3.12. Investment & M&A Priorities 3.12.1. Acquisition of AgriTech startups and AI analytics solution providers 3.12.2. Strategic partnerships in automation, robotics, and precision farming technologies 3.12.3. Expansion of AI platform capabilities and digital agriculture ecosystems 3.12.4. Investment in advanced analytics, sustainability, and climate-smart solutions 3.12.5. Global expansion and technology integration investments 3.13. 7-Year Strategic Roadmap (2026–2034) 3.13.1. Revenue growth through technology adoption and platform expansion 3.13.2. Strengthening of advanced analytics and automation solution portfolios 3.13.3. Scaling partnerships with farmers, agribusinesses, and technology providers 3.13.4. Expansion of sustainable and precision agriculture initiatives 3.13.5. Regional market penetration and digital infrastructure development strategies 4. Insights & Actionable Recommendations 4.1. Key Findings 4.2. Strategic Moves & Industry Outlook 4.3. Research Methodology

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements